
 Universal Remote Controls Market | 2026-2036
Universal Remote Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Remote Controls Market Analytics
Market Context
Premium voice-activated specification tiers is collapsing the gap between basic infrared handhelds and integrated smart home hubs. Logitech leverages its Harmony software ecosystem to sustain loyalty among home-theater enthusiasts. Universal Electronics Inc. anchors its position through captive supply of RF chipsets to cable operators. Guangzhou SYSTO Trading dominates cost-optimized manufacturing for entry-level handheld remotes across Southeast Asian retail channels.
Technical Definition and Segments
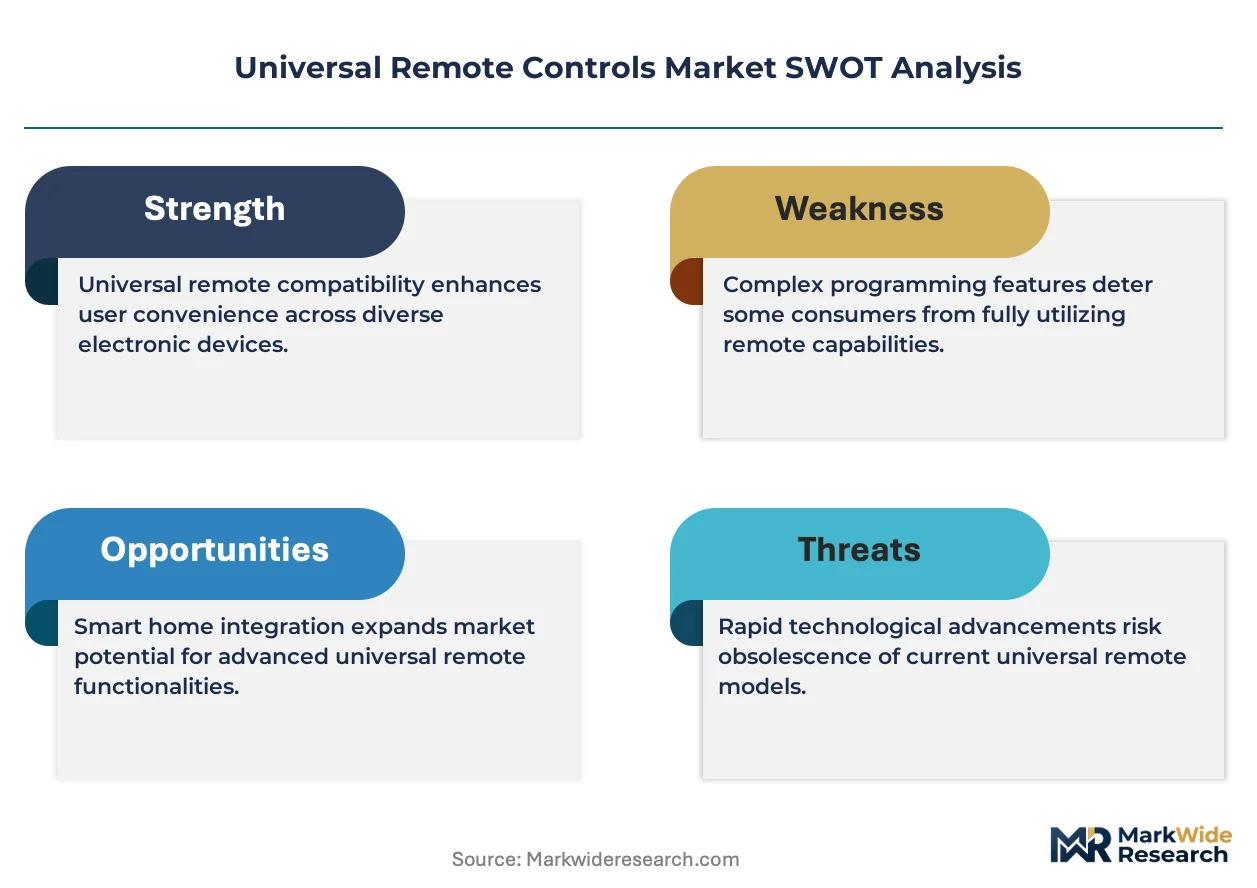
A universal remote control is a handheld or installed electronic device programmed to operate multiple consumer electronics appliances through standardized infrared, radio frequency, or wireless protocols, typically supporting 50,000-plus device codes and macro sequencing for automated scene control. Smart remotes and learning remotes now capture the fastest expansion as households replace single-function legacy units with Bluetooth-enabled and Wi-Fi-connected alternatives. Infrared technology still occupies the largest volume tier due to entrenched television and set-top box compatibility, though RF modules command superior margins in commercial and hospitality installations where wall penetration and extended range prove essential.
Regulatory Environment
The Federal Communications Commission governs RF emission limits for universal remotes sold in the United States, while the European Union's Radio Equipment Directive and REACH chemical compliance shape market access for Bluetooth and Wi-Fi models across member states. China's Ministry of Industry and Information Technology certifies wireless transmission frequencies under GB standards, forcing manufacturers to maintain region-specific firmware variants. Stakeholders must monitor evolving Matter protocol certification requirements and energy-efficiency labeling mandates that will determine which product architectures justify continued R&D investment.
Market Dynamics
The Matter protocol certification is forcing universal remote manufacturers to abandon proprietary RF stacks in favor of interoperable architectures, compressing development timelines while expanding addressable device ecosystems.
Growth Catalysts
- Smart home integration:Households in the United States are replacing single-function remotes with Bluetooth-enabled hubs that consolidate lighting, climate, and entertainment control.
- REACH chemical compliance:The European Union's substance restrictions are accelerating migration from legacy solder compositions to lead-free assembly processes.
- Hospitality automation:Hotels across Germany are deploying RF-based universal remotes to enable centralized in-room device management.
Market Restraints
- Silicon supply concentration:RF chipset fabrication depends on a limited number of advanced foundries in Taiwan, creating vulnerability to capacity constraints.
- Infrared legacy lock-in:Entrenched television and set-top box installed bases perpetuate demand for obsolete line-of-sight technology.
- GB standards fragmentation:China's Ministry of Industry and Information Technology mandates region-specific firmware variants, inflating SKU complexity.
Strategic Opportunities
- Aging device replacement cycles:Consumers in China are upgrading decade-old infrared systems as television refresh intervals compress.
- Matter protocol tailwind:Certification requirements under the Connectivity Standards Alliance are creating tiered product positioning for interoperable versus siloed systems.
- Voice control convergence:Integration of natural language processing with gesture recognition is opening premium specification tiers.
Industry Challenges
- Firmware engineering scarcity:Qualified embedded systems developers capable of Matter stack implementation command compensation premiums that strain mid-tier manufacturers.
- Multi-protocol certification timelines:Simultaneous Bluetooth Low Energy, Wi-Fi, and Thread compliance testing extends product launch windows by six to nine months.
Report Scope
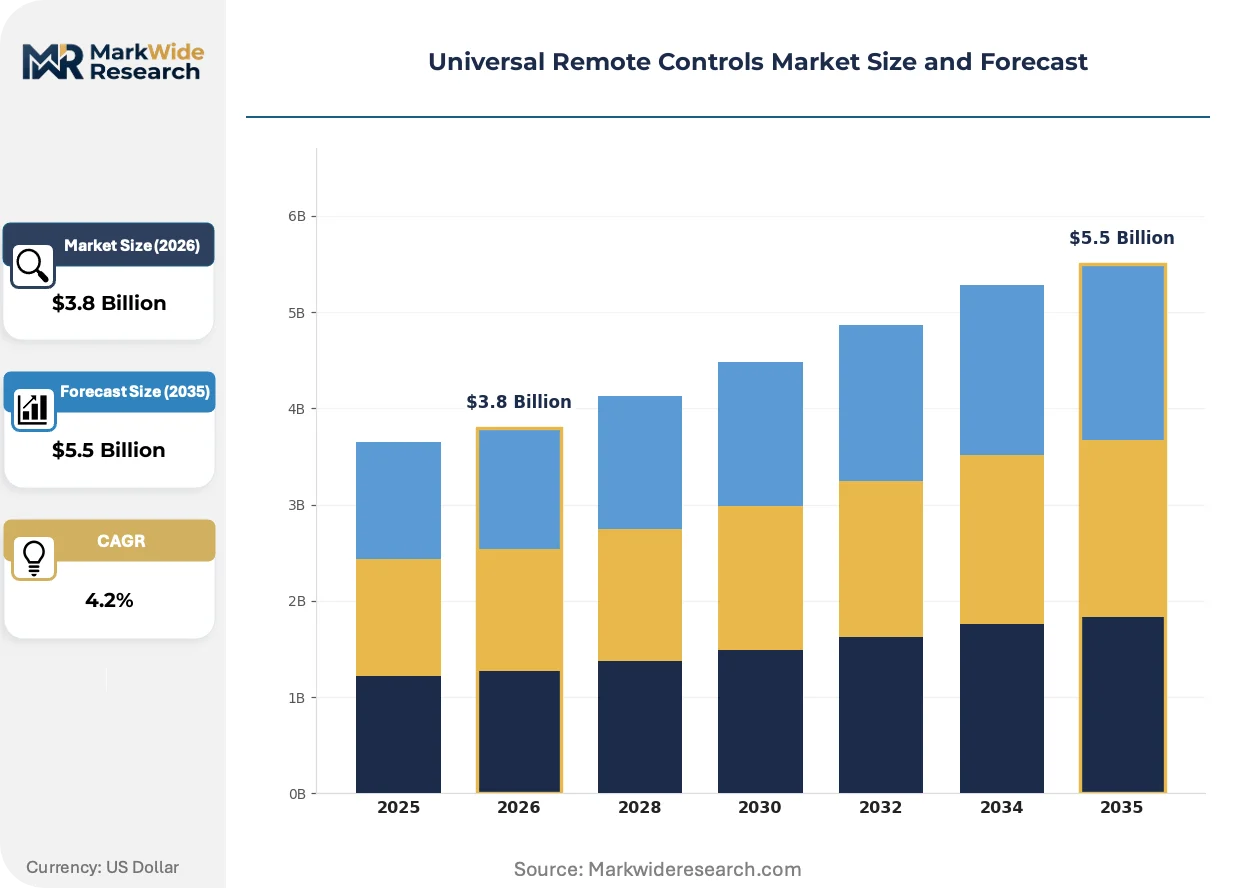
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Remote Controls Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Remotes, In-Wall Controls, Smart Remotes, Learning Remotes Technology: Infrared, Bluetooth, Wi-Fi, RF End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Online Retail, Offline Retail, Direct Sales, Integrators |
| Companies Covered | Logitech, Jasco, Universal Electronics Inc. (UEI), Amazon Basics, Voxx International, Universal Remote Control (URC), Philips, Guangzhou SYSTO Trading Co., Ltd., BroadLink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Remote Controls Market Evolving Landscape
Protocol standardization is collapsing the boundary between dedicated remotes and software-based control surfaces, redistributing value toward ecosystem orchestration rather than hardware shipment volume.
Thread mesh networking is bifurcating the residential connectivity layer from cloud-dependent architectures. Smart home installers in the United States are specifying Thread-enabled remotes for offline-first installations. This technology is bifurcating premium positioning between latency-sensitive local control and feature-rich cloud-dependent alternatives.
FCC Part 15 emission limits are tightening testing documentation requirements for RF-enabled universal remotes sold in the United States. Manufacturers must now submit detailed modulation characteristic reports alongside traditional power spectral density measurements. The commercial installation segment is absorbing these compliance costs through higher specification tiers while entry-level handheld producers delay RF model introductions.
Subscription-based remote configuration services are displacing one-time hardware purchases in the hospitality vertical. Hotel chains in Germany are contracting managed service providers to maintain device code libraries and macro programming across property portfolios. This shift is most visible in mid-scale urban properties where in-house technical staff has been consolidated to regional hubs.
Universal Remote Controls Market Segmentation
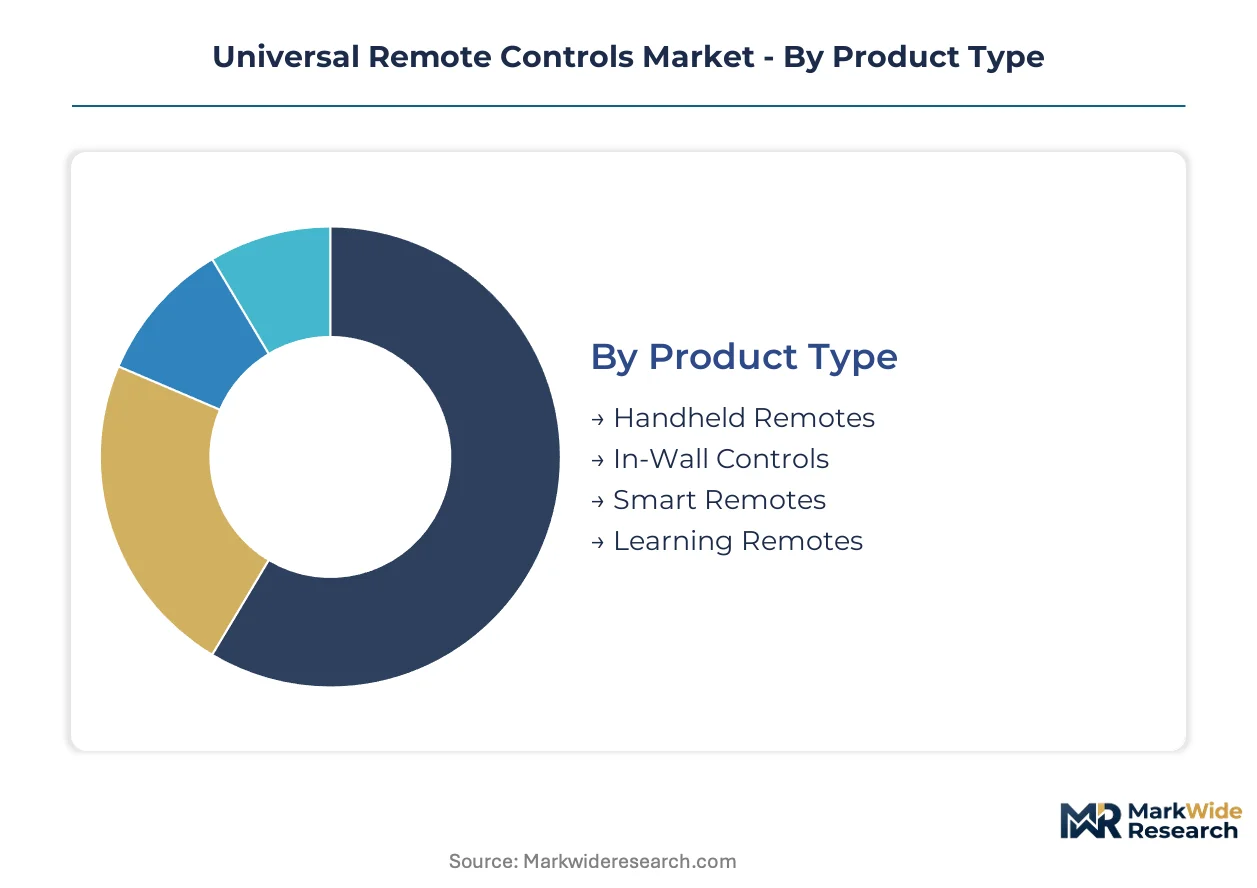
Segmentation in universal remote controls reveals how protocol complexity and installation environment reshape margin structures. Manufacturers optimize SKU portfolios by matching connectivity technology to end-use durability requirements and channel service intensity.
Product Type:
Margin pools concentrate in installed control systems where programming services and recurring firmware updates extend revenue capture beyond hardware shipment.
- Smart Remotes:Bluetooth Low Energy and Wi-Fi connectivity enable Matter protocol interoperability for consolidated smart home orchestration. Demand clusters in United States metropolitan households upgrading from infrared legacy systems as streaming device proliferation complicates entertainment center management. Voice-activated specification tiers command premium positioning against basic handheld alternatives.
- Learning Remotes:Macro sequencing capability absorbs infrared code libraries from existing appliances through optical learning sensors rather than database lookup. Germany's hospitality sector specifies these for property-wide standardization where guest room device mixes vary by construction vintage. Programming complexity sustains integrator channel margins.
- Handheld Remotes:Cost-optimized infrared and RF units dominate volume shipment for replacement cycles in emerging markets.
- In-Wall Controls:Fixed installation touch panels with PoE or low-voltage wiring serve commercial automation projects.
Smart Remotes holds installed capacity. Learning Remotes is rotating up the share rankings.
Technology:
Cost tier stratification separates mature infrared componentry from RF modules requiring FCC Part 15 certification investment.
- RF:Radio frequency transmission penetrates walls and cabinet enclosures without line-of-sight constraints, enabling centralized hotel property management systems. Commercial installations in Germany absorb higher unit costs for range reliability. Chipset supply concentrates in Taiwan foundries, compressing margin for mid-tier manufacturers without captive sourcing.
- Bluetooth:Low Energy stacks support smartphone companion apps and Matter protocol thread border router integration. Residential demand in United States concentrates around ecosystem interoperability promises. FCC emission documentation requirements extend development timelines six to nine months.
- Infrared:Legacy LED transmission dominates television and set-top box compatibility despite obsolescence trajectory.
- Wi-Fi:Direct IP connectivity enables cloud-dependent feature sets and over-the-air firmware updates.
RF commands specification premiums. Bluetooth is climbing the fastest through residential channel expansion.
End User:
Application durability requirements separate consumer replacement cycles from commercial procurement emphasizing centralized manageability.
- Hospitality:Hotel chains contract managed service providers for device code library maintenance and macro programming across property portfolios. Germany's mid-scale urban properties consolidate technical staff to regional hubs, shifting procurement toward subscription-based configuration services. RF-based universal remotes enable centralized in-room device management without guest-visible complexity.
- Residential:Household replacement of decade-old infrared systems accelerates as television refresh intervals compress in China. Smart home integration deepens adoption through consolidated lighting, climate, and entertainment control.
- Commercial:Corporate meeting room installations prioritize standardized control surfaces.
- Healthcare:Antimicrobial surface specifications and sealed enclosures serve clinical environment hygiene protocols.
Hospitality anchors service revenue attachment. Residential is gaining share fastest through smart home convergence.
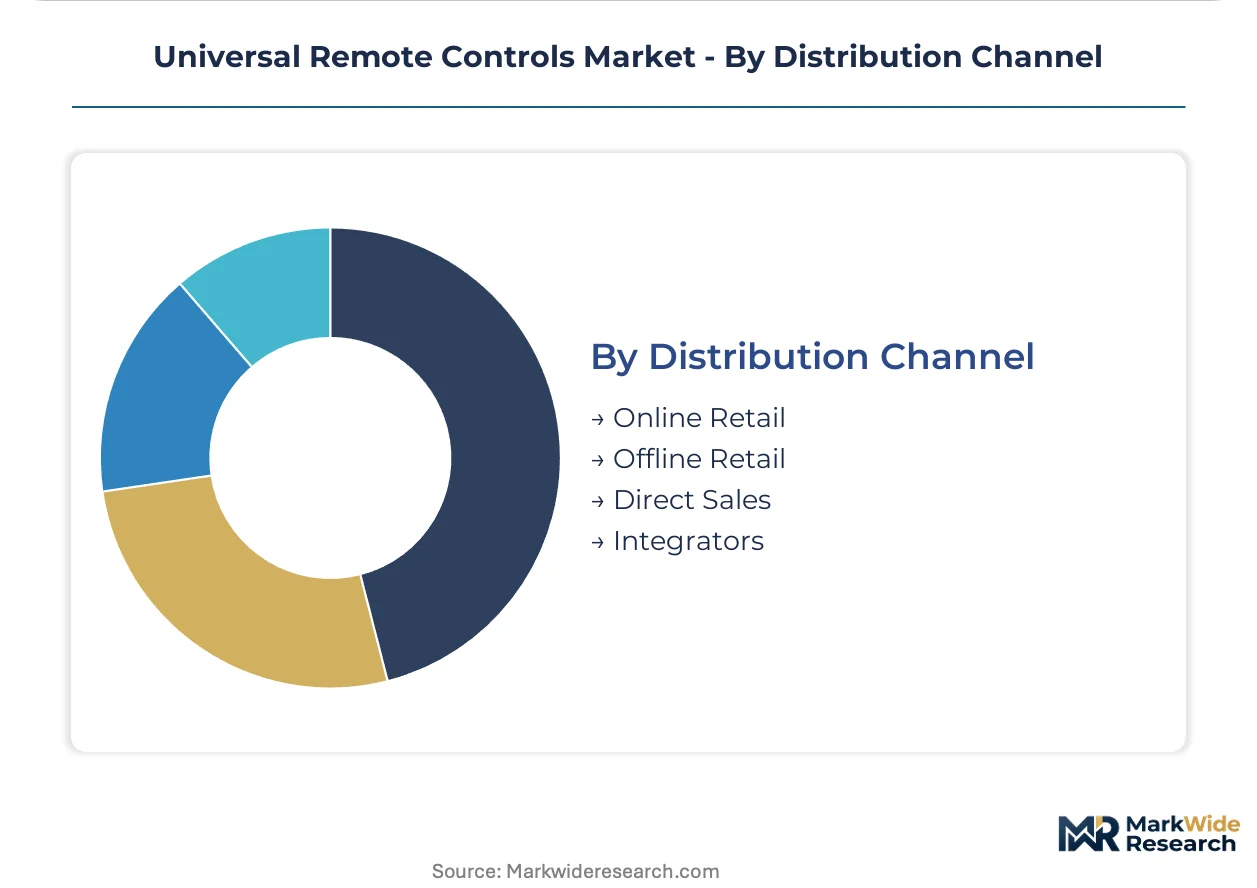
Distribution Channel:
Customer type determines whether procurement flows through self-service retail or specification-driven integrator relationships.
- Integrators:Smart home installation firms in United States specify Thread-enabled remotes for offline-first residential architectures. Technical consultation and post-installation support justify margin structures unavailable through mass retail. Matter protocol certification requirements create tiered product positioning that integrators exploit for differentiation.
- Direct Sales:Cable operators and hospitality chains procure captive volumes through manufacturer direct relationships. Universal Electronics Inc. anchors position through RF chipset supply to North American cable operators.
- Online Retail:E-commerce platforms aggregate consumer comparison shopping for replacement handheld units.
- Offline Retail:Big-box electronics stores sustain impulse purchase visibility for entry-level SKUs.
Integrators capture specification influence. Direct Sales is rotating up the share rankings through hospitality vertical concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers ship cost-optimized infrared handhelds to Southeast Asian retail channels while United States households drive premium smart remote adoption. Germany anchors European hospitality procurement. Taiwan foundries concentrate RF chipset fabrication.
United States
Metropolitan households replace legacy infrared systems with Bluetooth-enabled hubs consolidating lighting and entertainment control. FCC Part 15 emission limits tighten testing documentation requirements for RF-enabled models. Smart home installers in California specify Thread-enabled remotes for offline-first residential architectures.
Germany
Hotel chains deploy RF-based universal remotes for centralized in-room device management without guest-visible complexity. REACH chemical compliance accelerates migration from legacy solder compositions to lead-free assembly processes. Mid-scale urban properties in Berlin consolidate technical staff to regional hubs, shifting procurement toward subscription-based configuration services.
China
Consumers upgrade decade-old infrared systems as television refresh intervals compress in urban centers. MIIT certifies wireless transmission frequencies under GB standards, forcing manufacturers to maintain region-specific firmware variants. Guangzhou anchors cost-optimized manufacturing for entry-level handheld remotes across domestic and export channels.
Taiwan
Advanced foundries concentrate RF chipset fabrication for cable operators and commercial installers. Capacity constraints at these facilities create vulnerability across the supply chain. Taipei-based semiconductor clusters supply captive volumes to North American cable operators through direct manufacturer relationships.
Universal Remote Controls Market Competitive Landscape
Listed leaders compete with private specialists across ecosystem integration and manufacturing scale dimensions. The vendor base stratifies between software-anchored platforms, component-integrated manufacturers, and cost-driven fabricators. Three archetypes dominate: ecosystem orchestrators leveraging proprietary software stacks, RF specialists with captive chipset supply, and volume producers optimizing Southeast Asian retail channels. Competitive moves center on Matter protocol certification races and direct procurement relationships with cable operators and hospitality chains.
Within the ecosystem orchestrator tier, Logitech leverages its Harmony software platform to sustain loyalty among home-theater enthusiasts. Universal Electronics Inc. anchors the RF specialist position through captive supply relationships with North American cable operators. Guangzhou SYSTO Trading Co., Ltd. represents the volume-driven archetype, occupying cost-optimized manufacturing for entry-level handheld remotes across Southeast Asian retail channels.
| Leading Market Players |
|---|
| Logitech |
| Jasco |
| Universal Electronics Inc. (UEI) |
| Amazon Basics |
| Voxx International |
| Universal Remote Control (URC) |
| Philips |
| Guangzhou SYSTO Trading Co., Ltd. |
| BroadLink |
| Others |
Value Network & Pricing Analysis
Ninety-day chipset lead times from Taiwan foundries compress margin flexibility for RF-enabled universal remote manufacturers while amplifying pricing power among captive suppliers to North American cable operators. This inventory-to-pricing dynamic separates manufacturers with backward-integrated component sourcing from assembly-only competitors exposed to spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the universal remote controls market. Price differentiation rests on Matter protocol certification grade and volume scale commitments from hospitality chains. Cost compression in entry-level infrared handhelds is intensifying because Guangzhou SYSTO Trading floods Southeast Asian retail channels with undifferentiated alternatives. Hospitality procurement teams show lowest price sensitivity due to subscription-based configuration service bundling.
Supply Chain Analysis
Taiwan and China anchor RF chipset fabrication and cost-optimized assembly respectively for universal remote manufacturing. Raw material dependencies include silicon wafers, lithium coin cells, and ABS enclosures. Single-source vulnerability concentrates at advanced foundries supplying Bluetooth Low Energy modules to mid-tier producers. Distribution runs through direct manufacturer relationships with cable operators and integrator channels serving smart home installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-based control applications threaten dedicated hardware incumbents as households consolidate device management through ecosystem-native software interfaces.
For Market Incumbents: Compound defensive positioning through captive RF chipset supply relationships and accelerated Matter certification investment. Logitech's Harmony software ecosystem demonstrates how platform stickiness resists substitution from app-based alternatives. Universal Electronics Inc. anchors margin protection through direct procurement contracts with North American cable operators that lock out modular competitors. For New Entrants and Emerging Players: Differentiate on Thread-enabled offline-first architectures targeting United States metropolitan smart home installers frustrated by cloud-dependent latency. The hospitality vertical in Germany presents penetrable white-space where subscription-based managed services displace one-time hardware purchases. Go-to-market execution should prioritize integrator channel partnerships over mass retail distribution. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because protocol standardization collapses hardware differentiation toward ecosystem orchestration capabilities. Acquisition targets should profile as RF specialists with captive foundry relationships or software-anchored platforms with recurring revenue attachment. The signal to watch is Matter certification completion rates as a leading indicator of which product architectures justify continued R&D investment.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Interoperability mandates under the Connectivity Standards Alliance determine product viability across United States and European Union markets. |
| Backward Integration into RF Chipsets | Captive semiconductor sourcing insulates margin from Taiwan foundry capacity constraints affecting mid-tier competitors. |
| Subscription Service Launch | Managed configuration contracts with German hotel chains convert transactional hardware revenue into recurring service attachment. |
| Integrator Channel Partnership | Technical specification influence through United States smart home installers commands premium positioning unavailable through retail. |
| Voice Control Convergence | Natural language processing integration opens premium specification tiers beyond basic handheld alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from smart home installation firms, hospitality procurement directors, RF chipset procurement leads, and consumer electronics retail category managers and refined through secondary validation against FCC Part 15 filings, MIIT GB standard certifications, SEC 10-K disclosures from listed component suppliers, and hospitality industry procurement databases. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates protocol adoption curves, replacement cycle compression, and certification timeline delays as primary uncertainty sources. Segmentation dimensions modeled include connectivity technology, installation environment, distribution channel, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to smart home penetration data and television refresh interval observations. Industry-specific forecast inputs incorporate Matter certification completion rates and Taiwan foundry capacity utilization trends.
Material uncertainties — silicon supply disruptions, regulatory protocol revisions, and smartphone substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and hospitality procurement pattern continuity. Recalibration cycles align with material shifts in Connectivity Standards Alliance specification releases and foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Watch Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Vape Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
FMCG Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market