
 Smart Carry-On Luggage Market | 2026-2036
Smart Carry-On Luggage Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Carry-On Luggage Market Insights
Subscription-based GPS tracking services is recalibrating how manufacturers monetize smart carry-on luggage beyond the initial hardware sale. Samsonite leverages its global distribution network to anchor premium positioning across airport retail channels. Rimowa differentiates through aluminum construction heritage paired with digital connectivity modules. Away Travel competes on direct-to-consumer channel control and modular battery replacement programs.
Smart carry-on luggage integrates hard-shell or soft-shell enclosures with embedded lithium power banks, Bluetooth proximity sensors, and GPS location modules to enable real-time tracking, remote locking, and device charging during transit. The assembly requires precision molding of polycarbonate or aluminum shells alongside UL-certified battery compartment isolation to meet aviation safety standards. Smart suitcase configurations dominate unit volume due to standardized sizing for overhead bin compliance, while GPS-enabled products capture disproportionate margin pools from security-conscious segments. Bluetooth-based proximity alerts lead technology adoption for short-range anti-theft functionality, though RFID integration is gaining traction in business traveler channels for automated baggage handling compatibility.
FAA guidelines on lithium-ion battery watt-hour limits constrain power bank specifications for US-bound products, while IATA Dangerous Goods Regulations shape international airline acceptance protocols. The EU's CE marking requirements and REACH chemical compliance standards govern material composition for European market access. Stakeholders must monitor evolving airline-specific bans on smart luggage with non-removable batteries and prioritize modular power architectures that adapt to jurisdiction-specific carriage rules.
Market Dynamics
Aviation safety regulators are fragmenting product design requirements across jurisdictions, forcing manufacturers to engineer modular battery architectures that adapt to airline-specific carriage rules rather than pursuing universal compliance.
Growth Catalysts
- Business traveler demand:Frequent flyers prioritize real-time baggage tracking and remote locking capabilities, creating premium price tolerance for connected luggage features.
- FAA lithium battery guidelines:Removable power bank mandates have standardized modular design practices, enabling faster product certification cycles for US-bound shipments.
- Bluetooth proximity sensors:Short-range anti-theft functionality now ships as baseline equipment, expanding addressable market from security-conscious segments to mainstream leisure travelers.
Market Restraints
- Polycarbonate resin volatility:Hard-shell enclosure costs fluctuate with petrochemical feedstock prices, compressing margin buffers for mid-tier manufacturers.
- Supply concentration in Guangdong:Precision molding and battery compartment assembly cluster in China's Pearl River Delta, exposing production schedules to regional logistics disruptions.
- IATA Dangerous Goods Regulations:International airline acceptance protocols vary by carrier, creating inventory segmentation costs and complicating global distribution strategies.
Strategic Opportunities
- India premium travel corridor:Underpenetrated connected luggage penetration among domestic business flyers offers first-mover positioning before local manufacturing scales.
- RFID-IATA integration:Automated baggage handling compatibility standards create upgrade cycles for existing Bluetooth-only installed bases at major hub airports.
- Subscription GPS tracking:Recurring revenue services monetize hardware relationships beyond point-of-sale, shifting customer lifetime value calculations for direct-to-consumer brands.
Industry Challenges
- UL-certified battery isolation engineering:Aviation-grade compartment design requires specialized thermal runaway containment expertise that outstrips available talent pools.
- Multi-jurisdiction certification timelines:Parallel FAA, CE marking, and IATA compliance processes extend product launch windows and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Carry-On Luggage Market |
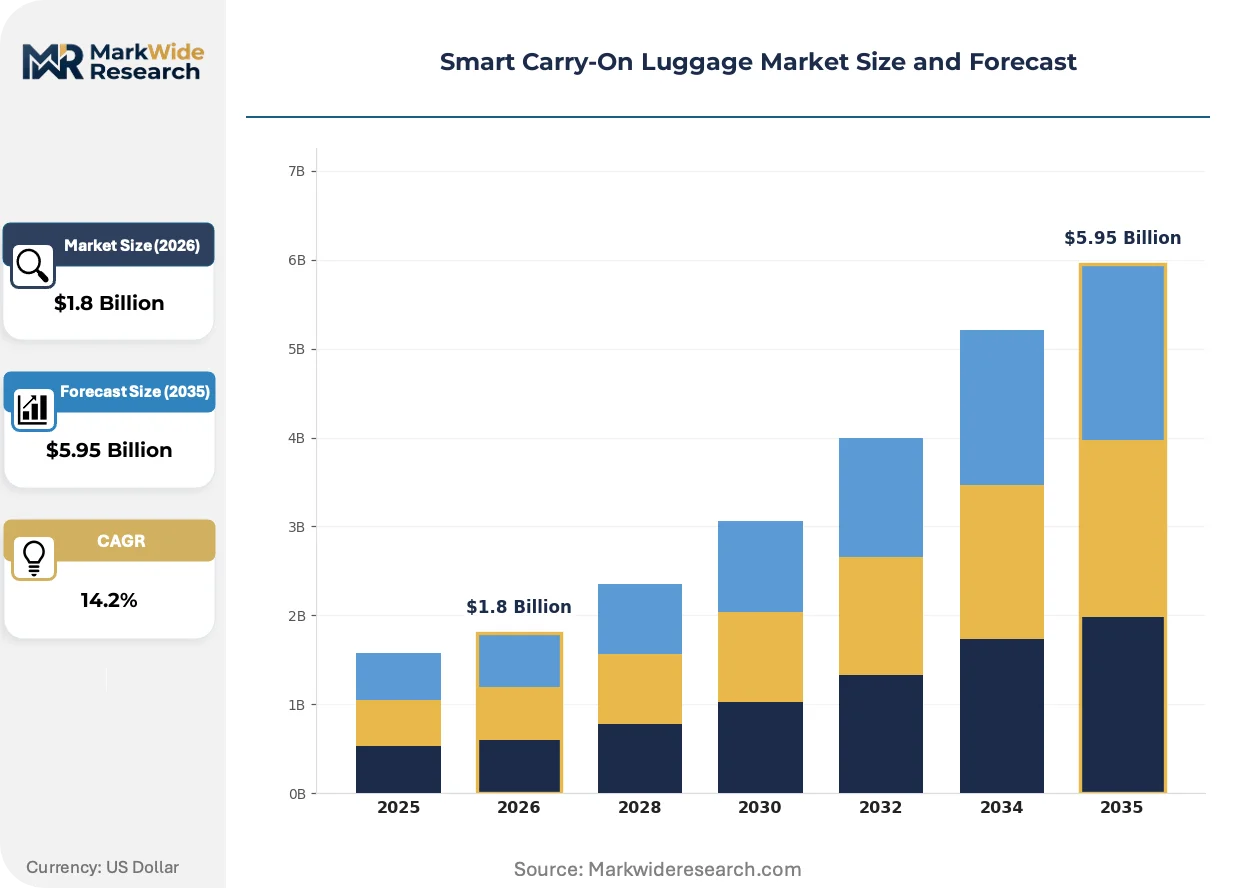
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Suitcase, Smart Backpack, Smart Duffel, Smart Briefcase Technology: Bluetooth, RFID, GPS, Lithium Battery End User: Frequent Travelers, Business Travelers, Students, Adventurers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Travel Retail |
| Companies Covered | Samsonite, Rimowa, Tumi, Away Travel, Delsey, Travelpro International, Horizn Studios, Level8, Arlo Skye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Carry-On Luggage Market Trends and Innovations
Digital connectivity modules are converging with traditional luggage construction, compressing development cycles and redefining which competencies determine competitive advantage in travel goods manufacturing.
GPS-GSM hybrid tracking is unifying location services with cellular fallback protocols, eliminating dead zones in aircraft cargo holds and underground baggage systems. Corporate travel managers now specify this dual-mode architecture in RFPs for executive luggage programs. The technology is unifying previously separate device-charging and asset-tracking procurement decisions into single-vendor relationships.
REACH chemical compliance standards are restricting polycarbonate additive formulations used in European market products, forcing reformulation of flame-retardant compounds. German and French distributors now require full material disclosure documentation before listing new SKUs. Premium aluminum-shell manufacturers capture share as they face fewer substitution constraints under the same regulatory framework.
Airport retail channel consolidation is concentrating buyer power among duty-free operators and travel convenience chains, marginalizing independent luggage boutiques. Direct-to-consumer brands bypass this gatekeeper structure through pre-order crowdfunding and modular battery replacement subscriptions. China and Germany exhibit the most pronounced channel bifurcation between heritage retail and digital-native entrants.
Smart Carry-On Luggage Market Segmentation
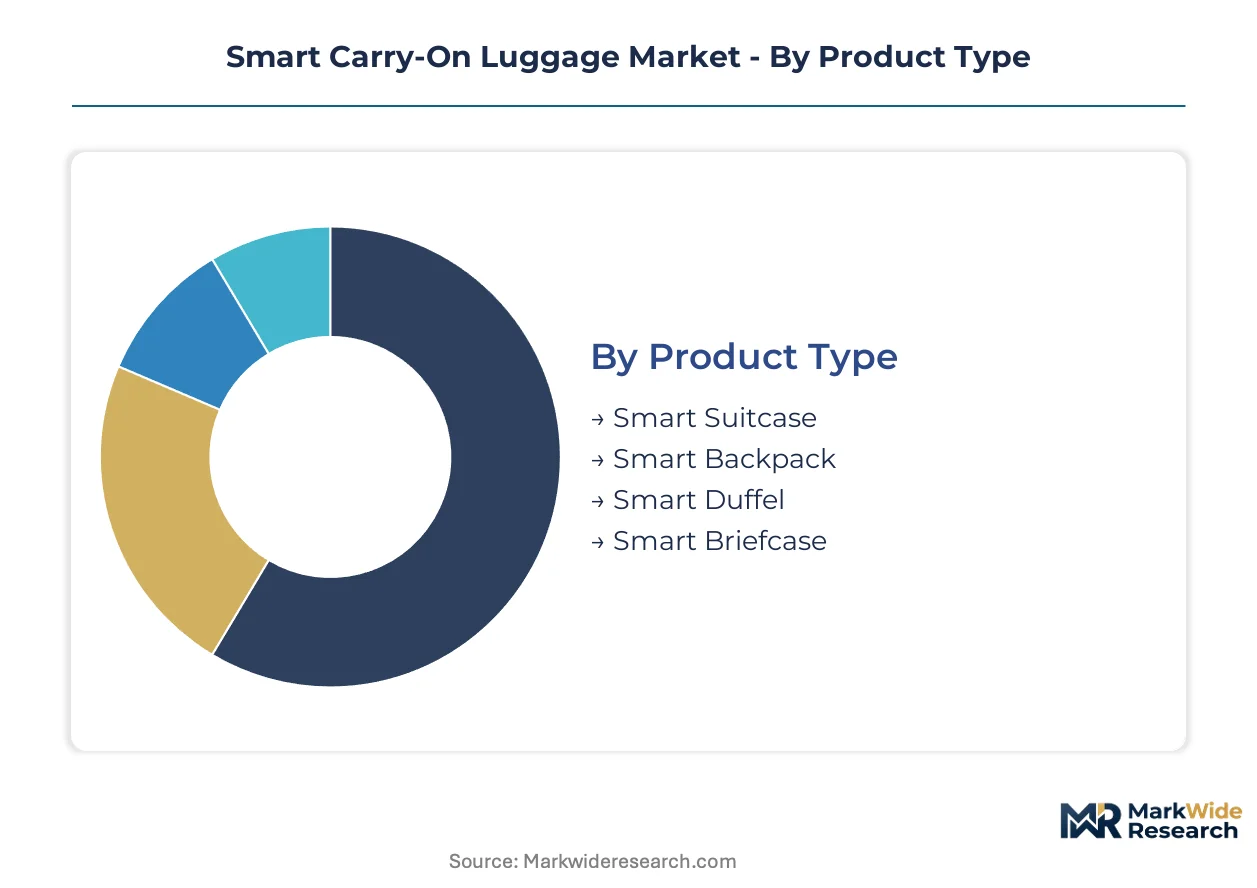
Segmentation in smart carry-on luggage reveals how distinct user workflows and regulatory exposure shape purchasing criteria. Buyers prioritize overhead bin compliance, battery modularity, or connectivity range depending on travel frequency and route complexity.
Product Type:
Overhead bin dimensional limits and battery accessibility rules drive purchase decisions across enclosure formats.
- Smart Suitcase:Hard-shell polycarbonate or aluminum enclosures integrate UL-certified battery compartments with GPS-GSM modules. Demand concentrates among business travelers on US-China and Germany-United States premium corridors where FAA and IATA carriage rules require removable power architectures.
- Smart Backpack:Soft-shell nylon or polyester construction with embedded Bluetooth proximity sensors and laptop charging ports. Adoption accelerates among students and urban commuters in India and Germany who prioritize under-seat flexibility and lighter carry weight.
- Smart Duffel:Flexible compartment designs with RFID-tagged pockets for automated baggage handling compatibility. Frequent leisure travelers favor this format for irregular cargo shapes.
- Smart Briefcase:Compact form factors with device charging and remote locking for executive day trips. Corporate procurement programs in the United States specify this category for short-haul executive travel.
Volume sits with Smart Suitcase; growth tilts toward Smart Backpack.
Technology:
Regulatory jurisdiction determines which connectivity protocols manufacturers must certify for market access.
- Bluetooth:Short-range proximity alerts via BLE 5.0 modules enable anti-theft functionality within 30-meter ranges. This baseline technology ships across all price tiers due to minimal certification burden and universal smartphone compatibility.
- GPS:GPS-GSM hybrid tracking with cellular fallback eliminates location dead zones in aircraft cargo holds and underground baggage systems. Corporate travel managers in the United States and Germany now mandate this dual-mode architecture in executive luggage RFPs.
- RFID:Passive and active radio-frequency identification enables automated baggage handling at IATA-compliant hub airports. Installation accelerates at Frankfurt, Atlanta, and Beijing Capital as airlines retrofit sortation infrastructure.
- Lithium Battery:Removable power banks with watt-hour ratings under FAA limits constrain design flexibility but enable US market access. Modular architectures now dominate product roadmaps to accommodate jurisdiction-specific carriage rules.
Bluetooth captures installed base volume; GPS expands most quickly.
End User:
Travel frequency and security sensitivity segment willingness to pay for connected features.
- Business Travelers:Frequent flyers averaging 50+ annual segments demand real-time tracking, remote locking, and device charging. This segment commands premium pricing and drives GPS-GSM specification in corporate procurement programs across the United States and Germany.
- Frequent Travelers:Leisure road warriors prioritize Bluetooth proximity alerts and modular battery replacement for cost-conscious connectivity. Demand clusters in China's domestic premium travel corridors.
- Students:Price-sensitive buyers favor lightweight smart backpacks with basic charging and anti-theft features. India's underpenetrated connected luggage market shows particular concentration here.
- Adventurers:Durability-focused users require ruggedized enclosures with extended battery life for off-grid positioning. Specialized demand remains fragmented across expedition travel operators.
Business Travelers anchor revenue; Students claim the steepest expansion trajectory.
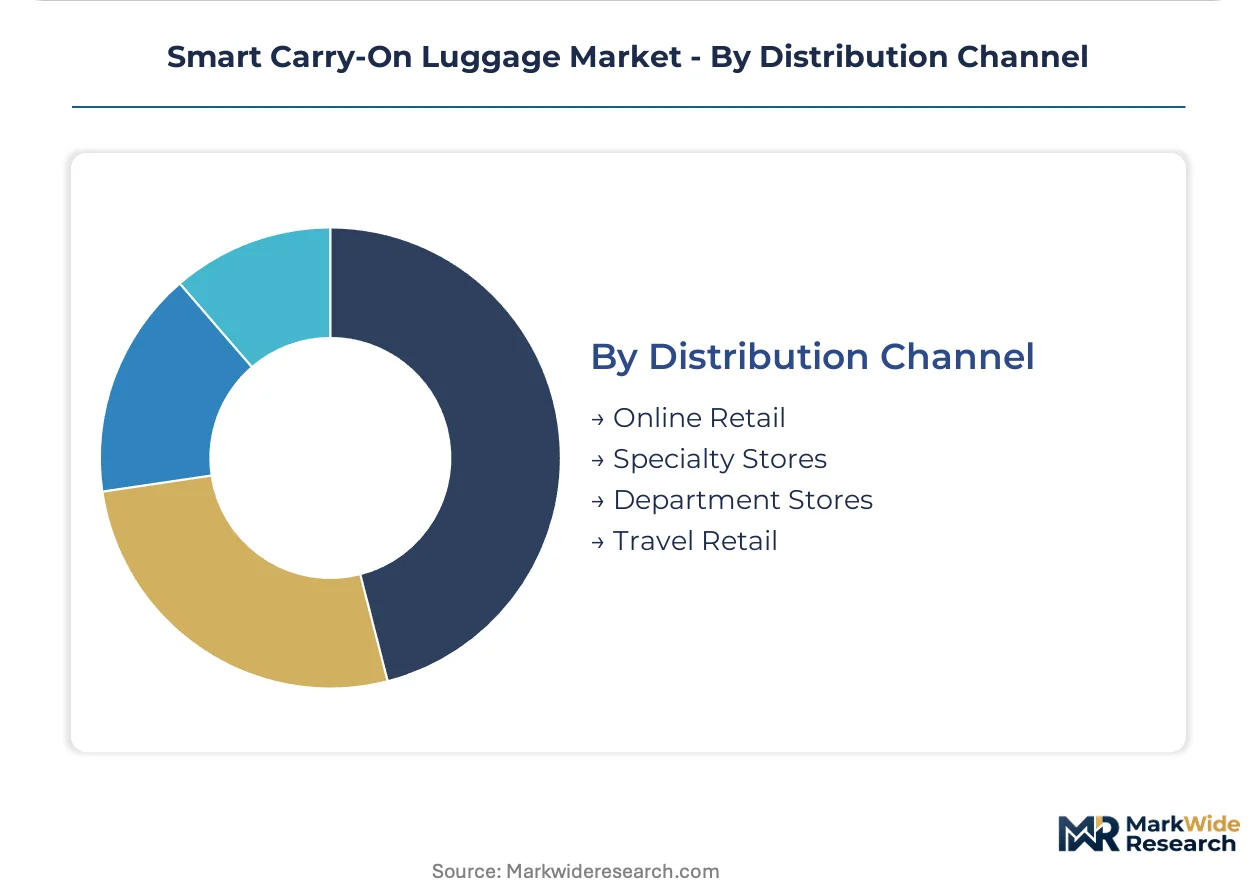
Distribution Channel:
Channel control determines margin capture and customer relationship duration.
- Online Retail:Direct-to-consumer platforms enable subscription GPS tracking monetization and modular battery replacement programs. Digital-native brands leverage this channel to bypass duty-free gatekeepers in China and Germany.
- Travel Retail:Airport duty-free operators and travel convenience chains concentrate buyer power, marginalizing independent boutiques. Heritage manufacturers anchor premium positioning here through Samsonite's global distribution network.
- Specialty Stores:Independent luggage retailers provide hands-on battery demonstration and fitting services. Foot traffic declines as airport retail consolidates.
- Department Stores:Mid-tier positioning with seasonal promotional cycles attracts mainstream leisure buyers. Inventory breadth constraints limit smart feature assortment depth.
Travel Retail holds volume concentration; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province concentrates precision molding and battery compartment assembly, while the United States, Germany, and China absorb the majority of finished goods. This production-consumption asymmetry exposes distribution networks to regional logistics disruptions and jurisdiction-specific certification delays.
United States
FAA lithium-ion watt-hour limits and removable power bank mandates shape product specifications for US-bound inventory. Business travelers on domestic premium corridors drive GPS-GSM hybrid tracking adoption in corporate procurement programs. Atlanta and Dallas-Fort Worth serve as distribution hubs where airport retail consolidation concentrates buyer power among duty-free operators.
China
Domestic premium travel corridors between Beijing, Shanghai, and Shenzhen accelerate smart backpack adoption among frequent leisure travelers. MIIT radio equipment certification and GB standards for lithium battery transport govern product design for local manufacturing. The Pearl River Delta cluster around Shenzhen and Dongguan houses precision molding capacity and UL-certified battery isolation engineering expertise.
Germany
REACH chemical compliance standards and CE marking requirements restrict polycarbonate additive formulations for European market access. Frankfurt Airport's automated baggage handling retrofit drives RFID integration demand among business traveler segments. Bavaria and North Rhine-Westphalia host heritage luggage manufacturers anchoring premium positioning through airport retail channels.
India
Underpenetrated connected luggage penetration among domestic business flyers creates first-mover positioning opportunities before local manufacturing scales. BIS certification for electronic products and DGFT import regulations shape market entry strategies. Maharashtra and Karnataka concentrate demand from students and urban commuters prioritizing lightweight smart backpacks with basic charging features.
Japan
METI energy efficiency standards and PMDA-equivalent consumer product safety protocols govern smart luggage market access. Tokyo and Osaka business districts specify compact smart briefcases for executive day-trip procurement programs. Kanto region distributors require full material disclosure documentation under evolving chemical compliance frameworks.
Smart Carry-On Luggage Market Competitive Landscape
Top-tier vendors anchor premium positioning through global airport retail networks, while direct-to-consumer specialists compete on subscription monetization and modular service programs. The vendor base stratifies across heritage manufacturers with aluminum construction expertise, digital-native brands with channel control, and Asian fabricators with cost-optimized polycarbonate enclosures. Strategic archetypes include full-service luggage houses, connectivity module integrators, and component specialists. Dominant competitive moves encompass M&A to acquire thermal runaway containment engineering capabilities and strategic partnerships with airlines for automated baggage handling compatibility.
Within the heritage manufacturer tier, Samsonite and Rimowa exemplify premium positioning through global distribution scale and aluminum construction heritage respectively. Away Travel occupies a distinct position as a digital-native direct-to-consumer brand leveraging subscription GPS tracking and modular battery replacement programs to bypass traditional airport retail gatekeepers.
| Leading Market Players |
|---|
| Samsonite |
| Rimowa |
| Tumi |
| Away Travel |
| Delsey |
| Travelpro International |
| Horizn Studios |
| Level8 |
| Arlo Skye |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap polycarbonate molders in Guangdong Province anchor tier-two manufacturing, constraining capacity expansion capital and amplifying pricing leverage for heritage brands with captive aluminum-shell production. This ownership structure concentrates supply-side discipline while fragmenting cost-down pressure across battery compartment integrators competing for UL-certified assembly slots.
Pricing Analysis
Margin tightening in mid-tier polycarbonate enclosures traces to petrochemical feedstock volatility and Guangdong resin import dependencies. Three-tier pricing structure across premium aluminum, standard polycarbonate, and economy ABS tiers separates Rimowa's heritage positioning from Away's direct-to-consumer subscription bundling and Level8's cost-optimized China domestic play. Certification tier—specifically FAA-compliant removable battery architectures versus fixed-cell legacy inventory—drives the steepest price premiums. Students and urban commuters in India exhibit highest price sensitivity, while US corporate procurement programs for executive travel show lowest elasticity.
Supply Chain Analysis
UL-certified battery isolation engineering gates supplier qualification, limiting certified compartment assemblers to Guangdong, South Korea, and select Bavarian specialists. Precision molding draws from polycarbonate resin suppliers in Saudi Arabia and Singapore, lithium cells from South Korean and Japanese producers, and GPS-GSM modules from Taiwanese connectivity specialists. Single-source vulnerability concentrates in Guangdong's Pearl River Delta cluster, where regional logistics disruptions propagate through global finished goods distribution. Distribution runs through airport duty-free operators and direct-to-consumer platforms, with channel bifurcation most pronounced in China and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation-grade thermal runaway containment engineering capacity scarcity props pricing power for certified manufacturers, constraining supply elasticity across the projection horizon.
For Market Incumbents: Hedge polycarbonate cost exposure through backward integration into aluminum-shell production or strategic sourcing partnerships with Saudi resin suppliers. Acquire thermal runaway containment engineering capabilities via specialist tuck-ins before certification bottlenecks harden. Prioritize modular battery architecture R&D to maintain FAA compliance optionality as IATA carriage rules fragment. For New Entrants and Emerging Players: Launch via direct-to-consumer crowdfunding platforms targeting India's underpenetrated student and urban commuter segments with lightweight smart backpacks. Exploit BIS certification backlogs to establish first-mover positioning before local manufacturing scales. Anchor go-to-market on modular battery replacement subscriptions rather than hardware margin capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor connectivity module integrators with captive UL-certified battery compartment engineering in South Korea and Bavaria over pure-play polycarbonate assemblers. Five-to-ten-year viability hinges on airline partnership density for automated baggage handling compatibility. Watch Frankfurt and Atlanta RFID retrofit completion rates as inflection indicators for enterprise procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Architecture Investment | FAA and IATA compliance flexibility preserves US and EU market access amid regulatory fragmentation. |
| RFID-IATA Integration Partnership | Automated baggage handling compatibility at Frankfurt and Atlanta hubs unlocks corporate procurement RFPs. |
| Direct-to-Consumer Platform Launch | Subscription GPS tracking monetization bypasses airport duty-free gatekeeper consolidation in China and Germany. |
| Thermal Runaway Containment Acquisition | UL-certified engineering scarcity limits competitor replication and sustains premium pricing tiers. |
| India Market Entry with Smart Backpacks | BIS certification first-mover positioning captures student segment growth before local manufacturing scales. |
Research Methodology
Document review covered customs trade databases, SEC filings from publicly traded luggage and electronics manufacturers, FAA and IATA regulatory guidance documents, and REACH compliance bulletins, complemented by interviews with product development executives at heritage luggage houses, procurement managers at airport duty-free operators, UL certification engineers, and direct-to-consumer brand operations leads. Secondary validation drew from airline baggage handling infrastructure disclosures, polycarbonate resin price indices, and MIIT radio equipment certification registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Unit volume and value projections across the analysis window reflect demand modeling by product type, technology protocol, end-user segment, and distribution channel, with geographic splits calibrated to country-specific regulatory adoption curves. CAGRs derive from logistic diffusion curves fitted to business traveler connectivity adoption patterns and corporate procurement specification timelines. Forecast inputs incorporate FAA lithium battery rule evolution scenarios and IATA Dangerous Goods Regulation harmonization probabilities.
Polycarbonate resin price volatility, FAA watt-hour limit revisions, and airline-specific smart luggage ban implementations are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding certification timeline standardization and RFID infrastructure deployment rates at major hub airports. A model refresh is warranted upon material change in IATA automated baggage handling compatibility mandates or EU REACH chemical compliance scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Trolley Bags Market
Luggage
United States Sports Bags Market
Luggage
Backpack Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Global Premium Luggage Market
Luggage
Kids Backpack Market
Luggage
Second Hand Bag Market
Luggage
Trunks Market
Luggage
Laptop Carry Case Market
Luggage
Smart Bags Market
Luggage
Bags Market
Luggage
Global Luggage Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Travel and Business Bags Market
Luggage
Sports Luggage Market
Luggage
Camera Bag Market