
 Second Hand Bag Market | 2026-2036
Second Hand Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Second Hand Bag Market Outlook
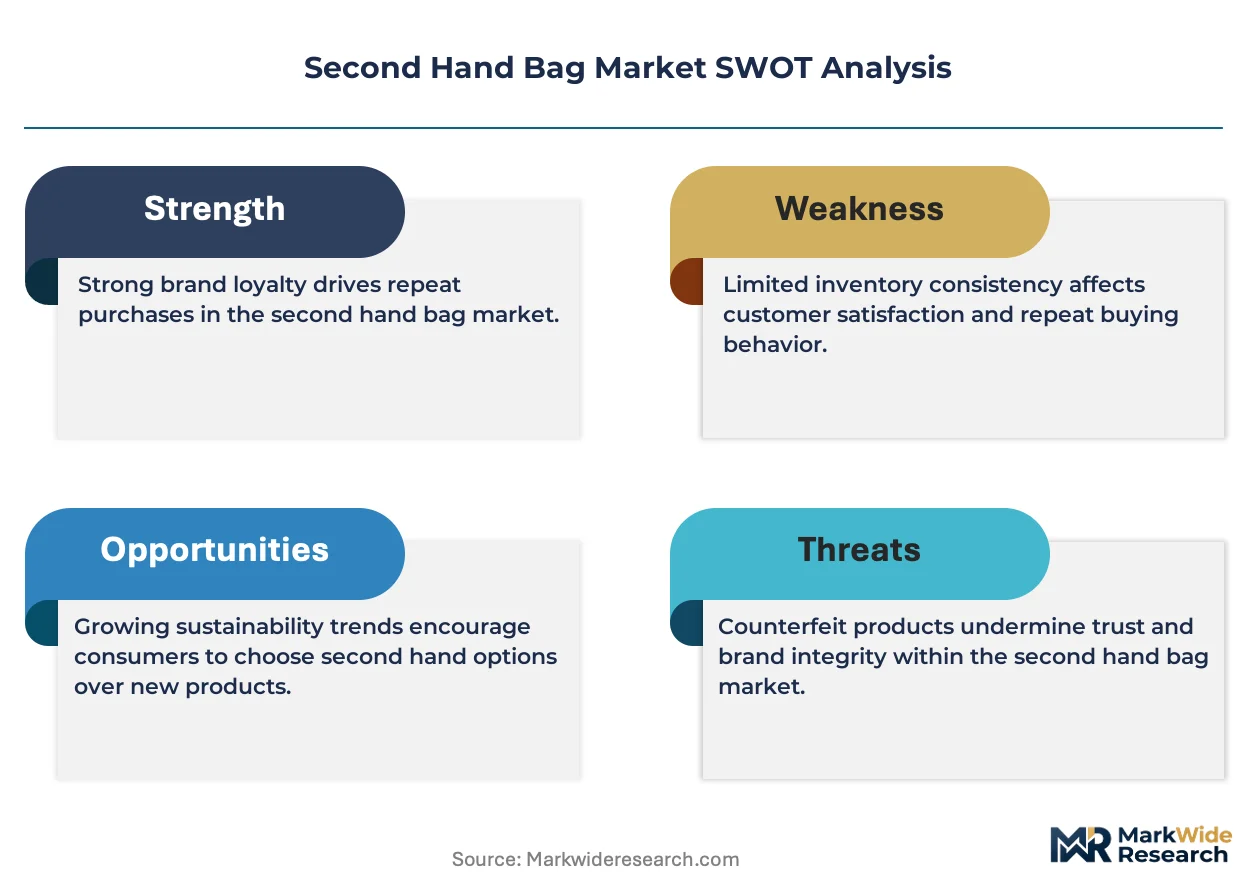
The authentication-capability gap between capital-heavy platforms and lean marketplaces is unwinding competitive hierarchies in pre-owned luxury accessories. The RealReal sustains proprietary in-house authentication infrastructure across eleven physical facilities. Fashionphile leverages consignment-based inventory models that minimize working-capital intensity. Rebag anchors consumer trust through its Clair pricing algorithm and direct-purchase guarantees.
Second hand bags comprise previously owned personal carrying accessories evaluated for condition, provenance, and authenticity before recommerce. Leather constructions dominate authenticated resale due to material longevity and brand heritage value retention. Handbags and totes lead transaction volumes, while clutches command premium price-to-weight ratios in luxury consignment. The leather material segment captures the deepest margin pools, whereas synthetic alternatives expand accessibility in mid-range and affordable tiers.
France's DGCCRF enforces anti-counterfeiting statutes that mandate traceability documentation for resale platforms. The EU Green Deal's circular economy action plan imposes extended producer responsibility frameworks on fashion value chains. The US FTC's Green Guides scrutinize environmental marketing claims in resale channels. Stakeholders must monitor evolving authentication standards and cross-border customs classifications that determine platform operating economics.
Market Dynamics
The authentication-capability gap between capital-heavy platforms and lean marketplaces is compressing competitive hierarchies in pre-owned luxury accessories, forcing working-capital discipline and proprietary technology investments.
Growth Catalysts
- EU Green Deal circular economy mandates:Extended producer responsibility frameworks accelerate authenticated pre-owned commerce across European fashion value chains.
- Digital resale platforms:Fashion-conscious millennials and Gen Z buyers drive adoption through mobile-first authentication and consignment interfaces.
- Leather material longevity:Brand heritage value retention in leather constructions sustains deep margin pools for authenticated resale specialists.
Market Restraints
- Authentication labor intensity:Proprietary in-house infrastructure requires physical facility networks that strain operating leverage for emerging platforms.
- Cross-border customs friction:Divergent tariff classifications for pre-owned luxury goods complicate platform economics in transatlantic trade corridors.
- Synthetic material substitution:Mid-range accessible alternatives erode pricing power in non-luxury tiers where provenance premiums collapse.
Strategic Opportunities
- Clutch segment premiumization:Price-to-weight ratio advantages in compact luxury formats remain underexploited by volume-focused marketplaces.
- Direct-purchase guarantee models:Algorithmic pricing transparency builds consumer trust and accelerates inventory velocity versus consignment delays.
- French regulatory anchoring:DGCCRF traceability documentation requirements create compliance moats for platforms with established documentation systems.
Industry Challenges
- Authentication talent scarcity:Expertise in provenance verification and condition grading requires specialized training pipelines that outpace platform scaling.
- FTC Green Guides compliance:Environmental marketing claims in resale channels face heightened scrutiny, demanding legal infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second Hand Bag Market |
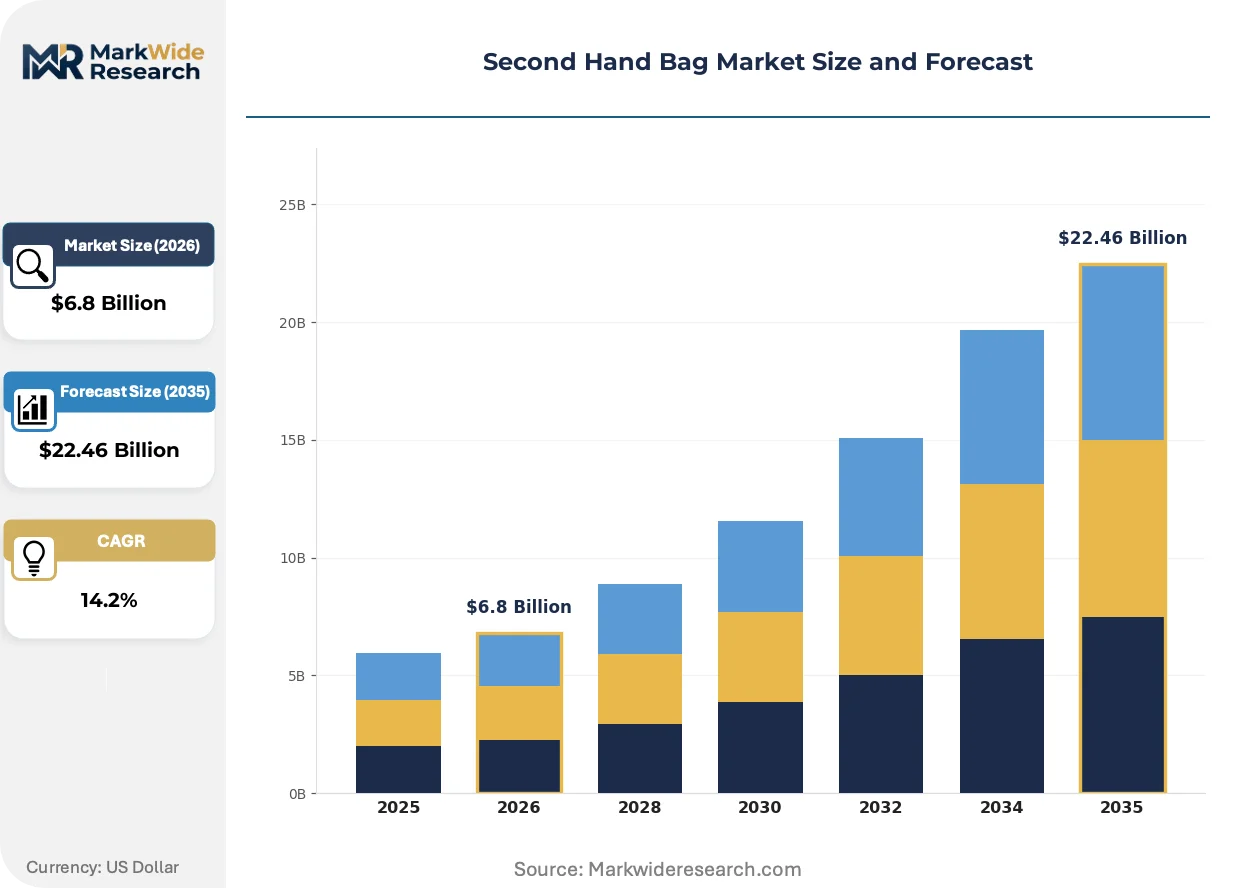
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handbags, Backpacks, Clutches, Totes Material: Leather, Canvas, Synthetic, Cotton Brand: Chanel, Gucci, Louis Vuitton, Prada Price Tier: Luxury, Mid-range, Affordable, Discounted |
| Companies Covered | The RealReal, Fashionphile, Rebag, Farfetch, Vestiaire Collective, The 1916 Company, Alex Cooper Auctioneers, Poshmark, ThredUp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second Hand Bag Market Strategic Shifts
Algorithmic pricing and authentication automation are compressing transaction friction while regulatory traceability mandates reshape platform infrastructure requirements across resale channels.
Machine-learning condition assessment is decomposing traditional expert-dependent authentication workflows. Mid-range resale platforms deploy computer vision for preliminary grading, reducing specialist labor bottlenecks. This compression of authentication costs is decomposing the capital barrier that previously protected incumbent marketplaces.
France's DGCCRF anti-counterfeiting statutes now mandate traceability documentation for all resale platforms operating within national jurisdiction. The enforcement mechanism requires serialized provenance chains that increase compliance overhead. Luxury consignment specialists in Paris and Lyon have responded by building captive documentation systems that smaller cross-border entrants cannot replicate.
Buyer preference is rotating toward direct-purchase guarantees over traditional consignment delays. Fashion-conscious consumers in urban French markets now prioritize immediate liquidity and price transparency. This behavioral pivot rewards platforms with algorithmic pricing infrastructure while compressing margins for legacy consignment-dependent operators.
Second Hand Bag Market Segmentation
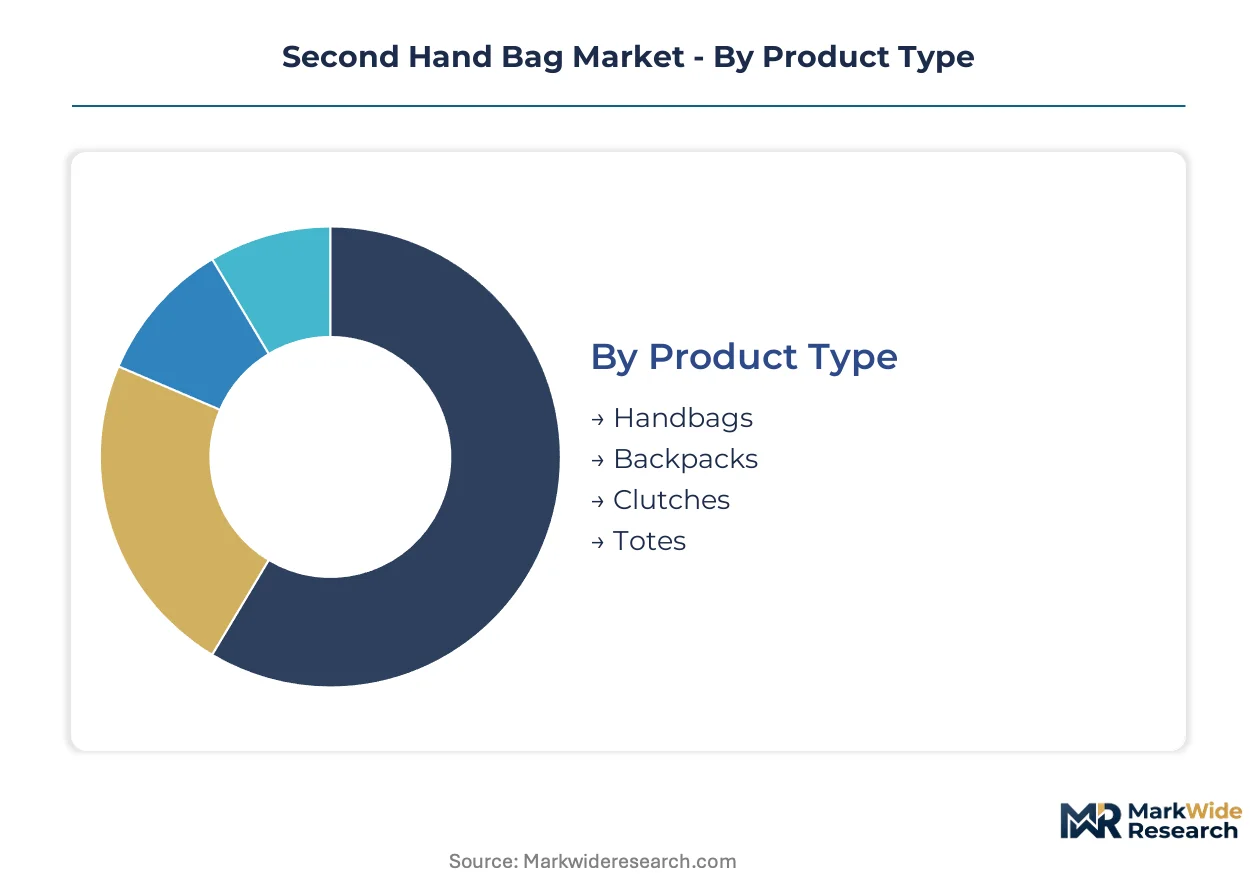
Pre-owned bag commerce fragments across four distinct taxonomies that reshape platform inventory strategies and authentication workflows. Each segmentation axis channels different margin structures, customer acquisition costs, and resale velocity profiles. Platforms must optimize across these dimensions simultaneously to capture sustainable economics.
Product Type:
Channel mix varies sharply by format: structured silhouettes dominate authenticated luxury consignment, while soft constructions concentrate in peer-to-peer marketplaces.
- Handbags:Structured silhouettes with reinforced frames and hardware closures define this core category. Demand concentrates in Paris and Milan resale corridors where archival documentation commands authentication premiums. Leather construction dominance sustains margin depth despite higher inspection labor.
- Backpacks:Dual-strap carrying systems with compartmentalized interiors attract functional utility buyers. Urban commuter markets in Berlin and Amsterdam drive volume through durability-focused purchasing. Growth pace accelerates fastest among Gen Z demographics prioritizing hands-free mobility.
- Clutches:Compact handheld formats for evening and formal occasions. Compact dimensions reduce shipping costs and authentication time.
- Totes:Open-top carrying structures with maximal interior volume. Workwear applications dominate secondary market flows.
By volume, totes lead. By growth pace, backpacks are expanding most quickly.
Material:
Cost tier alignment determines authentication intensity: premium substrates require proprietary expertise while synthetic alternatives enable automated grading.
- Leather:Tanned hide constructions with grain-specific wear patterns that authenticate provenance. French atelier heritage brands in Lyon and Paris sustain deepest margin pools through material longevity documentation. EU Green Deal circular economy mandates favor durable substrate resale.
- Synthetic:Polyurethane and PVC alternatives with uniform surface characteristics. Mid-range accessible pricing in Spanish and Italian secondary markets drives volume scaling. Fastest share gains among price-sensitive entry buyers.
- Canvas:Woven cotton-polyester blends with printed monogram patterns. Coated variants require specialized condition assessment.
- Cotton:Natural fiber constructions with higher degradation susceptibility. Limited authenticated resale presence outside casual tier platforms.
Leather commands highest unit economics. Synthetic materials climb fastest in transaction count.
Brand:
Customer type stratification separates investment-grade collectors from aspiration-driven first-time buyers across heritage house recognition tiers.
- Chanel:Quilted leather constructions with chain-link hardware and interlocking CC motifs. Tokyo and Seoul auction channels sustain price floor stability through Asian collector density. Authentication labor intensity peaks with hardware serialization verification.
- Louis Vuitton:Coated canvas monogram patterns with leather trim constructions. French domestic resale platforms leverage proximity to Paris headquarters for documentation access. Steepest volume trajectory among entry-luxury demographics.
- Gucci:Italian leather goods with web stripe and bamboo hardware signatures. Milan-based consignment specialists dominate European trade flows.
- Prada:Nylon and Saffiano leather constructions with triangular plaque hardware. German market penetration lags other heritage houses.
Chanel leads in price per unit. Louis Vuitton posts the steepest expansion trajectory in transaction volume.
Price Tier:
Margin structure maturity separates established authentication infrastructure from emerging platform opportunities.
- Luxury:Four-figure price points with archival documentation and original packaging requirements. Vestiaire Collective and The RealReal capture this tier through captive authentication facilities. Supply concentration in French and Italian primary markets.
- Mid-range:Accessible heritage and contemporary designer access. Algorithmic pricing transparency builds velocity here.
- Affordable:Sub-three-hundred price points with streamlined condition grading. Volume scales through automated computer vision assessment.
- Discounted:Damaged or incomplete provenance inventory with significant price reductions. Liquidation channels absorb this tier.
Luxury tier generates highest authentication fees. Mid-range pricing is gaining share fastest among platform revenue mixes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import asymmetries in authenticated luxury accessories concentrate trade flows through specific national corridors. France maintains structural surplus in pre-owned leather goods re-export, while the United States absorbs net imports through platform-mediated cross-border transactions.
France
Paris and Lyon anchor European authentication infrastructure through heritage atelier proximity. The DGCCRF enforces serialized traceability documentation that elevates compliance costs for cross-border entrants. Vestiaire Collective's captive documentation systems in Île-de-France create regulatory moats that smaller platforms cannot replicate.
United States
Millennial and Gen Z buyers in New York and Los Angeles drive mobile-first consignment adoption. The FTC's Green Guides scrutinize environmental marketing claims, demanding legal infrastructure investments from resale platforms. The RealReal operates proprietary authentication facilities across eleven physical locations concentrated in coastal metropolitan corridors.
China
Shanghai and Beijing collectors sustain price floor stability for heritage house archival pieces. SAMR's anti-counterfeiting enforcement intensifies documentation requirements for cross-border luxury resale. Domestic platforms leverage proximity to Hong Kong auction channels for authentication expertise transfer.
Japan
Tokyo's auction density supports investment-grade collector liquidity for quilted leather constructions. METI's consumer protection frameworks mandate condition disclosure standards that exceed regional baselines. Osaka-based consignment specialists dominate domestic trade flows for Italian heritage brands.
Germany
Berlin and Amsterdam corridor buyers prioritize durability-focused backpack formats for urban commuting. The KBA's product safety oversight extends to imported pre-owned accessories through customs classification scrutiny. Munich-based platforms lag in Gucci penetration relative to other European markets.
Second Hand Bag Market Competitive Environment
Concentration sits with capital-intensive authentication platforms that have built proprietary physical infrastructure. The competitive hierarchy compresses as lean marketplaces deploy algorithmic pricing and computer vision grading to reduce specialist labor bottlenecks. Two archetypes dominate: facility-heavy consignment specialists and technology-enabled direct-purchase operators. M&A activity targets authentication talent pipelines, while strategic partnerships with heritage houses secure documentation access.
Within the facility-heavy tier, The RealReal and Vestiaire Collective exemplify capital-intensive authentication models with captive physical networks. Fashionphile occupies a position representing consignment-based inventory approaches that minimize working-capital intensity. Rebag anchors the algorithmic-pricing archetype through direct-purchase guarantee structures that accelerate inventory velocity.
| Leading Market Players |
|---|
| The RealReal |
| Fashionphile |
| Rebag |
| Farfetch |
| Vestiaire Collective |
| The 1916 Company |
| Alex Cooper Auctioneers |
| Poshmark |
| ThredUp |
| Others |
Value Chain & Pricing Dynamics
Synthetic material substitution in mid-range tiers simultaneously redraws supply geography toward Asian manufacturing clusters and compresses pricing premiums that leather constructions historically commanded in authenticated resale channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels in the second hand bag market. Price differentiation hinges on authentication grade and brand heritage documentation, with luxury tiers commanding substantial premiums for serialized provenance chains. Cost compression in synthetic-accessible segments intensifies as automated computer vision grading reduces specialist labor overhead. Entry-level buyers exhibit highest price sensitivity, while investment-grade collectors demonstrate inelastic demand for archival-condition heritage pieces.
Supply Chain Analysis
Just-in-time inventory preferences dominate consignment-based platforms, whereas direct-purchase guarantee operators maintain strategic stockpiles to accelerate fulfillment velocity. Supply concentrates in France, Italy, and China, with Paris and Lyon anchoring European authentication infrastructure. Raw material dependencies center on tanned hides, coated canvas, and hardware components from specialized ateliers. Single-source vulnerability in expert authenticator talent pools threatens platform scaling. Distribution runs through captive platform marketplaces and cross-border digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against synthetic-material substitution eroding leather-premium pricing power while algorithmic pricing transparency commoditizes traditional consignment delays.
For Market Incumbents: Fortify authentication infrastructure through captive documentation systems that satisfy DGCCRF traceability mandates, creating compliance moats smaller entrants cannot replicate. Expand proprietary physical facility networks in Paris and Lyon to anchor European trade volumes. Vertical integration into algorithmic pricing engines defends margin position against technology-enabled challengers. For New Entrants and Emerging Players: Differentiate on direct-purchase guarantee models that eliminate consignment friction and accelerate inventory velocity. Target the clutch segment's underexploited price-to-weight ratio advantages in compact luxury formats. Deploy computer vision grading to reduce authentication labor bottlenecks and compress capital barriers to entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with established regulatory compliance infrastructure and captive authentication talent pipelines. Long-term viability rests on documentation system investments that outlast cyclical fashion preferences. Acquisition candidates should demonstrate algorithmic pricing capabilities and French regulatory anchoring. Watch authentication talent scarcity as the inflection indicator for platform economics deterioration.| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Infrastructure Expansion | Proprietary physical facilities in Paris and Lyon satisfy DGCCRF documentation mandates. |
| Algorithmic Pricing Engine Development | Clair-type transparency engines build consumer trust and accelerate inventory turns. |
| Direct-Purchase Guarantee Launch | Eliminates consignment delays that frustrate millennial and Gen Z liquidity preferences. |
| Computer Vision Grading Deployment | Reduces specialist labor bottlenecks in mid-range synthetic material assessment. |
| French Regulatory Compliance Investment | Serialized traceability systems create defensible moats against cross-border entrants. |
Study Parameters
Cross-validation between platform transaction data and heritage house documentation records anchors the qualitative findings. Primary interviews with authentication specialists, consignment platform executives, luxury brand archivists, and circular economy compliance officers combine with secondary validation from customs trade records, EU regulatory filings, and platform financial disclosures. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across material substitution scenarios and authentication automation adoption curves shapes the projection framework. The analysis models product type, material grade, brand tier, and price segment dimensions across the projection horizon. CAGRs derive from trend extrapolation adjusted for regulatory mandate impacts and generational purchasing behavior shifts. Authentication labor cost trajectories and synthetic material penetration curves constitute key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated authentication automation diffusion would require recalibration. Forecasts reflect assumptions about documentation standardization and cross-border customs classification stability. Revision becomes warranted when authentication talent scarcity crosses thresholds that stall platform scaling economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Travel Bag Market
Luggage
Laptop Messenger Bags Market
Luggage
Sewing Bags Market
Luggage
Bags Market
Luggage
Travel and Business Bags Market
Luggage
Global Premium Luggage Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Trunks Market
Luggage
Kids Backpack Market
Luggage
Smart Bags Market
Luggage
Backpack Market
Luggage
Global Luggage Market
Luggage
Camera Bag Market
Luggage
Sports Luggage Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Trolley Bags Market