
 Travel and Business Bags Market | 2026-2036
Travel and Business Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Travel and Business Bags Market Outlook
The EU Green Deal is expanding compliance obligations across luggage supply chains, forcing reformulation of synthetic components and traceability of leather sourcing. Samsonite International S.A. leverages its vertically integrated manufacturing base to absorb these compliance costs without margin erosion. Delsey S.A. competes through recycled polyester integration across its core suitcase lines. VIP Industries Limited anchors its position in price-accessible segments across South Asian distribution networks.
Travel and business bags encompass wheeled luggage, handheld carriers, and wearable transport systems engineered from woven synthetics, tanned hides, or laminated composites, typically featuring reinforced seams, telescopic handles, and compartmentalized interiors designed for garment protection and mobility efficiency. The primary purpose centers on secure, organized transit of personal and professional goods across multimodal transportation networks. Backpacks now dominate volume in commuter-adjacent segments where lightweight nylon constructions meet daily corporate mobility needs. Leather briefcases retain premium margin pools among senior executive buyers despite slower volume expansion. Wheeled suitcases sustain replacement-cycle revenue as airlines tighten cabin-baggage dimension rules and travelers prioritize compliance-ready dimensions.
REACH regulates chemical content in European-sourced textiles and hardware, while the EU Green Deal mandates recycled content minimums and extended producer responsibility frameworks that reshape cost structures for polyester and nylon-intensive product lines. The US EPA oversees volatile organic compound emissions from adhesive and coating processes in domestic assembly facilities, adding compliance layers for brands maintaining North American production. Stakeholders must monitor evolving border-adjustment mechanisms and material-certification requirements that will determine which suppliers retain market access without price repositioning.
Market Dynamics
Hybrid work patterns are fragmenting travel frequency into shorter, more frequent trips that demand lighter, modular luggage systems rather than traditional checked baggage formats.
Growth Catalysts
- EU Green Deal recycled-content mandates:Minimum recycled polyester thresholds in hard-shell luggage are accelerating supplier certification programs and opening premium positioning for compliant brands.
- China domestic business travel normalization:Post-pandemic corporate mobility in tier-one cities is driving replacement cycles for wheeled carry-on systems among frequent domestic flyers.
- Lightweight nylon composite advances:Cross-weave ballistic fabrics with integrated RFID shielding are penetrating commuter backpack segments previously dominated by heavier canvas constructions.
Market Restraints
- Petrochemical input volatility:Crude-derived polyester and nylon resin pricing swings compress margin predictability for synthetic-intensive product lines.
- Tannery supply concentration:Premium leather sourcing clusters in Northern Italy and select Indian clusters create bottleneck risk for full-grain briefcase manufacturers.
- REACH compliance cost layering:ECHA chemical registration requirements for hardware coatings and textile treatments add fixed overhead to European distribution models.
Strategic Opportunities
- India price-accessible segment depth:Underpenetrated organized retail channels in secondary cities offer volume expansion for polycarbonate hard-shell entrants.
- Airline cabin-baggage rule harmonization:Carriers tightening dimensional limits create replacement demand for compliance-optimized luggage formats.
- Repair-service subscription models:Extended producer responsibility frameworks under EU Green Deal enable recurring revenue streams through refurbishment networks.
Industry Challenges
- Traceability system integration:Blockchain-linked material provenance platforms require capital deployment and supplier onboarding coordination.
- Multi-standard certification timelines:Simultaneous BIS, REACH, and FAA testing protocols for smart luggage electronics extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel and Business Bags Market |
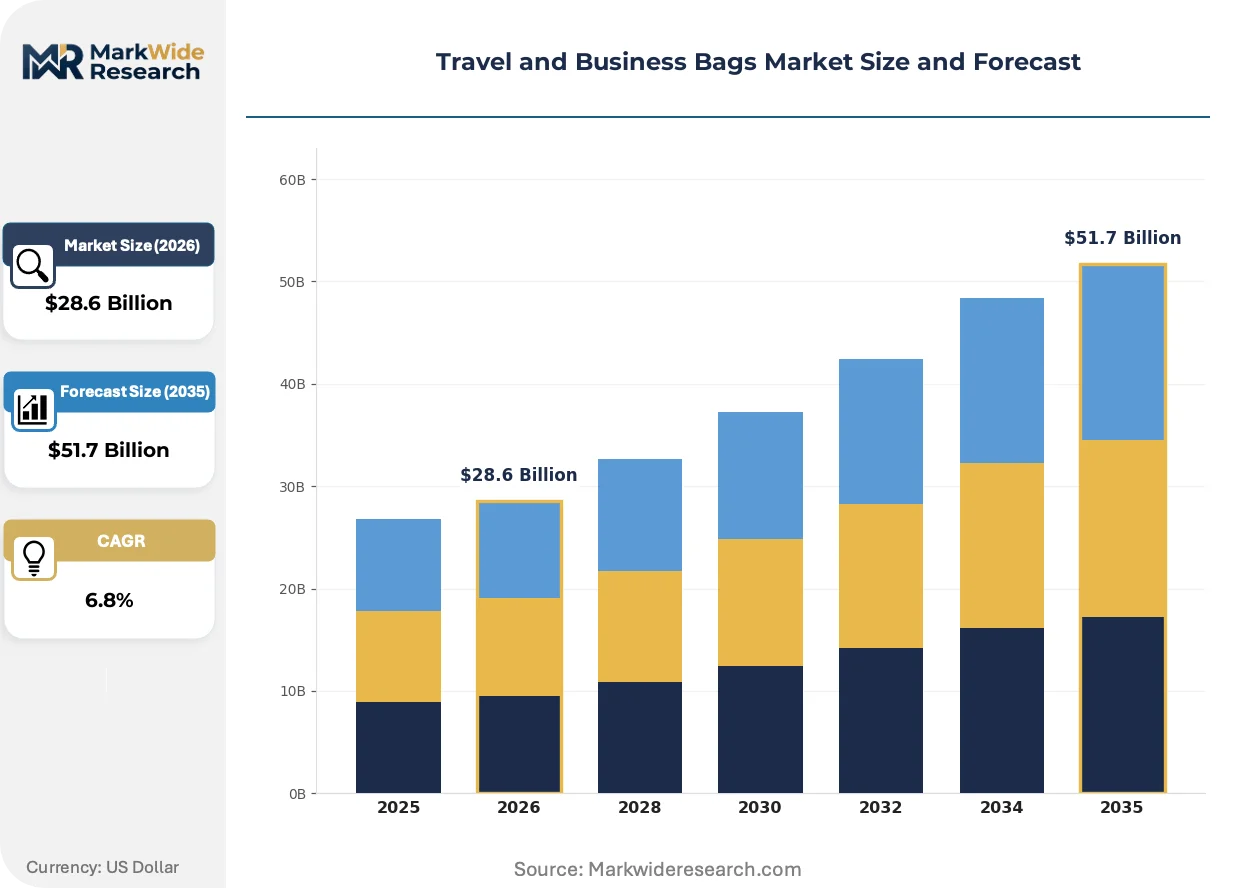
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Totes, Briefcases, Suitcases Material: Leather, Polyester, Nylon, Canvas Feature: Water Resistant, Lightweight, Expandable, Wheeled End User: Corporate Professionals, Travelers, Students, Tourists |
| Companies Covered | Samsonite International S.A., Delsey S.A., Briggs & Riley Travelware LLC, Tumi Holdings, Inc., VIP Industries Limited, Rimowa, Victorinox AG, Thule Group, Hermes International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel and Business Bags Market Strategic Shifts
Material science breakthroughs and regulatory pressure on circularity are converging to redefine product architecture and end-of-life accountability across luggage categories.
Recycled ocean-bound polyethylene terephthalate is overtaking virgin polyester in hard-shell suitcase production. Premium brands are adopting this feedstock for entire product lines. The shift is compressing virgin resin offtake and forcing petrochemical suppliers to renegotiate volume commitments with molded-shell manufacturers.
REACH substance restriction updates are tightening limits on chromium VI in leather tanning auxiliaries. ECHA enforcement is redirecting tannery procurement toward vegetable-tanning alternatives. Italian and Spanish leather-goods manufacturers are absorbing reformulation costs and passing selective premiums to executive briefcase buyers.
Direct-to-consumer channel expansion is displacing wholesale dependency among mid-tier luggage brands. Owned e-commerce platforms with virtual fit visualization are capturing urban professional segments. This pattern is most visible in Germany and the Netherlands where digital-native buyers prioritize configuration flexibility over in-store tactile evaluation.
Travel and Business Bags Market Segmentation
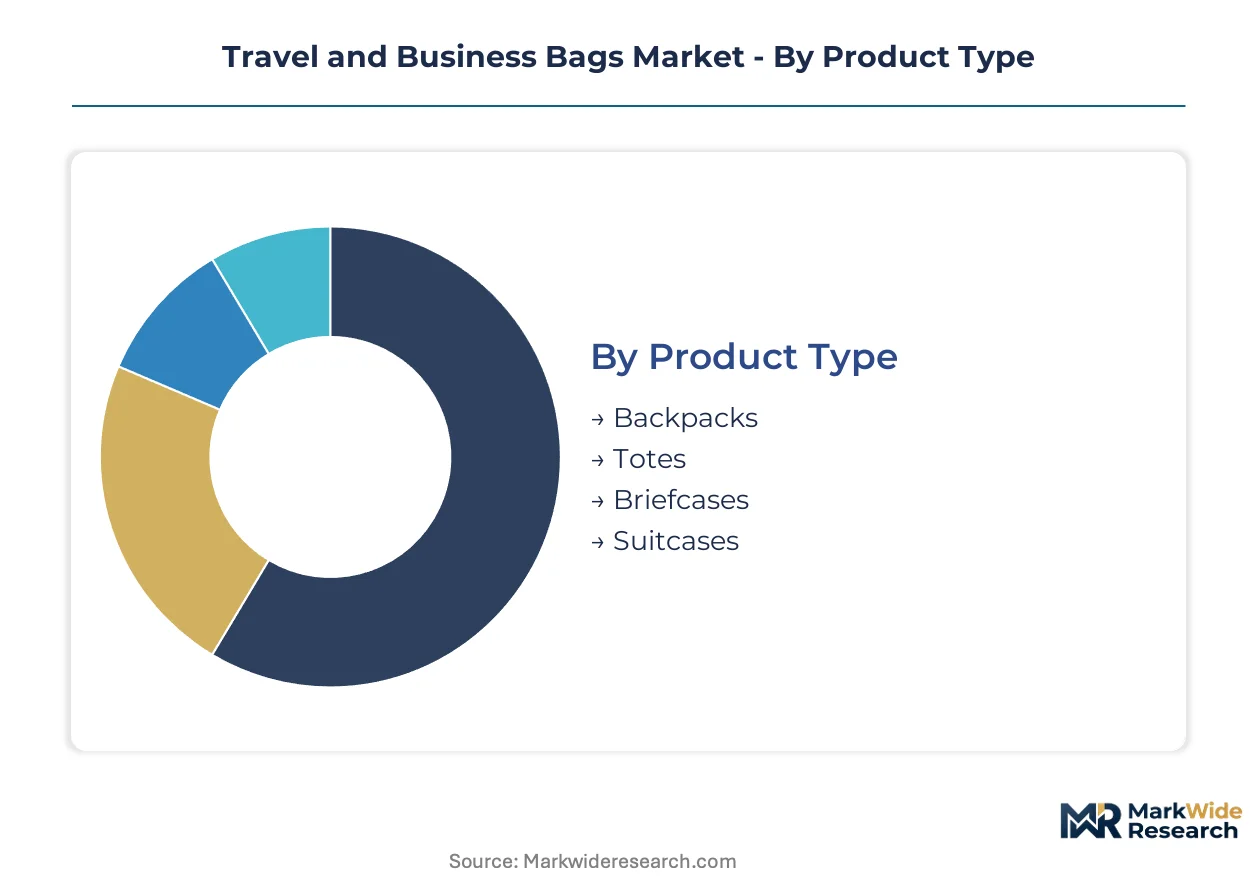
Product architecture in travel and business bags splits between standalone mobility systems and integrated transport solutions. Material sourcing and feature engineering create distinct margin tiers that reshape competitive positioning across distribution channels.
Product Type:
Standalone portable systems dominate commuter workflows while embedded organizational features penetrate premium corporate procurement.
- Backpacks:Cross-weave nylon constructions with padded laptop compartments and ergonomic harness systems. Demand concentrates among corporate professionals in Shanghai and Shenzhen hybrid work environments where daily multimodal commuting drives lightweight modular requirements.
- Suitcases:Molded polycarbonate or ABS hard-shell structures with telescopic handles and spinner wheel arrays. Frequent domestic flyers across China's tier-one cities prioritize compliance-optimized dimensions as airlines tighten cabin-baggage enforcement.
- Briefcases:Structured leather or synthetic portfolios with document organizers and tablet sleeves. Senior executive buyers in Frankfurt and Milan sustain premium positioning despite slower volume expansion.
- Totes:Unstructured open-top carriers in canvas or coated fabrics for short-duration personal transport. Urban professionals in Amsterdam and Copenhagen favor these for same-day business circuits.
Backpacks lead volumes today; suitcases are gaining share fastest.
Material:
Cost tier stratification separates petrochemical-derived synthetics from tanned hide supply chains with divergent compliance burdens.
- Polyester:Recycled polyethylene terephthalate feedstocks now displace virgin resin in hard-shell production. EU Green Deal recycled-content minimums accelerate supplier certification programs across molded-shell manufacturers.
- Leather:Full-grain and top-grain hides from Northern Italian and select Indian tannery clusters. REACH substance restrictions on chromium VI redirect procurement toward vegetable-tanning alternatives with selective premium pass-through.
- Nylon:Ballistic weave and ripstop constructions with water-repellent coatings. Lightweight composite advances penetrate commuter segments previously dominated by heavier canvas.
- Canvas:Cotton duck or waxed cotton fabrics in heritage-styled messenger bags and totes. Sustainability-conscious buyers in German direct-to-consumer channels drive modest residual demand.
Polyester dominates production scale; leather commands highest unit margins.
Feature:
Application-specific engineering separates air-travel-optimized formats from ground-mobility designs with distinct certification requirements.
- Wheeled:Four-spinner or two-wheel inline systems with reinforced chassis and corner guards. Replacement-cycle revenue sustains as carriers harmonize dimensional limits across domestic Chinese and European routes.
- Lightweight:Sub-2kg constructions using honeycomb framing and denier-reduced fabrics. Business travelers on short-haul European sectors prioritize these for cabin-baggage allowance optimization.
- Water Resistant:Coated zippers, seam-sealed construction, and hydrophobic fabric treatments. Commuter demand in rainy climates drives specification in backpack and briefcase categories.
- Expandable:Zippered gusset systems adding 15-25% volume capacity. Leisure travelers favor these for flexible return-trip loading on mixed-purpose journeys.
Wheeled configurations anchor revenue; lightweight engineering climbs the fastest.
End User:
Customer type determines volume scale versus margin capture with divergent replacement frequencies and brand loyalty patterns.
- Corporate Professionals:Hybrid work patterns fragment travel frequency into shorter, more frequent trips demanding modular luggage systems. Procurement concentrates in employer-subsidized programs and individual premium purchases.
- Travelers:Frequent flyers on business and leisure circuits with replacement cycles tied to airline rule changes and durability wear. This segment spans price-accessible through premium tiers.
- Students:Price-sensitive buyers prioritizing volume capacity and basic durability for educational migration and holiday travel. Distribution runs through mass retail and e-commerce platforms.
- Tourists:Occasional leisure travelers with destination-specific purchase behavior and souvenir-carry requirements. Seasonal demand spikes align with vacation periods in source markets.
Corporate professionals drive premium margins; travelers represent the broadest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leather goods manufacturing originated in Italian artisan clusters during the early twentieth century, with tanneries in Tuscany establishing quality benchmarks later adopted across European supply chains. This heritage concentration shaped premium positioning standards that persist in contemporary luggage markets.
China
Domestic business travel normalization in Shanghai, Beijing, and Shenzhen drives replacement cycles for wheeled carry-on systems among frequent flyers. The Ministry of Ecology and Environment enforces dual carbon goals that pressure molded-shell manufacturers toward recycled feedstock adoption. Manufacturing clusters in Guangdong and Zhejiang provinces scale polycarbonate hard-shell output for both domestic consumption and export markets.
United States
Hybrid work patterns fragment corporate travel into shorter, more frequent trips demanding modular luggage systems. The FAA maintains dimensional enforcement standards for smart luggage electronics that extend product certification timelines. Design and marketing functions concentrate in New York and Los Angeles while assembly operations span domestic facilities and Mexican maquiladora partnerships.
Germany
Direct-to-consumer channel expansion captures urban professional segments prioritizing configuration flexibility over tactile evaluation. ECHA administers REACH substance restrictions on hardware coatings and textile treatments that add compliance overhead. Industrial design expertise clusters in Munich and Hamburg, feeding premium engineering specifications across European distribution networks.
India
Price-accessible segment depth in secondary cities offers volume expansion for polycarbonate hard-shell entrants. BIS certification requirements for luggage durability standards create entry barriers for unorganized competitors. Manufacturing concentrates in Maharashtra and Gujarat where organized retail penetration remains underdeveloped relative to metropolitan centers.
Italy
Premium leather briefcase demand among senior executive buyers sustains margin pools despite slower volume expansion. EU Green Deal mandates redirect tannery procurement toward vegetable-tanning alternatives with selective premium pass-through. Artisan production persists in Florence and Milan while industrial-scale operations serve mid-tier European markets.
Travel and Business Bags Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered market positions. Vertically integrated manufacturers absorb compliance cost layering through captive material sourcing and in-house molding operations. Three archetypes dominate: heritage luxury houses commanding executive briefcase premiums, scale-driven hard-shell specialists optimizing recycled-content supply chains, and regional price-accessible players leveraging distributed retail networks. Competitive moves center on supplier certification programs for EU Green Deal alignment and direct-to-consumer platform investments displacing wholesale dependency.
Among heritage-positioned specialists, Samsonite International S.A. and Delsey S.A. exemplify divergent responses to regulatory pressure. Samsonite's integrated manufacturing base represents upstream control strategies for compliance cost absorption. Delsey's recycled polyester integration across core lines occupies a position between premium engineering and sustainability-marketed accessibility. VIP Industries Limited anchors the price-accessible archetype through South Asian distribution density. These three patterns illustrate how capital structure and geographic footprint determine strategic optionality under tightening material standards.
| Leading Market Players |
|---|
| Samsonite International S.A. |
| Delsey S.A. |
| Briggs & Riley Travelware LLC |
| Tumi Holdings, Inc. |
| VIP Industries Limited |
| Rimowa |
| Victorinox AG |
| Thule Group |
| Hermes International |
| Others |
Value Chain & Pricing Dynamics
Petrochemical resin costs cascade through three distinct pricing tiers as virgin polyester feedstock volatility compresses margin buffers for molded-shell manufacturers while recycled-content premiums command buyer willingness-to-pay in European corporate procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-grain leather briefcases with vegetable-tanning certification from polycarbonate hard-shell systems and price-accessible nylon backpacks. Price differentiation rests on REACH compliance tier and volume scale, with EU Green Deal-certified recycled polyester commanding selective premiums. Cost compression in standard-tier hard-shell luggage is intensifying because petrochemical input swings erode contract-margin predictability. Students and occasional tourists exhibit highest price sensitivity; senior executive buyers in Milan and Frankfurt demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-retail and wholesale distribution channels handle volume flows from Guangdong and Zhejiang manufacturing clusters to European and North American end-markets. Raw material sourcing draws from Northern Italian tanneries for premium leather, Saudi and Qatari petrochemical complexes for virgin polyester resin, and coastal Chinese recycling facilities for ocean-bound PET feedstock. Single-source vulnerability concentrates in chromium-free tanning auxiliaries as REACH substance restrictions redirect procurement. Distribution runs through organized retail networks in India and owned e-commerce platforms in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The travel and business bags market functions as a regulatory compounder where EU Green Deal recycled-content mandates and extended producer responsibility frameworks create sustained demand for compliance-ready supply chains.
For Market Incumbents: Extend certification coverage across supplier tiers to preempt REACH substance restriction updates and absorb reformulation costs through backward integration into captive tannery partnerships. Consolidate repair-service networks under subscription models to capture recurring revenue streams mandated by EU extended producer responsibility frameworks. Channel control through direct-to-consumer platform investments displaces wholesale dependency among digital-native urban professionals. For New Entrants and Emerging Players: Begin with price-accessible polycarbonate hard-shell positioning in Indian secondary cities where organized retail penetration remains underdeveloped and BIS certification creates defendable barriers against unorganized competitors. Target employer-subsidized corporate procurement programs in Chinese tier-one cities with lightweight modular systems optimized for hybrid work travel patterns. Go-to-market leverage rests on virtual fit visualization and configuration flexibility over tactile retail evaluation. For Investors and Strategic Acquirers: Roll-up economics work for regional price-accessible specialists with distributed South Asian retail networks because compliance cost layering under EU Green Deal and REACH frameworks disadvantages sub-scale competitors lacking certification infrastructure. Long-term viability favors acquisition targets with in-house molding capabilities and recycled feedstock supplier relationships. The signal to watch is airline cabin-baggage rule harmonization frequency as a replacement-cycle demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Supply Chain Certification | EU Green Deal compliance unlocks premium positioning in German and Dutch direct-to-consumer channels. |
| Repair-Service Subscription Launch | Extended producer responsibility frameworks enable recurring revenue capture through refurbishment networks. |
| Lightweight Nylon Composite R&D Investment | Cross-weave ballistic fabrics with RFID shielding penetrate commuter segments in Shanghai and Shenzhen. |
| Direct-to-Consumer Platform Expansion | Owned e-commerce with virtual fit visualization displaces wholesale dependency among urban professionals. |
| Vegetable-Tanning Supplier Partnership | REACH chromium VI restrictions redirect tannery procurement toward premium leather alternatives. |
Study Parameters
Coverage spans China, India, Germany, Italy, and the United States, with primary inputs from each market combining executive interviews with brand managers, category buyers at organized retailers, supply planners at molded-shell manufacturers, and channel sales heads alongside secondary validation from customs records, SEC filings, and EU ECHA regulatory databases. Bottom-up demand modeling triangulates against top-down production capacity assessments across Guangdong and Zhejiang clusters.
Rate-of-change decomposition separates volume growth from mix-shift effects across product type, material grade, feature configuration, and end-user archetype throughout the forecast period. CAGRs derive from segment-level demand elasticity modeling against airline rule changes, petrochemical price indices, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate domestic business travel normalization patterns in Chinese tier-one cities and REACH substance restriction implementation timelines.
Several conditions sit outside the modeled scope, including geopolitical trade barrier escalation, abrupt airline industry consolidation affecting baggage policy harmonization, and breakthrough material science displacing incumbent synthetic and leather constructions. Forecasts reflect documented assumptions about regulatory enforcement consistency and recycled feedstock availability scaling. Periodic stress-testing of base assumptions is recommended against petrochemical volatility spikes and tannery supply concentration disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Backpack Market
Luggage
Laptop Messenger Bags Market
Luggage
Global Premium Luggage Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Smart Bags Market
Luggage
Kids Backpack Market
Luggage
Trunks Market
Luggage
Travel Bag Market
Luggage
Sewing Bags Market
Luggage
Trolley Bags Market
Luggage
United States Sports Bags Market
Luggage
Camera Bag Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Laptop Carry Case Market
Luggage
Second Hand Bag Market
Luggage
Smart Carry-On Luggage Market