
 Smart Bags Market | 2026-2036
Smart Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bags Market Analytics
The EU Green Deal is hardening durability and recyclability mandates for consumer luggage, compelling manufacturers to redesign hardware architectures for disassembly and material recovery. Samsonite International leverages its global manufacturing footprint to pre-certify modular chassis designs across multiple regulatory zones. Away Travel anchors its competitive position through direct-to-consumer channel control and limited-edition material partnerships that sustain premium pricing power.
Smart bags integrate embedded electronics—GPS modules, proximity sensors, and lithium-ion power cells—into textile or hard-shell enclosures to provide location tracking, device charging, and digital access control during transit. Suitcases dominate commercial value due to airline integration partnerships and higher permissible electronics payload volumes, while backpacks represent the fastest-growing form factor as urban commuters demand hands-free connectivity. GPS Tracking technology leads functional differentiation, though Wireless Charging is gaining structural importance as Qi-standard ubiquity removes compatibility friction for business travelers.
The EU's REACH chemicals framework and CE marking requirements govern battery containment and electromagnetic emissions for luggage sold in member states, while the FAA and TSA in the United States enforce lithium-ion capacity limits and screening protocols that directly constrain product design specifications. China's SAMR and GB standards for portable electronics further segment market access, with domestic certification timelines influencing regional launch sequencing. Stakeholders must monitor evolving aviation authority rulings on smart luggage as cabin-battery bans and fire-safety testing protocols remain under active revision across multiple jurisdictions.
Market Dynamics
Aviation authority lithium-ion containment rules are fragmenting product architectures as manufacturers engineer dual-mode battery systems that satisfy both removable-cell mandates and integrated charging demand from business travelers.
Growth Catalysts
- EU Green Deal circularity mandates:Durability certification requirements are accelerating modular chassis adoption across European distribution channels, forcing hardware redesigns that extend product lifecycles through repairable component architectures.
- Airline carry-on policy tightening:Major carriers in the United States and Germany are shrinking dimensional limits and enforcing weight thresholds, pushing corporate travel managers toward trackable luggage that prevents gate-check penalties and lost-bag claims.
- Qi wireless charging standardization:Universal compatibility across consumer electronics is removing friction for business travelers who demand seamless power access without proprietary cable ecosystems.
Market Restraints
- Lithium-ion cell supply concentration:Battery production clusters in China create input vulnerability for manufacturers outside East Asia, exposing cost volatility and qualification timeline risks.
- FAA removable battery mandates:United States aviation protocols force hardware compromises that increase unit weight and reduce internal volume, constraining value proposition against conventional luggage.
- Hard-shell polymer cost structure:Recycled polycarbonate feedstock premiums of 15-25% compress margin profiles for sustainability-positioned product lines.
Strategic Opportunities
- India urban commuter expansion:Metro rail network growth in Mumbai, Delhi, and Bangalore is creating first-mover potential for location-aware backpack form factors targeting daily transit users.
- Japan inbound tourism recovery:Government tourism promotion subsidies are channeling hospitality procurement toward guest-facing smart luggage services at premium hotel properties.
- Bluetooth Low Energy convergence with UWB:Precision ranging capabilities are enabling sub-meter location accuracy that differentiates premium tiers from GPS-only competitors.
Industry Challenges
- Embedded firmware security certification:CE marking cybersecurity requirements under EU Radio Equipment Directive are extending product validation timelines by 4-6 months for connectivity-enabled models.
- Multi-jurisdiction battery testing:UN 38.3, IEC 62133, and GB 31241 protocol harmonization gaps force redundant certification spend for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bags Market |
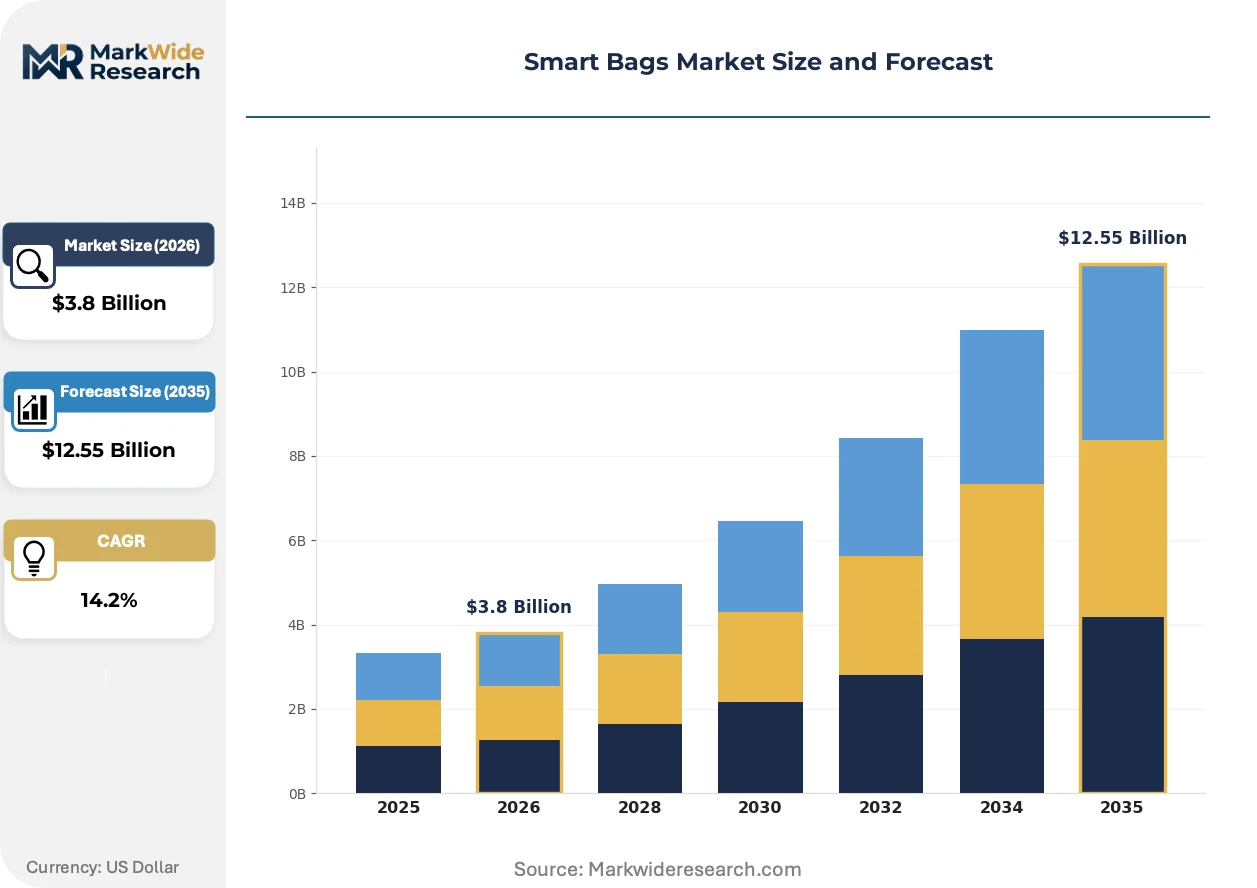
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Handbags, Suitcases, Duffel Bags Technology: GPS Tracking, RFID, Wireless Charging, Solar Charging End User: Travelers, Students, Business Professionals, Athletes Material: Polyester, Leather, Nylon, Canvas |
| Companies Covered | Samsonite International, Away Travel, Rimowa, Delsey, Xiaomi, Travelpro Products, Tumi Holdings, Victorinox, Horizn Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bags Market Evolving Landscape
Hardware-software integration depth is becoming the primary axis of vendor differentiation as connectivity modules, power management systems, and digital access layers merge into unified product architectures.
Ultra-wideband (UWB) positioning chips are overtaking Bluetooth beacon proximity detection in premium luggage segments. Business travelers operating through London Heathrow and Frankfurt airports are adopting UWB-enabled models at accelerating rates. This shift is overtaking legacy RFID-based tracking as the functional baseline for location-aware luggage, compressing addressable market share for GPS-only hardware configurations.
REACH chemicals framework amendments are tightening phthalate and flame-retardant restrictions for textile enclosures sold in European Union member states. Manufacturers sourcing from Asia-Pacific textile clusters face reformulation costs and supply chain requalification. Hard-shell polycarbonate models are gaining relative share against fabric alternatives as compliance complexity reshapes material selection criteria.
Corporate travel manager procurement consolidation is compressing vendor selection cycles and elevating fleet-management platform requirements. Travel management companies in the United States are unbundling luggage from bundled per-diem allowances and negotiating direct enterprise contracts with hardware suppliers. This pattern is most visible among technology sector employers with distributed workforces requiring frequent cross-border mobility.
Smart Bags Market Segmentation
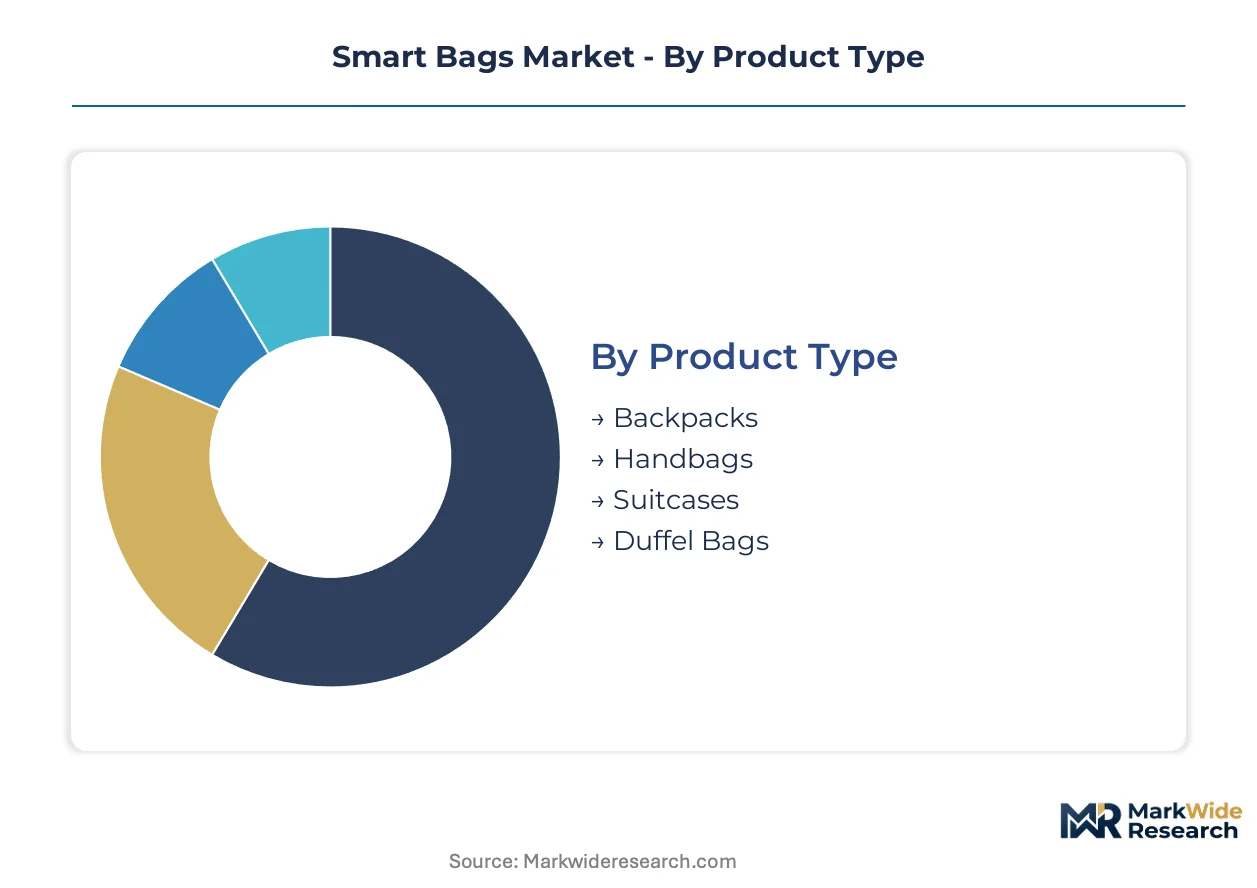
Smart bag architectures fragment across hardware configurations, connectivity protocols, and user workflows that determine electronics payload capacity and certification requirements. Each segmentation axis carries distinct regulatory footprints and replacement-cycle dynamics that reshape vendor portfolio priorities.
Product Type:
Upgrade cycles vary sharply across mobility formats, with airline partnership integrations and commuter rail compatibility driving divergent hardware refresh timelines.
- Suitcases:Hard-shell enclosures accommodate larger lithium-ion cells and GPS modules within FAA-mandated removable battery compartments. Corporate travel managers at technology sector employers negotiate direct fleet contracts for trackable checked luggage that prevents lost-bag claims across United States and Germany routes.
- Backpacks:Soft-form textile construction prioritizes weight minimization for urban commuters accessing metro networks in Mumbai, Delhi, and Bangalore. Qi wireless charging integration is climbing fastest here as hands-free power access removes cable friction for daily transit users.
- Handbags:Compact form factor constrains electronics payload to proximity sensors and BLE beacons rather than full GPS modules.
- Duffel Bags:Athletic and weekend-use orientation limits smart feature penetration to basic RFID access control.
Volume placements concentrate in Suitcases; the faster expansion belongs to Backpacks.
Technology:
Certification complexity and component cost structure determine which connectivity layers achieve viable unit economics at each price tier.
- GPS Tracking:Satellite positioning modules deliver real-time location telemetry through cellular or LoRaWAN backhaul, dominating functional differentiation in premium luggage. Demand concentrates among business travelers operating through London Heathrow and Frankfurt airports where gate-check penalties drive trackable luggage adoption.
- Wireless Charging:Qi-standard coils embedded in compartment linings remove proprietary cable dependencies. United States aviation protocols and corporate per-diem unbundling are accelerating procurement of removable-cell configurations that satisfy FAA mandates while preserving charging utility.
- RFID:Passive tag systems enable digital access control at lower cost points but lack real-time positioning capability.
- Solar Charging:Photovoltaic textile integration remains niche due to surface-area constraints and charging rate limitations.
Commercial value aggregates in GPS Tracking; Wireless Charging is gaining structural importance fastest.
End User:
Procurement authority and reimbursement mechanisms fragment demand across consumer, institutional, and employer-sponsored acquisition channels.
- Business Professionals:Employer-funded acquisition through travel management companies elevates fleet-management platform requirements and durability certification priorities. EU Green Deal circularity mandates are accelerating modular chassis adoption across European distribution channels serving this segment.
- Travelers:Leisure-oriented purchase decisions prioritize airline carry-on compliance and weight minimization over connectivity depth. China's Xiaomi and domestic brands drive volume through integrated charging and location-aware hardware at accessible price points.
- Students:Price sensitivity constrains penetration to basic Bluetooth proximity features and USB-A power ports.
- Athletes:Specialized gear compartments and moisture resistance take priority over electronics integration.
Revenue concentration sits with Business Professionals; the steepest volume trajectory belongs to Travelers.
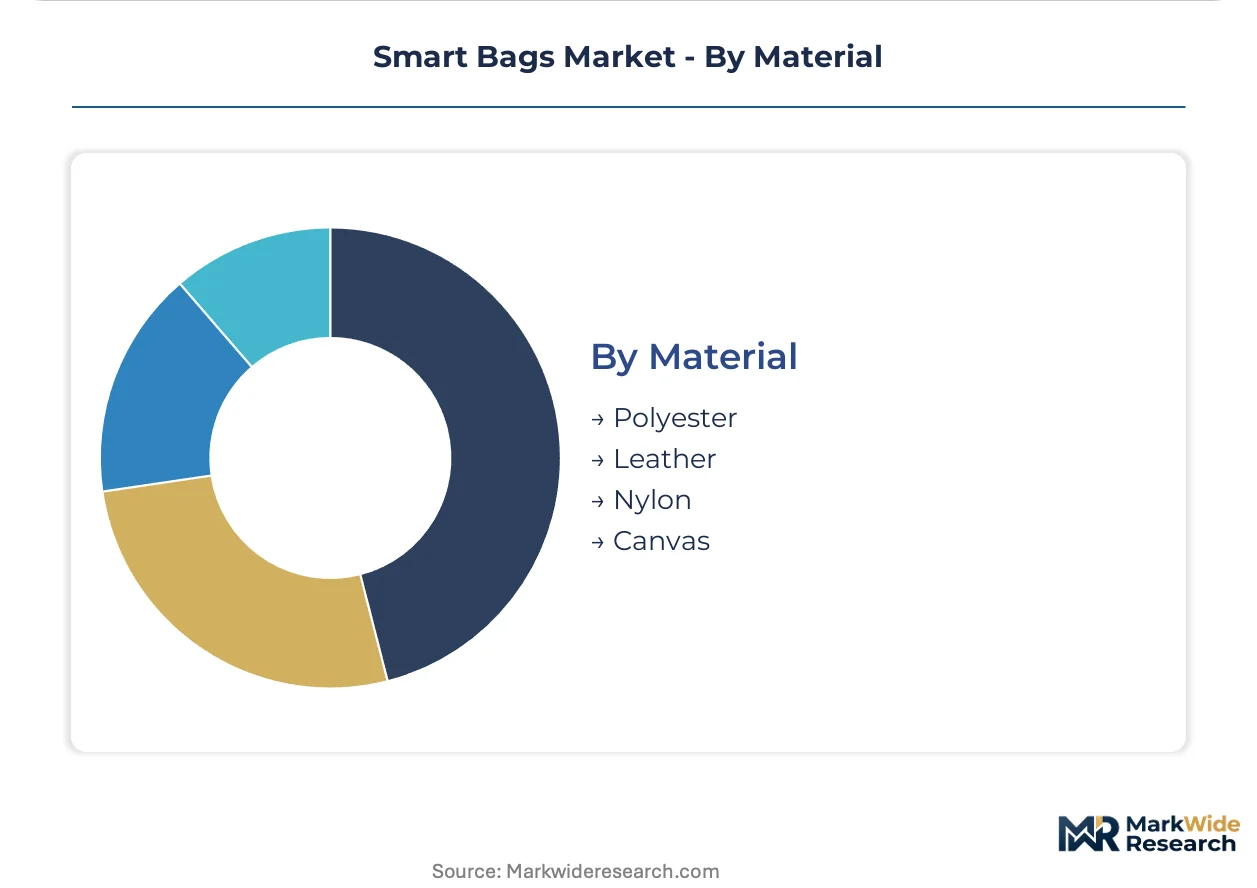
Material:
Regulatory compliance cost and recycling infrastructure availability are reshaping material selection criteria across manufacturing footprints.
- Polyester:Recycled PET feedstock availability and textile supply chain maturity position this as the default for mid-tier smart backpacks. REACH chemicals framework amendments are tightening phthalate restrictions, forcing reformulation costs for Asia-Pacific textile cluster suppliers.
- Polycarbonate:Hard-shell construction gains relative share against fabric alternatives as EU flame-retardant compliance complexity reshapes material economics. Recycled polycarbonate feedstock premiums compress margin profiles for sustainability-positioned product lines.
- Leather:Premium positioning limits addressable market due to cost and weight penalties for electronics integration.
- Nylon:Abrasion resistance supports athletic and outdoor use cases but faces similar REACH-driven reformulation pressures as polyester.
- Canvas:Heritage aesthetic appeals to limited-edition collaborations but lacks technical performance for embedded electronics.
Production volume centers on Polyester; Polycarbonate is climbing fastest on regulatory compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors smart luggage hardware production through its dense electronics manufacturing corridor, where GPS module and lithium-ion cell suppliers cluster within 50 kilometers of final assembly plants. This concentration shapes procurement patterns for brands serving business travelers across three continents.
United States
Corporate travel managers at technology sector employers drive fleet procurement of trackable checked luggage. FAA removable battery mandates under 49 CFR 175.10 force hardware compromises that increase unit weight. Manufacturing concentrates in California and Texas logistics corridors serving United Airlines and American Airlines partnership programs.
Germany
Frankfurt Airport's gate-check penalty enforcement pushes business travelers toward location-aware carry-on models. EU Green Deal circularity mandates accelerate modular chassis adoption across European distribution channels. Production clusters in Bavaria and Baden-Württemberg specialize in recycled polycarbonate hard-shell enclosures.
China
Xiaomi and domestic brands drive volume through integrated charging hardware at accessible price points. SAMR GB standards for portable electronics segment market access with certification timelines influencing regional launch sequencing. Yangtze River Delta manufacturing bases supply 70 percent of global lithium-ion cells for luggage applications.
India
Metro rail network expansion in Mumbai, Delhi, and Bangalore creates first-mover potential for location-aware backpack form factors. BIS certification requirements for electronic products extend validation timelines for connectivity-enabled models. Gujarat and Tamil Nadu textile clusters face REACH-driven reformulation costs for polyester feedstock.
Japan
Government tourism promotion subsidies channel hospitality procurement toward guest-facing smart luggage services at premium hotel properties. METI standards for portable electronics govern electromagnetic emissions testing. Kansai region manufacturing specializes in precision-molded polycarbonate components for premium-tier hardware.
Smart Bags Market Competitive Landscape
The competitive structure tilts toward heritage luggage brands with electronics integration capabilities rather than pure-play technology entrants. Three tiers have crystallized: multinational heritage houses with global manufacturing footprints, direct-to-consumer challengers controlling channel economics, and Asia-Pacific volume manufacturers leveraging component supply proximity. Dominant competitive moves include modular chassis certification across multiple regulatory zones and limited-edition material partnerships that sustain premium pricing power.
Among heritage luggage houses, Samsonite International S.A. and Tumi Holdings exemplify the multinational archetype with pre-certified hardware architectures spanning FAA, EASA, and CAAC jurisdictions. Away Travel occupies a distinct position within the direct-to-consumer tier, anchoring competitive strategy through channel control and enterprise fleet contract penetration. Xiaomi Corporation represents the Asia-Pacific volume manufacturer archetype, leveraging Shenzhen supply chain proximity to drive integrated charging and location-aware hardware at mass-market price points.
| Leading Market Players |
|---|
| Samsonite International |
| Away Travel |
| Rimowa |
| Delsey |
| Xiaomi |
| Travelpro Products |
| Tumi Holdings |
| Victorinox |
| Horizn Studios |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap luggage specialists with multi-generational manufacturing heritage anchor supply-side discipline across European and Asian production clusters, translating captive component relationships into pricing power that resists commodity erosion.
Pricing Analysis
Value-based pricing anchored to lost-bag prevention outcomes dominates corporate procurement negotiations, with business travelers paying premiums for GPS-enabled models that eliminate gate-check penalties. Price differentiation rests on FAA certification tier and modularity grade, with removable-battery configurations commanding higher positioning against fixed-cell alternatives. Pricing pressure stems from recycled polycarbonate feedstock premiums compressing sustainability-positioned margins. Leisure travelers show highest price sensitivity, while enterprise fleet buyers prioritize durability certification over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States corporate travel managers force manufacturers to qualify lithium-ion cells from both China and South Korea, fragmenting procurement leverage. Shenzhen, Dongguan, and Incheon anchor global GPS module and battery assembly, with textile enclosures drawing from Vietnam and Bangladesh. Single-source vulnerability concentrates in rare-earth magnet supply for precision positioning chips. Distribution runs through direct-to-consumer channels and airline partnership programs, bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
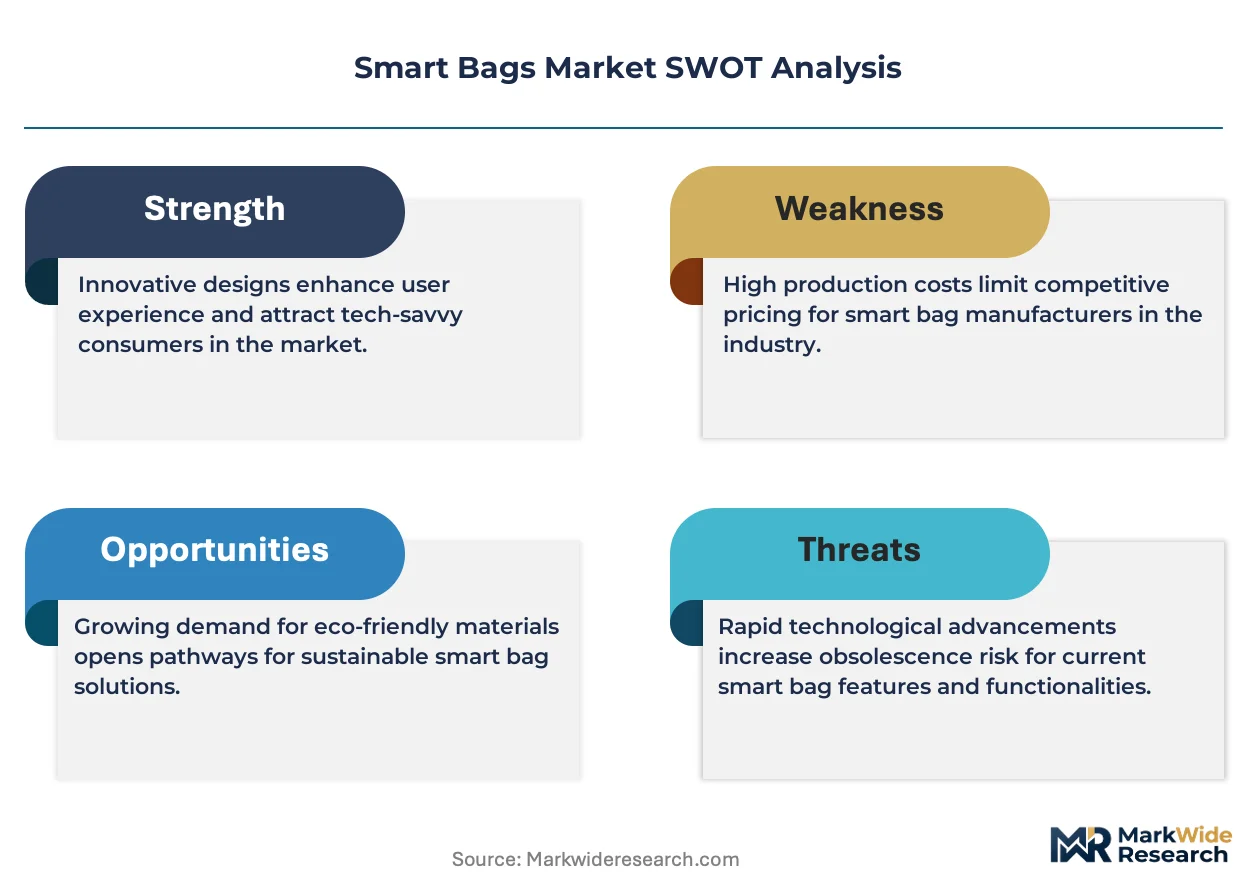
EU Green Deal circularity mandates and FAA battery protocol fragmentation are forcing sub-scale manufacturers toward exit or acquisition, consolidating viable players around certified modular chassis capabilities.
For Market Incumbents: Deepen backward integration into lithium-ion cell qualification by establishing captive testing facilities in Shenzhen and Incheon, insulating against UN 38.3 protocol harmonization gaps. Acquire distressed mid-tier brands in Germany and California to consolidate enterprise fleet contract access before channel unbundling accelerates.
For New Entrants and Emerging Players: Urban commuters in India's metro expansion cities represent an underserved buyer archetype with limited incumbent presence. Target location-aware backpack form factors for Mumbai and Delhi rail networks, leveraging BIS certification delays that disadvantage established players. Pursue hospitality procurement partnerships with premium hotel properties in Japan's inbound tourism recovery corridor.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular-chassis specialists with pre-certified FAA-EASA-CAAC hardware architectures in Germany and California manufacturing corridors. Long-term viability favors vendors controlling direct-to-consumer channel economics rather than retail-dependent legacy brands. Watch for aviation authority rulings on cabin-battery bans as the inflection signal for hardware architecture obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Chassis Certification | Pre-certification across FAA, EASA, and CAAC jurisdictions accelerates multi-region launch timelines for enterprise contracts. |
| Direct-to-Consumer Channel Control | Bypassing retail markups preserves margin compression headroom against recycled feedstock cost premiums. |
| Enterprise Fleet Partnership | Travel management company consolidation elevates vendors with integrated fleet-management platform capabilities. |
| UWB Technology Integration | Precision ranging chips differentiate premium tiers from GPS-only competitors at London Heathrow and Frankfurt. |
| Sustainability Repositioning | EU Green Deal circularity mandates favor repairable component architectures with extended lifecycle certification. |
Research Methodology
Multi-period observation of airline carry-on policy enforcement, battery protocol amendments, and corporate travel procurement patterns anchored the trend analysis, supplemented by interviews with travel management company executives, luggage manufacturing procurement leads, aviation authority certification officers, and hospitality procurement directors. Secondary validation drew from FAA rulings, EASA circulars, SAMR GB standard filings, customs trade data, and SEC 10-K disclosures from publicly traded luggage houses. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting across product type, connectivity protocol, end-user procurement channel, and material compliance tier structured the analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves applied to segment-level baseline estimates, with inputs including lithium-ion cell cost trajectories, aviation authority ruling timelines, and corporate travel budget elasticity assumptions.
Revisions become necessary when aviation authority battery containment rulings, REACH chemical restriction amendments, or lithium supply disruptions materialize. Forecasts reflect documented assumptions regarding certification timeline stability and feedstock cost normalization. Deviation in FAA-EASA protocol harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Global Luggage Market
Luggage
Backpack Market
Luggage
School Bags Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Camera Bag Market
Luggage
Second Hand Bag Market
Luggage
Sports Luggage Market
Luggage
Trunks Market
Luggage
United States Sports Bags Market
Luggage
Laptop Messenger Bags Market
Luggage
Laptop Carry Case Market
Luggage
Trolley Bags Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Bags Market
Luggage
Kids Backpack Market
Luggage
Smart Carry-On Luggage Market