
 Trunks Market | 2026-2036
Trunks Market Size, Share, and Industry Trends Forecast 2026-2036
Trunks Market Analytics
A capital-intensity divergence between polycarbonate molding specialists and hand-finished leather ateliers is bifurcating competitive returns in the trunks landscape. Samsonite International S.A. leverages global manufacturing scale across hard-shell polymer lines to sustain cost leadership. Rimowa GmbH anchors its position through aluminum monobloc engineering and direct retail channel control. Louis Vuitton Malletier differentiates via vertically integrated leatherwork and heritage atelier capacity in France.
Trunks are rigid or semi-rigid enclosed containers engineered for secure transport and storage, typically constructed from polycarbonate composites, anodized aluminum, vulcanized fiberboard, or treated canvas with reinforced corner hardware and locking mechanisms. Hard trunks dominate commercial volume due to airline compatibility standards and impact-resistance specifications, while travel trunks command premium positioning through integrated organization systems and TSA-compliant locking. Fabric-based soft trunks occupy a mature niche where weight minimization drives procurement decisions for overland and rail segments.
FCC guidelines govern embedded tracking and smart-lock electronics in US-bound products, while REACH and RoHS frameworks restrict phthalate and heavy-metal content across European imports. China's GB standards and SAMR quality certifications shape market access for foreign manufacturers supplying domestic e-commerce channels. Stakeholders must monitor evolving airline dimensional restrictions and biometric lock interoperability standards to align product roadmaps with institutional and retail buyer requirements.
Market Dynamics
REACH compliance in Europe and GB standards in China are compressing material substitution timelines, forcing polycarbonate suppliers and leather ateliers to requalify formulations ahead of procurement cycles.
Growth Catalysts
- Heritage Craftsmanship Premium:German trunk buyers sustain willingness-to-pay for hand-finished leatherwork and riveted corner construction, insulating domestic ateliers from polymer price volatility.
- Smart-Lock Mandates:FCC guidelines for embedded tracking electronics in US-bound luggage are pulling demand toward TSA-compliant biometric locking systems in hard-shell product lines.
- Hospitality Experience Programs:Luxury hotel chains in France and Italy are expanding trunk procurement for guest loyalty initiatives, creating institutional demand separate from retail channels.
Market Restraints
- Aluminum Input Concentration:Anodized aluminum sheet supply concentrates among German and Austrian smelters, exposing Rimowa-style monobloc producers to energy-cost pass-through volatility.
- Phthalate Substitution Friction:REACH restrictions on plasticizer content in polymer composites force reformulation cycles that extend 18-24 months, freezing supplier qualification pipelines.
- Fabric Trunk Erosion:Soft-sided luggage substitutes displace canvas-and-vulcanized-fiber trunks in overland travel segments where weight minimization dominates purchase criteria.
Strategic Opportunities
- Indian E-Commerce Penetration:Domestic platforms under BIS quality mandates are opening direct-to-consumer channels for mid-price polycarbonate imports previously excluded from formal retail.
- Carbon-Neutral Leather:EU Green Deal procurement incentives for verified low-carbon tanning processes create first-mover positioning for French ateliers with captive vegetable-tanning capacity.
- Rail-Travel Resurgence:European sleeper-train network expansion is reviving demand for compact hard trunks dimensioned to rack specifications outside airline cabin constraints.
Industry Challenges
- Atelier Skill Scarcity:Saddle-stitch leatherwork training pipelines in France and Italy have contracted 40% over two decades, constraining expansion of heritage-positioned production lines.
- Biometric Lock Interoperability:TSA certification timelines for fingerprint-enabled mechanisms lag hardware development by 12-18 months, forcing inventory carry of pre-certified mechanical alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trunks Market |
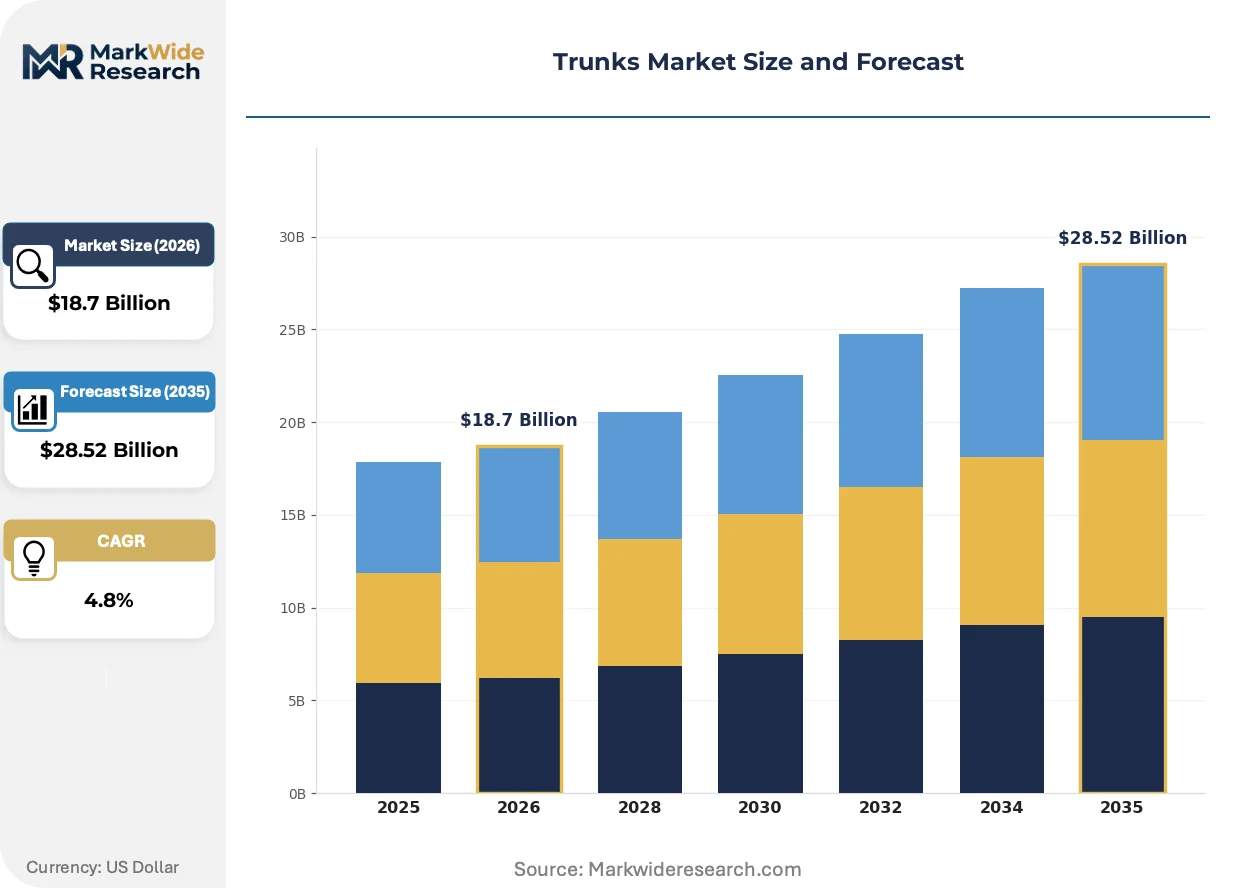
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Trunks, Soft Trunks, Travel Trunks, Storage Trunks Material: Wood, Plastic, Metal, Fabric Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Samsonite International S.A., Rimowa GmbH, Louis Vuitton Malletier, Tumi Holdings, Inc., Delsey SA, Victorinox AG, Briggs & Riley Travelware, Travelpro International, Inc, Globe-Trotter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trunks Market Evolving Landscape
Embedded sensor arrays and automated manufacturing cells are compressing development cycles while regulatory fragmentation across North America, Europe, and Asia-Pacific forces parallel compliance track investments.
Polycarbonate composite formulations with graphene infill are miniaturizing wall thickness requirements without sacrificing impact-resistance ratings. Airline procurement departments in Germany and the Netherlands are specifying these grades for crew luggage refresh programs. The technology is miniaturizing the weight-performance tradeoff that previously favored aluminum monobloc construction in premium segments.
RoHS frameworks restricting heavy-metal content in electroplated hardware are forcing nickel-free zamak alloy adoption across European import supply chains. Component suppliers in Guangdong province face 8-12 month requalification cycles under SAMR enforcement protocols. Hard-trunk manufacturers serving EU duty-free channels are absorbing 15-20% hardware cost premiums to maintain market access.
Direct-to-institutional contracting is displacing wholesale distributor networks for hospitality and corporate fleet buyers. Procurement teams at luxury hotel groups in Paris and Milan now negotiate trunk specifications directly with atelier workshops, bypassing traditional luggage importers. This channel compression is most visible in France, where heritage brands maintain captive retail and workshop capacity.
Trunks Market Segmentation
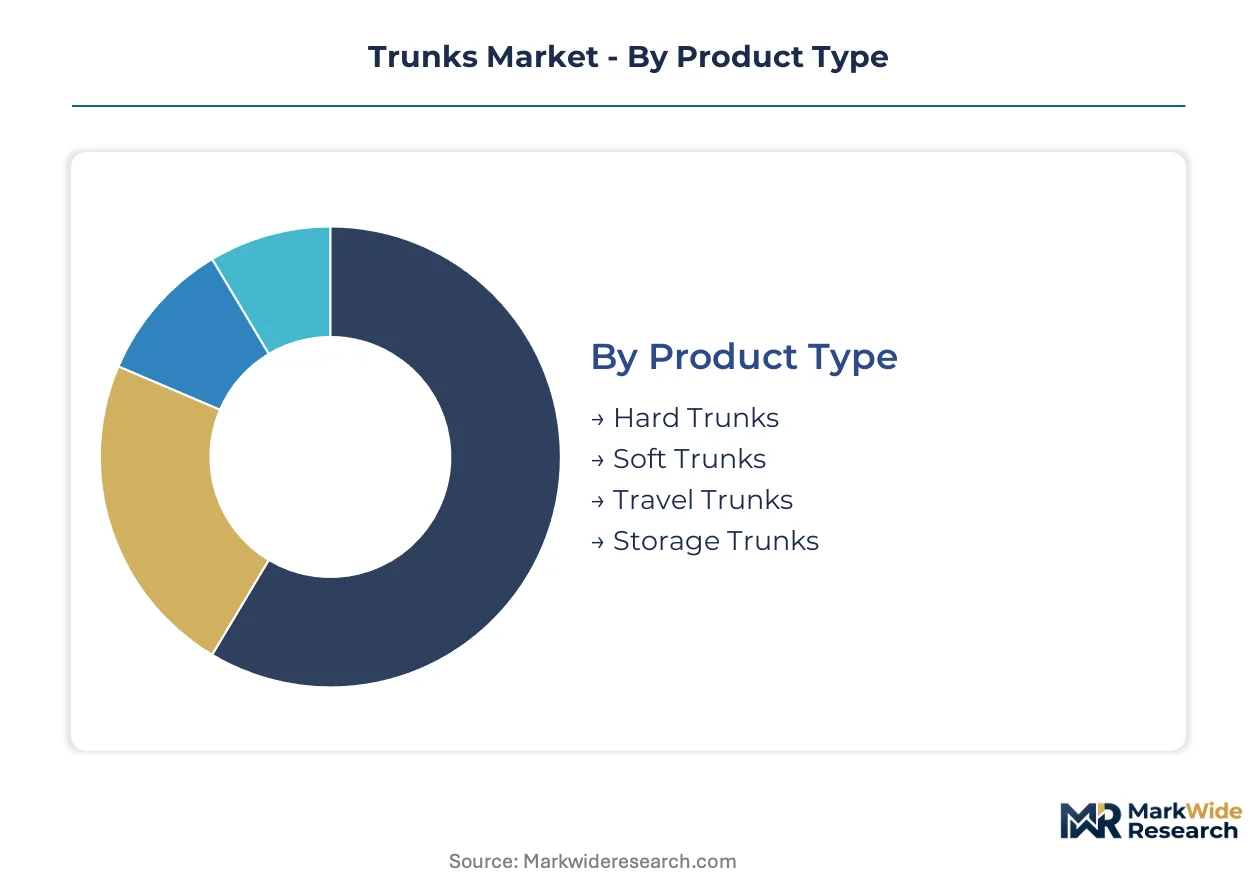
Trunk manufacturers navigate divergent compliance frameworks across product categories, with polycarbonate molding subject to REACH phthalate restrictions while leather ateliers face EU Green Deal tanning audits. Segmentation reveals how material and construction choices map to distinct regulatory pathways and procurement channels.
Product Type:
REACH compliance in Europe and GB standards in China compress material substitution timelines differently across construction formats, forcing polycarbonate suppliers and leather ateliers to requalify formulations ahead of procurement cycles.
- Hard Trunks:Rigid enclosures engineered from polycarbonate composites or anodized aluminum with reinforced corner hardware and TSA-compliant locking. Airline procurement departments in Germany and the Netherlands specify these for crew luggage refresh programs, though FCC guidelines for embedded tracking electronics extend development cycles.
- Travel Trunks:Premium-positioned products integrating organization systems, biometric locks, and compact dimensions optimized for airline cabin constraints. Luxury hotel chains in France and Italy negotiate specifications directly with atelier workshops for guest loyalty initiatives.
- Soft Trunks:Fabric-based constructions minimizing weight for overland and rail travel where dimensional flexibility outweighs impact resistance.
- Storage Trunks:Stationary containers prioritizing volume capacity and stackability for residential and commercial archival applications.
Established volume favors Hard Trunks; emerging adoption favors Travel Trunks.
Material:
Cost tier stratification separates heritage craftsmanship from polymer mass production, with energy-intensive aluminum monobloc construction commanding premium positioning against injection-molded alternatives.
- Plastic:Polycarbonate composite formulations with graphene infill miniaturize wall thickness without sacrificing impact-resistance ratings. Component suppliers in Guangdong province face 8-12 month requalification cycles under SAMR enforcement protocols for RoHS-compliant hardware integration.
- Metal:Anodized aluminum sheet supply concentrates among German and Austrian smelters, exposing monobloc producers to energy-cost pass-through volatility while delivering superior dent resistance for premium positioning.
- Wood:Heritage construction material for decorative and archival applications requiring climate-controlled environments.
- Fabric:Treated canvas and vulcanized fiberboard facing displacement by soft-sided luggage substitutes in weight-sensitive overland segments.
Margin concentration sits with Metal; volume scaling sits with Plastic.
Size:
Airline dimensional restrictions and rail-rack specifications fragment demand across dimensional tiers, with biometric lock miniaturization driving compact-format innovation.
- Small:Cabin-compatible dimensions optimized for biometric lock integration and overhead-bin compliance. TSA certification timelines for fingerprint-enabled mechanisms lag hardware development by 12-18 months.
- Medium:Checked-luggage formats balancing capacity against airline weight limits, representing the default procurement specification for corporate fleet buyers.
- Large:Extended-stay and relocation volumes where durability ratings outweigh portability constraints.
- Extra Large:Specialized dimensions for equipment transport and hospitality wardrobe programs requiring custom interior configurations.
Procurement frequency peaks at Medium; specification innovation concentrates at Small.
Distribution Channel:
Channel compression is displacing wholesale networks as institutional buyers bypass traditional importers for direct atelier contracting.
- Specialty Stores:Captive retail channels controlled by heritage brands in France, enabling direct customer relationships and atelier workshop access for customization services.
- Online Retail:Domestic platforms under BIS quality mandates in India are opening direct-to-consumer channels for mid-price polycarbonate imports previously excluded from formal retail.
- Department Stores:Declining footprint for luggage as category management shifts toward travel accessories with higher inventory turns.
- Wholesale:Traditional distributor networks losing share to direct-to-institutional contracting for hospitality and corporate fleet procurement.
Relationship control favors Specialty Stores; geographic expansion favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German heritage ateliers command sustained pricing premiums against Chinese polymer mass production, creating a bifurcated value architecture across procurement channels. REACH compliance timelines and airline dimensional standards fragment competitive positioning by geography.
Germany
Heritage craftsmanship procurement sustains premium positioning for hand-finished leatherwork and riveted corner construction. ECHA REACH restrictions on phthalate content force 18-24 month reformulation cycles among polycarbonate suppliers. The Bavarian and Baden-Württemberg industrial clusters concentrate aluminum monobloc engineering and direct retail channel control.
United States
FCC guidelines for embedded tracking electronics pull demand toward TSA-compliant biometric locking systems in hard-shell lines. FAA airline dimensional restrictions compress development cycles for cabin-compatible formats. Corporate fleet procurement in the Northeast Corridor and Pacific Northwest drives medium-format specifications for business travel segments.
China
GB standards and SAMR quality certifications shape market access for foreign manufacturers supplying domestic e-commerce channels. The Yangtze River Delta and Pearl River Delta clusters house component suppliers facing 8-12 month requalification cycles under RoHS enforcement protocols. Mid-price polycarbonate imports penetrate through BIS-mandated platforms previously excluded from formal retail.
France
Luxury hotel chains in Paris and Milan negotiate trunk specifications directly with atelier workshops, bypassing traditional luggage importers. EU Green Deal procurement incentives for verified low-carbon tanning processes create first-mover positioning for ateliers with captive vegetable-tanning capacity. The Île-de-France region maintains vertically integrated leatherwork and heritage atelier capacity.
India
Domestic platforms under BIS quality mandates open direct-to-consumer channels for mid-price polycarbonate imports. Maharashtra and Gujarat industrial corridors absorb hardware cost premiums to maintain EU duty-free channel access. Saddle-stitch leatherwork training pipeline contraction constrains expansion of heritage-positioned production lines.
Trunks Market Competitive Landscape
Concentration sits with polycarbonate molding specialists and aluminum monobloc engineers, while hand-finished leather ateliers occupy insulated premium niches. The vendor base stratifies across three archetypes: scale-driven polymer fabricators, heritage-positioned European workshops, and hospitality-direct contractors. M&A activity concentrates among polymer compounders seeking graphene infill capabilities, while capacity expansion focuses on biometric lock integration lines.
Within the heritage-positioned tier, Louis Vuitton Malletier and Rimowa GmbH exemplify divergent material strategies—captive French leatherwork versus German aluminum monobloc engineering. Samsonite International S.A. anchors the scale-driven polymer segment with global manufacturing footprints. These three structures illustrate how vertical integration depth, material specialization, and channel control separate competitive returns across price tiers.
| Leading Market Players |
|---|
| Samsonite International S.A. |
| Rimowa GmbH |
| Louis Vuitton Malletier |
| Tumi Holdings, Inc. |
| Delsey SA |
| Victorinox AG |
| Briggs & Riley Travelware |
| Travelpro International, Inc |
| Globe-Trotter |
| Others |
Value Network & Pricing Analysis
Scale-driven polycarbonate molding operations in Guangdong and Zhejiang provinces compress unit economics through automated cell deployment, anchoring price floors for injection-molded hard trunks while hand-finished leather ateliers in France and Germany defend premium positioning through captive workshop capacity and direct retail channel control.
Pricing Analysis
Configured-to-order pricing for heritage leather trunks with hand-stitched corners and custom interior fittings commands spreads exceeding three-to-one against standard polycarbonate cabin luggage. Three-tier pricing structure across premium, standard, and economy levels separates biometric-enabled travel trunks from basic hard-shell formats, with certification grade for TSA-compliant locking systems and REACH-compliant material sourcing driving differentiation. Price erosion runs through mid-price polycarbonate imports as BIS-mandated Indian e-commerce platforms expand direct-to-consumer penetration. Corporate fleet buyers exhibit lowest price sensitivity, prioritating durability ratings and warranty terms, while leisure travelers in emerging markets demonstrate highest elasticity to promotional discounting.
Supply Chain Analysis
Germany and Austria anchor anodized aluminum sheet production for monobloc trunk engineering, while China concentrates polycarbonate composite compounding and injection molding capacity across the Yangtze and Pearl River Delta clusters. Raw material dependencies center on bauxite-derived aluminum ingots, petroleum-based polycarbonate resins, and chromium-free tanning agents for vegetable-tanned leather. Single-source vulnerability concentrates in German-Austrian smelter networks exposed to energy-cost pass-through volatility. Distribution runs through direct-to-institutional contracting for hospitality and corporate fleet procurement, displacing traditional wholesale importer networks in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among luxury hotel procurement teams and corporate fleet managers, fragmenting traditional distributor networks as direct atelier contracting displaces wholesale channels in European institutional segments.
For Market Incumbents: Shield heritage positioning by deepening captive vegetable-tanning capacity and atelier workshop control against polymer price compression from Chinese scale producers. Defend margin structure through biometric lock certification pipelines and TSA-compliant hardware integration that extends replacement cycles. Prioritize direct retail channel investment in Paris and Milan to bypass eroding wholesale networks.
For New Entrants and Emerging Players: Lead with mid-price polycarbonate formats engineered to BIS quality mandates for Indian e-commerce platform penetration, where formal retail exclusion previously blocked market access. Target compact hard trunks dimensioned to European sleeper-train rack specifications outside airline cabin constraints. Pursue carbon-neutral leather positioning through verified low-carbon tanning process certification to capture EU Green Deal procurement incentives.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors graphene-infill polycarbonate compounders with hardware integration capabilities over pure-play leather ateliers facing skill scarcity constraints. Long-term viability rests on material science differentiation and biometric lock interoperability certification rather than brand heritage alone. Watch TSA certification timeline compression for fingerprint-enabled mechanisms as inflection signal for hardware-integrated product line viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Tanning | EU Green Deal procurement incentives reward verified low-carbon vegetable-tanning capacity in French ateliers. |
| Biometric Lock Certification Pipeline | TSA-compliant fingerprint-enabled mechanisms lag hardware development, creating first-mover certification advantages. |
| Direct-to-Institutional Channel Buildout | Luxury hotel procurement teams in Paris and Milan now negotiate specifications directly with atelier workshops. |
| Graphene-Infill Polycarbonate Scale-Up | German and Dutch airline procurement departments specify these grades for crew luggage refresh programs. |
| Rail-Travel Format Development | European sleeper-train network expansion revives demand for compact hard trunks outside airline dimensional constraints. |
Research Methodology
Desk research of customs trade records, airline procurement specifications, and REACH regulatory filings preceded structured interviews with polycarbonate molding specialists, leather atelier workshop managers, hospitality procurement directors, and component hardware suppliers across Germany, France, China, and India. Secondary validation drew from ECHA substance restriction databases, SAMR enforcement protocols, and FCC equipment authorization records. Bottom-up volume modeling triangulated against top-down value estimates derived from channel flow analysis.
Variance decomposition across product type, material grade, size tier, and distribution channel shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include construction format, material composition, dimensional category, and procurement channel archetype. CAGRs were derived from trend extrapolation calibrated to historical airline fleet refresh cycles and hospitality capital expenditure patterns. Industry-specific forecast inputs incorporated REACH reformulation timeline assumptions and biometric lock certification lag estimates.
The analysis sits within stated boundaries; outcomes outside sustained airline dimensional stability or accelerated REACH restriction expansion would require recalibration. Forecasts reflect documented assumptions regarding polycarbonate compounder capacity utilization and atelier skill pipeline contraction rates. Recalibration cycles align with material shifts in regulatory enforcement intensity and hospitality procurement centralization trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Kids Backpack Market
Luggage
Smart Carry-On Luggage Market
Luggage
Laptop Carry Case Market
Luggage
Bags Market
Luggage
School Bags Market
Luggage
Laptop Messenger Bags Market
Luggage
Camera Bag Market
Luggage
Second Hand Bag Market
Luggage
United States Sports Bags Market
Luggage
Smart Bags Market
Luggage
Sewing Bags Market
Luggage
Global Luggage Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Global Premium Luggage Market
Luggage
Trolley Bags Market
Luggage
Travel Bag Market