
 Global Premium Luggage Market | 2026-2036
Global Premium Luggage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Premium Luggage Market Outlook
Buyer concentration is fragmenting across aspirational luxury consumers and experience-driven tourists, which is repositioning volume toward entry-premium price bands. Samsonite leverages its multi-brand architecture to serve both heritage buyers and digital-native segments. Rimowa anchors its position through aluminum craftsmanship and monobloc polycarbonate engineering. Tumi differentiates via ballistic nylon durability and integrated USB charging systems.
Premium luggage comprises travel goods engineered from aerospace-grade polycarbonate, full-grain leather, or woven ballistic nylon, with structural specifications including TSA-approved locking mechanisms, multi-wheel spinner systems, and interior compression panels designed for garment protection during transit. Hard shell constructions dominate value pools due to superior durability perception and brand markup potential, while soft shell variants sustain growth through lightweight portability and expandability features favored by frequent business travelers. Distribution through duty-free shops captures margin-rich impulse purchases in aviation retail environments.
REACH regulations in Europe restrict phthalates and heavy metals in polymer formulations, compelling reformulation of polycarbonate blends across supply chains. The US Consumer Product Safety Commission monitors lead content in metal hardware and zipper components. California's Proposition 65 requires warning labels on products containing regulated chemicals, affecting leather tanning processes and coated fabrics. Stakeholders must monitor evolving chemical disclosure mandates and aviation weight restrictions that could redefine material selection criteria for next-generation product lines.
Market Dynamics
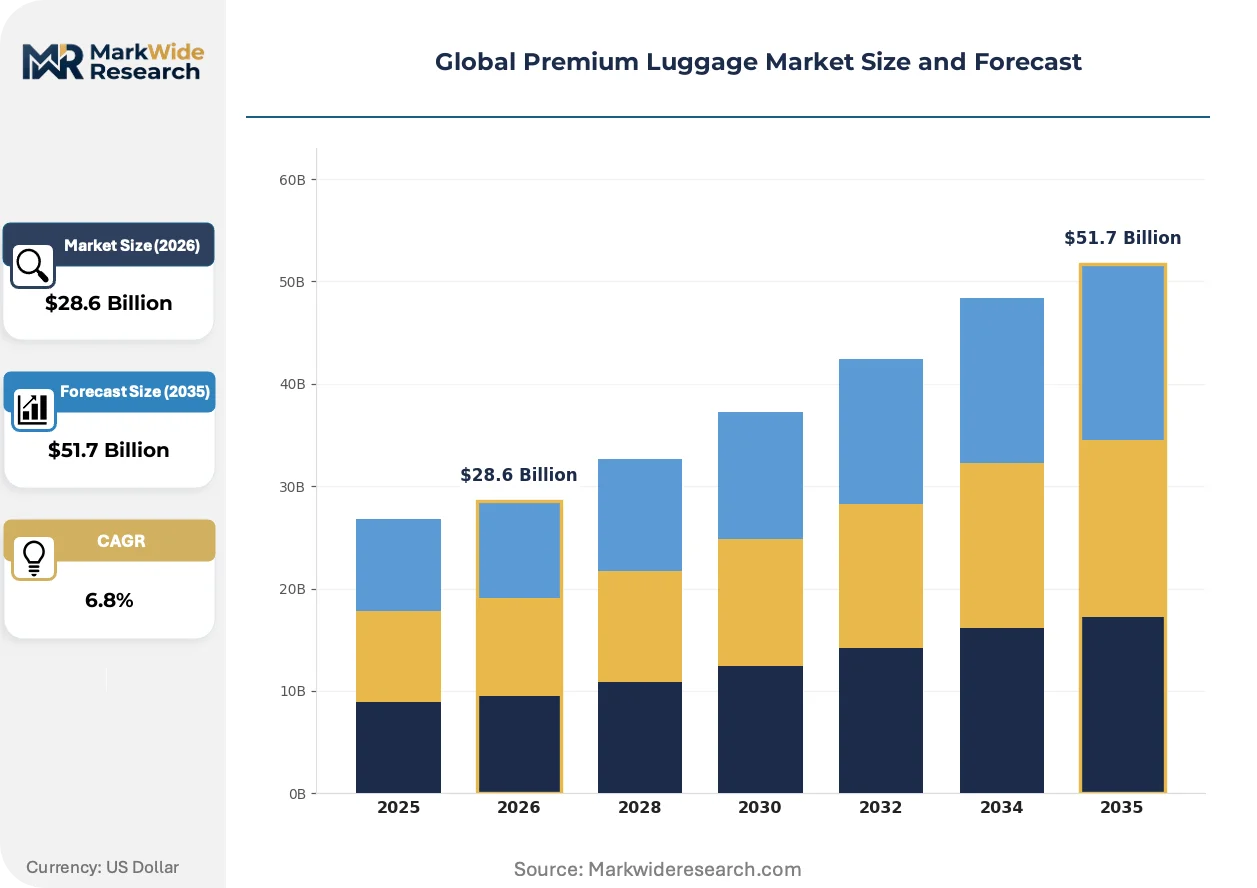
Material compliance mandates from REACH and California's Proposition 65 are forcing polycarbonate and leather reformulation across supply chains, while duty-free retail expansion in China reconfigures volume distribution toward aviation-adjacent channels.
Growth Catalysts
- Hainan Duty-Free Zones:China's island province eliminates tariffs on luxury goods, redirecting outbound tourist spending toward domestic aviation retail environments and compressing traditional retail margins.
- REACH Chemical Restrictions:ECHA-mandated phthalate and heavy metal limits compel aerospace-grade polycarbonate suppliers to develop compliant polymer blends, creating first-mover advantages for reformulation-capable manufacturers.
- Business Travel Recovery:Corporate mobility budget normalization post-pandemic restores procurement of lightweight ballistic nylon carry-ons with integrated charging systems for frequent domestic and regional routes.
Market Restraints
- Aluminum Input Volatility:Aerospace-grade aluminum sheet pricing fluctuates with energy costs and smelter capacity constraints in China and Russia, compressing margin predictability for heritage metal-shell producers.
- Prop 65 Labeling Burden:California's warning requirements for chromium-tanned leather and coated fabrics create compliance documentation overhead that disadvantages smaller tannery suppliers without dedicated regulatory staff.
- Aviation Weight Restrictions:IATA-mandated cabin baggage limits constrain material density choices, penalizing premium hard-shell constructions that exceed 7-10 kilogram thresholds on low-cost carriers.
Strategic Opportunities
- India Outbound Tourism:India's expanding middle-class international travel creates underpenetrated demand for entry-premium polycarbonate spinners priced between domestic mass-market and European heritage tiers.
- EU Green Deal Alignment:The EU's circular economy action plan rewards recyclable monobloc shell designs and bio-based interior linings with preferential retail placement in duty-free environments.
- Smart Luggage Convergence:Integration of GPS tracking modules with TSA-approved battery-removal systems enables premium positioning for tech-forward travelers on trans-Pacific routes.
Industry Challenges
- Skilled Aluminum Craftsmanship Scarcity:Monobloc shell welding and anodizing expertise concentrates in German and Japanese manufacturing clusters, limiting production scaling for new market entrants.
- Dual Certification Timelines:Simultaneous TSA lock approval and airline-specific size compliance testing extends product development cycles by 8-14 months for multi-wheel spinner systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Premium Luggage Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Shell, Soft Shell, Garment Bags, Duffle Bags Material: Polycarbonate, Leather, Canvas, Nylon End User: Business Travelers, Tourists, Luxury Consumers, Students Distribution Channel: Online Retail, Specialty Stores, Department Stores, Duty-Free Shops |
| Companies Covered | Samsonite, Rimowa, Tumi, Louis Vuitton, Hermès, Briggs & Riley, Victorinox, Delsey, Travelpro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Premium Luggage Market Strategic Shifts
Product engineering is converging with digital connectivity and circular material science, compressing traditional hardware-only differentiation while elevating software-integrated and sustainability-certified offerings.
Recycled aerospace-grade polycarbonate is absorbing virgin polymer demand in premium hard-shell manufacturing. European heritage brands and Asian contract manufacturers alike are adopting post-industrial regrind content exceeding 50% by weight. This material transition is compressing petrochemical feedstock dependence while requiring new supply partnerships with aviation sector waste recovery programs.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing zipper and hardware suppliers to migrate toward alternative lubricant formulations. ECHA enforcement actions against non-compliant Asian component vendors are accelerating supply chain auditing investments. Italian and Spanish leather-goods clusters are responding fastest due to existing chemical management infrastructure from luxury apparel compliance programs.
Direct-to-consumer configuration tools are fragmenting traditional wholesale relationships. Buyers now specify interior panel layouts, wheel hub colors, and monogram placement through brand-operated digital platforms, bypassing department store intermediaries. This behavioral shift is most visible among Chinese millennial travelers purchasing through WeChat mini-programs linked to Hainan duty-free inventory systems.
Global Premium Luggage Market Segmentation
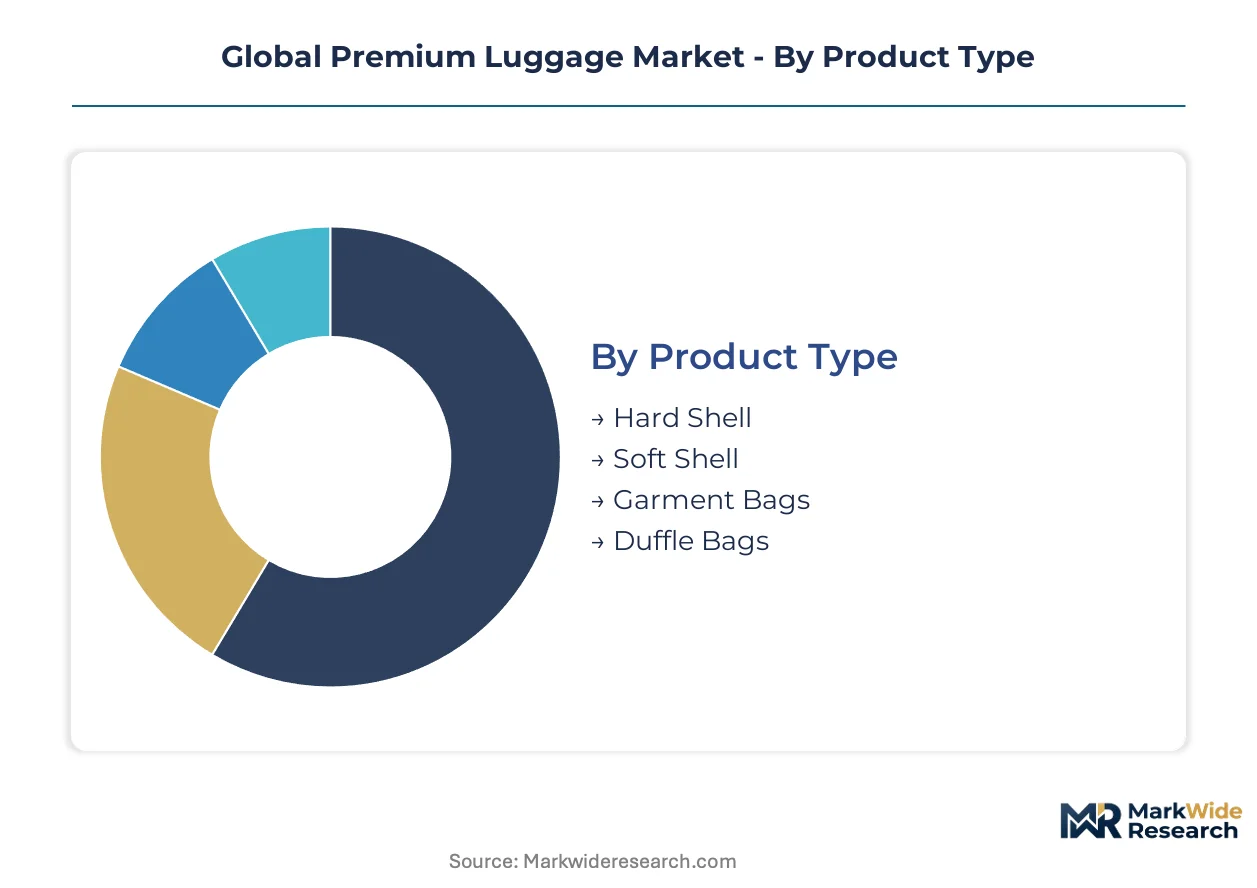
Premium luggage purchasing decisions diverge sharply across travel frequency, durability expectations, and channel accessibility. Understanding these fault lines enables manufacturers to align material investments with margin architecture and geographic rollout sequencing.
Product Type:
Durability perception and weight tolerance drive the primary purchase calculus for frequent flyers versus occasional vacationers.
- Hard Shell:Monobloc aerospace-grade polycarbonate or aluminum constructions withstand checked baggage handling stress. Corporate procurement teams favor these for international routes where baggage handlers operate under time pressure.
- Soft Shell:Woven ballistic nylon and coated canvas deliver sub-3-kilogram empty weights critical for low-cost carrier cabin limits. Business travelers on regional European routes prioritize these for overhead bin compliance.
- Garment Bags:Structured interior hanging systems protect suiting for same-day meeting arrivals.
- Duffle Bags:Unstructured volumes accommodate irregular cargo shapes favored by adventure tourism segments.
Hard Shell leads on scale; Soft Shell leads on momentum.
Material:
REACH compliance timelines and aviation sector waste recovery partnerships are redefining supplier qualification criteria across polymer and tannery networks.
- Polycarbonate:Virgin and post-industrial regrind formulations exceeding 50% recycled content now dominate hard-shell manufacturing. ECHA Annex XVII restrictions on phthalates compel reformulation investments that favor large-scale polymer compounders with dedicated regulatory staff.
- Leather:Full-grain vegetable-tanned hides command heritage brand positioning, though chromium-tanned variants face California Proposition 65 labeling burdens that compress tannery margins.
- Canvas:Waxed cotton and hemp blends serve sustainability-positioned entry-premium tiers.
- Nylon:Ballistic weave specifications from 1050-denier Cordura sustain soft-shell durability claims.
Polycarbonate anchors volume concentration; Leather retains pricing power in heritage channels.
End User:
Travel purpose and budget authority create distinct feature requirements across charging integration, monogram visibility, and interior organization.
- Business Travelers:Integrated USB-C power delivery and TSA-approved battery removal systems dominate procurement specifications. Lightweight construction under 7 kilograms ensures compliance with IATA cabin baggage guidelines on Lufthansa, Delta, and Emirates routes.
- Tourists:Expandable zipper systems and scratch-resistant finishes absorb the handling intensity of leisure travel. Hainan duty-free zone purchases concentrate here among Chinese outbound travelers.
- Luxury Consumers:Limited-edition collaborations and precious metal hardware justify 4-10x pricing multiples over functional equivalents.
- Students:Entry-premium polycarbonate spinners balance cost constraints with durability expectations for semester-abroad programs.
Business Travelers concentrate procurement volume; Tourists are expanding most quickly as aviation retail recovers.
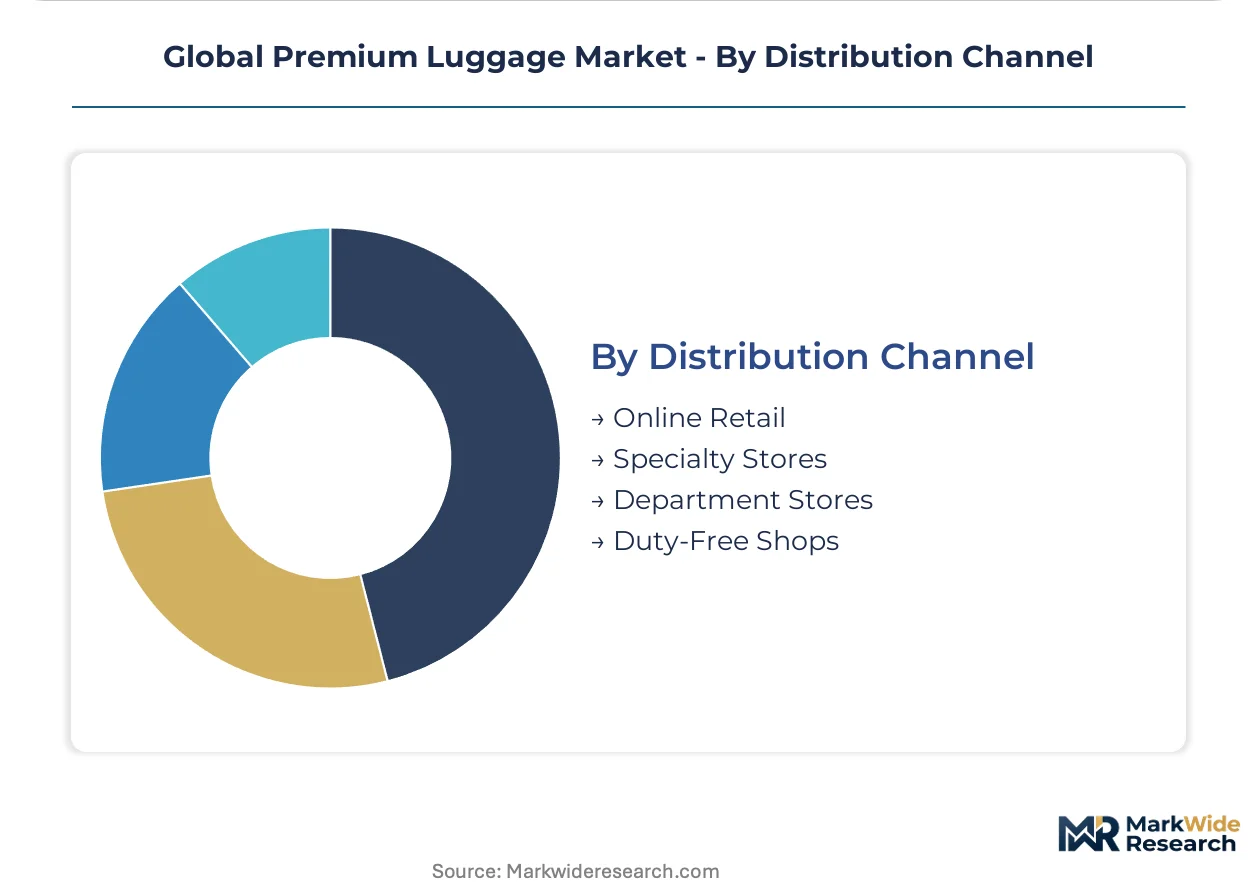
Distribution Channel:
Margin capture and customer data ownership are shifting volume from wholesale intermediaries toward brand-controlled digital platforms and aviation-adjacent retail.
- Online Retail:Direct-to-consumer configuration tools now enable interior panel customization and monogram placement through WeChat mini-programs and proprietary brand apps. This bypasses department store margin stacking while capturing first-party purchase data.
- Specialty Stores:Trained staff demonstrate wheel system durability and locking mechanism operation for high-consideration purchases. These locations concentrate in Frankfurt, Dubai, and Singapore aviation retail corridors.
- Department Stores:Multi-brand comparison shopping persists for gift purchases and first-time premium buyers.
- Duty-Free Shops:Hainan island province elimination of luxury tariffs redirects spending from European capitals toward domestic Chinese aviation retail.
Online Retail is gaining share fastest; Duty-Free Shops sustain margin density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian leather artisans and German metalworkers anchor the industry's craft heritage, while Chinese polymer engineers and Indian textile specialists concentrate in emerging supply clusters. Workforce density in these geographies shapes where reformulation investments and retail expansion capital flow.
China
Hainan duty-free zones redirect outbound tourist spending toward domestic aviation retail, compressing traditional European retail margins. MIIT enforces GB standards for polymer safety in consumer goods, accelerating compliant polycarbonate blend development. Guangdong province hosts the densest concentration of spinner wheel assembly plants serving global brand OEM contracts.
Germany
Business traveler procurement from Lufthansa hubs sustains demand for sub-7-kilogram cabin-compliant constructions. ECHA REACH Annex XVII restrictions on phthalates compel reformulation partnerships between Cologne-based polymer compounders and shell manufacturers. Bavaria's monobloc aluminum welding workshops supply heritage brands with anodizing expertise concentrated around Munich industrial corridors.
United States
Corporate mobility budget normalization restores procurement of integrated charging systems for Delta and American Airlines frequent flyers. California Proposition 65 warning requirements for chromium-tanned leather create compliance documentation overhead that disadvantages smaller tannery suppliers. Texas distribution centers handle bulk import volumes for North American e-commerce fulfillment networks.
Italy
Full-grain vegetable-tanned leather commands heritage positioning among luxury consumers in Milan and Rome retail corridors. Existing chemical management infrastructure from luxury apparel compliance programs accelerates REACH zipper and hardware reformulation responses. Tuscan tannery clusters around Florence adapt chromium-free processes to maintain California market access.
India
Expanding middle-class international travel creates underpenetrated demand for entry-premium polycarbonate spinners priced between domestic mass-market and European heritage tiers. BIS certification requirements for imported luggage quality standards filter substandard imports from unbranded competitors. Maharashtra's Mumbai-Pune industrial corridor concentrates contract manufacturing for Asian brand licensees serving outbound tourism growth.
Global Premium Luggage Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered positioning architectures. The vendor base organizes around heritage European houses, American functionality brands, and Asian manufacturing platforms serving licensed production. Three archetypes dominate: craft-anchored luxury maisons, engineering-driven durability specialists, and scale-oriented multi-brand portfolios. Competitive moves concentrate on direct-to-consumer channel capture and sustainable material certification partnerships.
Within the heritage luxury tier, Louis Vuitton and Hermès exemplify craft-anchored positioning through leather ateliers and precious metal hardware programs. Samsonite occupies a position as the scale-driven multi-brand architect, while Rimowa and Tumi represent engineering-focused durability archetypes with aluminum monobloc and ballistic nylon specializations respectively. These five names anchor the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| Samsonite |
| Rimowa |
| Tumi |
| Louis Vuitton |
| Hermès |
| Briggs & Riley |
| Victorinox |
| Delsey |
| Travelpro |
| Others |
Value Chain & Pricing Dynamics
Post-industrial polycarbonate regrind adoption exceeding 50% by weight simultaneously compresses petrochemical feedstock costs and concentrates reformulation capability among large-scale polymer compounders with dedicated ECHA compliance staff. This materials transition redistributes margin capture from virgin resin distributors toward aviation sector waste recovery programs and certified regrind suppliers.
Pricing Analysis
Unbundled component customization now dominates direct-to-consumer channels while bundled after-sales service packages sustain heritage retail premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and geographic delivery cost variation. Pricing pressure stems from aluminum input volatility driven by energy cost fluctuations at Chinese and Russian smelters. Corporate procurement teams demonstrate lowest price sensitivity due to corporate mobility budget authority, while student segments concentrate price elasticity in entry-premium tiers.
Supply Chain Analysis
Dual-sourcing requirements from global brand OEMs mandate simultaneous qualification of German-Japanese aluminum craftsmanship clusters and Guangdong spinner wheel assembly plants. Aerospace-grade polycarbonate draws from Belgium, Thailand, and South Korea; full-grain leather feeds from Tuscan and Andalusian tannery networks. Single-source vulnerability concentrates in monobloc shell welding expertise around Munich industrial corridors. Distribution runs through Hainan duty-free aviation retail corridors and Texas e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
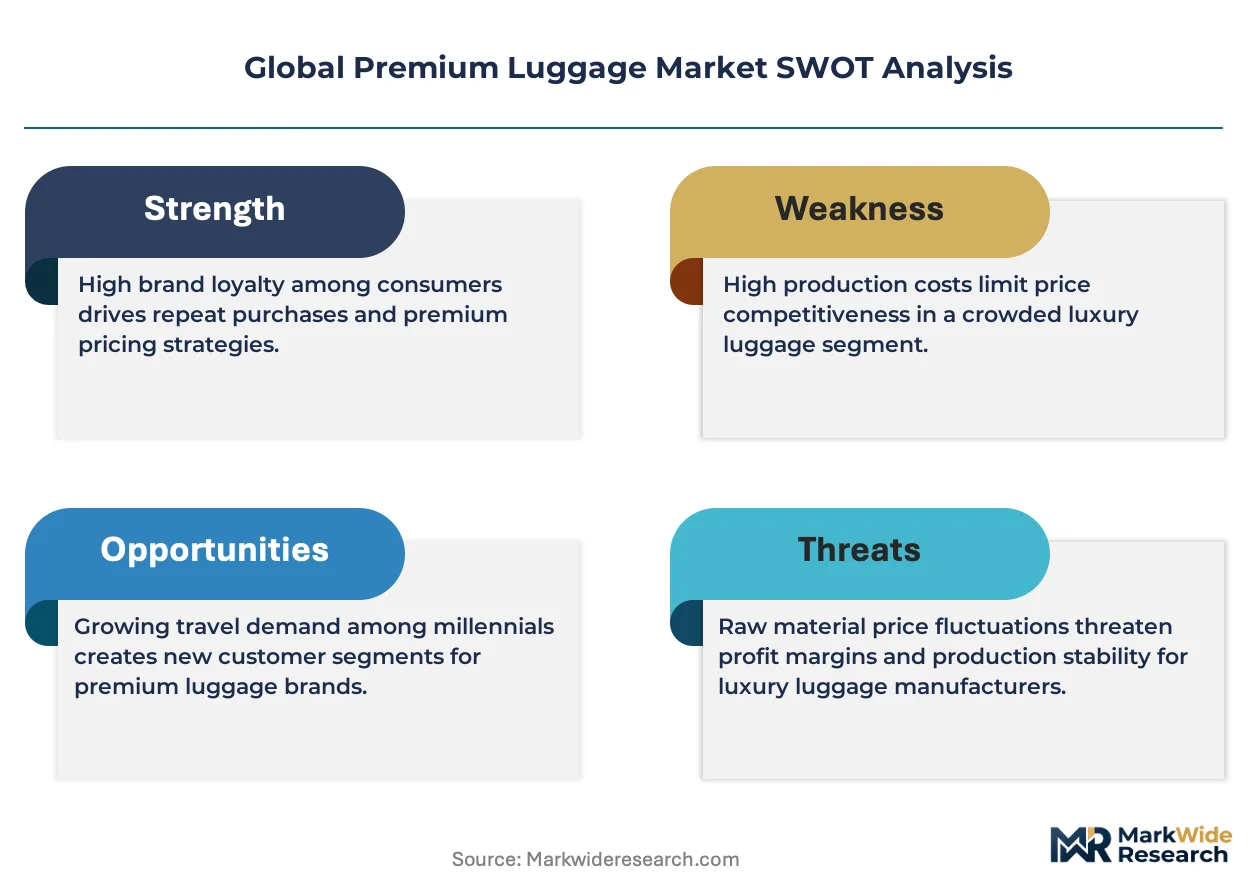
This market functions as a geographic-arbitrage play between REACH-compliant European supply chains and California Proposition 65 labeling burdens that disadvantage smaller tannery suppliers without dedicated regulatory staff.
For Market Incumbents: Extend anodizing expertise partnerships into Indian contract manufacturing corridors before BIS certification requirements harden import barriers. Deepen backward integration into post-industrial polycarbonate regrind supply through aviation sector waste recovery programs to defend margin position against aluminum input volatility. For New Entrants and Emerging Players: Aviation-adjacent retail specialists in Hainan duty-free zones offer the most penetrable channel partnership structure for entry-premium positioning. Target India's expanding middle-class outbound tourism through Mumbai-Pune industrial corridor contract manufacturing relationships and localized polycarbonate spinner assembly. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian manufacturing platforms serving licensed production with underdeveloped direct-to-consumer channel capture. Long-term viability hinges on circular economy certification alignment with EU Green Deal preferential retail placement. Watch ECHA enforcement actions against non-compliant Asian component vendors as inflection signal for supply chain auditing investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Configuration Platform Launch | WeChat mini-program integration with Hainan duty-free inventory systems captures first-party purchase data from Chinese millennial travelers. |
| Recycled Content Certification Investment | EU Green Deal circular economy alignment secures preferential retail placement in aviation-adjacent duty-free environments. |
| REACH-Compliant Polymer Reformulation Partnership | ECHA Annex XVII phthalate restriction compliance creates first-mover advantage among large-scale compounders with dedicated regulatory staff. |
| Aviation Retail Channel Expansion | Hainan island tariff elimination redirects outbound tourist spending from European capitals toward domestic Chinese aviation retail. |
| Smart Luggage Convergence Development | GPS tracking module integration with TSA-approved battery-removal systems enables premium positioning for tech-forward trans-Pacific travelers. |
Study Parameters
Coverage spans China, Germany, United States, Italy, and India, with primary inputs from each market's stakeholder ecosystem. Primary interviews with brand supply chain directors, tannery compliance officers, aviation retail procurement managers, and polymer compounder R&D leads combined with secondary validation from ECHA enforcement databases, MIIT GB standards filings, US CPSC product safety alerts, and customs trade records. Bottom-up shipment data triangulated against top-down consumer spending estimates across the analysis window.
Granularity-level modeling disaggregated volume and value across hard shell, soft shell, garment bag, and duffle bag product types; polycarbonate, leather, canvas, and nylon material grades; business traveler, tourist, luxury consumer, and student end-user segments; and online retail, specialty store, department store, and duty-free shop distribution channels. CAGRs derived from regression-based trend extrapolation incorporating aluminum price index trajectories, aviation passenger recovery curves, and regulatory compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IATA cabin baggage weight restriction tightening and REACH Annex XVII expansion to additional chemical classes. Deviation in Hainan duty-free zone policy continuity or ECHA enforcement intensity against Asian component vendors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Second Hand Bag Market
Luggage
United States Sports Bags Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
School Bags Market
Luggage
Laptop Messenger Bags Market
Luggage
Laptop Carry Case Market
Luggage
Sports Luggage Market
Luggage
Global Luggage Market
Luggage
Travel and Business Bags Market
Luggage
Smart Carry-On Luggage Market
Luggage
Smart Bags Market
Luggage
Bags Market
Luggage
Backpack Market
Luggage
Sewing Bags Market
Luggage
Trolley Bags Market