
 Global Outdoor Sports Luggage Market | 2026-2036
Global Outdoor Sports Luggage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Outdoor Sports Luggage Market Foresight
The EU Green Deal is consolidating demand around recycled-content mandates and extended producer responsibility frameworks across European outdoor retail channels. Patagonia leverages its repair-and-resale infrastructure to anchor premium positioning in climate-conscious segments. Osprey Packs specializes in technical backpack architectures for multi-day trekking, while The North Face competes through integrated apparel-and-luggage ecosystems that reduce buyer decision friction.
Global outdoor sports luggage encompasses purpose-built transport and storage systems engineered with ripstop nylon weaves, waterproof TPU laminates, and anatomically framed suspension for load distribution across variable terrain. These products serve expedition-grade mobility where standard travel cases fail under abrasion, moisture, and dynamic compression. Backpacks and duffel bags occupy the core volume tier, with hydration packs representing the fastest-expanding category as ultralight trekking and fast-packing participation rises. Nylon and polyester still dominate material procurement, though TPU coated fabric is gaining share in kayaking and ski segments where submersion resistance determines product survival.
REACH and RoHS in Europe restrict phthalate-based coatings and heavy-metal dyes in textile manufacturing, forcing reformulation of waterproofing chemistries across supplier bases. The EPA and California's Proposition 65 impose parallel constraints on U.S. imports, while China's GB standards govern domestic production and export certification for brands manufacturing in Shenzhen and Dongguan clusters. Stakeholders must monitor how diverging chemical compliance calendars between Brussels and Beijing reshape sourcing geography and inventory staging decisions.
Market Dynamics
Material traceability mandates under the EU Green Deal are compressing supplier qualification timelines while forcing parallel reformulation of waterproofing chemistries across Asian manufacturing clusters.
Growth Catalysts
- REACH and RoHS compliance deadlines:European retailers now require full chemical disclosure for nylon and polyester inputs, accelerating certified supplier consolidation across the value chain.
- Ultralight trekking participation:Hydration pack demand is expanding as fast-packing athletes prioritize weight-to-capacity ratios above durability metrics.
- Shenzhen-Dongguan production clusters:Chinese manufacturing hubs are capturing volume share through integrated TPU lamination and ripstop weaving capabilities.
Market Restraints
- Petrochemical input volatility:Nylon and polyester resin prices fluctuate with crude oil indices, compressing margin visibility for mid-tier manufacturers.
- TPU coating supply concentration:Submersion-grade laminate production concentrates among German and Japanese specialty chemical suppliers, creating single-source vulnerability.
- California Proposition 65 litigation exposure:Heavy-metal dye lawsuits against imported luggage are forcing costly pre-shipment testing protocols.
Strategic Opportunities
- Indian Himalayan expedition sector:Technical mountaineering growth in Uttarakhand and Himachal Pradesh is outpacing domestic gear supply, creating import substitution potential.
- Bio-based polyester R&D pipelines:Castor oil-derived polymers are achieving abrasion parity with virgin nylon, opening premium positioning for early adopters.
- Direct-to-expedition-team sales channels:Alpine guiding companies are bypassing retail markup through bulk procurement contracts with manufacturers.
Industry Challenges
- Load-bearing suspension engineering talent:Anatomical frame design expertise concentrates among veteran backpack specialists, constraining new entrant product development velocity.
- Dual certification timelines:Simultaneous EPA and ECHA compliance testing extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Outdoor Sports Luggage Market |
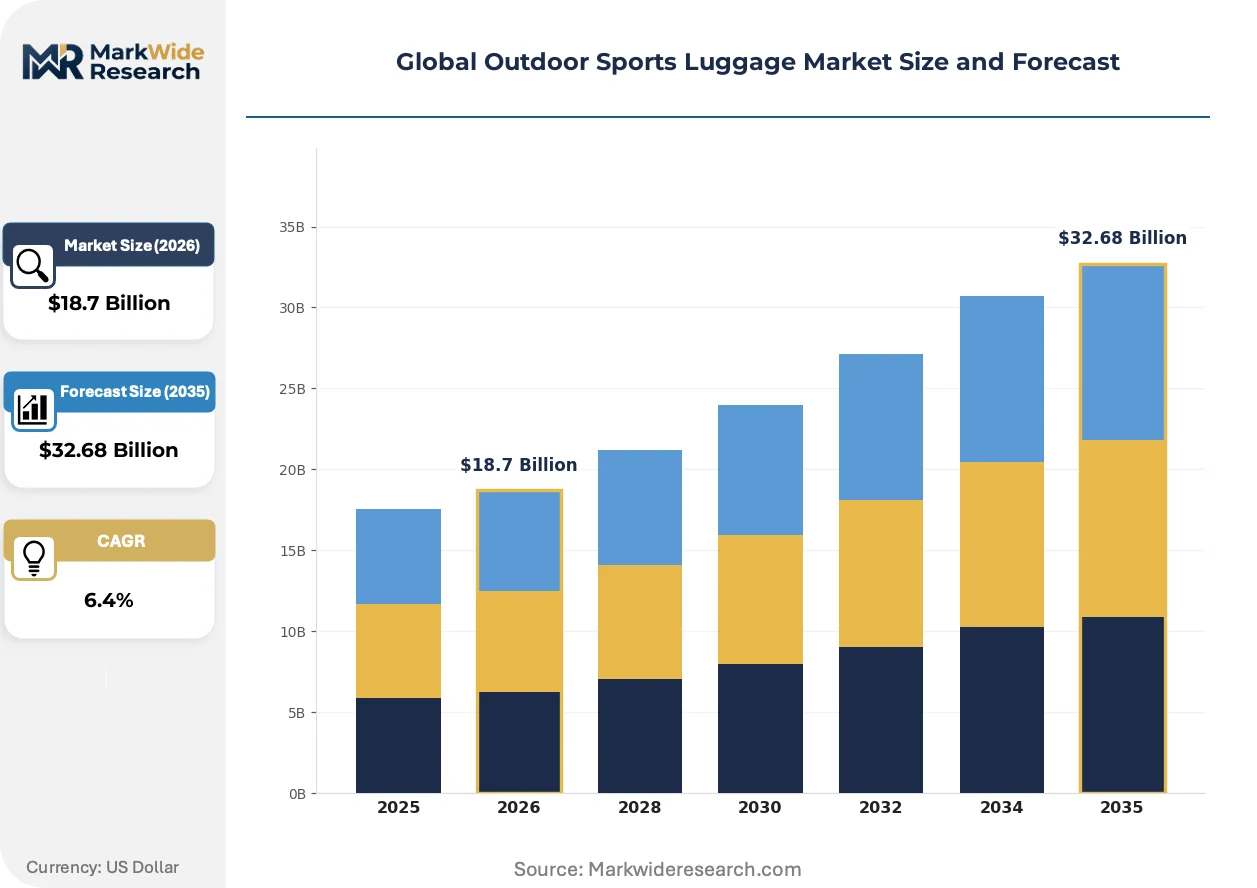
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Duffel Bags, Travel Totes, Rolling Suitcases, Hydration Packs Material: Nylon, Polyester, Canvas, Leather, TPU Coated Fabric Application: Hiking, Mountaineering, Camping, Skiing, Kayaking End User: Adventure Enthusiasts, Expedition Teams, Outdoor Trainers, Power Lifting Athletes |
| Companies Covered | Nike, Inc., Adidas AG, Under Armour, Inc., The North Face, Osprey Packs, Patagonia, PUMA SE, Columbia Sportswear, Arc'teryx Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Outdoor Sports Luggage Market Shifts & Advancements
Climate-adaptive design requirements are fusing material science breakthroughs with regulatory compliance automation, reshaping how manufacturers validate product performance across extreme environments.
Modular suspension architecture is unifying load distribution systems across backpack and duffel categories. Alpine expedition teams are adopting interchangeable hip belts and shoulder harnesses that transfer between pack sizes. This convergence is compressing SKU proliferation while enabling manufacturers to serve multiple trek durations with shared component platforms.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of durable water repellent coatings across European supply chains. Manufacturers must now validate alternative chemistries through ECHA-registered testing protocols. Ski and kayak luggage segments face the steepest compliance curves given submersion performance requirements.
Repair-and-resale service unbundling is fragmenting traditional retail relationships. Outdoor enthusiasts in Germany and Austria now prioritize brands offering in-house refurbishment over warranty replacement. This preference shift is visible in technical backpack replacement cycles, where buyers extend usable life through component-level servicing rather than full product turnover.
Global Outdoor Sports Luggage Market Segmentation
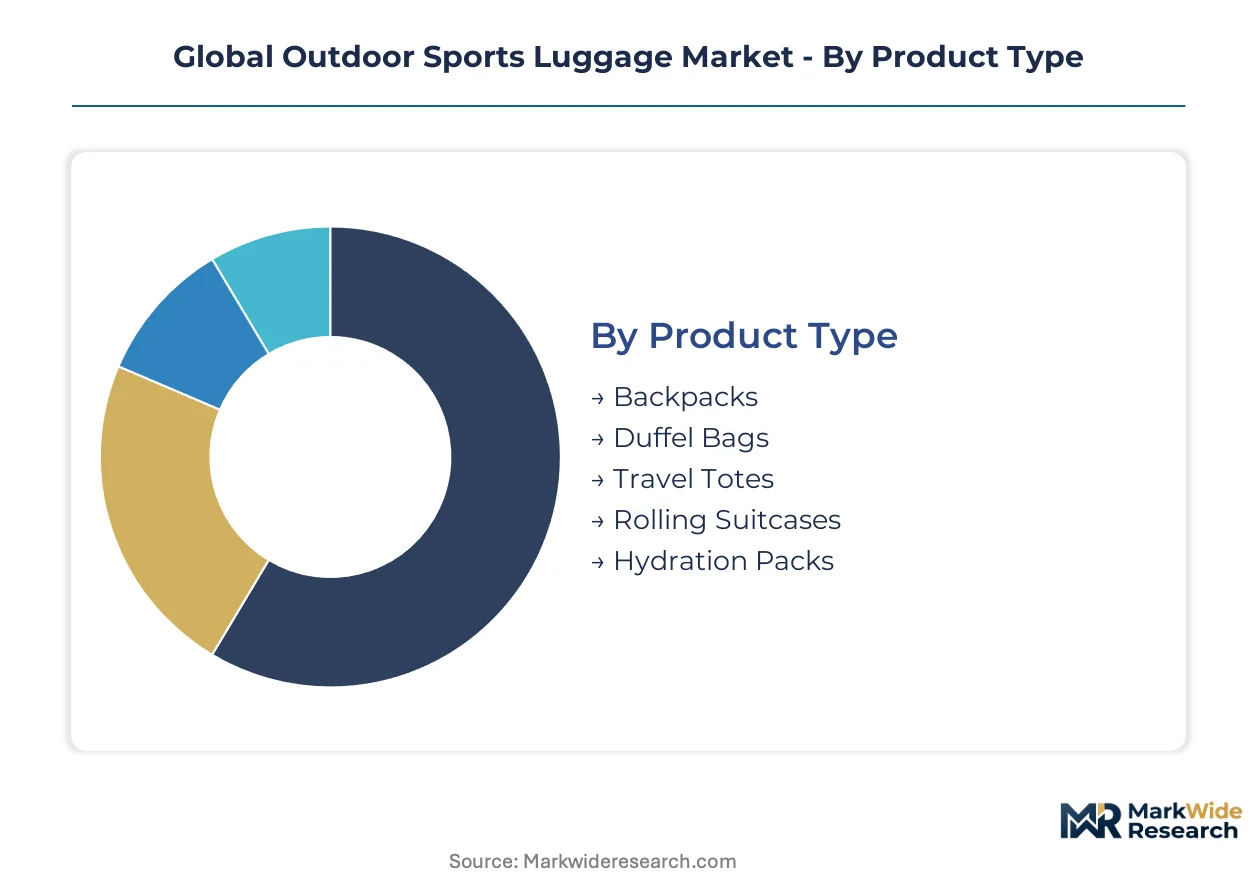
Segmentation in outdoor sports luggage reveals divergent engineering priorities across user intensity levels. Volume concentration sits with recreational hikers, while premium margins attach to expedition-grade technical specifications.
Product Type:
Volume concentration favors multi-day trekking formats, while premium replacement cycles concentrate in specialized submersion-resistant designs.
- Backpacks:Anatomically framed suspension systems distribute dynamic loads across hip belts and shoulder harnesses. German alpine guiding companies drive replacement demand through component-level servicing rather than full product turnover.
- Duffel Bags:Cylindrical or rectangular soft-shell architectures prioritize abrasion resistance over structured organization. Expedition teams in Uttarakhand and Himachal Pradesh favor oversized capacities for base-camp logistics.
- Travel Totes:Open-top unstructured designs serve casual outdoor retail and day-trip provisioning. Weekend camping participation in Austria and Switzerland sustains steady procurement.
- Rolling Suitcases:Telescoping handle and wheel systems trade terrain adaptability for airport mobility. Urban outdoor enthusiasts in Munich and Zurich deploy these for fly-in trekking destinations.
- Hydration Packs:Integrated reservoir sleeves and tube routing minimize weight-to-capacity ratios. Fast-packing athletes across Colorado and California prioritize these for ultralight summit attempts.
Mature deployment sits with backpacks. Newer deployment is concentrated in hydration packs.
Material:
Cost tier stratification separates commodity petrochemical inputs from certified recycled-content alternatives commanding regulatory compliance premiums.
- Nylon:Ripstop weaves with high tenacity yarns deliver tear resistance under dynamic tension. REACH Annex XVII restrictions on perfluorinated compounds are forcing DWR coating reformulation across European supply chains.
- Polyester:Lower moisture absorption than nylon reduces weight gain in humid conditions. Shenzhen-Dongguan manufacturing clusters dominate virgin and recycled PET sourcing for mid-tier production.
- Canvas:Heavy cotton duck weaves provide breathable abrasion resistance for dry-climate trekking. Heritage aesthetic positioning sustains niche demand among European outdoor enthusiasts prioritizing repairability.
- Leather:Full-grain hides offer puncture resistance and aging patina for expedition-grade duffel reinforcement. Italian tanneries supply premium positioning segments despite moisture-sensitivity limitations.
- TPU Coated Fabric:Thermoplastic polyurethane laminates create submersion-grade barriers for kayak and ski luggage. German and Japanese specialty chemical suppliers concentrate production, creating single-source vulnerability.
Volume leadership belongs to nylon. Bio-based polyester alternatives are gaining share fastest.
Application:
Customer type intensity separates casual weekend participants from professional expedition contractors with distinct durability requirements.
- Hiking:Day-trip and multi-day trail systems demand balanced weight-to-capacity optimization. Appalachian Trail thru-hikers and Pacific Crest Trail section hikers drive seasonal procurement spikes in North American retail.
- Mountaineering:Technical ice and rock environments require ice-axe attachment points and crampon patches. Alpine guiding companies in Chamonix and Zermatt negotiate bulk procurement contracts bypassing retail markup.
- Camping:Base-camp logistics prioritize volume capacity over weight minimization. Family outdoor recreation in Bavaria and Tyrol sustains replacement cycles for entry-level duffel formats.
- Skiing:Boot and helmet compartments with padded protection dominate design specifications. Austrian and Swiss alpine resorts drive premium positioning for climate-adaptive hard-shell and soft-shell hybrid formats.
- Kayaking:Submersion resistance and drainage compatibility determine product survival in whitewater and sea-kayak environments. Pacific Northwest and Norwegian fjord expedition operators specify IPX7-equivalent sealing standards.
Revenue concentration rests with mountaineering. Participation expansion is climbing the fastest in kayaking.
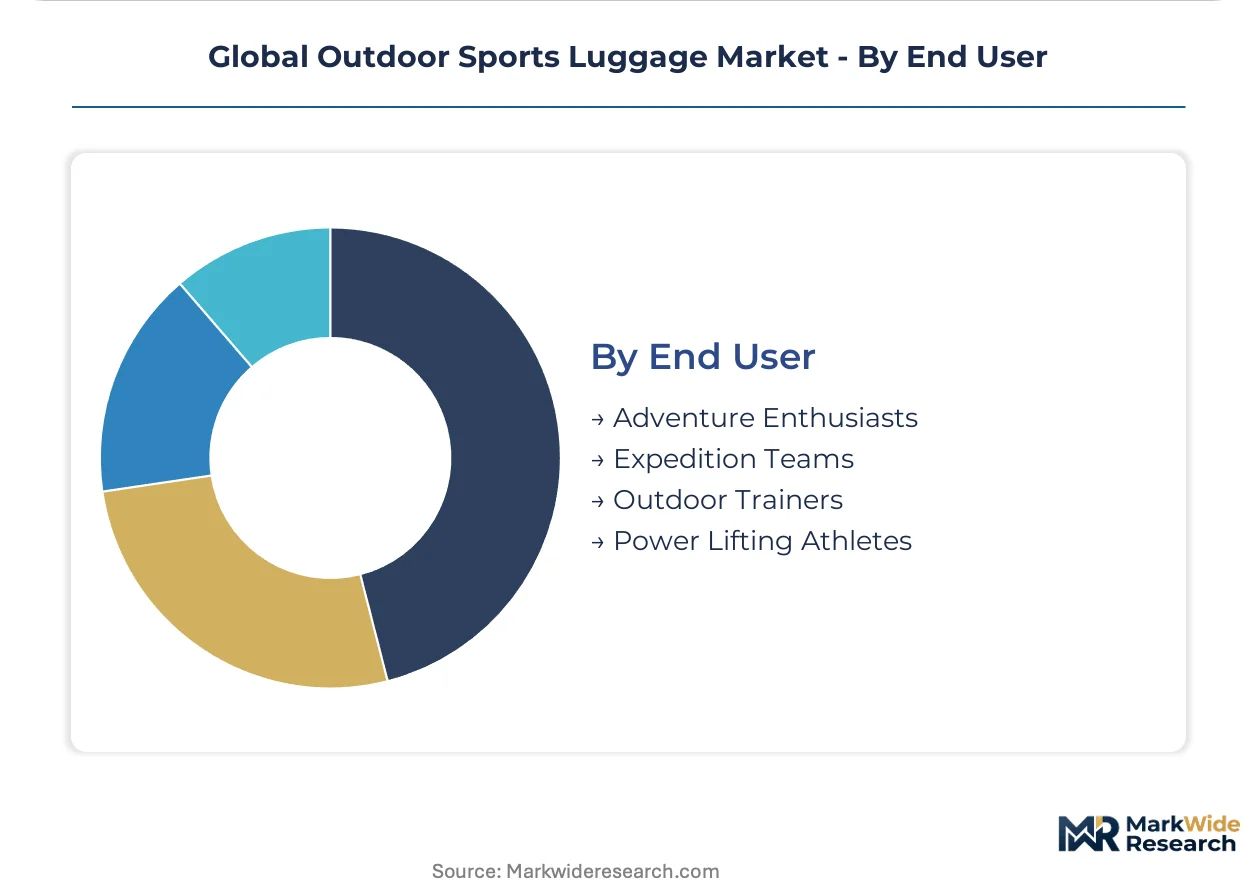
End User:
Margin structure separates individual retail purchasers from institutional volume contracts with diverging service and warranty expectations.
- Adventure Enthusiasts:Self-directed recreationalists purchase through specialty retail and direct-to-consumer channels. German and Austrian consumers prioritize repair-and-resale service infrastructure in brand selection.
- Expedition Teams:Professional guiding companies and scientific research operations deploy gear under extreme-use conditions. Bulk procurement contracts with manufacturers compress per-unit margins while securing volume commitments.
- Outdoor Trainers:Certification instructors and wilderness educators require durable equipment for repeated student-group use. Colorado Outward Bound and similar programs drive mid-tier backpack replacement cycles.
- Power Lifting Athletes:Niche segment requiring reinforced duffel architectures for weight plate and equipment transport. CrossFit affiliate networks in Texas and Florida sustain specialized procurement demand.
Established volume sits with adventure enthusiasts. Institutional growth is concentrating in expedition teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European technical mountaineering culture, driving premium backpack replacement cycles through alpine guiding company procurement. Shenzhen-Dongguan manufacturing clusters capture volume share through integrated TPU lamination capabilities. Denver and Chamonix expedition operators set performance standards for submersion-resistant designs.
Germany
Technical mountaineering culture in Bavaria and Baden-Württemberg drives premium duffel bag and backpack replacement demand. EU Green Deal material traceability mandates compress supplier qualification timelines for recycled nylon inputs. Munich and Stuttgart industrial corridors concentrate repair-and-resale service infrastructure serving alpine guiding companies.
United States
Fast-packing athletes across Colorado and California prioritize hydration packs with minimized weight-to-capacity ratios. EPA and California Proposition 65 impose parallel constraints on phthalate-based coatings and heavy-metal dyes. Pacific Northwest kayak expedition operators specify IPX7-equivalent sealing standards for whitewater gear procurement.
China
Shenzhen-Dongguan production clusters dominate integrated TPU lamination and ripstop weaving capabilities for mid-tier export manufacturing. GB standards govern domestic production and export certification requirements. Yangtze River Delta fabric mills supply certified recycled PET inputs meeting ECHA-registered testing protocols.
India
Technical mountaineering growth in Uttarakhand and Himachal Pradesh outpaces domestic gear supply, creating import substitution potential. Central pollution control board directives align with REACH compliance trajectories for chemical disclosure. Delhi-NCR distribution hubs stage inventory for Himalayan expedition team bulk procurement contracts.
Switzerland
Alpine resorts in Valais and Graubünden drive premium positioning for climate-adaptive hard-shell and soft-shell hybrid ski luggage. Swissmedic-equivalent product safety frameworks govern technical equipment certification. Zürich and Geneva specialty retailers prioritize brands offering component-level servicing over warranty replacement.
Global Outdoor Sports Luggage Market Competitive Landscape
The competitive structure tilts toward integrated apparel-and-luggage ecosystems and technical specialists with repair infrastructure. Consolidation concentrates among heritage outdoor brands with established alpine credibility, while mid-tier fabricators face margin compression from petrochemical input volatility. Three archetypes dominate: climate-conscious premium positioned players, technical backpack architecture specialists, and diversified sportswear conglomerates with outdoor divisions. Competitive moves center on backward integration into TPU coating supply chains and direct-to-expedition-team sales channel development.
Within the technical specialist tier, Osprey Packs and Arc'teryx Equipment exemplify load-bearing suspension engineering expertise concentrated among veteran backpack designers. Patagonia occupies a position anchoring climate-conscious segments through repair-and-resale service infrastructure. Among diversified conglomerates, Adidas AG and Nike, Inc. leverage apparel ecosystems to reduce buyer decision friction across integrated product ranges. The North Face sits within the heritage alpine credibility archetype, serving guiding company bulk procurement requirements.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Under Armour, Inc. |
| The North Face |
| Osprey Packs |
| Patagonia |
| PUMA SE |
| Columbia Sportswear |
| Arc'teryx Equipment |
| Others |
Supply & Pricing Matrix
Petrochemical resin costs cascade through outdoor sports luggage manufacturing from Shenzhen-Dongguan weaving clusters to European retail markup, compressing margin visibility for mid-tier fabricators while premium brands capture certification-grade premiums through backward integration into recycled nylon sourcing.
Pricing Analysis
Load-bearing suspension performance anchors value-based pricing tiers across the outdoor sports luggage market. Three-tier pricing structure across premium, standard, and economy levels separates expedition-grade technical specifications from recreational hiking formats. Price differentiation stems from REACH-compliant material certification and anatomical frame engineering expertise. Cost compression in mid-tier nylon backpacks is intensifying because Shenzhen-Dongguan manufacturers compete on volume scale. Adventure enthusiasts exhibit highest price sensitivity, while alpine guiding companies prioritize durability metrics over per-unit cost.
Supply Chain Analysis
TPU laminate supply rests on German and Japanese specialty chemical producers, creating single-source vulnerability for submersion-grade kayak and ski luggage. Ripstop nylon weaving draws from Shenzhen-Dongguan production clusters, while recycled PET certification feeds from Yangtze River Delta fabric mills. Raw material dependencies center on virgin and recycled nylon resins, thermoplastic polyurethane coatings, and bio-based polyester alternatives. Distribution runs through specialty outdoor retail channels in Munich and Chamonix, direct-to-consumer platforms, and bulk procurement contracts with expedition operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The outdoor sports luggage sector is navigating a material-transition phase as bio-based polyester alternatives displace virgin nylon in climate-conscious segments, forcing legacy petrochemical-dependent manufacturers to reformulate supply chains or cede premium positioning.
For Market Incumbents: Deploy repair-and-resale service infrastructure as a defensive moat against fast-fashion outdoor entrants. Patagonia's refurbishment model demonstrates how component-level servicing extends replacement cycles and locks in alpine guiding company loyalty. Backward integration into certified recycled nylon sourcing protects margin structure against ECHA-registered testing protocol costs. Capacity addition in Indian Himalayan distribution hubs preempts import substitution demand from Uttarakhand and Himachal Pradesh expedition operators.
For New Entrants and Emerging Players: Begin with hydration pack specialization targeting fast-packing athletes across Colorado and California, where ultralight trekking participation outpaces established brand coverage. White-space concentration sits in bio-based polyester R&D pipelines, where castor oil-derived polymers achieve abrasion parity with virgin nylon. Direct-to-expedition-team sales channels bypass retail markup and compress customer acquisition costs for bulk procurement contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier fabricators with integrated TPU lamination capabilities in Shenzhen-Dongguan corridors, where petrochemical input volatility has compressed valuations. Long-term viability hinges on regulatory compliance automation and climate-adaptive design portfolios. The signal to watch is ECHA-registered testing protocol adoption rates among Asian manufacturing clusters, indicating which suppliers will survive EU Green Deal material traceability mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Nylon Sourcing | Secures REACH-compliant material streams for European retail channels under EU Green Deal mandates. |
| Direct-to-Expedition-Team Sales Channel Development | Bypasses specialty retail markup and locks volume commitments from Chamonix and Zermatt guiding companies. |
| Bio-Based Polyester R&D Pipeline Investment | Positions early adopters for premium pricing as castor oil-derived polymers achieve abrasion parity benchmarks. |
| Repair-and-Resale Service Infrastructure Expansion | Captures German and Austrian consumer preference for component-level servicing over warranty replacement. |
| TPU Lamination Capability Acquisition | Reduces single-source vulnerability from German and Japanese specialty chemical suppliers for submersion-grade products. |
Research Methodology
Independent corroboration across alpine guiding company procurement officers, Shenzhen-Dongguan manufacturing plant managers, European specialty retail category buyers, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with load-bearing suspension engineers and material science R&D directors combined with secondary validation from EU Green Deal implementation documents, REACH Annex XVII restriction updates, and customs trade data for nylon and polyester inputs. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the outdoor equipment sector.
Rate-of-change decomposition separates volume drivers from value migration across product type, material certification tier, application intensity, and end-user contract structure dimensions. CAGRs derive from segment-level growth trajectories weighted by replacement cycle patterns and regulatory compliance timeline impacts. Forecast inputs incorporate fast-packing participation trends, ECHA-registered testing protocol adoption curves, and petrochemical resin price volatility indices.
Regulatory calendar divergence between Brussels and Beijing, raw material supply disruption events, and ultralight trekking participation volatility are the dominant revision risks to the projection framework. Forecasts reflect documented assumptions about EU Green Deal enforcement intensity and bio-based polyester scale-up timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Global Luggage Market
Luggage
Sewing Bags Market
Luggage
Travel and Business Bags Market
Luggage
United States Sports Bags Market
Luggage
Kids Backpack Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Bags Market
Luggage
Trolley Bags Market
Luggage
Laptop Carry Case Market
Luggage
School Bags Market
Luggage
Camera Bag Market
Luggage
Trunks Market
Luggage
Smart Carry-On Luggage Market
Luggage
Second Hand Bag Market
Luggage
Laptop Messenger Bags Market
Luggage
Backpack Market