
 Trolley Bags Market | 2026-2036
Trolley Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Trolley Bags Market Analytics
Extended warranty and repair subscription services is consolidating around durable goods positioning, fundamentally altering how luggage brands monetize customer relationships. Samsonite International S.A. leverages its global retail footprint to sustain replacement-cycle revenue across premium and mid-market tiers. Rimowa GmbH anchors its competitive stance through aluminum craftsmanship heritage and airline partnership programs. VIP Industries Ltd. dominates price-sensitive segments in South Asia through mass-market distribution density.
Trolley bags are wheeled luggage systems incorporating telescopic handles, spinner or inline wheel configurations, and rigid or semi-rigid shells engineered from polycarbonate, ABS, or woven textiles, designed primarily for personal transport of garments and travel essentials during air, rail, or road transit. Cabin Bags command disproportionate attention as airlines enforce stricter dimensional limits, compressing design tolerances and favoring ultra-lightweight material innovation. Polyester retains volume leadership across mass-market manufacturing due to cost scalability and dye-sub pattern flexibility, while Leather occupies concentrated margin pools in executive business segments where longevity signals professional status.
FAA carry-on dimension guidelines and EU261 passenger rights frameworks indirectly shape product specifications by penalizing non-compliant luggage at boarding gates, forcing manufacturers toward dimensional precision. REACH chemical restrictions and California Proposition 65 disclosure requirements constrain coating and adhesive chemistries across European and North American supply chains. Stakeholders must monitor evolving airline baggage policies and material compliance thresholds rather than treating product portfolios as static seasonal cycles.
Market Dynamics
Airline dimensional enforcement is compressing design tolerances and forcing manufacturers toward ultra-lightweight polycarbonate and hybrid textile shells that maximize internal volume within shrinking carry-on limits.
Growth Catalysts
- FAA Carry-On Guidelines:Stricter boarding-gate enforcement of dimensional limits in the United States is accelerating replacement cycles as travelers discard non-compliant legacy luggage.
- Polycarbonate Shell Innovation:Advances in co-extrusion molding are enabling thinner-walled hard shells that retain impact resistance while reducing empty weight by meaningful margins.
- China Manufacturing Concentration:Integrated mold-making and textile finishing clusters in Guangdong and Zhejiang provinces compress production lead times for global brands.
Market Restraints
- ABS Resin Volatility:Petrochemical feedstock fluctuations for acrylonitrile-butadiene-styrene create margin compression for mid-market hard-shell producers.
- Aluminum Supply Concentration:Premium aluminum shell production depends on a limited supplier base in Germany and Japan, creating bottleneck risk for heritage craft positioning.
- REACH Chemical Compliance:ECHA restrictions on phthalate plasticizers and heavy metal pigments in coatings force reformulation cycles that extend product development timelines.
Strategic Opportunities
- India Mass-Market Penetration:Underdeveloped organized retail infrastructure in tier-two and tier-three cities creates whitespace for distribution-first entrants with localized price positioning.
- EU261 Passenger Rights Tailwind:Compensation frameworks for checked baggage mishandling incentivize cabin-compliant sizing, directly expanding addressable demand for sub-55-liter formats.
- RFID-Enabled Tracking Convergence:Integration of embedded luggage tracking with airline mobile applications opens subscription revenue streams beyond hardware margins.
Industry Challenges
- Telescopic Handle Engineering Talent:Shortage of mechanical engineers with expertise in aircraft-grade aluminum tubing and polymer glide systems constrains in-house R&D scaling.
- Multi-Certification Timeline Compression:Simultaneous pursuit of FAA, EASA, and IATA dimensional compliance extends validation cycles for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trolley Bags Market |
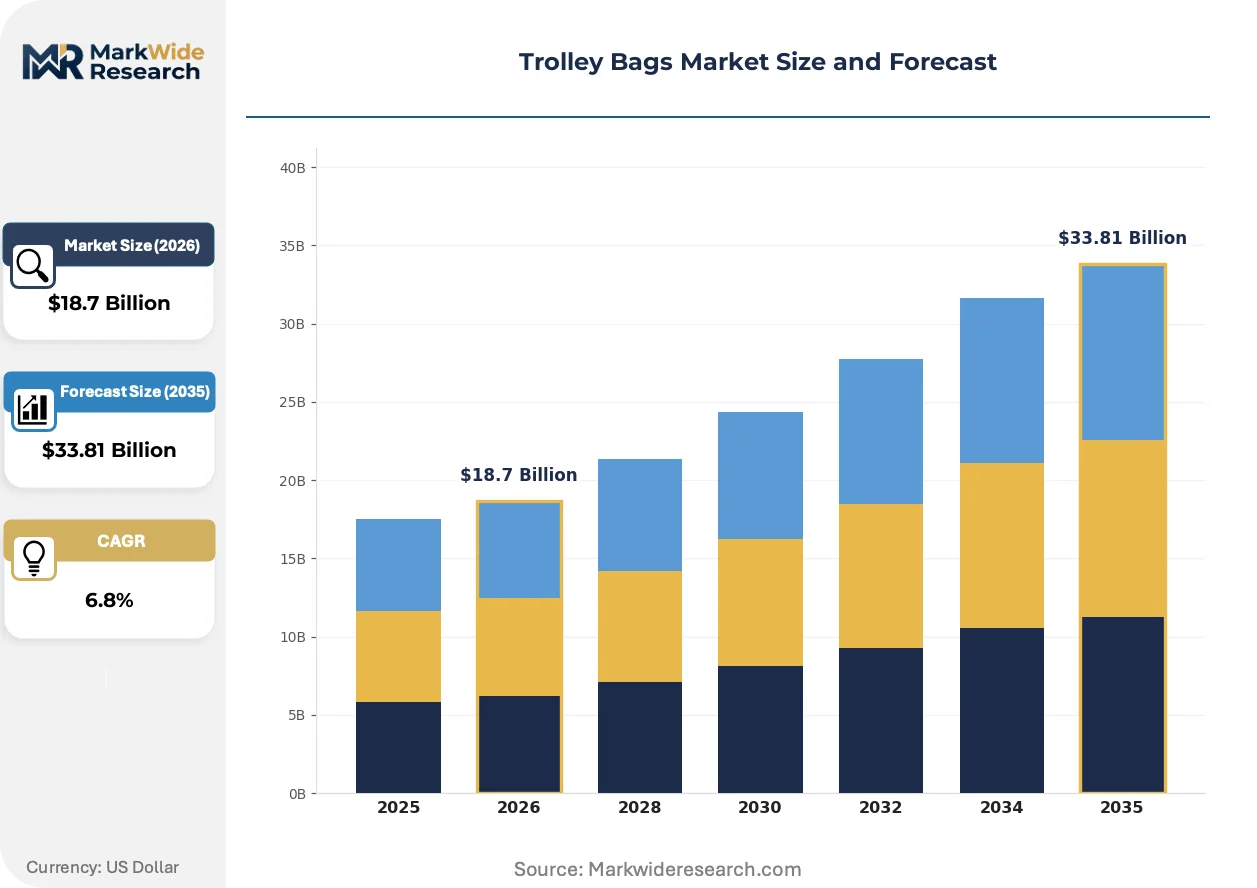
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Bags, Sports Bags, Cabin Bags, Luggage Sets Material: Polyester, Nylon, Leather, Canvas Size: Small, Medium, Large, Extra Large Usage: Leisure, Business, Adventure, Daily Commute |
| Companies Covered | Samsonite International S.A., Rimowa GmbH, TUMI Holdings, Inc., Delsey Paris, VIP Industries Ltd., American Tourister, Away, Victorinox AG, Briggs & Riley Travelware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trolley Bags Market Evolving Landscape
Material science breakthroughs and regulatory enforcement mechanisms are converging to reshape competitive positioning, with lightweight durability and dimensional precision emerging as the primary axes of differentiation.
Recycled polycarbonate blends are absorbing post-consumer waste streams from automotive and electronics sectors, transforming shell composition without sacrificing impact resistance. Premium brands in Germany and Japan are adopting these materials fastest, using sustainability credentials to defend margin position against mass-market polyester alternatives. The structural consequence is a bifurcation where recycled content is absorbing price premiums at the top tier while conventional virgin resins face commoditization pressure.
California Proposition 65 disclosure mandates are forcing explicit labeling of bisphenol-A and heavy metal traces in luggage coatings sold through US retail channels. Manufacturers serving the United States market must now maintain dual formulation inventories or reformulate globally to the stricter standard. Cabin bag categories see the most acute compliance pressure, as these products face the highest consumer scrutiny and retailer liability exposure.
Direct-to-consumer channel expansion is fragmenting traditional wholesale dependency, with specialized luggage brands building owned digital infrastructure to capture full margin and customer data. This pattern disrupts department store and duty-free retail, which historically controlled premium discovery and impulse purchase moments. The shift is most visible in urban China and South Korea, where mobile commerce penetration and influencer-driven discovery have compressed traditional retail's role in brand building.
Trolley Bags Market Segmentation
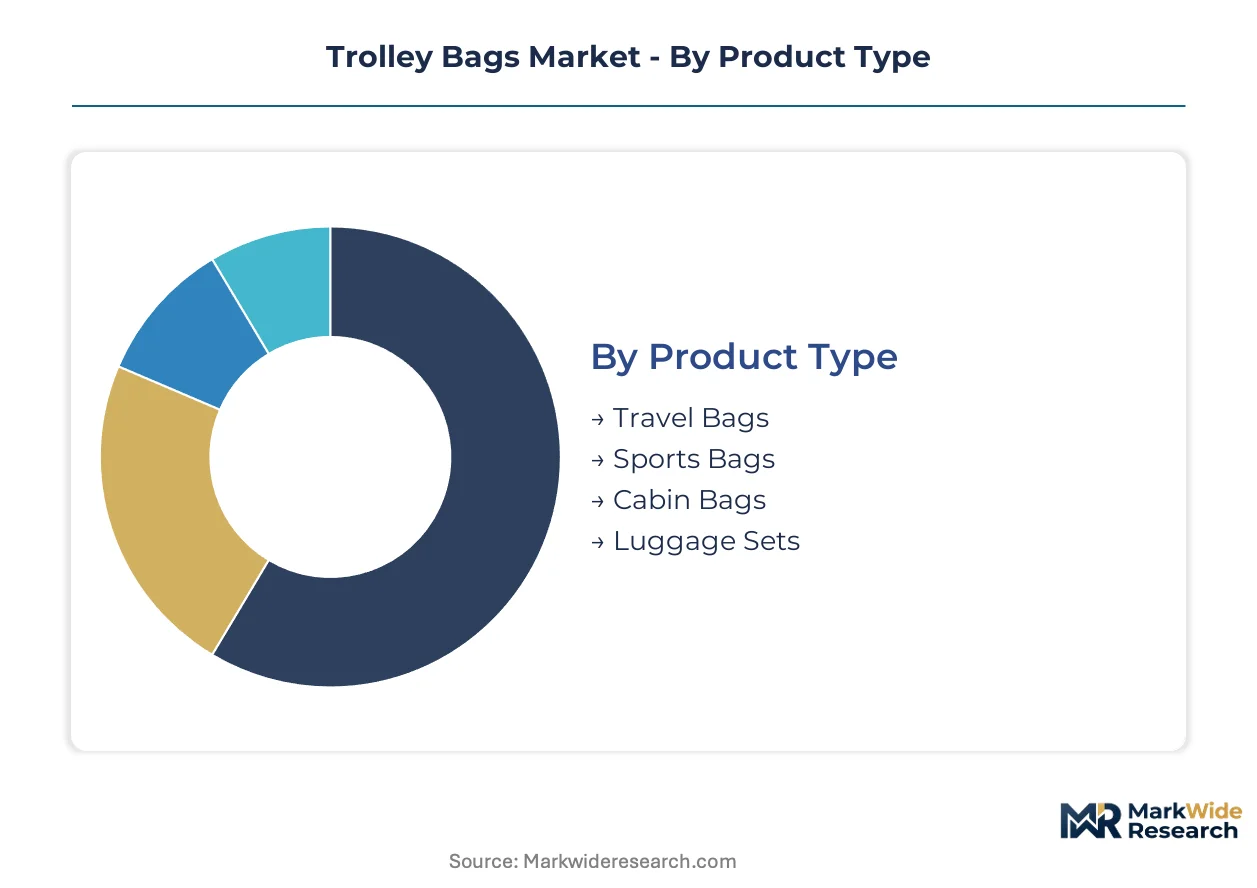
Segmentation in trolley bags reveals how airline enforcement and material science are splitting manufacturing investment across radically different cost structures. Each dimension—product format, shell composition, dimensional class, and trip purpose—carries distinct supply chain footprints and margin profiles that determine competitive viability.
Product Type:
Production tooling for hard-shell and soft-body formats concentrates in distinct regional clusters, with mold-making capabilities anchoring hard-shell output and textile finishing lines supporting soft-body assembly.
- Cabin Bags:Ultra-lightweight polycarbonate and hybrid textile shells engineered to sub-55-liter dimensional limits. FAA and EU261 enforcement compresses design tolerances, forcing rapid replacement cycles as travelers discard non-compliant legacy luggage.
- Travel Bags:Wheeled systems spanning checked and carry-on configurations, typically 60-120 liter capacity. Demand concentrates in Germany and United States retail channels where extended warranty programs sustain replacement-cycle revenue.
- Sports Bags:Reinforced compartments for equipment transport with abrasion-resistant base panels.
- Luggage Sets:Coordinated multi-piece assortments designed for family or extended-stay travel.
Cabin Bags absorb the bulk of installed capacity; Travel Bags is expanding most quickly.
Material:
Cost tier stratification runs from commodity synthetics through heritage natural materials, with recycled content premiums emerging as a distinct price floor at the top tier.
- Polyester:Woven textile substrate dominating mass-market manufacturing through dye-sub pattern flexibility and cost scalability. Guangdong and Zhejiang textile clusters compress production lead times for global brands serving price-sensitive segments.
- Polycarbonate:Co-extruded hard-shell resin enabling thinner-walled construction with retained impact resistance. Advances in recycled polycarbonate blends from automotive and electronics waste streams are absorbing post-consumer material fastest in Germany and Japan.
- Nylon:High-tenacity woven fabric with superior abrasion resistance for adventure and extended-use applications.
- Leather:Full-grain and corrected-grain hides occupying concentrated margin pools in executive business segments where longevity signals professional status.
- Canvas:Heavy cotton duck or waxed cotton fabric positioned in heritage and outdoor lifestyle positioning.
Polyester commands volume leadership; recycled polycarbonate blends are gaining share fastest.
Size:
Dimensional class determines airline compliance exposure and directly shapes material selection toward weight-minimization.
- Small:Sub-40-liter formats optimized for personal item allowances and single-day business trips.
- Medium:40-60 liter cabin-compliant range capturing the steepest expansion trajectory as FAA and EU261 enforcement tightens.
- Large:60-100 liter checked luggage formats where weight minimization matters less than structural durability.
- Extra Large:100+ liter expedition and relocation-scale capacity with reinforced frame systems.
Medium sizes absorb the bulk of innovation investment; Small formats are climbing the fastest.
Usage:
Customer type segmentation maps directly to distribution channel strategy and price positioning tolerance.
- Business:Professional travel formats emphasizing rapid-access compartments and device protection. Leather and aluminum shell demand concentrates here, with airline partnership programs in Germany and Japan anchoring premium positioning.
- Leisure:Family and vacation travel systems prioritizing capacity and value durability. Polyester and ABS resin formats dominate, with India mass-market penetration creating whitespace for distribution-first entrants in tier-two and tier-three cities.
- Adventure:Technical outdoor formats with reinforced chassis and weather-sealed construction.
- Daily Commute:Hybrid work-travel formats bridging professional and personal use cases.
Leisure absorbs the bulk of unit volume; Business commands the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing gravity concentrates in China while consumption anchors in Western Europe and North America, creating a transcontinental supply-demand divide that shapes logistics costs and brand positioning strategies.
United States
FAA carry-on enforcement at boarding gates accelerates replacement cycles for non-compliant legacy luggage. California Proposition 65 mandates explicit labeling of bisphenol-A traces in coatings sold through domestic retail channels. Los Angeles and New York Metro serve as primary distribution hubs where direct-to-consumer brands compress traditional department store margins.
Germany
EU261 passenger rights frameworks incentivize cabin-compliant sizing among business travelers seeking compensation protection. ECHA REACH restrictions on phthalate plasticizers force reformulation cycles for hard-shell coatings. Bavaria and North Rhine-Westphalia host premium aluminum shell fabrication clusters serving heritage craft positioning.
China
Guangdong and Zhejiang provinces integrate mold-making with textile finishing to compress production lead times for global brands. SAMR quality certification requirements and GB standards enforcement tighten export compliance thresholds. Shanghai and Shenzhen anchor e-commerce distribution infrastructure where mobile commerce penetration fragments traditional retail.
India
Tier-two and tier-three cities present whitespace for distribution-first entrants with localized price positioning. BIS quality standards and DGFT export incentives shape domestic manufacturing investment. Maharashtra and Gujarat concentrate mass-market polyester fabrication serving South Asian price-sensitive segments.
Japan
METI sustainability guidelines accelerate adoption of recycled polycarbonate blends from automotive waste streams. JIS standards certification creates premium tier differentiation for domestic and export markets. Kansai region hosts technical textile development clusters advancing hybrid shell innovation.
Trolley Bags Market Competitive Landscape
Top-tier vendors anchor premium aluminum and polycarbonate positioning, while mid-market specialists compete on material cost efficiency and distribution density. The vendor base stratifies across heritage craftsmanship, mass-market scale, and direct-to-consumer digital native archetypes. Dominant competitive moves include airline partnership program expansion and embedded RFID tracking service integration.
Among heritage European fabricators, Rimowa GmbH and Delsey Paris exemplify aluminum craftsmanship and polycarbonate innovation archetypes respectively. Samsonite International S.A. occupies a position spanning premium and mid-market tiers through global retail footprint density. VIP Industries Ltd. represents mass-market scale specialization with concentrated distribution in South Asian price-sensitive segments.
| Leading Market Players |
|---|
| Samsonite International S.A. |
| Rimowa GmbH |
| TUMI Holdings, Inc. |
| Delsey Paris |
| VIP Industries Ltd. |
| American Tourister |
| Away |
| Victorinox AG |
| Briggs & Riley Travelware |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Guangdong and Zhejiang provinces anchor hard-shell mold-making capacity, translating concentrated ownership into pricing discipline through captive tooling investments and long-term airline partnership contracts that resist spot-market volatility.
Pricing Analysis
Margin tightening in mid-market ABS resin tiers traces to petrochemical feedstock volatility and reformulation costs from ECHA REACH phthalate restrictions. Three-tier pricing structure across premium aluminum, standard polycarbonate, and economy polyester levels separates heritage craft positioning from mass-market scale. Price differentiation hinges on shell durability certification and airline partnership program status. Leisure travelers in India and Southeast Asia exhibit highest price sensitivity, while German and Japanese business segments absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Polycarbonate resin supply rests on German and Japanese specialty chemical producers, while aluminum shell fabrication concentrates in Bavaria and North Rhine-Westphalia heritage craft clusters. ABS resin draws from Chinese petrochemical complexes and Taiwan specialty polymer suppliers. Single-source vulnerability haunts premium aluminum tubing for telescopic handle systems. Distribution runs through Shanghai and Shenzhen e-commerce infrastructure, Los Angeles and New York Metro retail hubs, and Mumbai tier-two city wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum shell fabrication talent scarcity in Germany and Japan props pricing power for heritage-positioned vendors, constraining capacity expansion across premium tiers.
For Market Incumbents: Lock in airline partnership program exclusivity and embedded RFID tracking service subscriptions to defend against direct-to-consumer digital natives. Deepen backward integration into polycarbonate co-extrusion molding to capture resin margin compression. Prioritize ECHA REACH compliance certification investment to accelerate product development cycles versus reformulation-lagged competitors. For New Entrants and Emerging Players: Recycled polycarbonate blend innovation from automotive waste streams offers technology-first wedge into Germany and Japan sustainability-premium segments. Target India tier-two and tier-three city whitespace with localized price positioning below VIP Industries Ltd. mass-market density. Deploy influencer-driven mobile commerce discovery in South Korea and urban China to compress traditional department store gatekeeper roles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market polycarbonate specialists with mold-making captive capacity in Guangdong province. Long-term viability centers on dimensional precision engineering talent scarcity and airline compliance certification moats. Watch FAA carry-on enforcement intensity and EU261 compensation claim velocity as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Airline Partnership Program Expansion | Samsonite and Rimowa leverage Lufthansa and ANA co-branding to anchor premium discovery. |
| RFID-Enabled Tracking Integration | Embedded luggage tags with airline mobile apps open subscription revenue beyond hardware margins. |
| Recycled Polycarbonate Adoption | German and Japanese vendors absorb automotive waste streams to defend sustainability price premiums. |
| Direct-to-Consumer Channel Buildout | Away and specialized brands capture full margin and customer data, compressing department store roles. |
| India Distribution Network Penetration | Tier-two and tier-three city whitespace rewards localized price positioning below organized retail density. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving airline procurement officers, luggage brand supply chain directors, retail category buyers, and telescopic handle engineering specialists. Secondary sources included IATA baggage policy databases, ECHA REACH substance restriction updates, FAA enforcement guidance documents, and China SAMR quality certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Granularity-level modeling deployed product type, material composition, dimensional class, and trip purpose segmentation across the projection horizon. CAGRs derived from replacement cycle analysis, airline policy enforcement trajectory, and material science innovation diffusion curves. Forecast inputs incorporated polycarbonate resin price volatility indices and aluminum supply concentration risk assessments.
Several conditions sit outside the modeled scope, including pandemic-scale travel demand collapse, sudden airline baggage fee restructuring, and raw material trade war tariff imposition. Forecasts assume documented airline dimensional enforcement continuity and REACH chemical compliance threshold stability. A small set of named triggers warrants ongoing watch: FAA boarding-gate measurement technology deployment, EU261 compensation claim volume acceleration, and China dual carbon policy tightening on petrochemical feedstocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Global Premium Luggage Market
Luggage
Travel and Business Bags Market
Luggage
Smart Carry-On Luggage Market
Luggage
United States Sports Bags Market
Luggage
Smart Bags Market
Luggage
School Bags Market
Luggage
Travel Bag Market
Luggage
Sewing Bags Market
Luggage
Camera Bag Market
Luggage
Second Hand Bag Market
Luggage
Kids Backpack Market
Luggage
Backpack Market
Luggage
Laptop Messenger Bags Market
Luggage
Trunks Market
Luggage
Laptop Carry Case Market
Luggage
Global Outdoor Sports Luggage Market