
 Global Smart Luggage and Tracking Technologies Market | 2026-2036
Global Smart Luggage and Tracking Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Luggage and Tracking Technologies Market Foresight
Modular tracking bundles that pair GPS units with electronic locks is consolidating buyer choice around integrated security solutions rather than standalone devices. Samsonite International S.A. leverages its manufacturing scale to anchor premium smart suitcase production across Asian supply chains. Away Travel Inc. differentiates through direct-to-consumer channel control and minimalist hardware-software integration.
Smart luggage and tracking technologies encompass connected baggage systems incorporating GPS receivers, Bluetooth Low Energy beacons, RFID inlays, and rechargeable lithium power banks, typically operating at 2.4 GHz ISM bands with location accuracy down to one meter for UWB implementations; these systems serve commercial aviation and logistics operators seeking real-time asset visibility and theft prevention. GPS Trackers lead product type revenue as airline baggage mishandling liabilities drive carrier-funded deployments, while UWB technology captures the fastest expansion as precision indoor positioning replaces legacy Bluetooth proximity alerts in hub airports. Bluetooth Trackers occupy a mature, margin-compressed tier where consumer price sensitivity limits premiumization.
The FAA governs lithium-ion battery configurations in checked and carry-on smart luggage, effectively banning non-removable power cells from cargo holds and forcing hardware redesigns toward detachable battery architectures. EASA and China's CAAC have issued parallel technical directives, creating a fragmented but converging compliance baseline for manufacturers selling across jurisdictions. Stakeholders must monitor whether ICAO harmonizes these standards or perpetuates the current patchwork of national exemptions.
Market Dynamics
Airlines are consolidating baggage tracking mandates around RFID and UWB standards, forcing hardware vendors to redesign for detachable battery architectures while precision positioning replaces legacy proximity alerts.
Growth Catalysts
- RFID Mandates:IATA Resolution 753 requires member carriers to track every bag at key journey points, creating carrier-funded procurement cycles for integrated tracking hardware.
- China:Domestic carriers including China Eastern and China Southern are deploying UWB-enabled smart luggage systems at scale, establishing the country as the primary volume demand center.
- Real-Time Asset Visibility:Logistics operators now treat baggage as trackable inventory, extending smart luggage adoption beyond aviation into intermodal freight corridors.
Market Restraints
- Lithium Supply Concentration:Cobalt and lithium processing concentrates in the Democratic Republic of Congo and China's Jiangxi province, exposing battery costs to geopolitical friction.
- FAA Cargo Restrictions:Non-removable power cells face effective bans from checked baggage holds, forcing costly hardware redesigns toward modular battery architectures.
- Bluetooth Saturation:Consumer-grade BLE trackers face margin compression as commodity hardware from Shenzhen manufacturers floods direct-to-consumer channels.
Strategic Opportunities
- India:Underpenetrated domestic aviation infrastructure and rising middle-class air travel create first-mover advantages for UWB-integrated luggage systems.
- EU AI Act:Compliance requirements for automated baggage handling systems create premium tiers for manufacturers embedding explainable positioning algorithms.
- Direct-to-Consumer Channels:Bypassing airline procurement committees via subscription-based tracking services unlocks recurring revenue models outside hardware margins.
Industry Challenges
- Cross-Border Certification:Divergent FAA, EASA, and CAAC lithium battery standards force parallel testing tracks, extending product launch timelines by 8-14 months.
- Legacy System Integration:Hub airports operate decades-old baggage handling infrastructure that lacks API compatibility with modern UWB beacon networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Luggage and Tracking Technologies Market |
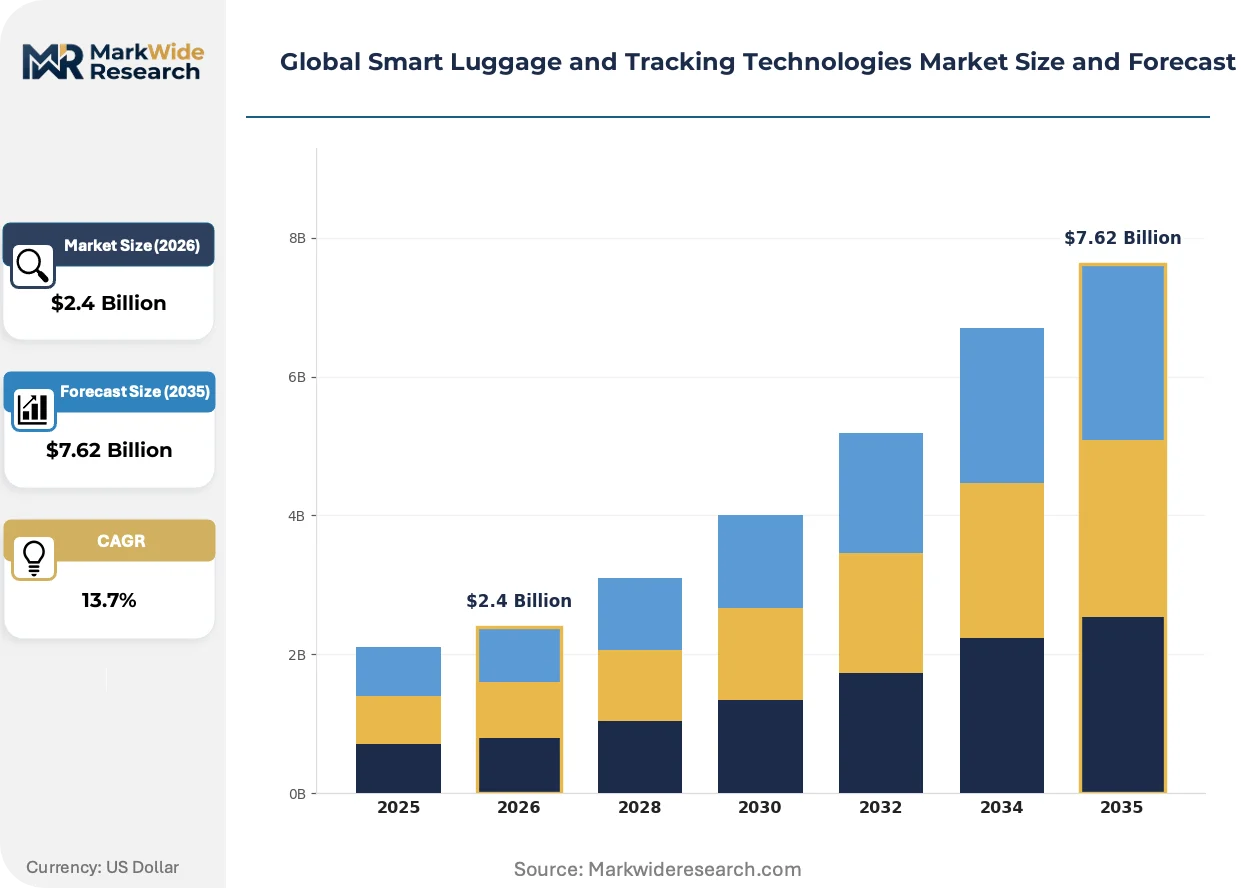
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Suitcases, GPS Trackers, RFID Tags, Bluetooth Trackers, Electronic Locks Technology: GPS, Bluetooth Low Energy, RFID, NFC, Cellular Networks, UWB Application: Travel Agencies, Airlines, Hospitality Chains, Courier Services, Rental Services End User: Business Travelers, Leisure Travelers, Corporate Fleet Managers, Tour Operators |
| Companies Covered | Delsey Paris, Bluesmart, Inc., Samsonite International S.A., ForwardX Robotics, Travelpro International, Inc., Away Travel Inc., Rimowa, Samsara Luggage, Inc., TUMI Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Luggage and Tracking Technologies Market Shifts & Advancements
Precision positioning technologies are compressing the accuracy gap between outdoor GPS and indoor navigation, while regulatory fragmentation around power sources forces modular design architectures.
UWB chipsets operating at 6.5 GHz are overtaking legacy Bluetooth proximity detection in hub airport deployments. Major carriers in Germany and the Netherlands are retrofitting baggage halls with UWB anchor networks capable of one-meter location accuracy. This precision is compressing mishandling liability costs and enabling automated sortation without barcode scanning.
The EU AI Act's risk classification framework now covers automated baggage handling systems with decision-making autonomy. Manufacturers selling into European hub airports must document algorithmic transparency for luggage routing decisions. Systems lacking explainable positioning logic face exclusion from procurement shortlists at airports in France and Germany.
Enterprise procurement teams at logistics operators now unbundle hardware from connectivity subscriptions, treating tracking devices as commoditized endpoints while negotiating multi-year data service contracts separately. This pattern is most visible in the United States, where freight forwarders prioritize API-accessible location feeds over branded hardware specifications.
Global Smart Luggage and Tracking Technologies Market Segmentation
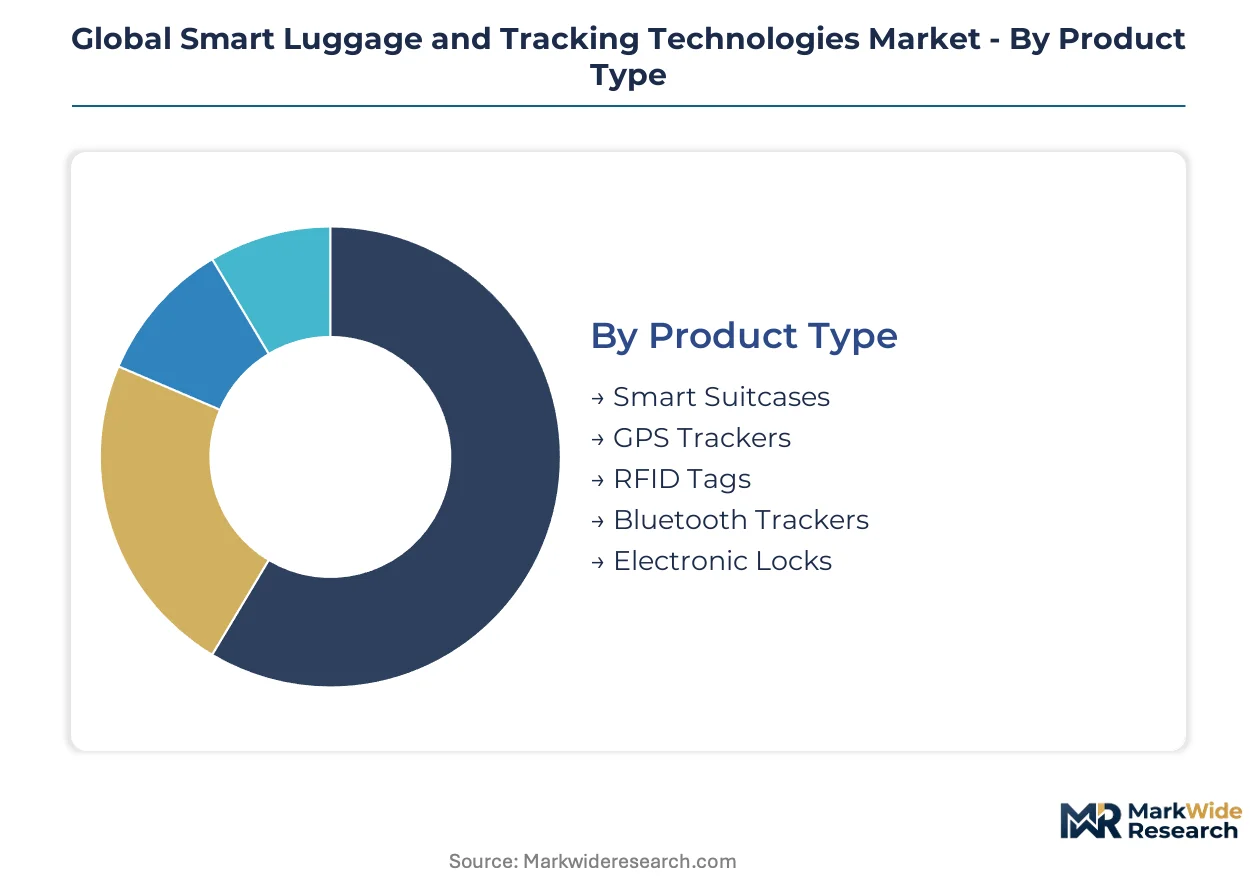
Segmentation in smart luggage and tracking technologies reveals how procurement authority splits between carrier-funded enterprise deployments and traveler-purchased consumer hardware. Each dimension carries distinct margin profiles, certification requirements, and replacement cycles that reshape vendor go-to-market strategies.
Product Type:
Buyers differentiate by who controls the procurement decision—airlines funding fleet-wide tracking infrastructure versus individual travelers purchasing retail luggage.
- GPS Trackers:Standalone satellite-receiving modules with embedded SIM cards deliver meter-scale outdoor positioning. Airline baggage mishandling liability programs in the United States and Germany are driving carrier-funded bulk deployments for high-value cargo routes.
- Smart Suitcases:Integrated hard-shell luggage incorporating GPS receivers, electronic locks, and rechargeable power banks. China Eastern and China Southern are procuring UWB-enabled variants at scale for domestic hub operations, establishing detachable battery architectures as the compliance baseline.
- RFID Tags:Passive inlay stickers operating at UHF frequencies for automated baggage sortation. IATA Resolution 753 mandates are accelerating airline adoption across European trunk routes.
- Bluetooth Trackers:Low-cost BLE beacons for proximity-based location alerts. Shenzhen manufacturing clusters have compressed retail margins to commodity levels in North American direct-to-consumer channels.
- Electronic Locks:TSA-compliant biometric or PIN-activated locking mechanisms. Hospitality chains in Dubai and Singapore are bundling these with premium luggage rental programs.
GPS Trackers lead volumes today; Smart Suitcases are gaining share fastest.
Technology:
Technology selection tracks the precision-versus-cost tradeoff that hub airports face when retrofitting legacy baggage halls.
- UWB:Ultra-wideband chipsets at 6.5 GHz achieve one-meter indoor accuracy. Schiphol Airport and Frankfurt Airport anchor are retrofitting anchor networks to enable automated sortation without barcode scanning.
- RFID:UHF inlays at 860-960 MHz for automated tunnel scanning. The technology dominates baggage handling infrastructure at London Heathrow and Paris Charles de Gaulle under carrier compliance mandates.
- GPS:Satellite-based outdoor positioning using L1/L5 bands. Courier services across Brazil and India rely on GPS for intermodal freight corridor visibility.
- Bluetooth Low Energy:2.4 GHz proximity beacons with 50-meter range. Consumer luggage brands in Japan and South Korea embed BLE for smartphone-tethered anti-theft alerts.
- NFC:Near-field communication for tap-to-unlock luggage authentication. Tour operators in Italy and Spain are piloting NFC-integrated rental systems.
- Cellular Networks:LTE-M and NB-IoT modules for wide-area tracking without smartphone dependency. Logistics operators in Australia and Canada specify cellular for remote route segments.
RFID anchors installed base; UWB is climbing the fastest.
Application:
Application segmentation maps to who owns the traveler relationship and captures the data monetization opportunity.
- Airlines:Fleet-wide baggage tracking mandates under IATA Resolution 753. Delta Air Lines and Lufthansa Group are funding integrated RFID-UWB hardware procurements.
- Courier Services:Last-mile parcel visibility for high-value shipments. DHL Express and FedEx operations in the Netherlands and Singapore specify multi-technology trackers.
- Travel Agencies:Commission-based luggage rental and insurance bundling. Thomas Cook's successor entities in the United Kingdom are testing subscription tracking services.
- Hospitality Chains:Guest luggage storage and concierge tracking. Marriott properties in Dubai and Hilton clusters in Tokyo are piloting UWB-enabled bell services.
- Rental Services:Short-term luggage and equipment hire with embedded recovery systems. Startups in Berlin and San Francisco are building hardware-as-a-service models.
Airlines dominate procurement value; Courier Services show steepest expansion trajectory.
End User:
End user categories split by travel frequency, expense account access, and sensitivity to baggage loss consequences.
- Business Travelers:High-frequency flyers with employer-funded luggage and tracking subscriptions. Corporate travel policies at Siemens and SAP specify smart luggage for intercontinental routes.
- Leisure Travelers:Price-sensitive vacationers purchasing retail trackers. Amazon and direct-to-consumer brands in the United States capture this segment through seasonal promotional cycles.
- Corporate Fleet Managers:Enterprise procurement of pooled luggage assets for rotating staff. Consulting firms in London and New York maintain shared smart luggage inventories.
- Tour Operators:Group travel coordinators managing collective baggage logistics. Intrepid Travel and G Adventures operations in Australia specify RFID-tagged group luggage.
Business Travelers anchor premium pricing; Corporate Fleet Managers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart luggage industry traces its commercial origins to early GPS-integrated prototypes developed in United States aviation corridors during the 2010s, with subsequent scaling concentrated in Asian manufacturing clusters and European hub airport retrofits.
United States
FAA lithium battery regulations and carrier mishandling liability programs drive enterprise procurement of detachable battery architectures. The FAA mandates non-removable power cells face effective bans from checked baggage holds. Dallas-Fort Worth and Atlanta anchor major airline procurement operations where Delta Air Lines funds integrated RFID-UWB hardware deployments.
China
Domestic carriers deploy UWB-enabled smart luggage systems at scale, establishing the country as the primary volume demand center. CAAC technical directives on lithium battery configurations parallel FAA standards, forcing modular design compliance. Shenzhen manufacturing clusters produce commodity BLE trackers that compress retail margins across North American direct-to-consumer channels.
Germany
Frankfurt Airport and Munich anchor UWB anchor network retrofits enabling automated baggage sortation without barcode scanning. The EU AI Act's risk classification framework covers automated baggage handling systems, requiring algorithmic transparency documentation. Bavaria-based logistics operators now unbundle hardware from connectivity subscriptions, prioritizing API-accessible location feeds.
Netherlands
Schiphol Airport leads European hub deployment of precision indoor positioning infrastructure. EASA technical directives create fragmented but converging compliance baselines for cross-border manufacturers. Amsterdam's logistics corridor hosts freight forwarders specifying multi-technology trackers for high-value cargo routes.
India
Underpenetrated domestic aviation infrastructure and rising middle-class air travel create first-mover advantages for UWB-integrated luggage systems. The Bureau of Indian Standards issues parallel technical guidelines on battery safety. Mumbai and Delhi-NCR clusters attract testing facilities for modular battery architectures targeting tropical climate resilience.
Global Smart Luggage and Tracking Technologies Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and channel control dimensions, with integrated hardware-software vendors commanding pricing power over Shenzhen-based component assemblers. The vendor base organizes into three strategic archetypes: legacy luggage manufacturers retrofitting connectivity modules, direct-to-consumer brands controlling end-user relationships, and robotics specialists automating baggage handling infrastructure. Dominant competitive moves include backward integration into UWB chipset sourcing and subscription-based tracking service launches that decouple recurring revenue from hardware margins.
Within the legacy luggage tier, Samsonite International S.A. and Delsey Paris occupy positions as scale-driven manufacturers with established airline procurement relationships. Away Travel Inc. exemplifies the direct-to-consumer archetype through channel control and minimalist integration approaches. ForwardX Robotics represents automation specialists targeting hub airport infrastructure retrofits rather than traveler-purchased hardware.
| Leading Market Players |
|---|
| Delsey Paris |
| Bluesmart, Inc. |
| Samsonite International S.A. |
| ForwardX Robotics |
| Travelpro International, Inc. |
| Away Travel Inc. |
| Rimowa |
| Samsara Luggage, Inc. |
| TUMI Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up luggage specialists anchor pricing discipline through captive battery sourcing from Jiangxi province, while Shenzhen contract manufacturers compress retail margins through commoditized BLE tracker exports. This ownership pattern concentrates supply-side bargaining power with carriers funding enterprise UWB deployments, forcing consumer brands toward subscription monetization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified detachable battery systems from uncertified cargo-banned alternatives from entry-tier Shenzhen assemblers. Price differentiation hinges on certification grade and after-sales service bundling, with EASA and CAAC compliance premiums widening spreads. Cost compression in the Bluetooth tier intensifies because Shenzhen manufacturing clusters flood direct-to-consumer channels. Leisure travelers purchasing retail trackers exhibit highest price sensitivity, while corporate fleet managers at Siemens and SAP absorb premium UWB-integrated luggage without volume negotiation.
Supply Chain Analysis
Freight costs from Jiangxi lithium processing centers to Dongguan assembly plants have prompted modular battery architecture redesigns that minimize hazardous material air-cargo surcharges. Manufacturing concentrates in China, Vietnam, and Mexico, with UWB chipset fabrication drawing from Taiwan and South Korea. Raw material dependencies span cobalt from the Democratic Republic of Congo, lithium carbonate from Chile, and rare earth magnets from China's Inner Mongolia region. Single-source vulnerability in cobalt supply exposes battery costs to geopolitical friction. Distribution runs through airline procurement committees for enterprise volumes and Amazon-direct channels for retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where carrier-funded UWB mandates and EU AI Act compliance requirements shift procurement toward premium specifications with embedded explainable positioning algorithms.
For Market Incumbents: Anticipate margin compression from Shenzhen BLE tracker commoditization by deepening backward integration into UWB chipset sourcing and securing EASA certification ahead of EU AI Act enforcement. Incumbents must defend position through captive supply of detachable battery architectures and API-accessible location feed subscriptions that decouple recurring revenue from hardware margins. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription tracking services targeting underpenetrated Indian domestic aviation infrastructure, where rising middle-class air travel creates first-mover advantages for UWB-integrated luggage systems without legacy airline procurement committee barriers. The most penetrable segment combines hospitality chain bell services with rental-as-a-service hardware models in Dubai and Singapore. For Investors and Strategic Acquirers: Logistics automation specialists are the most active acquirer in this space, seeking robotics capabilities for hub airport baggage handling retrofits. Long-term viability over the coming decade hinges on software-defined positioning algorithms rather than hardware endpoints. Target acquisition profile centers on UWB anchor network operators with Schiphol or Frankfurt Airport deployment credentials. The signal to watch is ICAO harmonization of lithium battery standards, which would compress cross-border certification timelines and unlock volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| UWB Chipset Backward Integration | Samsonite-scale manufacturers secure supply priority from Taiwan foundries amid aviation mandate acceleration. |
| Detachable Battery Architecture Redesign | FAA-compliant modular systems unlock checked baggage revenue previously banned under cargo restrictions. |
| API-First Tracking Subscription Launch | Freight forwarders in Amsterdam and Singapore prioritize data service contracts over branded hardware specifications. |
| EU AI Act Compliance Certification | Explainable positioning algorithms secure procurement shortlists at Frankfurt and Charles de Gaulle hub airports. |
| India Market Direct Entry | Mumbai and Delhi-NCR testing facilities enable tropical climate resilience validation for UWB-integrated systems. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with airline procurement directors, logistics operator technology leads, UWB chipset engineering teams, and hospitality chain operations managers. Secondary validation draws from FAA technical directive filings, EASA safety publications, CAAC regulatory notices, IATA Resolution 753 implementation reports, and customs trade data for lithium battery exports. Bottom-up segment sizing triangulates against top-down aviation passenger growth projections.
Granularity-level modeling disaggregates revenue across product type, technology protocol, application sector, and end-user archetype throughout the forecast period. The analytical framework applies technology adoption S-curves to UWB deployment timelines and carrier mandate compliance schedules. CAGRs derive from segment-level volume trajectories weighted by average selling price evolution across certification tiers. Industry-specific inputs include IATA baggage mishandling rate trends and lithium carbonate price indices from Jiangxi spot markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ICAO standardization delays or cobalt supply disruptions from the Democratic Republic of Congo. Stakeholders should weight assumptions against their own operating context, particularly regarding regulatory fragmentation tolerance and battery chemistry sourcing strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Global Premium Luggage Market
Luggage
Trunks Market
Luggage
Trolley Bags Market
Luggage
Bags Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Laptop Messenger Bags Market
Luggage
Travel Bag Market
Luggage
School Bags Market
Luggage
Laptop Carry Case Market
Luggage
United States Sports Bags Market
Luggage
Sports Luggage Market
Luggage
Kids Backpack Market
Luggage
Smart Bags Market
Luggage
Travel and Business Bags Market
Luggage
Sewing Bags Market
Luggage
Global Luggage Market