
 Kids Backpack Market | 2026-2036
Kids Backpack Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Backpack Market Foresight
CPSIA third-party testing certification is reorganizing supplier tiers, forcing smaller factories to absorb compliance costs or exit the juvenile products category. JanSport leverages its domestic U.S. manufacturing relationships to sustain faster turnaround on certified batches. Nike Inc. competes through performance-oriented material science, while Adidas AG anchors its position with school-sports crossover designs that navigate seasonal demand swings.
A kids backpack is a load-bearing container engineered for children, typically constructed with padded shoulder straps, sternum stabilizers, and water-resistant nylon or polyester shell fabrics rated between 300D and 600D denier, designed to distribute weight across developing musculoskeletal frames during daily school transport. Daypack configurations dominate volume sales for elementary-aged users, where margin pools concentrate in licensed character collaborations and ergonomic premium tiers. Polyester material grades lead manufacturing throughput due to dye-sublimation compatibility and cost efficiency, though canvas segments are gaining traction among sustainability-focused buyer cohorts seeking natural fiber alternatives.
The U.S. Consumer Product Safety Commission enforces CPSIA lead content and phthalate limits, while the European Chemicals Agency administers REACH SVHC restrictions that directly constrain zipper coatings, dyes, and synthetic fabric treatments used in children's bags. China's State Administration for Market Regulation applies GB standards for juvenile product labeling and mechanical safety, creating a three-jurisdiction compliance burden for brands sourcing across Asia. Stakeholders must monitor evolving chemical restriction lists and decide whether to regionalize supply chains or pursue unified global certification protocols that cover the strictest denominator.
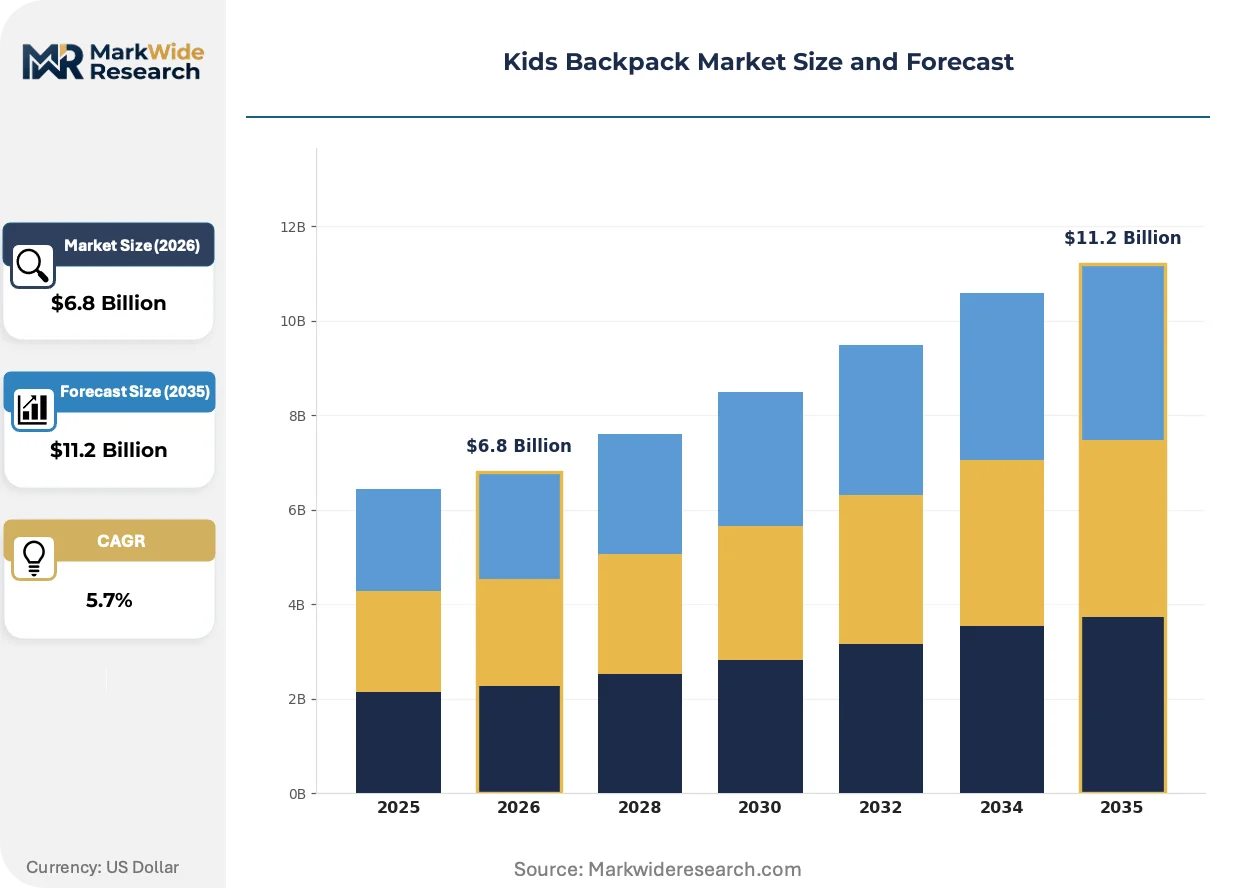
Market Dynamics
REACH SVHC restrictions and CPSIA third-party testing mandates are compressing supplier margins while concentrating production among vertically integrated manufacturers capable of absorbing multi-jurisdiction compliance costs.
Growth Catalysts
- Elementary enrollment expansion:Developing markets are extending compulsory education coverage, creating sustained replacement demand for age-appropriate ergonomic designs with sternum stabilizers and load-distribution frames.
- REACH compliance acceleration:The European Chemicals Agency's expanding restricted substance list is driving R&D investment in water-based zipper coatings and phthalate-free synthetic treatments, favoring technical specialists over commodity assemblers.
- Dye-sublimation printing:Polyester shell compatibility with high-definition character licensing is unlocking premium tier pricing for IP-holding brands in daypack configurations.
Market Restraints
- Petrochemical input volatility:Nylon and polyester feedstock costs fluctuate with crude oil derivatives, compressing margin pools for manufacturers locked into annual retail pricing contracts.
- Zhejiang-Guangdong supply concentration:Over 60 percent of global OEM capacity sits within 200 kilometers of Ningbo and Dongguan, exposing brands to concentrated weather, labor, or logistics disruptions.
- Canvas fiber performance ceiling:Natural fiber alternatives lack the tear strength and water resistance of 600D synthetic weaves, limiting their penetration beyond sustainability-focused urban buyer cohorts.
Strategic Opportunities
- India's organized retail penetration:Modern trade and e-commerce platforms are displacing traditional kirana distribution for school supplies in tier-2 and tier-3 cities, creating branded backpack access points.
- EU Green Deal alignment:The circular economy action plan's textile waste directives will reward take-back program infrastructure and recycled polyester sourcing with preferential retail placement.
- Smart textile convergence:Integration of RFID tracking modules and LED safety strips with conventional shell fabrics is opening price-insensitive urban parent segments.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous GB standard, CPSIA, and REACH testing creates 12-16 week product launch delays that misalign with seasonal back-to-school windows.
- Ergonomic design talent scarcity:Biomechanical engineering expertise for pediatric load distribution remains concentrated among orthopedic equipment specialists, not traditional bag manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Backpack Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolling, Daypack, Hydration Pack, Messenger Material: Nylon, Polyester, Canvas, Leather Size: Small, Medium, Large, Extra Large Age Group: Toddlers, Preschoolers, Elementary, Middle School |
| Companies Covered | JanSport, Herschel Supply Co., Nike Inc., Under Armour, Samsonite International S.A., Adidas AG, Puma SE, L.L. Bean, VIP Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Backpack Market Shifts & Advancements
Material substitution, chemical compliance automation, and direct-to-parent digital channels are restructuring how backpacks are engineered, certified, and sold to end users.
Recycled polyethylene terephthalate (rPET) filament yarn is supplanting virgin polyester in shell fabric production. Premium-tier brands in Germany and Scandinavia are mandating 100 percent recycled content for licensed collaborations. This shift is compressing price premiums for sustainability claims as rPET scales toward cost parity with conventional feedstock.
REACH's SCIP database requirements for article-level substance disclosure are forcing suppliers to digitize chemical inventory tracking. The European Chemicals Agency's enforcement is pushing mid-tier manufacturers toward unified ERP systems that auto-generate compliance documentation. Daypack suppliers serving EU retailers are absorbing software implementation costs to maintain shelf access.
Parent purchasing for elementary-aged children is migrating from seasonal retail trips to subscription-based replacement programs. Direct-to-consumer platforms in the United States are bundling size-exchange guarantees with annual delivery cycles. This behavior is most visible among dual-income households in coastal metropolitan areas seeking to eliminate last-minute back-to-school logistics friction.
Kids Backpack Market Segmentation
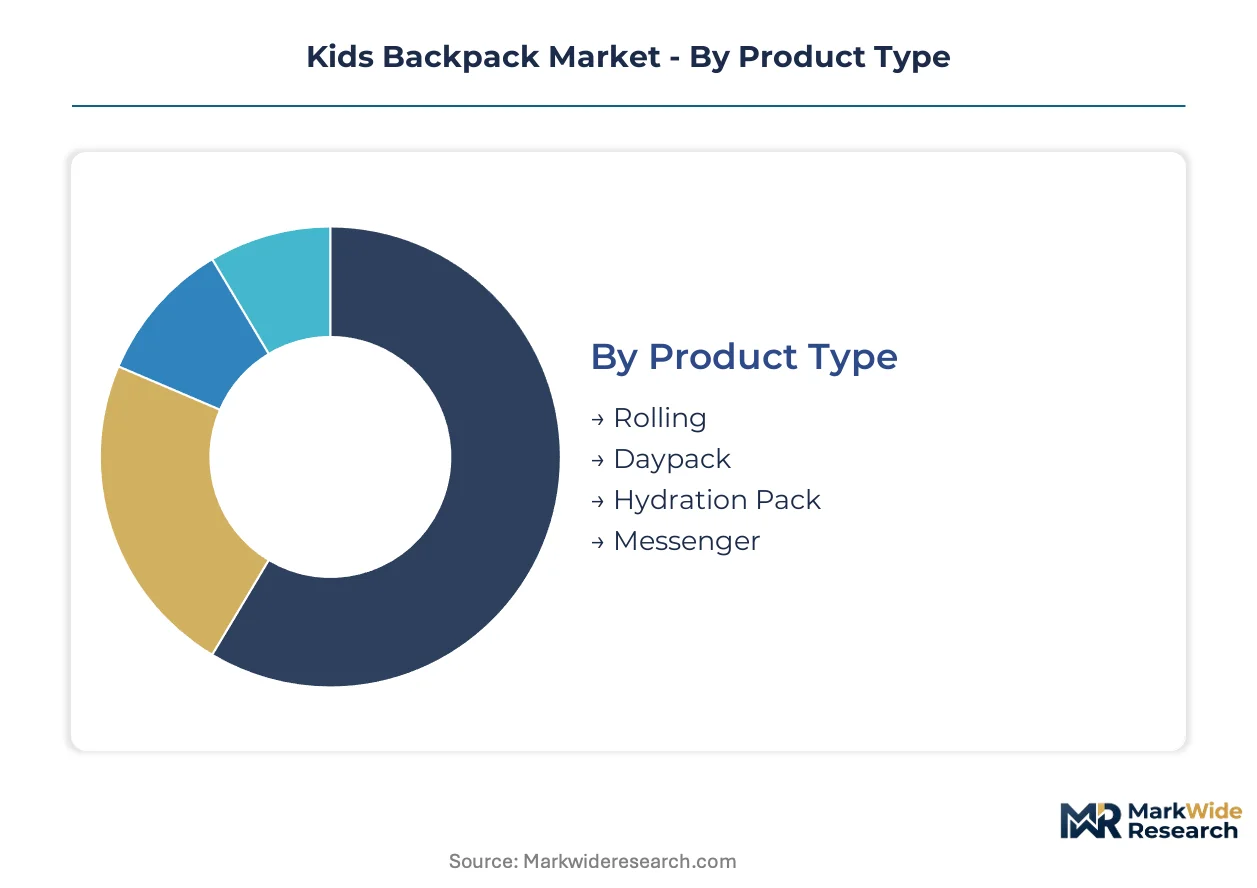
Margin concentration in kids backpacks varies sharply across product configurations and material grades. Licensed character collaborations and ergonomic premium tiers command pricing power, while commodity daypack segments compete on volume throughput and dye-sublimation compatibility.
Product Type:
Margin pools concentrate in daypack configurations for elementary-aged users, where licensed IP collaborations and ergonomic premium tiers extract maximum value per unit.
- Daypack:Standard two-strap configurations dominate elementary school transport. Demand clusters in China and the United States for licensed character collaborations that unlock premium pricing through dye-sublimation-compatible polyester shells.
- Rolling:Wheeled upright designs with telescoping handles address load-weight concerns for middle school textbook volumes. Penetration is accelerating in urban Japan and South Korea where walking distances to transit exceed 800 meters.
- Hydration Pack:Integrated reservoir systems target extracurricular sports use. Niche positioning limits volume but sustains margin through technical fabric specifications.
- Messenger:Single-strap crossbody designs appeal to style-conscious middle school demographics. Canvas and synthetic hybrid constructions dominate this aesthetic-driven segment.
Daypack holds installed capacity. Rolling is rotating up the share rankings.
Material:
Volume throughput favors synthetic weaves, though sustainability premiums are shifting procurement patterns toward recycled feedstocks.
- Polyester:300D to 600D denier grades lead global manufacturing throughput due to dye-sublimation compatibility and cost efficiency. REACH SVHC compliance is accelerating water-based coating R&D among EU-facing suppliers.
- Nylon:Higher tear strength and abrasion resistance position this material for premium outdoor-oriented daypacks. Petrochemical input volatility compresses margins for manufacturers locked into annual retail contracts.
- Canvas:Natural fiber alternatives gain traction among sustainability-focused urban buyer cohorts in Germany and Scandinavia. Performance ceilings on water resistance limit penetration beyond premium positioning.
- Leather:Genuine and synthetic variants occupy gift and ceremonial purchase occasions. Minimal volume share reflects durability concerns and animal welfare scrutiny in EU markets.
Polyester maintains dominant share. Canvas is climbing the fastest on sustainability credentialing.
Size:
Procurement specifications map directly to age-appropriate load-bearing limits and compulsory education stage transitions.
- Small:10-15 liter capacities serve preschool and early elementary users. CPSIA third-party testing requirements apply universally regardless of unit scale.
- Medium:16-20 liter configurations capture peak elementary enrollment expansion in developing markets. Ergonomic sternum stabilizers and load-distribution frames differentiate premium tiers.
- Large:21-25 liter volumes align with middle school textbook and device transport requirements. China and India show steepest demand acceleration as compulsory education extends.
- Extra Large:26+ liter capacities address specialized rolling configurations and multi-day excursion use. Niche positioning limits volume concentration.
Medium holds the volume anchor. Large is gaining share fastest on enrollment extension.
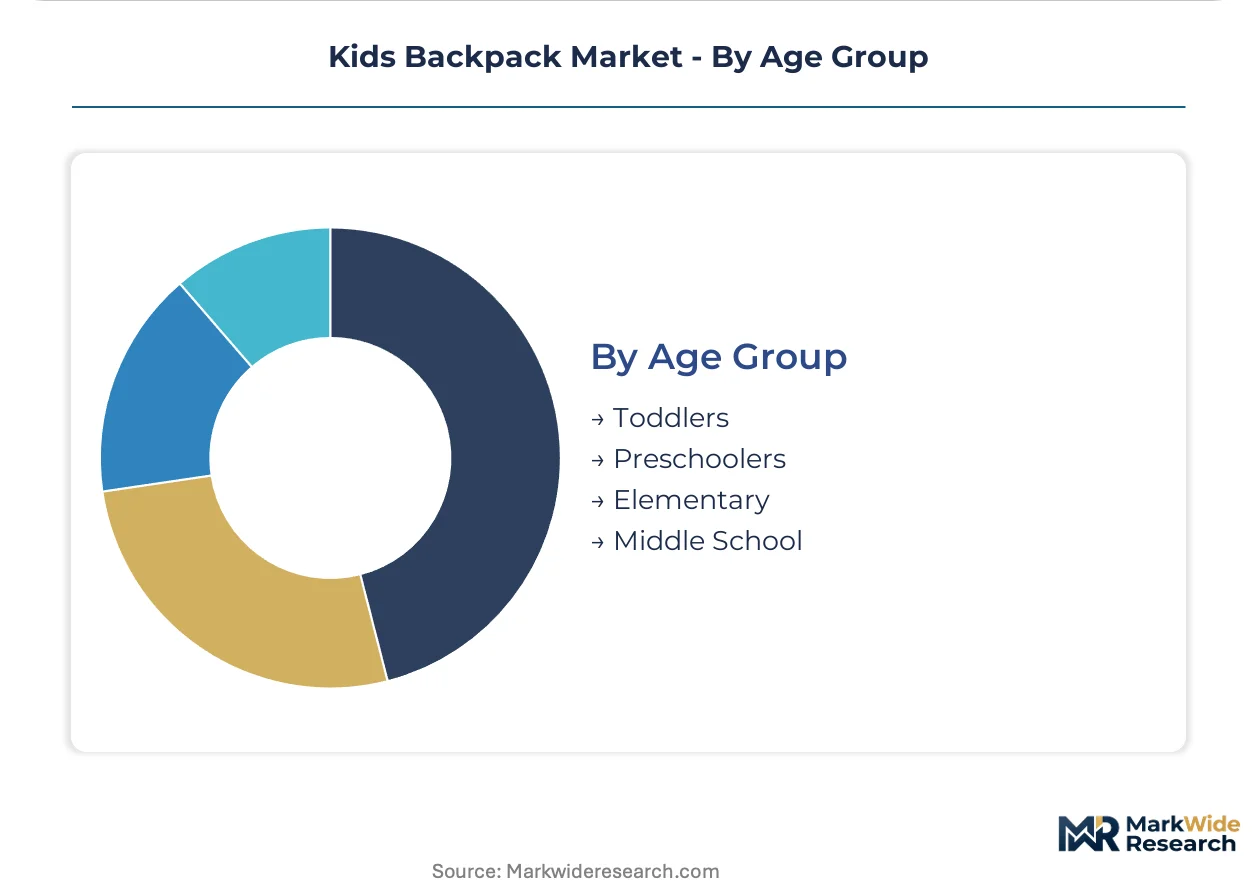
Age Group:
Replacement cycles and ergonomic design requirements diverge sharply across developmental stages.
- Elementary:Ages 6-11 drive sustained replacement demand as compulsory education expands in India, Indonesia, and Nigeria. Ergonomic frame engineering and licensed IP collaborations concentrate margin extraction here.
- Middle School:Ages 12-14 transition toward style-driven self-expression and heavier textbook loads. Sports crossover designs from athletic brands compete for share in this cohort.
- Preschoolers:Ages 3-5 represent gift-purchase occasions with lower price sensitivity. Safety certification and choking hazard compliance dominate supplier selection.
- Toddlers:Under age 3 constitutes minimal addressable market due to limited independent mobility and safety regulatory stringency.
Elementary anchors revenue concentration. Middle School is expanding most quickly on sports crossover positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-mandated education expansion and chemical safety protocols are redrawing procurement patterns across major consumption zones. REACH SVHC enforcement in Europe, CPSIA certification in the United States, and China's GB standard alignment are forcing brands to regionalize compliance infrastructure or absorb multi-jurisdiction testing costs.
United States
Elementary enrollment stabilization sustains replacement demand for ergonomic daypacks with sternum stabilizers. The Consumer Product Safety Commission enforces third-party CPSIA testing for lead content and phthalate limits, compressing supplier margins. JanSport leverages domestic manufacturing relationships in the Southeast to accelerate certified batch turnaround.
China
Compulsory education extension drives volume demand for medium and large capacity configurations. The State Administration for Market Regulation applies GB standards for juvenile product labeling and mechanical safety. Zhejiang and Guangdong provinces concentrate over sixty percent of global OEM capacity, with Ningbo and Dongguan clusters scaling rPET filament integration.
Germany
Sustainability-focused buyer cohorts in urban centers favor canvas and recycled polyester alternatives. The European Chemicals Agency's REACH SCIP database mandates article-level substance disclosure, digitizing supplier inventory tracking. Bavaria-based technical specialists invest in water-based zipper coating R&D to maintain EU retail access.
India
Organized retail and e-commerce platforms displace traditional kirana distribution in tier-2 and tier-3 cities. The Bureau of Indian Standards enforces BIS certification for imported juvenile products, creating entry barriers for uncertified suppliers. Maharashtra and Gujarat host emerging domestic brands scaling to capture branded backpack access points.
Japan
Urban walking distances exceeding eight hundred meters accelerate rolling backpack penetration for middle school textbook transport. The Ministry of Economy, Trade and Industry oversees product safety standards alignment with international protocols. Tokyo-Osaka corridor retailers prioritize ergonomic frame engineering and sports crossover designs from athletic brand licensees.
Kids Backpack Market Competitive Landscape
Listed leaders compete with private specialists across certification capacity and licensed IP access. The vendor base stratifies into three tiers: multinational athletic brands with material science R&D programs, vertically integrated luggage conglomerates with juvenile product divisions, and regional specialists competing on turnaround speed and character licensing agility. Two dominant competitive moves define positioning: backward integration into certified component manufacturing, and exclusive IP partnerships with entertainment studios for seasonal collection drops.
Within the athletic-brand archetype, Nike Inc. and Adidas AG exemplify performance-oriented material science positioning, while JanSport anchors the specialist tier with domestic U.S. manufacturing relationships that compress CPSIA certification timelines. Samsonite International S.A. represents the conglomerate structure, occupying a position that leverages global luggage distribution infrastructure for juvenile product line extensions.
| Leading Market Players |
|---|
| JanSport |
| Herschel Supply Co. |
| Nike Inc. |
| Under Armour |
| Samsonite International S.A. |
| Adidas AG |
| Puma SE |
| L.L. Bean |
| VIP Industries Ltd. |
| Others |
Supply & Pricing Matrix
Capacity utilization above 85 percent across Ningbo-Dongguan clusters compresses supplier margins while elevating price floors for compliant batches. This scale concentration forces brands to absorb multi-jurisdiction testing costs or regionalize procurement away from peak-demand windows.
Pricing Analysis
Certification level (CPSIA/REACH/GB-grade) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium ergonomic, standard daypack, and economy licensed configurations dominates transactional models. Price differentiation stems from phthalate-free synthetic treatments and licensed IP royalty burdens. Cost compression in economy tiers is intensifying because petrochemical feedstock volatility outpaces annual retail contract adjustments. Mass-market buyers in developing economies exhibit highest price sensitivity; coastal metropolitan dual-income households show lowest sensitivity for ergonomic premium tiers bundled with subscription replacement programs.
Supply Chain Analysis
Yantian Port congestion and Ningbo-Zhoushan weather disruptions expose brands to concentrated logistics chokepoints. Manufacturing capacity draws from China, Vietnam, and Bangladesh for cut-and-sew operations, with China retaining 60-plus percent of global OEM output. Raw material dependencies rest on rPET filament yarn, 600D polyester weaves, and water-based zipper coatings from Zhejiang chemical specialists. Single-source vulnerability concentrates in REACH-compliant coating suppliers serving EU-facing brands. Distribution runs through big-box retail seasonal buying cycles, direct-to-consumer subscription platforms, and organized modern trade in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market tracks a cyclical recovery anchored to elementary enrollment expansion in India, Indonesia, and Nigeria. Replacement demand for age-appropriate ergonomic designs sustains volume momentum through compulsory education policy implementation.
For Market Incumbents: Compound certification capacity through captive testing laboratories in Southeast Asia to compress 12-16 week launch delays. Backward integration into rPET filament production secures feedstock cost stability against petrochemical volatility. Threat from agile domestic Chinese brands scaling OEM-to-label transitions demands preemptive IP exclusivity negotiations with entertainment studios. For New Entrants and Emerging Players: Lead with sustainability credentialing in Germany and Scandinavia where canvas and recycled polyester alternatives command premium positioning. India's tier-2 and tier-3 cities present the most penetrable geography as kirana displacement accelerates. Go-to-market angle: direct-to-parent subscription bundles with size-exchange guarantees eliminating back-to-school logistics friction. For Investors and Strategic Acquirers: Technical specialists with water-based coating R&D and unified ERP compliance systems represent priority acquisition targets. Long-term viability rests on circular economy infrastructure alignment as EU textile waste directives mature. Signal to watch: SCIP database enforcement intensity determining supplier software implementation cost absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | Captive CPSIA/REACH testing laboratories compress launch timelines for seasonal retail windows. |
| rPET Supply Chain Integration | Backward control over recycled filament yarn insulates margin from petrochemical price volatility. |
| Direct-to-Consumer Platform Launch | Subscription replacement programs lock in coastal metropolitan household lifetime value. |
| Licensed IP Exclusivity Negotiation | Entertainment studio partnerships differentiate premium tiers through dye-sublimation character collaborations. |
| Circular Economy Infrastructure Buildout | Take-back program alignment with EU Green Deal textile directives secures preferential retail placement. |
Research Methodology
Desk research of customs trade records, juvenile product safety filings, and retail audit databases preceded structured interviews with OEM procurement managers, brand supply chain directors, and regulatory compliance officers. Primary fieldwork across Ningbo, Dongguan, and Ho Chi Minh City manufacturing clusters validated capacity utilization and certification cost structures. Secondary triangulation drew from CPSC enforcement actions, ECHA SVHC restriction updates, and SAMR GB standard amendments. Bottom-up unit economics and top-down enrollment-driven demand models converged on volume estimates.
Variance decomposition across product configuration, material grade, age group, and regional regulatory cluster shaped the analytical framework. Modeled segmentation captured daypack versus rolling versus messenger formats; polyester, nylon, canvas, and leather materials; small through extra-large capacities; and elementary, middle school, preschool, and toddler age cohorts. CAGRs derived from enrollment elasticity modeling and replacement cycle frequency analysis. Industry-specific inputs included REACH SVHC list expansion timelines and compulsory education policy implementation schedules.
Underlying assumptions cover stable petrochemical feedstock pricing, sustained REACH enforcement intensity, and gradual rPET cost parity achievement, with deviation risk concentrated in Zhejiang-Guangdong supply disruptions and abrupt chemical restriction amendments. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Travel and Business Bags Market
Luggage
Sports Luggage Market
Luggage
Trunks Market
Luggage
Laptop Messenger Bags Market
Luggage
Sewing Bags Market
Luggage
Travel Bag Market
Luggage
Second Hand Bag Market
Luggage
Global Premium Luggage Market
Luggage
Laptop Carry Case Market
Luggage
Backpack Market
Luggage
Smart Carry-On Luggage Market
Luggage
Global Luggage Market
Luggage
United States Sports Bags Market
Luggage
Smart Bags Market
Luggage
School Bags Market
Luggage
Camera Bag Market