
 Personal Hygiene Market | 2026-2036
Personal Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Hygiene Market Intelligence
Manufacturing capacity expansion in India is rewriting supply chain logistics and pricing for the Asia-Pacific consumer base. Procter & Gamble leverages its extensive global distribution networks to maintain market presence across multiple product categories. Unilever differentiates through brand-specific marketing campaigns that target distinct consumer demographics in emerging economies. Meanwhile, Kimberly-Clark Corporation specializes in paper-based hygiene products, controlling significant portions of that segment's value chain.
Personal hygiene products encompass formulations designed for cleaning, sanitizing, and maintaining the body's external health. These products often rely on surfactants for cleansing, emollients for moisturizing, and active ingredients like aluminum salts in antiperspirants for specific functional outcomes. Within product types, body washes and liquid soaps continue to gain share over traditional bar soaps due to perceived convenience and hygiene. Online retail is becoming a critical distribution channel, especially for premium and niche products, while supermarkets command the mass-market volume.
Regulatory frameworks from the US Food and Drug Administration (FDA), Europe's REACH regulation, and China's National Medical Products Administration (NMPA) govern ingredient safety and labeling. These standards create high barriers to entry and mandate extensive testing for new product formulations, particularly those with therapeutic claims. Navigating the divergent regional regulations for sustainable packaging and chemical restrictions is the primary strategic challenge for multinational firms.
Market Dynamics
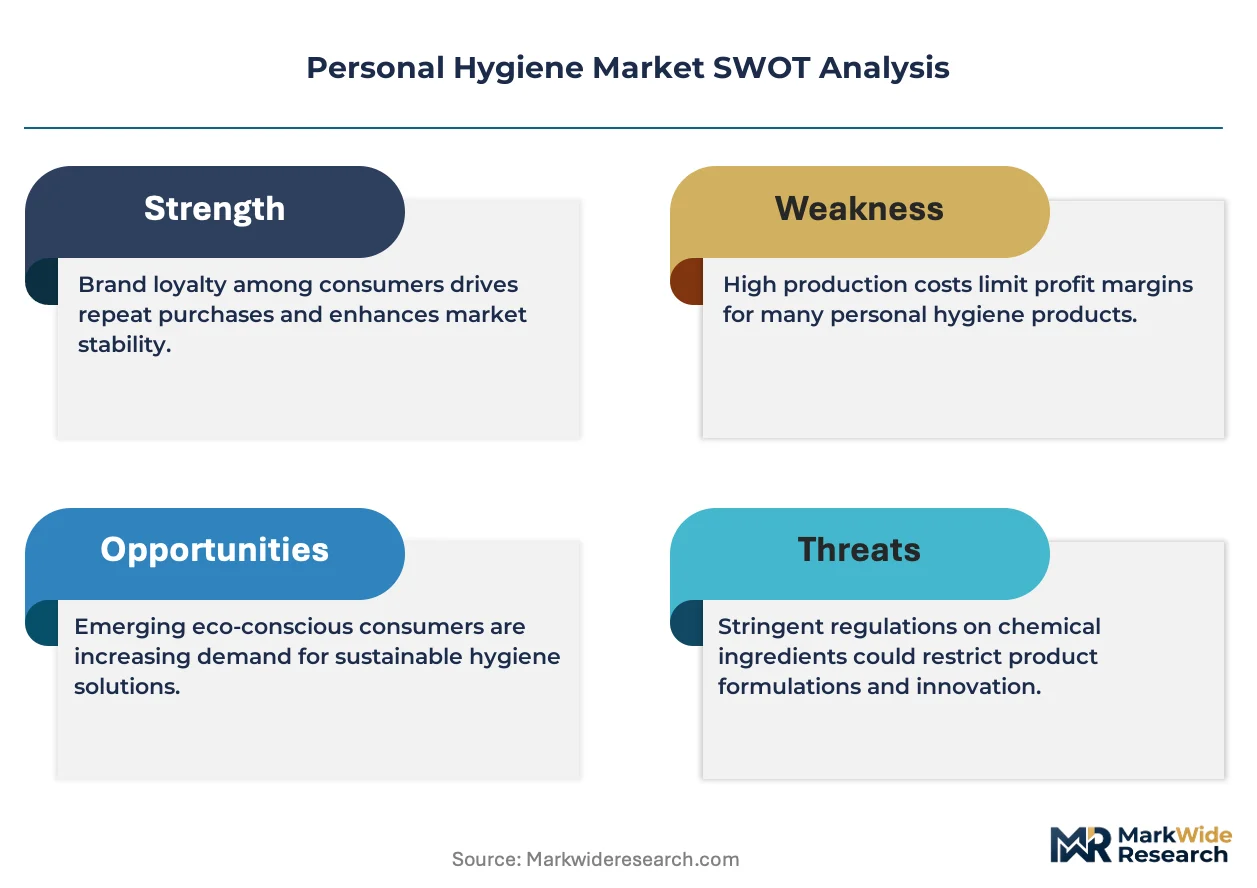
The personal hygiene market's evolution is defined by the structural tension between consumer demand for sustainable, ethically sourced products and the high cost of navigating fragmented, often contradictory, international regulatory standards for ingredients and packaging materials.
Growth Catalysts
- Expanding Men's Grooming Sector:A cultural shift towards male personal care, particularly in North America and Europe, is creating new product categories and expanding the consumer base for items beyond basic hygiene.
- E-commerce Channel Proliferation:The rise of direct-to-consumer brands and specialized online retailers provides a platform for niche and premium products to reach targeted demographics, bypassing traditional mass-market distribution gatekeepers.
- Hygiene Awareness in Emerging Economies:Increasing disposable incomes and public health initiatives in populous nations like India and Brazil are elevating baseline hygiene standards, driving volume growth for essential products like soaps, sanitizers, and oral care.
Market Restraints
- Divergent Regulatory Frameworks:Multinational corporations face significant compliance costs and extended time-to-market due to disparate ingredient safety and labeling rules set by bodies like the US FDA, Europe's REACH, and China's NMPA.
- Raw Material Price Volatility:The costs of key inputs, from petrochemical-derived surfactants and emollients to natural oils and biodegradable polymers, are subject to fluctuations in global commodity markets, impacting manufacturer margins.
- High Barriers to Formulation Innovation:The extensive clinical testing and safety substantiation required for new active ingredients, especially those with therapeutic claims like antiperspirants, create high R&D cost hurdles for new entrants.
Strategic Opportunities
- Waterless and Solid Formats:Developing products like shampoo bars, toothpaste tablets, and solid moisturizers meets consumer demand for sustainability by reducing water usage and plastic packaging, opening a high-growth product niche.
- Personalization Through Technology:Leveraging data analytics and direct-to-consumer feedback loops enables the creation of customized formulations tailored to individual skin types, hair conditions, or personal preferences, supporting premium pricing.
- Geographic Market Deepening:There is significant white space for market penetration in regions across Southeast Asia and Africa, where access to a wider variety of personal hygiene products beyond basic soap is still developing.
Industry Challenges
- Sustainable Packaging Integration:Shifting from traditional plastics to biodegradable or recycled materials requires significant operational adjustments in supply chain logistics, machinery retooling, and ensuring product stability and shelf life.
- Navigating Cross-Border Compliance:The administrative burden of securing and maintaining product registrations in multiple countries, each with unique documentation and testing protocols, presents a continuous operational challenge for global brands.
- Combating Counterfeit Goods:The growth of online marketplaces creates an ongoing challenge in policing and removing counterfeit hygiene products, which pose risks to brand reputation and consumer safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Hygiene Market |
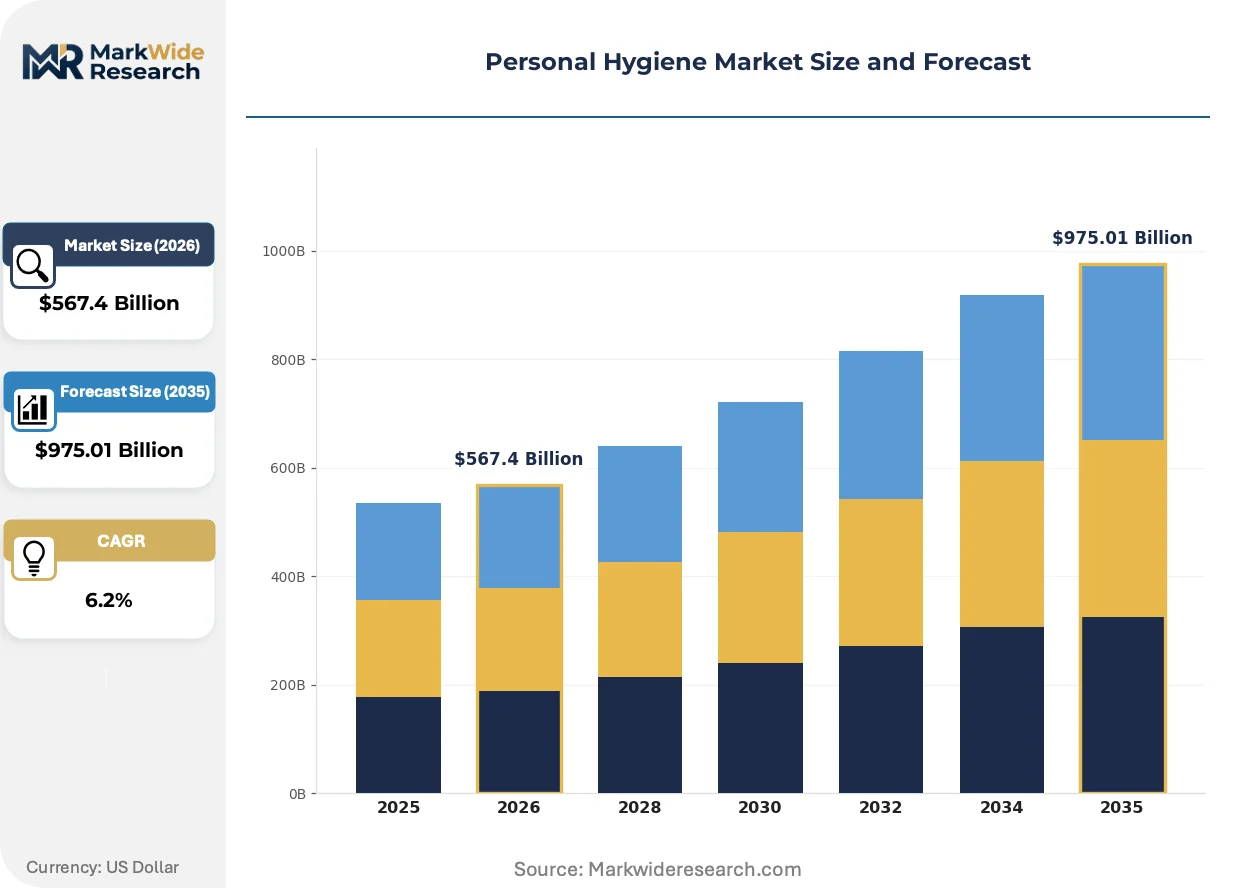
| Market Size in 2026 | $567.4 Billion |
| Market Size in 2035 | $975.01 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soaps, Body Washes, Deodorants, Moisturizers End User: Men, Women, Children, Infants Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores Packaging Type: Bottles, Tubes, Sachets, Jars |
| Companies Covered | Colgate-Palmolive Company, Reckitt Benckiser Group, Procter & Gamble, Braun Melsungen, 3M, Unilever, Kimberly-Clark Corporation, HARTMANN, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Hygiene Market Strategic Shifts & Innovations
Product identity is being redefined by material science innovations that prioritize sustainability and by digital platforms that foster transparency. Consumer ethics and ingredient knowledge are becoming as influential as brand marketing in shaping purchasing decisions across the personal hygiene landscape.
Waterless and solid-state formulations represent a significant product evolution. These concentrated formats, such as shampoo bars and toothpaste tablets, eliminate water as a primary ingredient, which drastically reduces packaging needs and transportation emissions. Eco-conscious consumers and travelers are the primary adopters, driving rapid growth in this niche. This innovation is collapsing the traditional product development lifecycle by enabling small, agile brands to compete on sustainability credentials rather than manufacturing scale.
European Union regulations are forcing systemic changes in product design and chemical formulation. The Single-Use Plastics Directive directly impacts products like wet wipes, while ongoing reviews under the REACH framework restrict or ban certain preservatives, UV filters, and surfactants. This regulatory pressure compels manufacturers to invest heavily in R&D for compliant packaging alternatives and safer chemical substitutes. Mass-market product lines with high sales volumes face the most significant financial and operational impact from these mandates.
Consumer purchasing behavior is shifting from brand-centric loyalty to ingredient-led decision-making. Shoppers actively seek out products featuring specific functional ingredients like hyaluronic acid or vitamin C, while also scrutinizing labels for "free-from" claims. This trend disrupts established mass-market dynamics, creating openings for transparent, science-backed challenger brands, particularly through online channels. This ingredient-focused procurement is most pronounced in the skincare and haircare segments in North America and Western Europe.
Personal Hygiene Market Segmentation
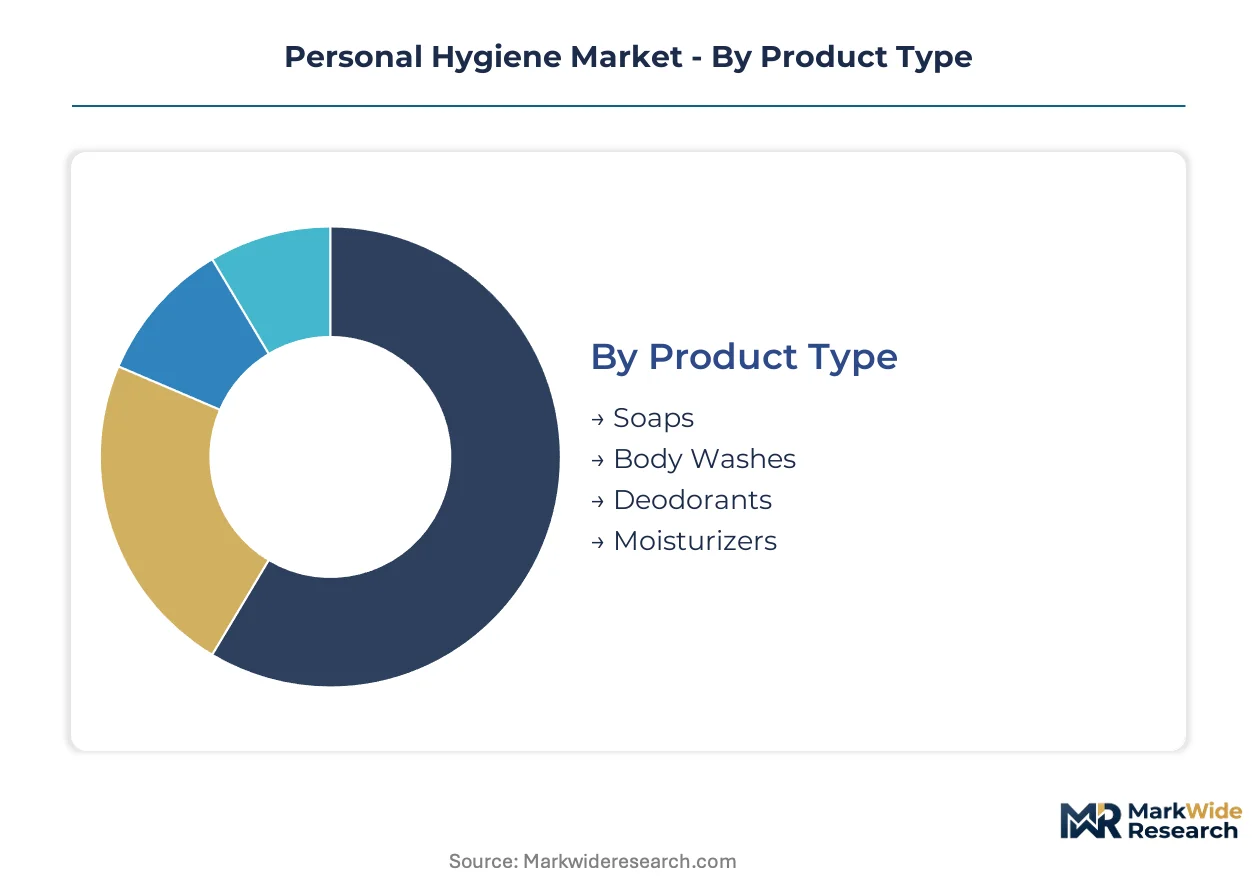
The personal hygiene market's segmentation reveals critical insights into consumer needs, product development priorities, and effective distribution strategies. Understanding these distinct segments allows firms to tailor offerings and marketing efforts precisely. This granular view highlights areas of concentrated demand and emerging opportunities across the product landscape.
Product Type:
The product type segmentation highlights the maturity spectrum of personal hygiene offerings, from established staples to rapidly evolving specialized formulations.
- Soaps:Traditional cleansing agents, typically solid bars or liquid formulations, used for basic body hygiene.
- Body Washes:Formulations containing surfactants and emollients for skin cleansing and hydration. Demand concentrates in urban centers like Brazil and India, driven by convenience and perceived hygiene benefits over traditional bar soaps.
- Deodorants:Products designed to mask or prevent body odor, often containing antimicrobial agents or fragrances. The men's grooming sector in North America and Europe drives significant demand, expanding beyond basic antiperspirants.
- Moisturizers:Emollient-rich formulations applied to the skin to prevent dryness and maintain hydration.
Soaps retain volume leadership due to widespread accessibility; body washes hold the steepest expansion curve.
End User:
This segmentation by end user reveals distinct purchasing behaviors and product requirements across various consumer demographics.
- Men:This segment encompasses grooming products and general hygiene items tailored for male consumers. Expanding demand in North America and Europe is driven by cultural shifts and new product categories.
- Women:Products specifically formulated for female personal care needs, including skincare, hair removal, and intimate hygiene. This segment often features premium and niche offerings, particularly through online retail channels.
- Children:Gentle formulations designed for the sensitive skin and specific hygiene requirements of younger individuals.
- Infants:Ultra-mild products developed for newborn and infant skin, emphasizing hypoallergenic and tear-free properties.
The women's segment commands the largest product diversity; the men's segment shows the most rapid category expansion.
Distribution Channel:
The distribution channel analysis highlights the diverse routes through which personal hygiene products reach consumers, reflecting varying accessibility and purchasing preferences.
- Supermarkets:Large retail outlets offering a broad range of personal hygiene products, serving as a primary channel for mass-market volume. These stores command significant sales across India and Brazil for essential items.
- Online Retail:E-commerce platforms and direct-to-consumer websites providing access to a wide array of products, including premium and niche brands. This channel is critical for reaching targeted demographics in Western Europe and North America.
- Pharmacies:Retailers specializing in health and wellness products, often stocking dermatological or therapeutic personal hygiene items.
- Convenience Stores:Small retail formats providing quick access to essential and impulse-purchase personal hygiene items.
Supermarkets maintain dominance for everyday purchases; online retail is gaining share for specialized and premium offerings.
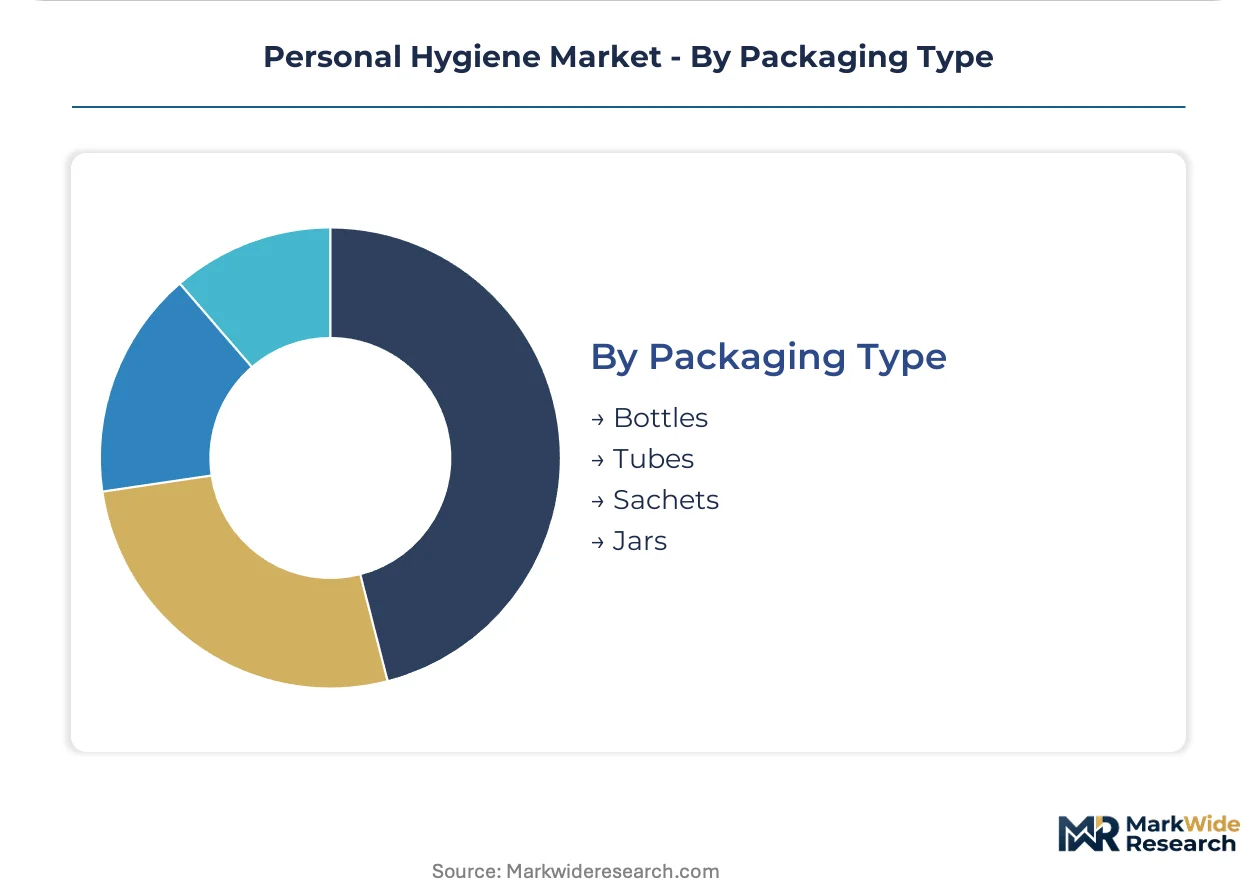
Packaging Type:
Packaging type segmentation reflects ongoing material science innovations and evolving consumer demands for sustainable and convenient product delivery.
- Bottles:Rigid or semi-rigid containers, typically plastic, used for liquid soaps, body washes, and lotions. The shift towards recycled and biodegradable plastics in Europe is influencing design and material choices.
- Tubes:Flexible cylindrical containers commonly used for creams, gels, and toothpaste, offering controlled dispensing. Demand for solid toothpaste tablets is influencing tube design.
- Sachets:Small, flexible pouches designed for single-use or travel-sized portions of liquid or cream products. These are particularly prevalent in emerging economies like India for affordability and accessibility.
- Jars:Wide-mouthed containers, often glass or plastic, used for thicker creams, balms, or solid formulations.
Bottles remain the most widespread format; sachets demonstrate high growth in cost-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global personal hygiene market benefits from robust port infrastructure, facilitating the movement of raw materials and finished goods across continents. This logistical backbone supports diverse regional growth patterns and enables manufacturers to serve widespread consumer bases efficiently. Strategic distribution hubs streamline supply chain operations for multinational firms.
United States
The United States market experiences significant demand growth from the expanding men's grooming sector and online retail penetration for premium products. The US Food and Drug Administration (FDA) sets stringent ingredient safety and labeling standards. New York's metropolitan area fosters a cluster of direct-to-consumer brands specializing in personalized hygiene formulations.
Germany
German consumers increasingly demand sustainable and ethically sourced personal hygiene products, influencing product design. Europe's REACH regulation compels manufacturers to invest in compliant chemical substitutes and safer formulations. The Rhine-Ruhr industrial heartland serves as a key manufacturing and innovation center for eco-friendly personal care items.
India
India's market experiences substantial volume growth driven by increasing hygiene awareness and rising disposable incomes across its vast consumer base. The Bureau of Indian Standards (BIS) ensures product quality and safety for mass-market personal care items. Mumbai's urban sprawl demonstrates concentrated demand for essential hygiene products, fueling manufacturing capacity expansion.
Brazil
Brazil's large consumer base and cultural emphasis on personal care drive strong demand for body washes and liquid soaps. Brazil's ANVISA agency enforces strict regulations on cosmetic and personal hygiene product formulations and labeling. São Paulo, as a prominent economic center, exhibits high consumption of convenience-oriented personal care products.
China
China's market witnesses growing demand for premium and niche personal hygiene products, often purchased through online retail channels. The National Medical Products Administration (NMPA) imposes rigorous testing and registration requirements for imported and domestic products. Shanghai, within the Yangtze River Delta, functions as a critical distribution and innovation center for luxury personal care.
Personal Hygiene Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing essential inputs. The personal hygiene market features a tiered structure, with global conglomerates operating alongside specialized niche players and agile direct-to-consumer brands. Strategic archetypes include diversified consumer goods giants, paper-based hygiene product specialists, and focused premium skincare providers. Companies primarily engage in portfolio diversification and geographic market deepening to maintain competitive positioning.
Diversified consumer goods giants like Procter & Gamble and Unilever exemplify broad market coverage across multiple product categories and distribution channels. These multinational corporations leverage extensive global distribution networks to maintain market presence in both mass-market and emerging economies. Kimberly-Clark Corporation, conversely, represents a specialized archetype, focusing on paper-based hygiene products and controlling significant portions of that segment's value chain. This specialization allows them to cater to specific consumer needs within a defined product area.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Reckitt Benckiser Group |
| Procter & Gamble |
| Braun Melsungen |
| 3M |
| Unilever |
| Kimberly-Clark Corporation |
| HARTMANN |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Overcapacity in certain commodity chemical feedstocks, particularly petrochemicals, drives both supplier behavior and pricing posture for personal hygiene product manufacturers. This utilization pressure influences contract negotiations for key ingredients and packaging materials.
Pricing Analysis
Volume-discount tiering structures characterize pricing across the personal hygiene market, with significant differentiation between mass-market and premium offerings. Price differentiation stems from brand premium and certification level, particularly for eco-friendly or dermatologically tested formulations. Pricing softness reflects intense competition in the mass-market segment for bar soaps and basic body washes. Consumers purchasing essential hygiene products in emerging economies like India demonstrate the highest price sensitivity, while premium skincare buyers in Western Europe are less price-sensitive.
Supply Chain Analysis
Raw material price volatility for petrochemical-derived surfactants and natural oils presents a structural risk across the supply chain. Geographic supply concentration for key ingredients draws from manufacturing hubs in China and India, alongside specialized chemical producers in Germany. Component dependencies include biodegradable polymers for sustainable packaging and paper pulp for specialized hygiene products. Distribution runs through a dual model, with supermarkets dominating mass-market volume and online retail capturing premium and niche product sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal hygiene market offers a service-attach opportunity, with personalized formulation subscriptions and smart dispenser refills expanding faster than traditional product hardware. This shift opens new recurring revenue streams for brands.
For Market Incumbents:Pre-empt challenger brands by accelerating investment in waterless and solid-format product innovation, directly addressing consumer demand for sustainability. Deepen vertical integration into sustainable packaging material production to mitigate supply chain risks and control costs. Expand manufacturing capacity in high-growth regions like India to counter regional competitors and optimize logistics for local consumption. Invest in digital platforms to capture direct-to-consumer feedback, allowing for rapid product iteration against emerging niche threats.
For New Entrants and Emerging Players:Establish a beachhead in the men's grooming sector or the waterless product niche, leveraging a clear sustainability or personalization value proposition. The online retail channel in Western Europe provides the most penetrable segment for science-backed, ingredient-led brands. A direct-to-consumer go-to-market angle, supported by transparent ingredient sourcing and custom formulation options, can attract discerning consumers. Focus on compliant packaging alternatives to differentiate from established players.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among direct-to-consumer brands specializing in personalized formulations or subscription-based refill models. Long-term viability favors entities capable of navigating divergent regulatory frameworks and integrating sustainable packaging at scale. Acquisition targets should include agile, technology-driven brands with strong intellectual property in new ingredient science or sustainable material development. The signal to watch for inflection is the widespread adoption of circular economy principles in packaging design across major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Packaging Integration | Reduces environmental impact and meets evolving consumer and regulatory demands in Europe. |
| Direct-to-Consumer Channel Expansion | Fosters direct consumer relationships and enables personalized product offerings in North America. |
| Waterless Product Development | Addresses eco-conscious consumer preferences and reduces transportation costs for global distribution. |
| Geographic Market Deepening in Asia-Pacific | Captures volume growth from increasing hygiene awareness and disposable incomes in India. |
| R&D Investment in Compliant Formulations | Ensures adherence to stringent ingredient safety regulations from the US FDA and Europe's REACH. |
Research Approach
Two parallel data streams informed the analysis: primary qualitative interviews and secondary quantitative data collection. Combining primary interviews with industry stakeholders and secondary validation provided a comprehensive market perspective. Key stakeholders included brand managers, R&D directors, procurement leads at major CPG firms, and regulatory affairs specialists. Secondary data sources encompassed customs/trade data, regulatory filings from NMPA and FDA, and retail audit data.
Forecast inputs being considered included disposable income growth, evolving regulatory changes from EU directives, and raw material cost fluctuations across the analysis window. The analytical framework integrated bottom-up and top-down triangulation to model market dynamics over the projection horizon. Segmentation dimensions modeled included product type, end user, distribution channel, packaging type, and key ingredient categories. Compound annual growth rates were derived through historical trend analysis and future demand projections.
Stress conditions across geopolitical shifts, new pandemic outbreaks, and major ingredient bans were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding consumer behavior shifts and technological advancements, acknowledging inherent market uncertainties. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Compostable Toothbrush Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
AI Toothbrush Market