
 Smart Luggage Market | 2026-2036
Smart Luggage Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Luggage Market Analysis
Business professionals is unwinding the historical dominance of leisure tourists as the primary revenue archetype in smart luggage procurement. Samsonite leverages its manufacturing scale across Asian production clusters to maintain cost discipline in the mid-premium tier. Away anchors direct-to-consumer channel control with a digital-native operating model that bypasses traditional retail markups. Rimowa specializes in aluminum-hybrid construction and monobloc shell engineering, occupying the ultra-premium price band with heritage craft positioning.
Smart luggage denotes wheeled travel containers integrated with electronic systems including GPS tracking modules, Bluetooth proximity sensors, lithium-ion power banks, and biometric locking mechanisms, typically constructed from polycarbonate composites or aluminum alloys with embedded antenna arrays and USB-C output ports. The primary commercial purpose centers on real-time asset location, digital access control, and mobile device charging during transit. GPS Tracking technology leads unit shipments among technology segments while Built-In Battery configurations face evolving aviation restrictions that reshape product roadmaps. Carry-On dimensions dominate volume as airlines enforce stricter cabin-baggage policies, though Checked Bags with integrated tracking command higher per-unit margins due to theft-risk premiums on long-haul routes.
FAA guidelines on lithium-ion battery containment and EASA cabin-baggage rules directly constrain product design specifications and limit battery capacities in carry-on configurations. CE marking requirements under EU electronics directives and FCC radio-frequency certifications govern market access for Bluetooth and GPS-enabled units sold across North American and European retail channels. Stakeholders must monitor evolving airline-specific protocols and cross-border electronics compliance as dual-certification costs reshape competitive economics for new entrants.
Market Dynamics
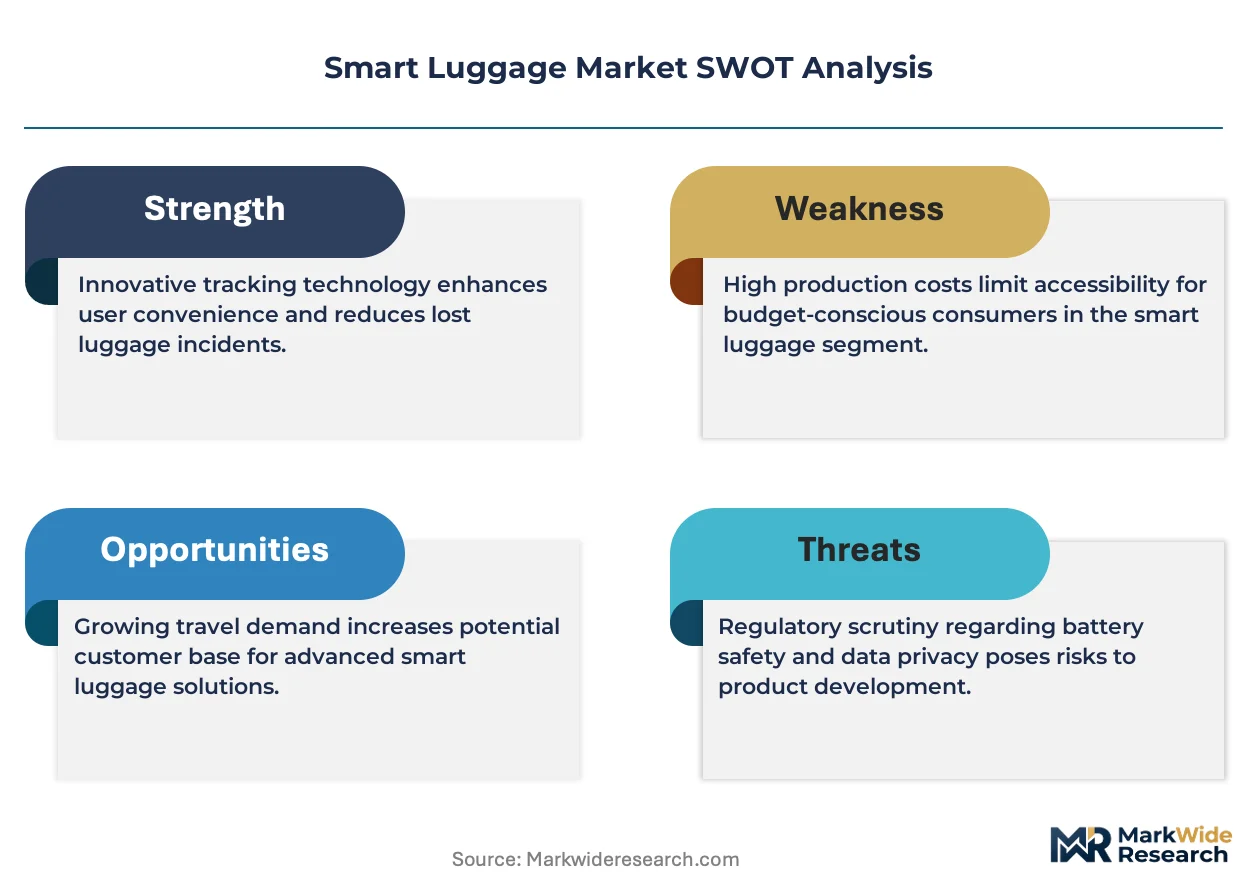
Airline carry-on restrictions under FAA and EASA guidelines are compressing battery capacities in smart luggage designs while simultaneously elevating demand for theft-resistant checked-bag configurations with embedded tracking modules.
Growth Catalysts
- FAA Lithium-Ion Guidelines:Tighter cabin-battery limits are redirecting R&D investment toward GPS-dominant tracking systems that operate without active power banks during flight segments.
- Business Traveler Demand:Frequent corporate flyers now prioritize real-time asset location and biometric access control over leisure-oriented capacity features.
- Polycarbonate Composite Shells:Embedded antenna arrays in lightweight thermoplastic structures enable signal transmission without compromising structural integrity or weight thresholds.
Market Restraints
- Dual-Certification Cost Burden:FCC radio-frequency approval for North America and CE marking under EU electronics directives impose parallel compliance expenses that disproportionately burden new entrants.
- Raw Material Concentration:Lithium-ion cell supply chains cluster in East Asian manufacturing hubs, exposing producers to geopolitical friction and input cost volatility.
- Technical Limitation:Bluetooth proximity sensors suffer signal degradation in cargo holds, limiting theft-alert functionality for checked-bag deployments on long-haul routes.
Strategic Opportunities
- Underpenetrated Corporate Procurement:Enterprise travel departments in Germany and Japan remain underserved by bulk-configuration smart luggage programs with centralized fleet management.
- USB-C Power Delivery Convergence:Integration of GaN charging circuits with GPS modules creates unified power-data architectures that reduce component count and assembly complexity.
- Direct-to-Consumer Channel Expansion:Digital-native operating models bypass traditional retail markups and capture margin previously allocated to wholesale distribution layers.
Industry Challenges
- RF Engineering Talent Scarcity:Embedded antenna design for aluminum-hybrid shells requires specialized expertise that outpaces current graduate pipeline output.
- Airline-Specific Protocol Fragmentation:Carrier-by-carrier battery containment rules complicate SKU rationalization and inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Luggage Market |
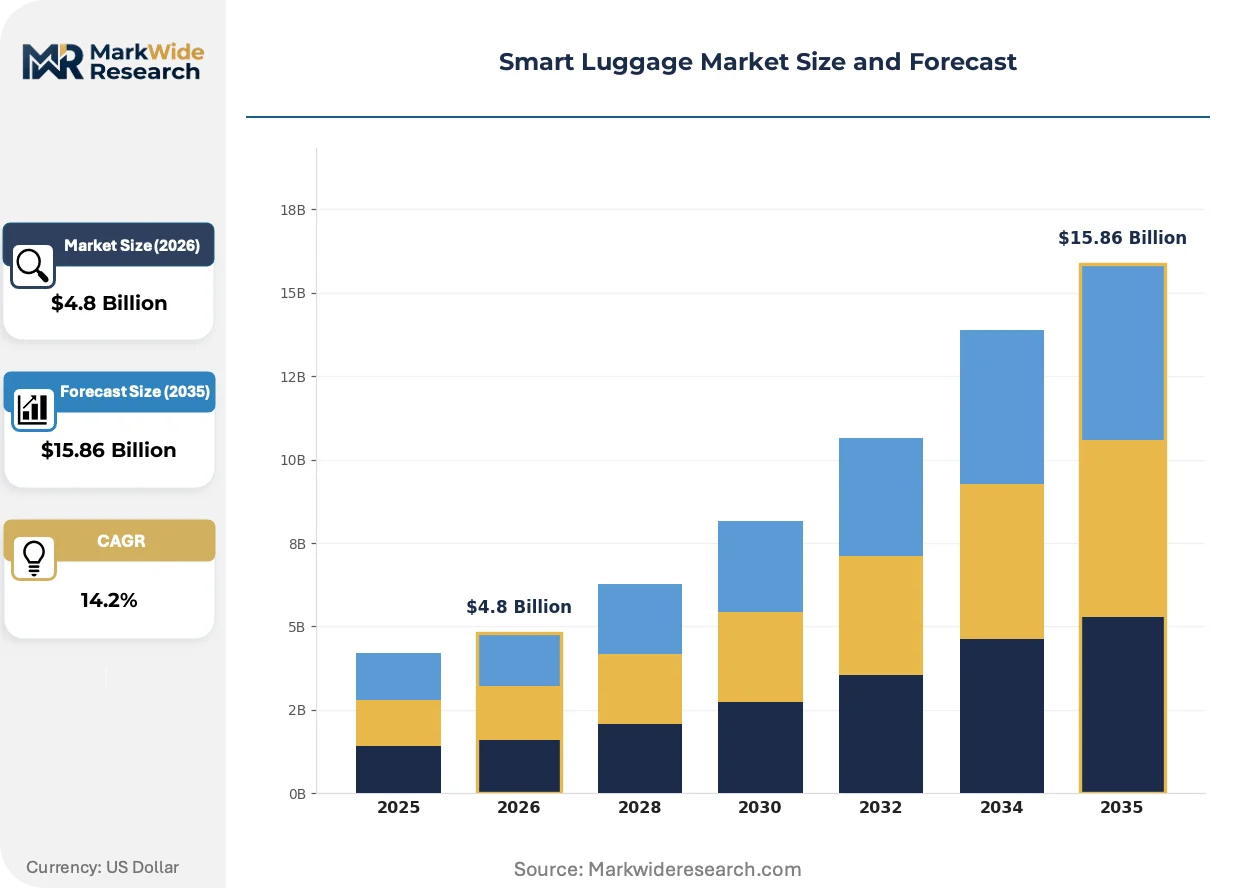
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carry-On, Checked Bags, Backpacks, Hybrid Luggage Technology: GPS Tracking, Bluetooth Connectivity, Built-In Battery, Smart Lock Use Case: Traveling, Business Trips, Adventure Travel, Weekend Getaways Customer Type: Frequent Travelers, Leisure Tourists, Business Professionals, Families |
| Companies Covered | Travelpro, Briggs & Riley, Samsonite, Monos, Delsey, Rimowa, Away, Béis, Tumi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Luggage Market Emerging Trajectories
Product roadmaps in smart luggage are pivoting from power-centric to tracking-centric architectures as aviation authorities tighten energy-storage restrictions. This reorientation is compressing development cycles and reshaping supplier relationships across the value chain.
Biometric locking mechanisms employing capacitive fingerprint sensors are displacing combination-based access systems in premium-tier carry-on configurations. Business travelers at Frankfurt and Tokyo hubs are adopting these units at accelerated rates. This shift is displacing mechanical lock suppliers from the specification chain and elevating semiconductor vendors into direct OEM relationships.
EASA cabin-baggage rules now mandate removable battery compartments for all lithium-ion configurations entering European airspace. This regulatory pressure forces redesign of monobloc shell structures to accommodate tool-free extraction mechanisms. Checked-bag manufacturers with integrated tracking are capturing margin premiums as carry-on designers absorb compliance-driven cost inflation.
Corporate procurement departments are consolidating vendor relationships around fleet-management platforms that unify tracking, warranty, and replacement logistics. Traditional retail channels lose volume to direct enterprise contracts. This concentration is most visible in United States technology sector travel programs where centralized billing and device provisioning dominate purchasing decisions.
Smart Luggage Market Segmentation
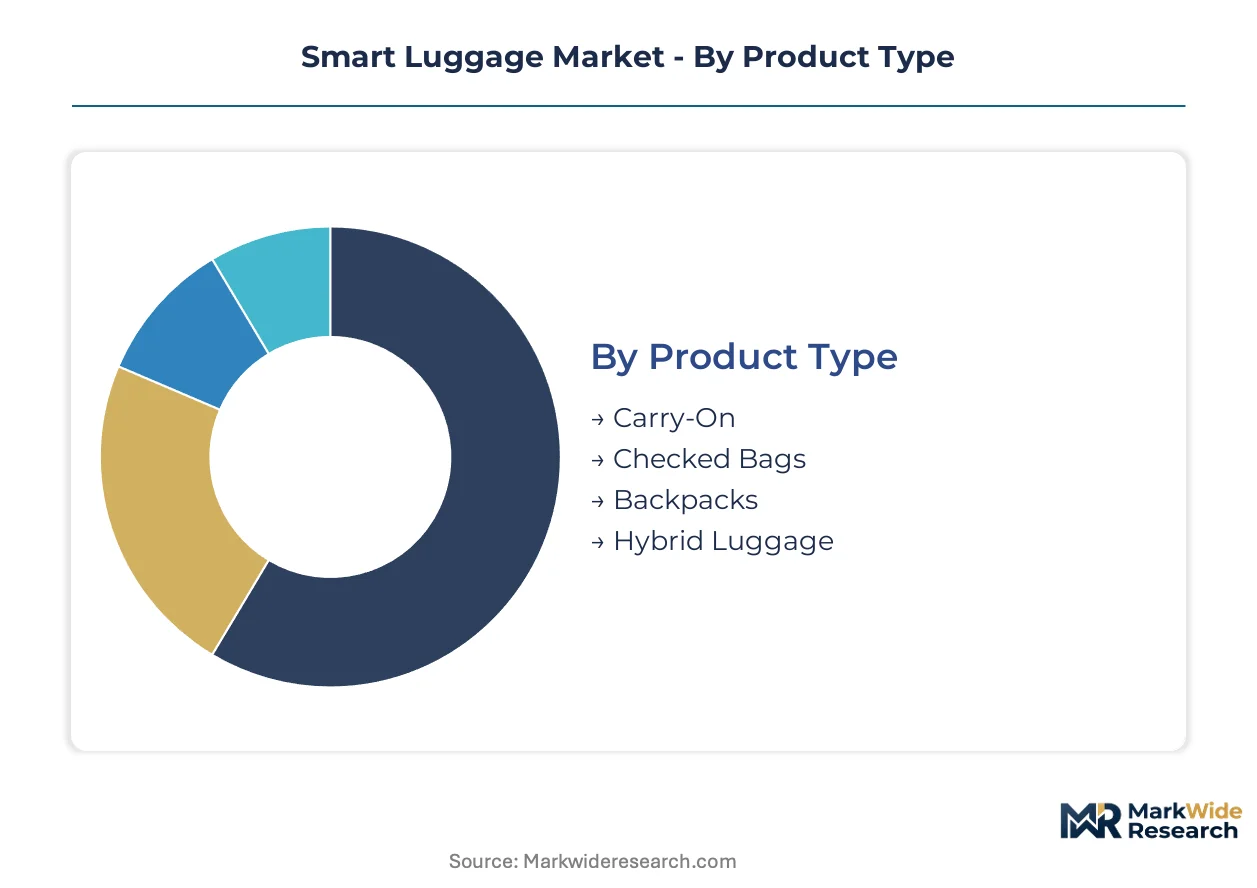
Smart luggage segmentation reveals how FAA and EASA regulations reshape product architecture across dimensions. Each category reflects distinct compliance burdens, margin structures, and adoption velocities that determine competitive positioning.
Product Type:
FAA lithium-ion containment rules and EASA removable-battery mandates create divergent design specifications across form factors, with carry-on units absorbing the steepest compliance costs.
- Carry-On:Compact wheeled containers engineered to fit standardized overhead compartments with embedded GPS modules and USB-C output arrays. Demand concentrates among business professionals at Frankfurt and Tokyo hubs where biometric access control commands premium positioning. FAA battery-capacity ceilings force GaN circuit miniaturization and compress per-unit margins.
- Checked Bags:Larger-volume containers with reinforced shell structures housing high-capacity tracking systems that operate in unpressurized cargo environments. Corporate procurement departments in Germany favor these configurations for long-haul fleet deployment where theft-risk premiums justify higher unit economics. Bluetooth signal degradation in cargo holds limits proximity-alert functionality.
- Backpacks:Wearable smart configurations with distributed antenna arrays and lightweight polycarbonate framing. Urban commuters in Japanese metropolitan corridors adopt these for intercity rail connectivity.
- Hybrid Luggage:Convertible form factors switching between wheeled and backpack modes with modular battery compartments. Adventure travel segments in the United States show emerging interest for multi-modal transit scenarios.
Checked Bags handles the majority of throughput; Backpacks is expanding most quickly on share.
Technology:
Aviation authority restrictions on active power storage during flight segments elevate tracking-centric architectures over charging-centric designs, reshaping R&D allocation and supplier relationships.
- GPS Tracking:Satellite-based location modules with embedded antenna arrays operating independently of lithium-ion power banks during transit. Business travelers prioritize real-time asset visibility over charging capacity, driving fastest adoption curves in United States corporate travel programs. Polycarbonate composite shells enable signal transmission without structural compromise.
- Bluetooth Connectivity:Proximity-based sensors linking to mobile devices for theft alerts and distance monitoring. Signal degradation in cargo holds constrains checked-bag deployment, limiting utility to carry-on configurations at Tokyo and Frankfurt hubs.
- Built-In Battery:Lithium-ion power banks with USB-C output ports for device charging during ground segments. EASA removable-compartment mandates force monobloc shell redesigns and inflate compliance costs.
- Smart Lock:Capacitive fingerprint sensors and biometric access mechanisms displacing mechanical combination systems. Semiconductor vendors now occupy direct OEM relationships previously held by lock manufacturers.
GPS Tracking captures the dominant technology share; Smart Lock climbs the fastest as biometric adoption accelerates.
Use Case:
Customer workflow patterns determine feature prioritization, with business-oriented scenarios demanding asset security and leisure contexts emphasizing capacity and durability.
- Traveling:General-purpose mobility encompassing mixed transit modes with balanced feature loads across tracking, charging, and access control. Volume concentrates in United States retail channels.
- Business Trips:Time-compressed itineraries requiring real-time location certainty and biometric access for sensitive materials. Enterprise procurement departments in Germany consolidate vendor relationships around fleet-management platforms.
- Adventure Travel:Ruggedized deployments with reinforced shell structures and extended battery autonomy for remote locations. Japanese outdoor enthusiasts drive niche demand.
- Weekend Getaways:Short-duration trips favoring lightweight configurations with minimal electronic complexity. Leisure tourists in the United States prioritize cost efficiency over connectivity density.
Business Trips generates the highest per-unit margins; Adventure Travel gains share fastest as outdoor activity participation rises.
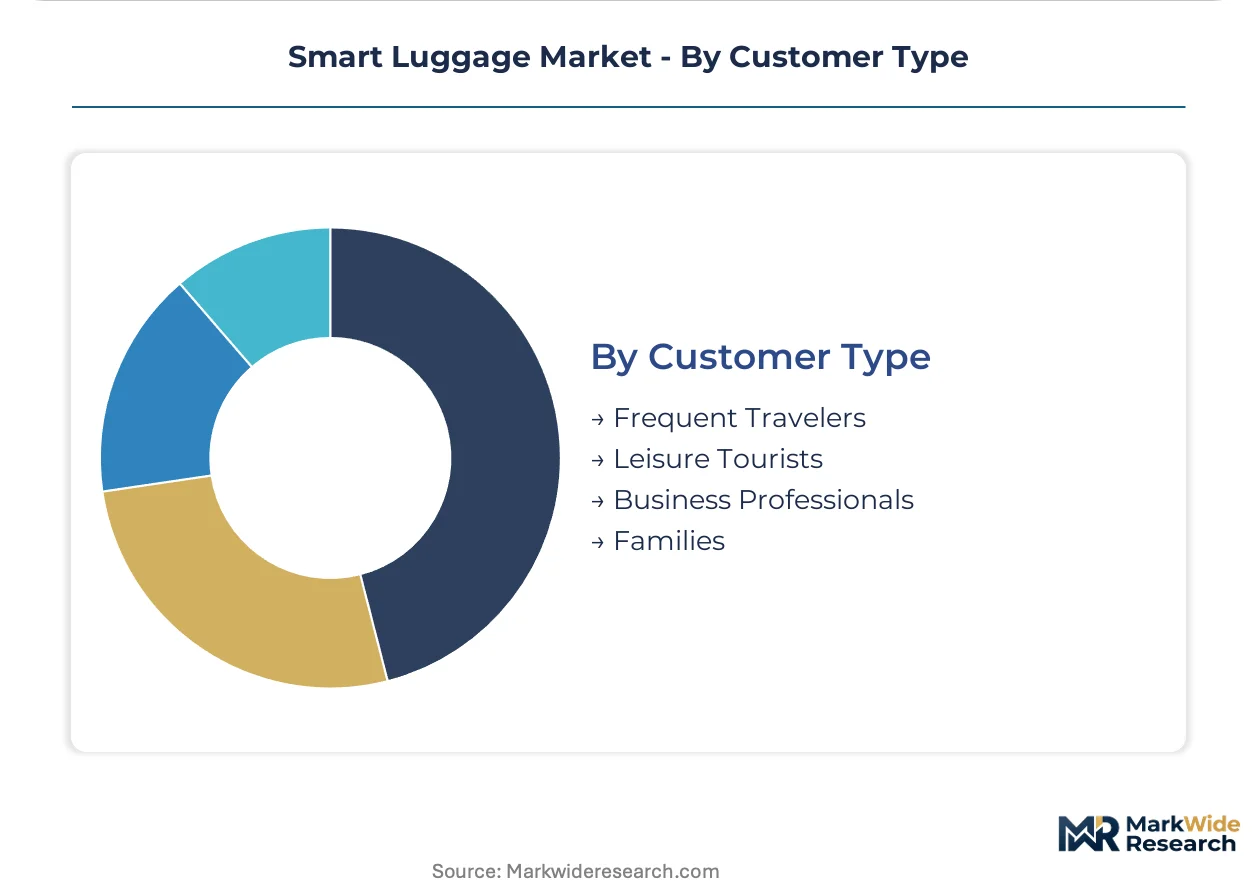
Customer Type:
Purchase authority and reimbursement structures create divergent channel economics, with corporate procurement bypassing retail markups that constrain leisure segment profitability.
- Frequent Travelers:High-velocity flyers with monthly transit patterns justifying premium connectivity investments. United States technology sector travel programs centralize billing and device provisioning for this cohort.
- Leisure Tourists:Seasonal purchasers prioritizing capacity and durability over real-time tracking functionality. Traditional retail channels retain volume here despite direct-to-consumer erosion.
- Business Professionals:Corporate travelers with centralized procurement authority and fleet-management platform integration. Frankfurt and Tokyo hub concentrations drive specification standardization.
- Families:Multi-unit purchasers seeking durability and value positioning with basic tracking sufficiency. Weekend getaway patterns dominate usage profiles.
Frequent Travelers anchors volume throughput; Business Professionals shows the steepest expansion trajectory as enterprise adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Business professionals in Frankfurt, Tokyo, and Dallas-Fort Worth drive procurement velocity as corporate travel departments consolidate vendor relationships around fleet-management platforms. Premium connectivity features command sustained buyer interest in markets with dense hub concentrations and stringent aviation oversight.
United States
Frequent flyers in the technology sector anchor demand through centralized procurement programs with unified billing and device provisioning. FAA lithium-ion guidelines compress battery capacities in carry-on configurations while elevating theft-resistant checked-bag deployments. Dallas-Fort Worth and Atlanta hubs concentrate enterprise adoption where real-time asset tracking justifies premium positioning.
Germany
Corporate procurement departments in Frankfurt and Munich prioritize biometric access control and GPS-dominant architectures for long-haul fleet deployment. EASA removable-battery mandates force redesign of monobloc shell structures to accommodate tool-free extraction mechanisms. Bavaria's industrial corridor hosts manufacturing clusters serving mid-premium tier specifications.
Japan
Urban commuters in Tokyo and Osaka metropolitan corridors adopt lightweight backpack configurations with distributed antenna arrays for intercity rail connectivity. METI standards govern electronics certification for Bluetooth and GPS-enabled units entering domestic retail channels. Kansai region manufacturing maintains precision assembly capabilities for polycarbonate composite shells.
United Kingdom
Business travelers at Heathrow and London City airports drive specification standardization for carry-on dimensions under tightened cabin-baggage enforcement. CE marking requirements under EU electronics directives govern market access for connectivity-enabled units despite post-Brexit regulatory divergence. Southeast England logistics clusters facilitate direct-to-consumer distribution bypassing traditional wholesale layers.
France
Leisure tourists in Paris and Lyon prioritize durability and capacity over connectivity density in weekend getaway patterns. ANSM and CNIL oversight intersect with aviation security protocols for biometric data handling in smart lock deployments. Île-de-France retail channels retain volume for seasonal purchasers despite enterprise procurement erosion elsewhere.
Smart Luggage Market Vendor Landscape
Player mix skews toward heritage luggage manufacturers diversifying into electronics integration alongside digital-native entrants bypassing traditional wholesale structures. Market structure exhibits tiered concentration with ultra-premium aluminum-hybrid specialists, mid-premium polycarbonate scale players, and direct-to-consumer challengers. Three strategic archetypes dominate: heritage craft-positioned European houses, Asian manufacturing-scale incumbents, and venture-backed digital natives. Competitive moves center on M&A for electronics capability acquisition and geographic expansion through direct-to-consumer channel buildout.
Within the heritage European tier, Rimowa and Delsey exemplify aluminum-hybrid and polycarbonate specialization respectively, occupying distinct price-positioning strata. Samsonite anchors the scale-driven mid-premium segment through Asian production cluster leverage. Among digital-native challengers, Away represents direct-to-consumer channel control with margin capture previously allocated to retail distribution layers.
| Leading Market Players |
|---|
| Travelpro |
| Briggs & Riley |
| Samsonite |
| Monos |
| Delsey |
| Rimowa |
| Away |
| Béis |
| Tumi |
| Others |
Supply Flow & Price Mechanics
GaN circuit miniaturization replacing conventional silicon power management simultaneously shifts component sourcing toward Taiwanese semiconductor foundries and compresses per-unit margins in carry-on configurations as FAA battery ceilings force cost absorption.
Pricing Analysis
Next-generation GPS-dominant architectures command premium positioning over prior-generation power-bank-centric designs while current-generation hybrid configurations face margin compression. Three-tier pricing structure across premium aluminum-hybrid, standard polycarbonate, and economy ABS tiers separates Rimowa heritage positioning from Samsonite scale economics. Pricing pressure stems from EASA removable-battery redesign costs inflating carry-on unit economics. Leisure tourists in United States retail channels exhibit highest price sensitivity; corporate procurement departments in Germany show lowest sensitivity due to fleet-management platform consolidation.
Supply Chain Analysis
Trans-Pacific container availability fluctuations and Port of Los Angeles congestion patterns elevate inbound logistics costs for polycarbonate resin shipments originating from East Asian petrochemical complexes. Lithium-ion cell production concentrates in China, South Korea, and Japan; GPS module fabrication draws from Taiwan and Vietnam. Raw material dependencies span cobalt cathode chemistry, polycarbonate thermoplastics, and RF antenna substrates. Single-source vulnerability in semiconductor foundry capacity threatens component availability. Distribution runs through direct-to-consumer digital channels and enterprise procurement platforms bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart luggage demand tracks corporate travel expenditure cycles, with recovery momentum building as technology sector travel programs in the United States reinstate centralized device provisioning.
For Market Incumbents: Compound manufacturing scale advantages in Asian production clusters through backward integration into polycarbonate compounding and GPS module assembly. Defend against digital-native entrants by accelerating FCC and CE dual-certification timelines that new entrants cannot match. Prioritize R&D allocation toward biometric lock semiconductor partnerships that displace mechanical suppliers from specification chains. For New Entrants and Emerging Players: FCC fast-track approval for GPS-only tracking configurations bypasses EASA removable-battery compliance burdens that encumber power-bank designs. White-space targets include underpenetrated corporate procurement departments in Japan and enterprise fleet-management platform integration. The most penetrable segment is adventure travel backpacks with modular battery architectures. Go-to-market execution should anchor direct-to-consumer channel control with digital-native operating models that capture retail margin layers. For Investors and Strategic Acquirers: The market sits at a cyclical recovery phase that favors digital-native challengers with proven customer acquisition economics over heritage manufacturers burdened by wholesale channel restructuring. Long-term viability centers on 5-10 year enterprise procurement platform consolidation trends that reward fleet-management capability. Acquisition target archetype: venture-backed direct-to-consumer brands with established FCC certification and enterprise sales infrastructure. Signal to watch: technology sector travel policy normalization at Dallas-Fort Worth and Seattle corporate headquarters.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Circuit Integration | Enables GPS-dominant architectures that comply with FAA lithium-ion ceilings while reducing component count. |
| Biometric Lock Partnership | Positions semiconductor vendors in direct OEM relationships previously held by mechanical lock manufacturers. |
| Enterprise Fleet Platform Launch | Captures corporate procurement volume in Germany and United States technology sector travel programs. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail markups and captures margin previously allocated to wholesale distribution layers. |
| Dual-Certification Acceleration | Secures FCC and CE marking ahead of competitors to lock in North American and European market access. |
Methodological Framework
The analysis maps GPS tracking modules, biometric lock systems, lithium-ion power banks, and polycarbonate shell manufacturing, each validated through product development executives at heritage luggage manufacturers, semiconductor vendor sales directors, airline procurement officers, and corporate travel managers. Primary interviews combined with secondary validation from FAA regulatory filings, EASA safety directives, FCC equipment authorization databases, and customs trade data for lithium-ion cell imports. Bottom-up unit shipment modeling triangulated against top-down corporate travel expenditure benchmarks.
Consistency checks validated volume and value outputs against airline baggage policy enforcement timelines and corporate travel recovery indicators across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, use case workflow, and customer procurement authority. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory intervention effects. Industry-specific forecast inputs encompass EASA removable-battery mandate compliance timelines and enterprise fleet-management platform penetration rates.
Underlying assumptions cover FAA and EASA regulatory stability, lithium-ion supply chain continuity, and corporate travel policy normalization, with deviation risk concentrated in airline-specific battery containment rule fragmentation and geopolitical friction in East Asian manufacturing hubs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Amenity Kits Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Snowboard Bags Market
Travel Accessories
Travel Pouches Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
India Travel Accessories Market
Travel Accessories
Backpack Systems Market