
 Internet of Robotic Things Market | 2026-2036
Internet of Robotic Things Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Robotic Things Market Outlook
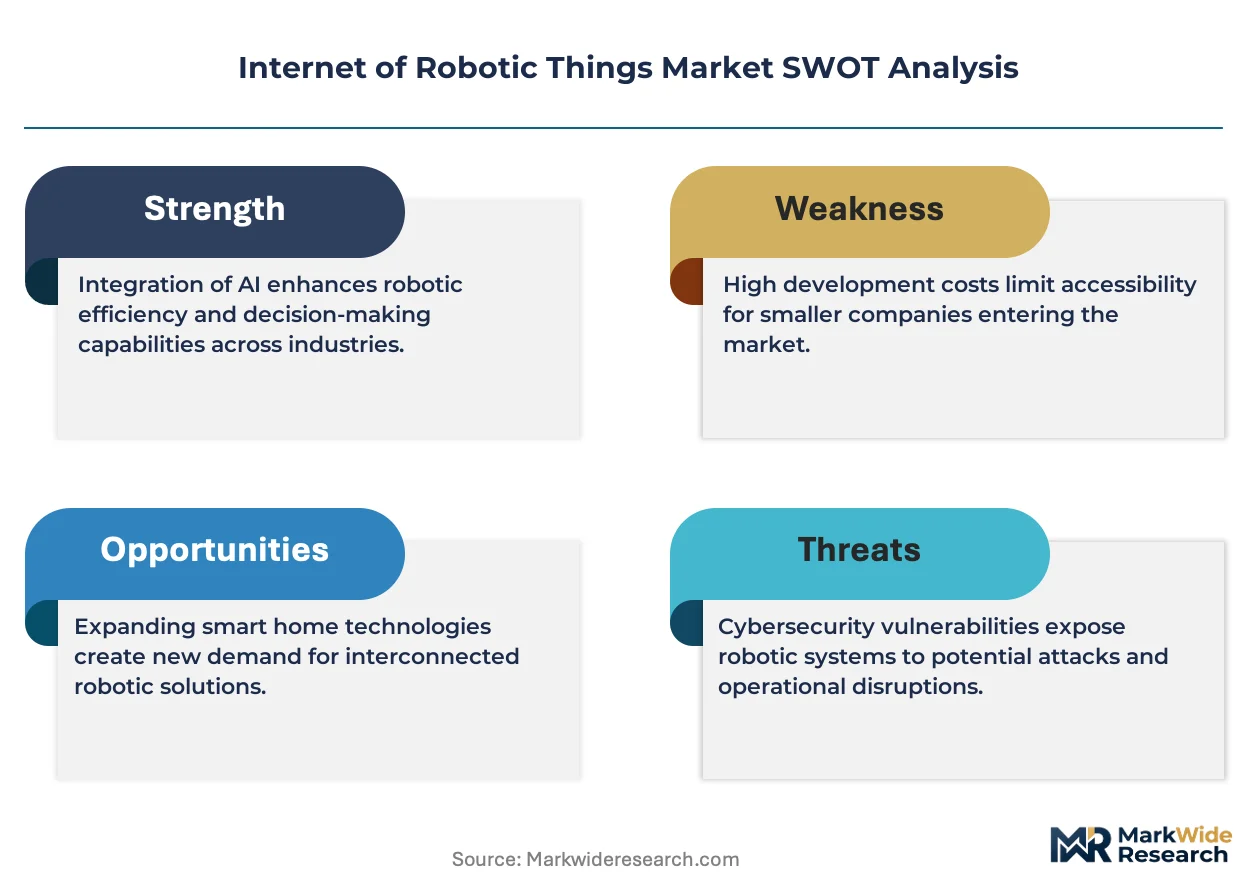
Industrial-grade connectivity specifications are reorganizing competitive dynamics across the Internet of Robotic Things landscape. FANUC Corporation leverages its captive controller architecture to dominate high-reliability manufacturing cells. ABB Ltd. anchors European demand through its integrated software-hardware platforms for process industries. Cisco Systems, Inc. competes at the network layer, extending industrial Ethernet and edge security into robotic communication stacks.
The Internet of Robotic Things denotes networked robotic systems that combine embedded sensor arrays, real-time actuation protocols, and cloud-connected intelligence to execute physical tasks with minimal human intervention; these systems typically operate on sub-50 millisecond latency thresholds to maintain coordination between distributed nodes. Collaborative robots and autonomous mobile robots represent the fastest-expanding product categories, as manufacturers prioritize flexible reconfiguration over fixed automation lines. AI and machine learning technology segments command disproportionate R&D investment, while sensor technology remains the margin pool where specialized component suppliers extract value from precision optical and haptic modules.
The EU AI Act and CE marking requirements under the Machinery Directive are reshaping product certification pathways for autonomous robotic systems entering European industrial environments. In the United States, OSHA safety standards and FCC wireless equipment authorizations create dual compliance tracks that influence hardware design decisions. Stakeholders must monitor how regulatory divergence between jurisdictions affects cross-border deployment architectures and software update governance models.
Market Dynamics
Smart factory adoption in automotive assembly is accelerating deployment of connected robotic systems, while the EU AI Act and machinery safety directives tighten compliance requirements for autonomous equipment. This dual pressure of operational demand and regulatory constraint defines current competitive positioning.
Growth Catalysts
- CE marking requirements under the Machinery Directive:European manufacturers must retrofit existing installations with safety-certified IoT modules, creating replacement demand for compliant robotic controllers.
- Automotive assembly automation:Electric vehicle production lines require flexible reconfiguration capabilities that only networked collaborative robots can deliver at scale.
- Stuttgart-Munich industrial cluster concentration:Germany's precision manufacturing ecosystem generates demonstration effects that pull neighboring markets toward integrated robotic deployments.
Market Restraints
- Industrial Ethernet component supply concentration:Specialized chipsets for sub-50 millisecond latency communication originate from a limited supplier base in East Asian foundries.
- EU AI Act compliance costs:Conformity assessment procedures for high-risk autonomous systems impose documentation burdens that extend product launch timelines.
- Legacy controller incompatibility:Proprietary fieldbus protocols in installed manufacturing equipment resist seamless integration with cloud-connected robotic nodes.
Strategic Opportunities
- Process industry verticals:Chemical and pharmaceutical manufacturers in Basel and Ludwigshafen represent underpenetrated demand for hazardous-environment robotic systems.
- 5G private network deployment:German industrial zones are licensing localized spectrum that enables ultra-reliable low-latency communication for mobile robot coordination.
- AI Act regulatory arbitrage:Early movers achieving notified body certification gain preferential access to public procurement tenders for autonomous infrastructure.
Industry Challenges
- OT-IT convergence expertise scarcity:Manufacturing engineers lack training in cybersecurity protocols required for cloud-connected actuation systems.
- Functional safety certification timelines:SIL-rated sensor validation for collaborative robot applications extends development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Robotic Things Market |
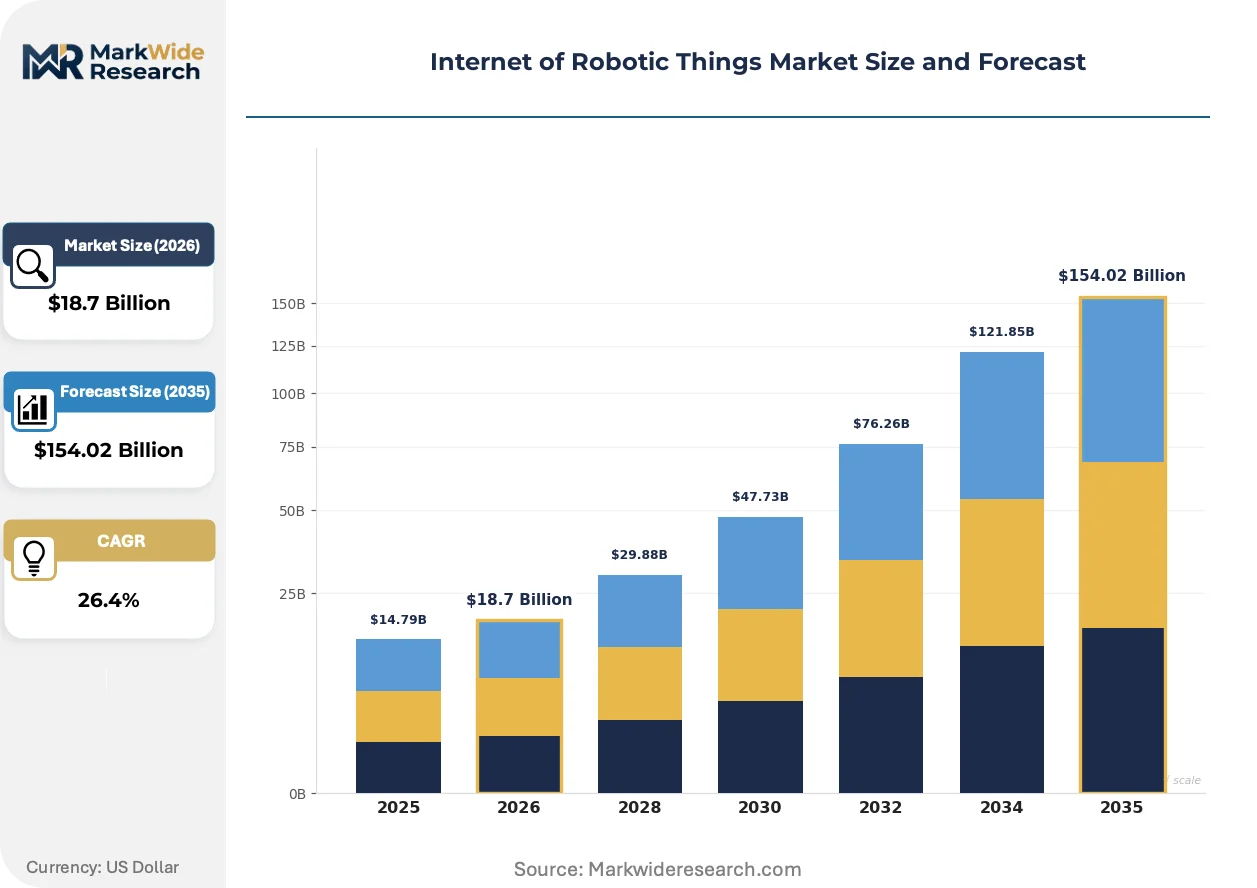
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Autonomous Mobile Robots Technology: AI, Machine Learning, Sensor Technology, Cloud Computing Application: Manufacturing, Healthcare, Logistics, Agriculture End User: Manufacturers, Hospitals, Warehousing, Farms |
| Companies Covered | FANUC Corporation, KUKA AG, ABB Ltd., Cisco Systems, Inc., Intel Corporation, Google, Yaskawa Electric Corporation, Northrop Grumman Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Robotic Things Market Strategic Shifts
Industrial-grade connectivity specifications are reorganizing how robotic systems communicate, process sensor data, and coordinate distributed actuation. Three developments are compressing traditional architecture boundaries.
Edge-native computing architectures are decomposing the centralized cloud model for robotic intelligence. Automotive tier-one suppliers now deploy containerized inference engines directly on robot-mounted gateways. This distributed topology reduces round-trip latency for collision avoidance algorithms below the 20-millisecond threshold required for human-robot collaboration.
REACH substance restrictions and RoHS recast directives are forcing redesigns of haptic sensor modules. European component suppliers are substituting rare-earth magnet alternatives in force-torque sensors. The machinery sector faces material qualification delays as notified bodies assess new alloy compositions for fatigue resistance.
Automotive OEMs now specify outcome-based performance contracts rather than capital equipment purchases. Tier-one suppliers assume operational risk for robotic cell uptime in exchange for per-unit processing fees. This arrangement concentrates in German and Austrian manufacturing regions where labor cost arbitrage justifies vendor-managed maintenance models.
Internet of Robotic Things Market Segmentation
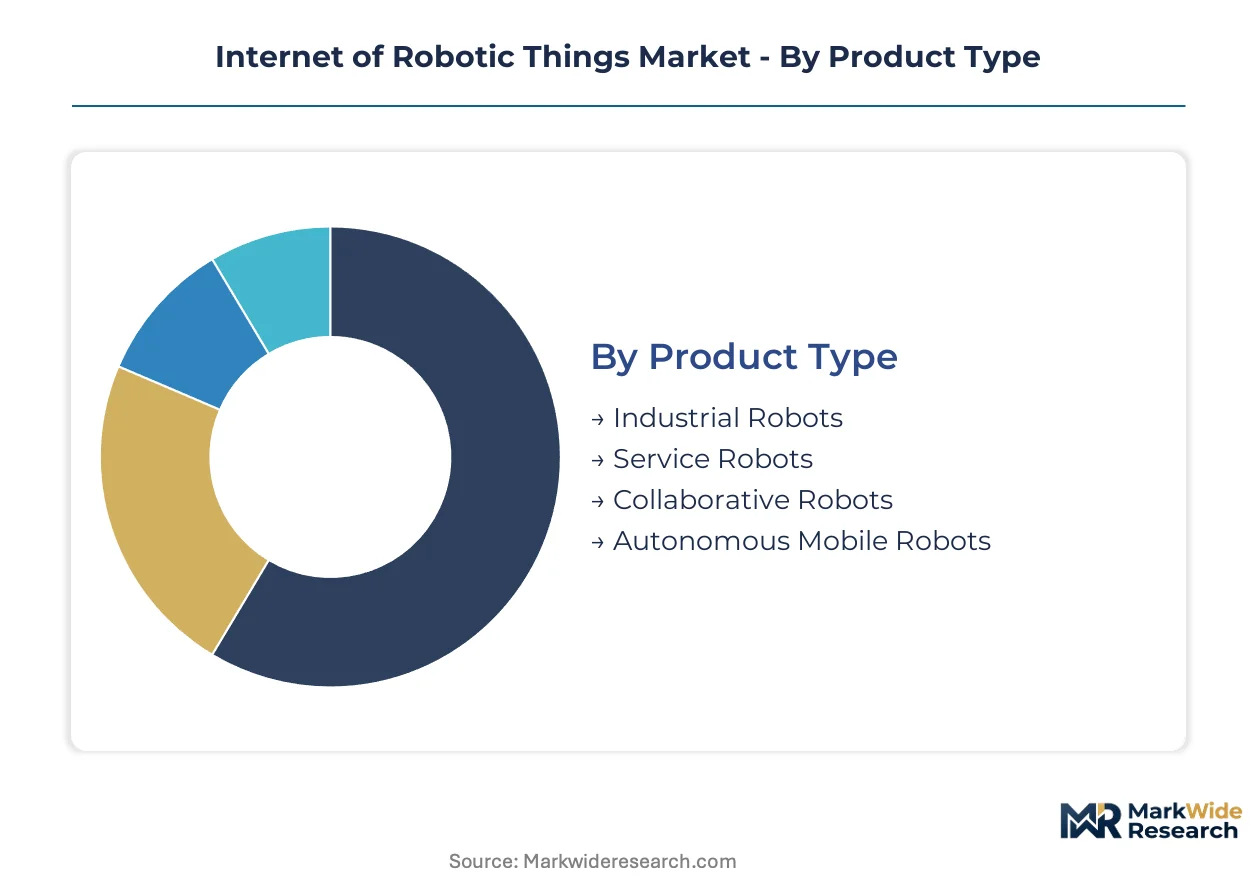
Segmentation in the Internet of Robotic Things market reveals how latency requirements, safety certification tiers, and connectivity architectures fragment procurement channels. Understanding these divisions clarifies which specifications command premium positioning versus commodity substitution.
Product Type:
Channel distribution varies sharply by product category, with system integrators dominating industrial robot sales while direct OEM relationships prevail for collaborative and mobile platforms.
- Industrial Robots:Fixed-position articulated systems with six-axis kinematic chains and IP54-rated enclosures dominate high-volume automotive welding and paint operations. Demand concentrates in Stuttgart and Munich manufacturing corridors where precision assembly tolerances below 0.1 millimeter justify controller-level redundancy investments.
- Collaborative Robots:Force-limited articulated arms with ISO/TS 15066-compliant power and force limiting enable fenceless human-robot workstations. German automotive tier-one suppliers deploy these fastest for electric vehicle battery module assembly where production lines reconfigure weekly.
- Service Robots:Semi-autonomous platforms for disinfection, delivery, and inspection operate on ROS-based middleware with Wi-Fi 6E backhaul.
- Autonomous Mobile Robots:Lidar-navigated platforms with SLAM localization and fleet management software coordinate warehouse inventory movement.
By volume, industrial robots lead. By growth pace, collaborative robots are expanding most quickly.
Technology:
Cost tiering separates these segments, with AI and machine learning commanding R&D premium allocation while sensor technology extracts hardware margin through specialized optical and haptic component supply.
- AI:Deep learning inference engines for predictive maintenance and quality inspection run on GPU-accelerated edge devices. Healthcare imaging robots in Basel pharmaceutical clusters deploy convolutional neural networks for defect detection.
- Machine Learning:Supervised learning pipelines for robotic grasp planning and trajectory optimization require labeled datasets from physical demonstrations. Logistics operators in Dutch port zones utilize reinforcement learning for container handling efficiency gains.
- Sensor Technology:Force-torque, vision, and proximity sensing modules with SIL-2 safety ratings.
- Cloud Computing:Distributed data lakes for fleet analytics and over-the-air software updates.
By margin capture, sensor technology leads. By investment velocity, AI is climbing the fastest.
Application:
Customer maturity divides these segments, with manufacturing exhibiting sophisticated procurement specifications while agriculture represents nascent adoption with tolerance for higher failure rates.
- Manufacturing:Discrete automation cells with MES integration and OEE tracking dominate precision engineering. Austrian machine tool builders specify sub-20 millisecond cycle times for CNC tending robots.
- Logistics:Goods-to-person fulfillment systems with AMR orchestration and pick-assist robotics scale in Rotterdam and Hamburg distribution hubs facing labor availability constraints.
- Healthcare:Surgical navigation and rehabilitation exoskeletons with FDA and CE dual certification.
- Agriculture:GPS-guided harvesting platforms with computer vision for crop selective picking.
By installed base, manufacturing leads. By deployment acceleration, logistics is gaining share fastest.
End User:
Procurement scale separates these buyers, with manufacturers consolidating vendor relationships while farms purchase through agricultural equipment distributors with extended financing terms.
- Manufacturers:Capital equipment purchasers with dedicated automation engineering teams negotiate outcome-based uptime contracts. German Mittelstand firms in Baden-Württemberg favor vendor-managed maintenance for robotic press tending lines.
- Warehousing:Third-party logistics operators with seasonal volume volatility prefer robotic-as-a-service subscriptions over capital expenditure.
- Hospitals:Clinical engineering departments with biocompatibility and sterilization requirements.
- Farms:Owner-operators with seasonal cash flow patterns and limited technical support infrastructure.
By contract value, manufacturers lead. By subscription model adoption, warehousing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision robotic controllers to automotive assembly plants across the United States and China. This trade corridor channels Stuttgart-engineered automation into Detroit EV factories and Shanghai battery gigafactories. German component suppliers now face REACH substance restrictions on rare-earth magnet alternatives.
Germany
Baden-Württemberg's Mittelstand machine tool builders drive demand for collaborative robot integration. The EU AI Act conformity assessment procedures extend product launch timelines for autonomous systems. Stuttgart-Munich manufacturing corridors deploy fenceless human-robot workstations for electric vehicle battery module assembly.
United States
Detroit-area EV production lines require flexible reconfiguration capabilities from networked collaborative robots. OSHA safety standards and FCC wireless equipment authorizations create dual compliance tracks influencing hardware design. Michigan and Ohio automotive clusters specify sub-20 millisecond cycle times for CNC tending robots.
China
Shanghai and Shenzhen battery gigafactories import German precision controllers for high-volume assembly operations. MIIT industrial internet standards mandate data localization for connected robotic systems. Yangtze River Delta manufacturing zones deploy 5G private networks for mobile robot fleet coordination.
Japan
Kanto and Nagoya industrial zones supply force-torque sensors for collaborative robot safety systems. METI's Society 5.0 roadmap accelerates human-robot collaboration pilots in aging workforce environments. Osaka-based automotive tier-one suppliers adopt containerized edge inference engines for collision avoidance.
South Korea
Seoul Capital Area semiconductor foundries demand robotic wafer handling with SIL-2 safety ratings. MFDS medical device regulations intersect with robotic surgical navigation certification requirements. Busan-Ulsan shipbuilding clusters test autonomous welding robots for hazardous-environment deployment.
Internet of Robotic Things Market Competitive Environment
Listed leaders compete with private specialists across industrial Ethernet and edge security layers. The vendor base concentrates around captive controller architectures and integrated software-hardware platforms. Three archetypes dominate: Japanese precision automation conglomerates, European process industry integrators, and American network infrastructure providers. Competitive moves center on strategic partnerships for 5G private network deployment and backward integration into specialized sensor modules.
Within the precision automation tier, FANUC Corporation and Yaskawa Electric Corporation represent Japanese-listed conglomerates with captive controller expertise. ABB Ltd. anchors European demand through its integrated platforms. Among network-layer specialists, Cisco Systems, Inc. occupies a position extending industrial Ethernet into robotic communication stacks.
| Leading Market Players |
|---|
| FANUC Corporation |
| KUKA AG |
| ABB Ltd. |
| Cisco Systems, Inc. |
| Intel Corporation |
| Yaskawa Electric Corporation |
| Northrop Grumman Corporation |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for industrial Ethernet chipsets from East Asian foundries concentrate pricing power among captive controller manufacturers while forcing tier-two system integrators toward extended payment terms. This inventory compression dynamic favors vertically integrated conglomerates with in-house semiconductor sourcing over modular assemblers exposed to spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers extract margin through SIL-2 safety certification and sub-20 millisecond latency guarantees, while economy tiers compete on per-axis controller cost. Cost compression in standard-tier collaborative robot arms is intensifying because automotive OEMs now specify outcome-based uptime contracts rather than capital equipment purchases. Tier-one automotive suppliers show least price sensitivity given vendor-managed maintenance models, whereas Mittelstand machine tool builders in Baden-Württemberg negotiate aggressively on initial hardware outlay.
Supply Chain Analysis
Taiwan Strait transit risk underwrites supply vulnerability for GPU-accelerated edge inference engines deployed in predictive maintenance modules. Component sourcing draws from Taiwan for advanced semiconductors, Germany for precision motion controllers, and Japan for force-torque sensors. Single-source vulnerability concentrates in rare-earth magnet alternatives for haptic modules facing REACH substance restrictions. Distribution runs through Stuttgart-Munich system integrators for European manufacturing corridors and direct OEM relationships for North American automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against cloud-native robotics platforms that disintermediate hardware-centric incumbents through software-defined automation stacks.
For Market Incumbents: Consolidate backward integration into specialized sensor modules to defend margin pools against modular competitors. Acquire edge-native computing capabilities to counter containerized inference engines from automotive tier-one suppliers. Priority rests on captive supply of SIL-rated optical and haptic components where notified body certification creates switching costs. For New Entrants and Emerging Players: EU AI Act fast-track certification for high-risk autonomous systems opens preferential access to German public procurement tenders. Target chemical and pharmaceutical manufacturers in Basel and Ludwigshafen as underpenetrated demand for hazardous-environment robotic systems. Go-to-market angle: 5G private network deployment partnerships with German industrial zones licensing localized spectrum. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core robotic divisions amid portfolio restructuring. Long-term viability centers on software-hardware integration depth rather than component supply alone. Signal to watch: automotive OEM adoption velocity of outcome-based performance contracts versus traditional capital equipment purchases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Modules | Captures margin pools in SIL-2 force-torque and optical sensing where REACH compliance creates qualification barriers. |
| 5G Private Network Deployment | Enables sub-10 millisecond coordination for mobile robot fleets in German industrial zones with localized spectrum licensing. |
| EU AI Act Certification Fast-Track | Secures preferential access to public infrastructure tenders before conformity assessment backlogs extend launch timelines. |
| Outcome-Based Performance Contracting | Shifts operational risk to vendors while locking in long-term maintenance revenue from automotive OEMs. |
| Edge-Native Computing Architecture | Reduces cloud dependency latency below 20-millisecond thresholds required for fenceless human-robot collaboration. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists and refined through secondary validation. Primary fieldwork combined structured interviews with maintenance directors at Stuttgart-Munich manufacturing corridors and procurement leads at automotive tier-one suppliers. Secondary sources encompassed EU AI Act implementation guidance, Machinery Directive conformity assessment databases, SEC filings from listed automation conglomerates, and German industrial cluster trade association reports. Bottom-up unit economics and top-down sectoral demand curves underwent iterative reconciliation.
Variance decomposition across product type, technology tier, application vertical, and end-user procurement model shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled dimensions included latency specification thresholds, safety certification tiers, and connectivity architecture choices. Industry-specific inputs comprised electric vehicle production line reconfiguration frequency and 5G private network deployment timelines in German industrial zones.
Decision-makers should treat outputs as directional under assumptions of sustained automotive assembly automation and stable EU regulatory implementation; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as CE marking enforcement intensity and East Asian semiconductor supply continuity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
China Cloud Robotics Market