
 High Precision Worm Shaft Market | 2026-2036
High Precision Worm Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
High Precision Worm Shaft Market Insights
The gap between conventional hobbing and modern continuous-profile grinding is narrowing as worm shaft producers chase AGMA 14-quality surfaces. KLINGELNBERG leverages its spiral bevel expertise to dominate high-end metrology-linked production. SEW-EURODRIVE anchors European supply through captive gear manufacturing integrated with its drive systems portfolio. Shuanghuan Transmission competes on scale, supplying hardened steel worm sets to China's expanding machine tool rebuild sector.
A high precision worm shaft is a threaded cylindrical component with profile accuracies typically held to DIN 3962 Class 4 or finer, meshing with a worm wheel to transmit motion at high reduction ratios with minimal backlash. It serves primarily in positioning systems where rotary-to-linear or speed-reduction precision determines end-product quality. Single-start worm shafts occupy the mature volume tier, while multi-start variants capture margin pools in robotics and aerospace equipment where rapid traverse with holding torque matters most. Stainless steel and hardened steel grades lead material selection as end users prioritize wear resistance in continuous-cycle automated manufacturing environments.
FDA device-quality requirements and EU machinery directives shape specifications for worm shafts deployed in medical automation and packaging machines, forcing producers to document material traceability and surface finish compliance. China's SAMR enforces GB standards for precision transmission components used in domestically produced machine tools, tightening import substitution criteria. Germany's KBA and Japan's METI both reference JIS B 1741 gear accuracy classes in automotive and industrial robot certification pathways. Stakeholders must monitor how REACH material restrictions and evolving dual carbon goals in China reroute alloy sourcing and heat-treatment energy costs before locking in long-term supply agreements.
Market Dynamics
Continuous-profile grinding technology is compressing tolerance bands below DIN 3962 Class 4 thresholds, forcing conventional hobbing operations to absorb capital costs or exit high-precision tiers entirely.
Growth Catalysts
- EU machinery directives:Medical automation OEMs in Germany and Switzerland must document surface finish traceability, creating captive demand for certified worm shaft suppliers.
- Robotics integrators:Automated manufacturing firms pursuing tighter positional accuracy are specifying multi-start worm geometries for rapid traverse with holding torque.
- China's GB standards:SAMR enforcement of precision-machining directives for domestically produced machine tools is tightening import substitution criteria and elevating minimum tolerances.
Market Restraints
- Alloy sourcing volatility:REACH material restrictions and China's dual carbon goals are rerouting heat-treatment energy costs, compressing margins on hardened steel grades.
- Metrology equipment concentration:High-end profile grinding requires KLINGELNBERG-class measuring centers concentrated in Germany and Japan, creating geographic supply risk.
- Substitution by direct-drive motors:Linear motor and torque motor architectures are eliminating mechanical reduction stages in semiconductor lithography equipment.
Strategic Opportunities
- India's PLI scheme for machine tools:Precision component makers can access production-linked incentives by supplying hardened worm sets to domestic CNC rebuild channels.
- Convergence of additive and subtractive:Hybrid manufacturing combining selective laser melting with precision grinding enables complex internal cooling geometries for aerospace actuators.
- Aftermarket service unbundling:Independent rebuild specialists in China's Yangtze River Delta are sourcing replacement worm sets outside captive OEM channels.
Industry Challenges
- Grinding operator scarcity:Continuous-profile grinding demands multi-axis programming skills that vocational pipelines in Germany and Japan struggle to replenish.
- AGMA 14 certification timelines:Surface finish validation for medical and aerospace tiers requires extended third-party metrology queues, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Precision Worm Shaft Market |
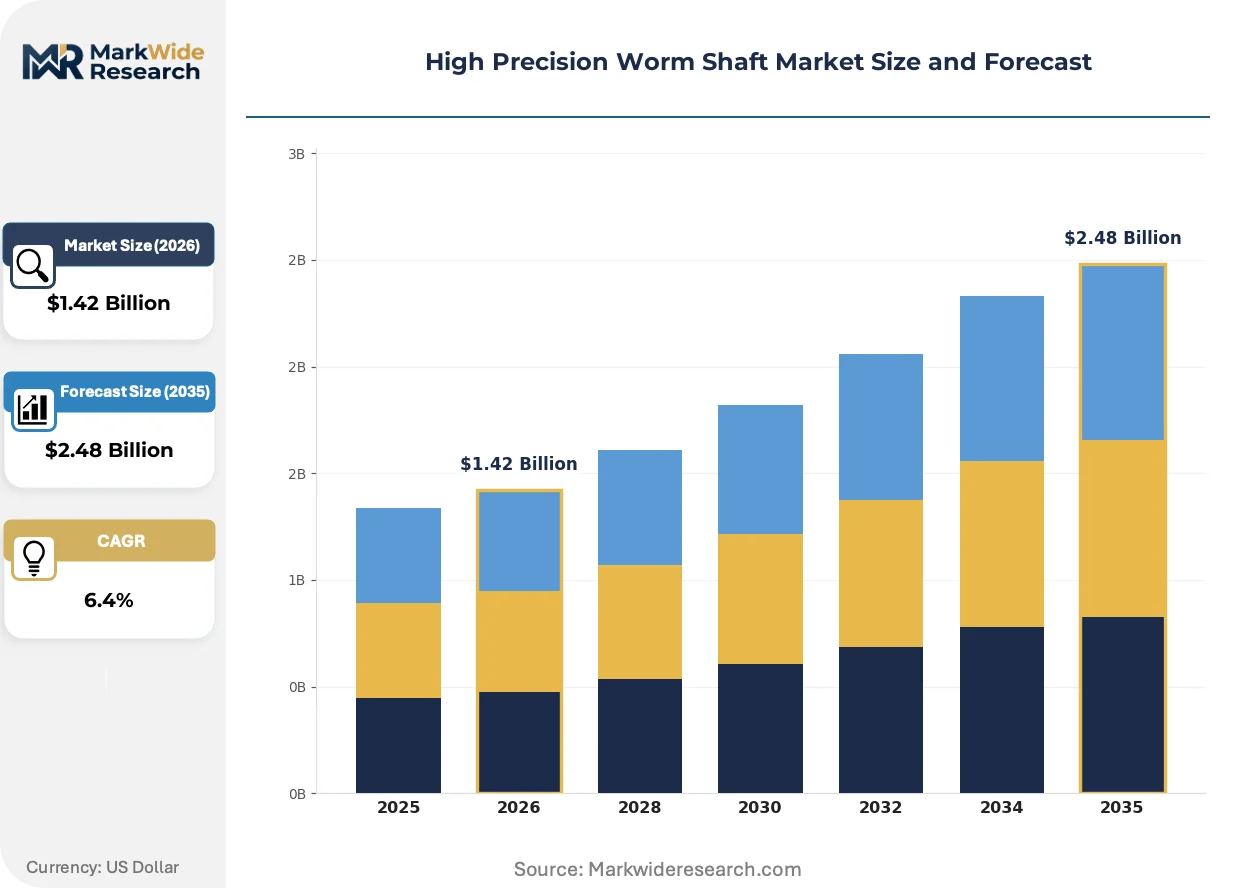
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Start Worm Shaft, Double-Start Worm Shaft, Multi-Start Worm Shaft, Threaded Worm Shaft, Helical Worm Shaft Material: Steel Alloy, Stainless Steel, Brass, Bronze, Hardened Steel, Aluminum Application: Machine Tools, Robotics, Aerospace Equipment, Packaging Machines, Textiles, Printing Presses End User: Automated Manufacturing Firms, Precision Engineering Workshops, Defense Contractors, Aerospace Assemblers, Robotics Integrators |
| Companies Covered | Shuanghuan Transmission, Jingduan Technology, ZOMAX, Zhejiang Guangjin Intelligent Technology, KLINGELNBERG, KHK Gears, Harmonic Drive Systems, SEW-EURODRIVE, Bonfiglioli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Precision Worm Shaft Market Trends and Innovations
Precision worm shaft production is bifurcating between captive integrated manufacturing for system OEMs and specialized toll grinding houses serving fragmented rebuild demand.
Cubic boron nitride (CBN) grinding wheels with optimized bond structures are extending tool life during hardened steel finishing. Aerospace actuator suppliers in Japan and Germany are adopting these abrasives to reduce wheel changeover frequency. Conventional aluminum oxide grinding is rendering obsolete for DIN 3962 Class 4 and finer specifications.
REACH substance restrictions on chromium-based coatings are forcing producers to qualify alternative surface treatments for corrosion resistance. ECHA's evolving candidate list is compelling worm shaft suppliers to document material composition down to 0.1% weight thresholds. Medical automation OEMs in Switzerland and Germany are responding by consolidating supplier bases to those with established chemical compliance databases.
Machine tool rebuild specialists are compressing procurement cycles from annual blanket orders to monthly call-offs tied to shop-floor utilization. This pattern disrupts traditional distributor stocking models and favors regional grinding houses with flexible batch capacities. China's machine tool rebuild sector exhibits this behavioral shift most visibly, with Yangtze and Pearl River Delta operators sourcing worm sets on 15-day lead times.
High Precision Worm Shaft Market Segmentation
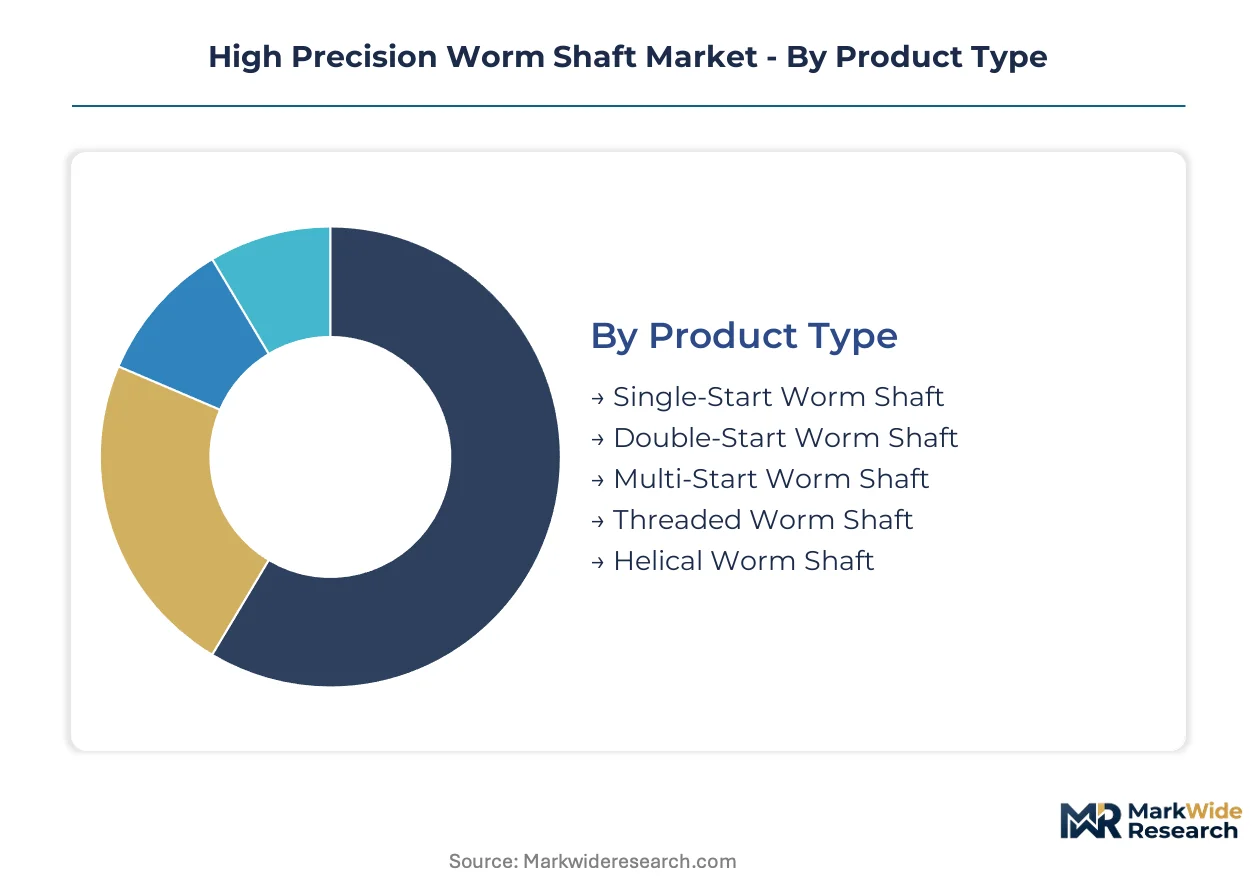
Precision worm shaft procurement patterns diverge sharply across product geometries, material specifications, and end-use rigor. Each segmentation axis reveals distinct margin structures and certification requirements that reshape supplier qualification criteria.
Product Type:
Single-start geometries dominate legacy machine tool retrofits where cost sensitivity outweighs traverse speed requirements. Multi-start variants command premium positioning in robotics and aerospace actuators demanding rapid positioning with minimal backlash.
- Single-Start Worm Shaft:One continuous thread wraps the cylindrical body, delivering maximum reduction ratios per revolution. German machine tool rebuilders specify these for legacy CNC axes where holding torque precision outweighs rapid traverse needs. DIN 3962 Class 4 certification remains standard for this mature tier.
- Multi-Start Worm Shaft:Multiple parallel threads advance the worm wheel faster per input rotation. Robotics integrators in Japan and Switzerland specify these for collaborative robot joints requiring quick positioning cycles without sacrificing repeatability. AGMA 14 surface finish validation separates qualified suppliers from commodity producers.
- Double-Start Worm Shaft:Intermediate geometry balancing reduction ratio against traverse speed for mid-precision automation equipment.
- Threaded Worm Shaft:Modified tooth profile optimized for specific meshing conditions in custom actuator assemblies.
- Helical Worm Shaft:Spiral tooth arrangement distributing load across multiple contact points for heavy-duty transmission applications.
Established volume favors Single-Start configurations; emerging adoption favors Multi-Start geometries in next-generation robotics.
Material:
Cost tiers stratify around heat-treatment energy intensity and alloy traceability documentation. Hardened steel and stainless grades absorb REACH compliance costs that disqualify smaller grinding houses.
- Hardened Steel:Through-hardened or case-hardened grades deliver wear resistance for continuous-cycle automated manufacturing. China's SAMR enforces GB material traceability for domestically produced machine tools, tightening import substitution criteria for this grade.
- Stainless Steel:Corrosion-resistant grades satisfy FDA device-quality requirements for medical automation and packaging machinery. Swiss and German OEMs consolidate supplier bases to those with established chemical compliance databases documenting composition down to 0.1% weight thresholds.
- Steel Alloy:Balanced mechanical properties for general industrial transmission applications.
- Brass:Lower friction coefficient suited for light-load positioning mechanisms.
- Bronze:Excellent machinability for prototype and low-volume custom worm sets.
- Aluminum:Weight-critical aerospace actuator applications where load ratings permit reduced material density.
Procurement concentrates in Hardened Steel for volume automation; Stainless Steel climbs fastest on medical and food-contact regulatory mandates.
Application:
End-use certification intensity determines supplier qualification barriers. Aerospace and medical tiers demand extended third-party metrology queues that delay revenue recognition.
- Robotics:Multi-start worm shafts enable rapid traverse with holding torque in collaborative and industrial robot joints. Japan's METI references JIS B 1741 gear accuracy classes in industrial robot certification pathways, elevating minimum tolerances for components in this channel.
- Aerospace Equipment:Precision actuators for flight control surfaces and landing gear mechanisms require AGMA 14-quality surfaces with full material pedigree documentation. Hybrid manufacturing combining selective laser melting with precision grinding enables complex internal cooling geometries for this segment.
- Machine Tools:Positioning axes and rotary tables for metal cutting equipment.
- Packaging Machines:High-speed filling and sealing equipment requiring FDA-compliant surface finishes.
- Textiles:Yarn tensioning and loom drive mechanisms.
- Printing Presses:Registration control and ink roller positioning systems.
Machine Tools anchor current procurement volumes; Aerospace Equipment and Robotics expand most quickly on precision automation trends.
End User:
Customer type dictates contract structures and technical service intensity. Defense and aerospace assemblers impose captive supply chain requirements that exclude independent grinding houses.
- Robotics Integrators:Automated manufacturing firms pursuing tighter positional accuracy specify certified worm shaft suppliers with documented surface finish traceability. Monthly call-offs tied to shop-floor utilization are compressing procurement cycles from annual blanket orders.
- Aerospace Assemblers:Tier-1 suppliers to commercial and defense aviation programs demand full material pedigree and extended validation protocols. Germany's KBA and Japan's METI both reference JIS B 1741 gear accuracy classes in certification pathways for this end user category.
- Automated Manufacturing Firms:System OEMs integrating worm drives into production equipment.
- Precision Engineering Workshops:Independent rebuild specialists sourcing replacement sets outside captive OEM channels.
- Defense Contractors:Military specification components with security-cleared supply chain requirements.
Automated Manufacturing Firms generate the largest order flow; Robotics Integrators and Aerospace Assemblers drive specification escalation and margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-machining exports supply automated manufacturing corridors across Switzerland and Austria, establishing a trade-flow corridor that anchors European worm shaft procurement. Chinese producers simultaneously penetrate Southeast Asian machine tool rebuild markets through Yangtze River Delta manufacturing clusters.
Germany
Industrial automation OEMs in Baden-Württemberg and Bavaria specify DIN 3962 Class 4 worm shafts for robotic positioning systems. KBA certification pathways reference JIS B 1741 gear accuracy classes, elevating minimum tolerances for automotive suppliers. Stuttgart's industrial automation corridor hosts captive gear manufacturing integrated with drive systems production.
China
SAMR enforcement of GB standards tightens import substitution criteria for domestically produced machine tools. Dual carbon goals reroute heat-treatment energy costs, compressing margins on hardened steel grades. Yangtze River Delta rebuild specialists source replacement worm sets on 15-day lead times, disrupting traditional distributor models.
Japan
METI references JIS B 1741 gear accuracy classes in industrial robot certification pathways, driving specification escalation for collaborative robot joints. Nagoya's precision engineering cluster adopts cubic boron nitride grinding wheels to reduce wheel changeover frequency. Aerospace actuator suppliers in Kanto pursue AGMA 14-quality surfaces with full material pedigree documentation.
Switzerland
Medical automation OEMs consolidate supplier bases to those with established REACH chemical compliance databases documenting composition down to 0.1% weight thresholds. Swissmedic device-quality requirements shape specifications for worm shafts deployed in packaging machines. Geneva-Zurich corridor firms document surface finish traceability under EU machinery directives.
India
PLI scheme for machine tools offers production-linked incentives to precision component makers supplying hardened worm sets to domestic CNC rebuild channels. BIS standards enforcement elevates minimum tolerances for precision transmission components. Maharashtra and Gujarat machine tool operators compress procurement cycles from annual blanket orders to monthly call-offs.
High Precision Worm Shaft Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure. Captive integrated manufacturers serving system OEMs dominate volume tiers, while specialized toll grinding houses capture fragmented rebuild demand. Three archetypes define competitive positioning: metrology-linked precision specialists, scale-driven hardened steel suppliers, and hybrid manufacturing integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms absorb capital costs for continuous-profile grinding technology.
Among German-based precision specialists, KLINGELNBERG and SEW-EURODRIVE occupy positions anchoring European supply through captive manufacturing and metrology-linked production. Chinese scale-driven producers including Shuanghuan Transmission exemplify the hardened steel supplier archetype, supplying worm sets to expanding machine tool rebuild sectors. These three entities represent the structural tension between precision-tier certification and volume-tier cost positioning that shapes supplier qualification criteria across robotics and aerospace channels.
| Leading Market Players |
|---|
| Shuanghuan Transmission |
| Jingduan Technology |
| ZOMAX |
| Zhejiang Guangjin Intelligent Technology |
| KLINGELNBERG |
| KHK Gears |
| Harmonic Drive Systems |
| SEW-EURODRIVE |
| Bonfiglioli |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Japan's precision grinding sector is elevating pricing power for KLINGELNBERG-class metrology-linked producers while compressing margins at conventional hobbing operations forced to absorb capital costs or exit high-precision tiers entirely.
Pricing Analysis
Cost-plus contracts indexed to nickel and cobalt alloy benchmarks dominate hardened steel procurement, with DIN 3962 Class 4 certification commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates AGMA 14-validated medical-grade suppliers from commodity machine-tool rebuild channels. Cost compression in standard-tier hardened steel is intensifying because China's dual carbon goals reroute heat-treatment energy costs. Robotics integrators exhibit lowest price sensitivity; Yangtze River Delta rebuild specialists show highest sensitivity.
Supply Chain Analysis
Export controls on cubic boron nitride grinding wheel technology limit flows from German and Japanese producers to Chinese grinding houses, constraining capacity expansion in precision tiers. Supply concentrates in Germany, Japan, and China for finished worm shafts, with raw material dependencies on Swedish bearing-grade steel, Austrian tool steel, and Chinese rare-earth elements for advanced abrasives. Single-source vulnerability runs through KLINGELNBERG-class measuring centers concentrated in Stuttgart and Nagoya. Distribution runs through captive OEM channels for aerospace assemblers and independent toll grinding houses for machine tool rebuild demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision worm shaft procurement is evolving into a service-attach opportunity as aftermarket rebuild specialists in China's Yangtze River Delta expand monthly call-off arrangements faster than new equipment hardware sales.
For Market Incumbents: Insulate AGMA 14-certified production tiers from price erosion by consolidating captive metrology capacity in Germany and Japan before REACH material restrictions disqualify smaller competitors. Backward integration into heat-treatment energy sourcing offsets dual carbon cost compression. Certification investment in FDA device-quality documentation creates switching costs for medical automation OEMs in Switzerland. For New Entrants and Emerging Players: India's underpenetrated CNC rebuild channel offers production-linked incentive access for hardened steel worm set suppliers qualifying under BIS standards. Target precision engineering workshops in Maharashtra and Gujarat with flexible batch capacities and 15-day lead time commitments. Partner with established European metrology houses for third-party surface finish validation rather than owning capital-intensive grinding assets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among toll grinding houses serving fragmented rebuild demand with monthly call-off contracts rather than annual blanket orders. Long-term viability centers on hybrid manufacturing capabilities combining selective laser melting with precision grinding for aerospace actuator applications. Watch for inflection when India's PLI scheme disbursements accelerate domestic machine tool production beyond current import substitution thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Profile Grinding Capacity Expansion | Captures DIN 3962 Class 4 and finer specifications as conventional hobbing exits high-precision tiers. |
| Hybrid Manufacturing Technology Adoption | Enables complex internal cooling geometries for aerospace actuators through selective laser melting integration. |
| REACH Compliance Database Investment | Documents material composition to 0.1% weight thresholds for Swiss and German medical automation OEMs. |
| Aftermarket Service Unbundling | Supplies replacement worm sets outside captive OEM channels to Yangtze River Delta rebuild specialists. |
| Production-Linked Incentive Qualification | Accesses India's PLI scheme by supplying hardened worm sets to domestic CNC rebuild channels. |
Research Methodology
Desk research of customs trade databases, JIS B 1741 certification registries, and SAMR GB standards filings preceded structured interviews with continuous-profile grinding operators, robotics integrator procurement heads, aerospace actuator design engineers, and machine tool rebuild specialists. Primary fieldwork across Germany's Baden-Württemberg corridor, Japan's Nagoya precision cluster, and China's Yangtze River Delta validated secondary findings. Bottom-up unit economics triangulated against top-down sector expenditure estimates.
Assumptions held fixed include current REACH substance restriction timelines and JIS B 1741 gear accuracy class enforcement patterns; alloy sourcing volatility and dual carbon policy intensity were varied across scenarios. Segmentation modeling covered product geometry, material specification, end-use certification intensity, and regional regulatory cluster. CAGRs derived from slope-log regression on validated data points across the analysis window. Forecast inputs included robotics deployment trajectories and machine tool rebuild cycle frequencies.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese scale-driven producers or accelerated substitution by direct-drive motor architectures would shift outcomes. Material shifts in ECHA candidate list evolution or METI robot certification pathway revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market