
 Industrial Spindles Market | 2026-2036
Industrial Spindles Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Spindles Market Foresight
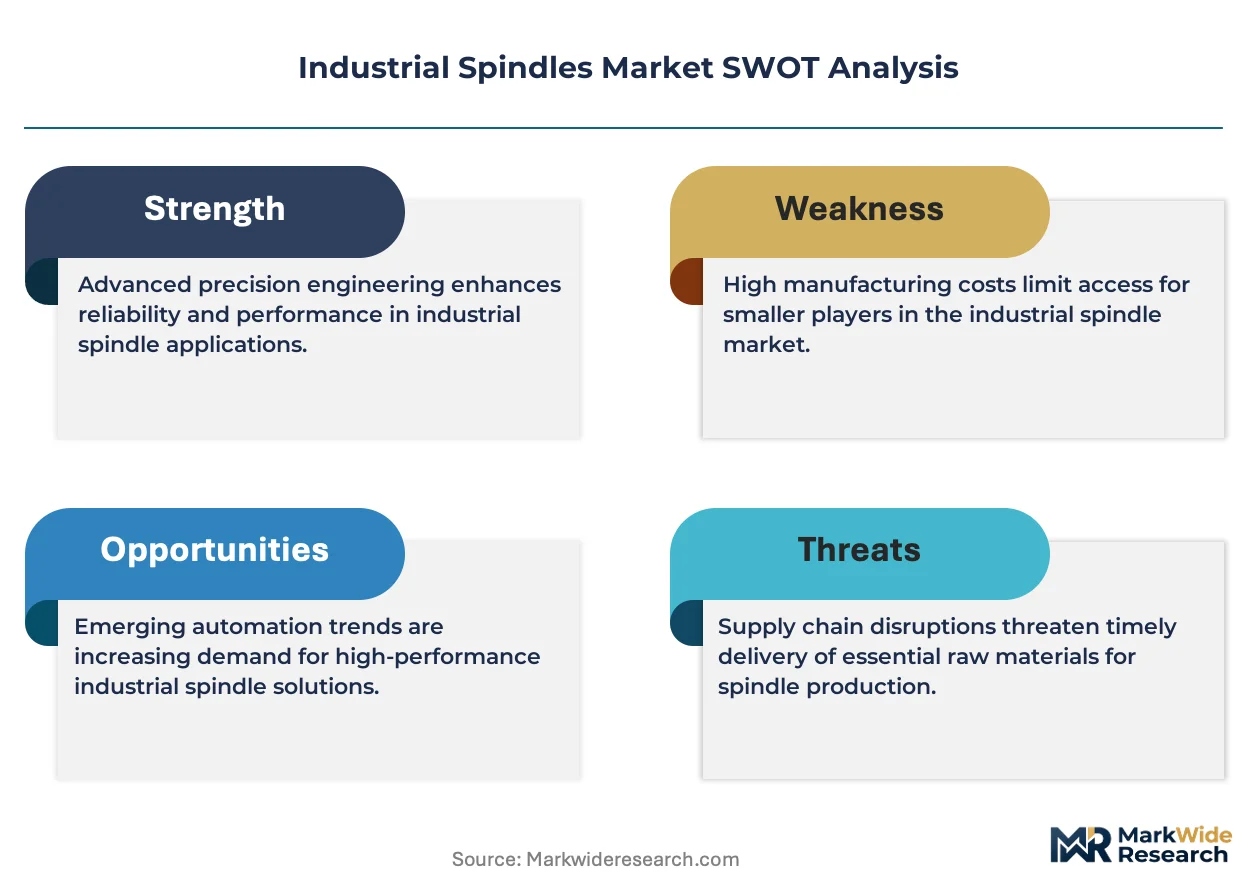
Precision-grade spindle specifications is rotating toward higher RPM tolerances and thermal stability benchmarks as OEMs recalibrate capital equipment plans. SycoTec GmbH & Co. KG leverages its German engineering base to dominate compact high-speed motor spindle architectures. Setco Inc anchors North American aftermarket service networks for heavy-duty machine tool rebuilds. SKF AB extends bearing integration expertise into sealed spindle cartridge designs that reduce contamination failure rates.
Industrial spindles are rotating assemblies that transmit power from a drive motor to a cutting tool or workpiece, typically operating at speeds from 1,000 to 100,000 RPM with runout tolerances measured in micrometers; they incorporate precision bearings, shaft housings, and cooling channels to maintain dimensional accuracy during material removal operations. High-speed spindles lead technology segment value pools because aerospace firms pay premiums for titanium and Inconel machining capability. Electromechanical drives displace mechanical belt-drive configurations in milling applications where variable speed control improves surface finish consistency. Precision spindles occupy the fastest-expanding product tier as machinery producers specify ISO 10791-tested units for five-axis machining centers.
CE marking under the EU Machinery Directive and ISO 230 vibration testing protocols shape European spindle procurement, while China's GB/T 17421 machine tool standards enforce domestic certification for imported precision assemblies. The US Occupational Safety and Health Administration lockout/tagout rules and NHTSA traceability requirements for automotive tooling chains add compliance layers that filter supplier qualification. Stakeholders must monitor how magnetically driven and direct drive technologies alter maintenance intervals and total cost of ownership calculations against conventional bearing systems.
Market Dynamics
Electromechanical direct-drive architectures are compressing maintenance intervals and recalibrating total cost of ownership calculations against conventional bearing systems, forcing OEMs to requalify supplier portfolios around sealed cartridge designs and thermal stability benchmarks.
Growth Catalysts
- ISO 230 vibration testing protocols:European machine tool builders now mandate certified precision tiers, accelerating replacement cycles for legacy belt-drive configurations in Germany's Baden-Württemberg cluster.
- Electric vehicle powertrain machining:Automotive OEMs specify high-speed spindles for titanium and Inconel cutting operations, concentrating demand in China's Yangtze River Delta manufacturing corridor.
- Five-axis machining center deployment:Aerospace contractors pay premiums for ISO 10791-tested units capable of micrometer runout tolerances at sustained RPM ranges.
Market Restraints
- Precision bearing supply concentration:Ceramic hybrid bearing production clusters in Japan and Germany create input cost volatility and extended lead times for tier-two spindle assemblers.
- CE marking compliance friction:The EU Machinery Directive's tightened safety requirements extend certification timelines by four to six months for non-European suppliers seeking market access.
- Magnetic levitation substitution threat:Magnetically driven spindle prototypes eliminate mechanical bearing wear entirely, threatening incumbent cartridge architectures in ultra-precision applications.
Strategic Opportunities
- Aftermarket service unbundling:Independent rebuild specialists capture margin pools previously held by original equipment manufacturers through predictive maintenance contracts and remanufactured cartridge programs.
- India's PLI scheme for machine tools:Production-linked incentives attract spindle component suppliers to establish localized assembly operations serving domestic automotive and defense machining demand.
- Direct drive-electromechanical convergence:Variable frequency drive integration with permanent magnet motors enables real-time speed control without mechanical transmission losses.
Industry Challenges
- Thermal management engineering scarcity:Spindle designers with expertise in computational fluid dynamics for cooling channel optimization command premium compensation and extended recruitment cycles.
- Legacy CNC controller integration:New sealed cartridge designs require protocol adaptation for Fanuc and Siemens control architectures, complicating retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Spindles Market |
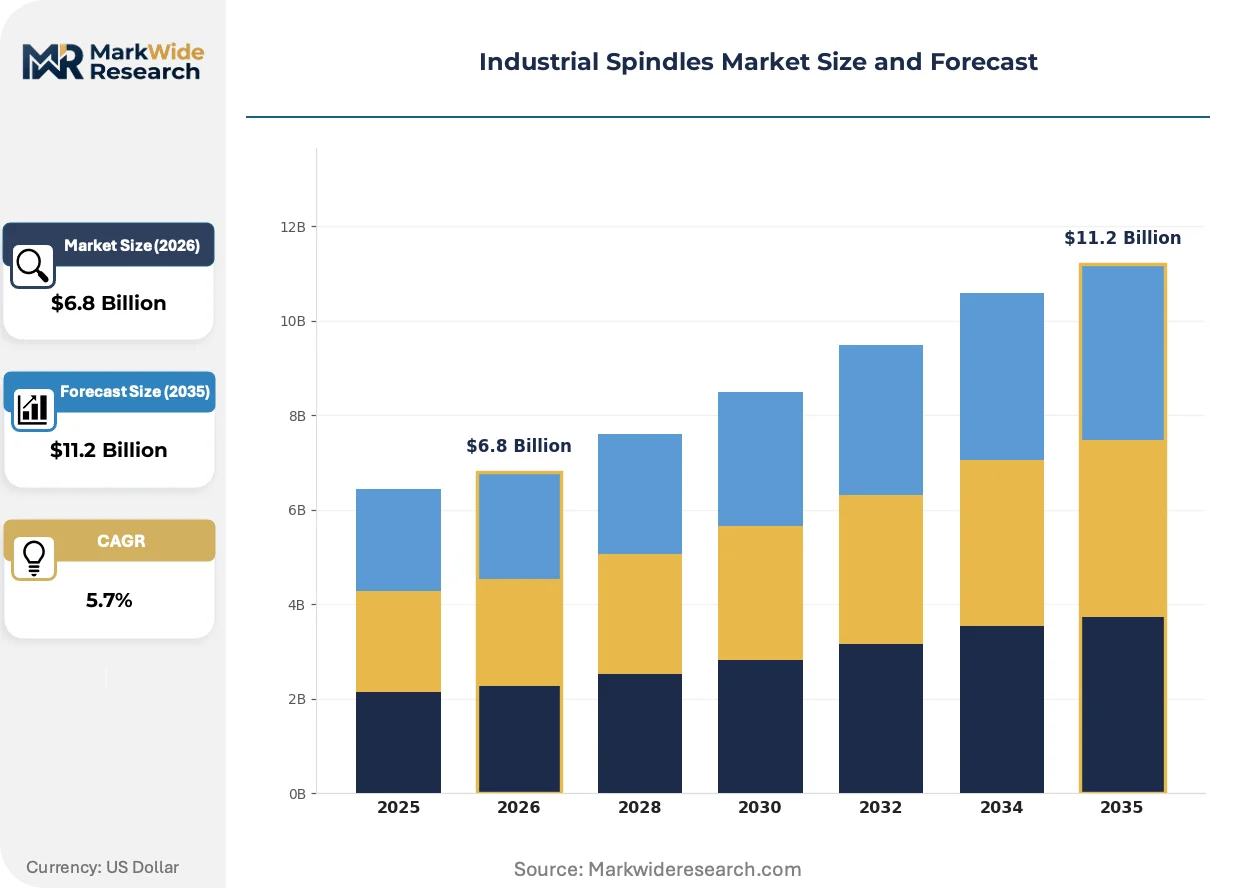
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Spindles, Horizontal Spindles, High-Speed Spindles, Precision Spindles End User: Automotive Manufacturers, Aerospace Firms, Textile Industries, Machinery Producers Technology: Mechanical Drives, Electromechanical Drives, Magnetically Driven, Direct Drive Application: Milling, Drilling, Grinding, Turning |
| Companies Covered | SycoTec GmbH & Co. KG, Setco Inc, TDM Spindles SA, GMN Paul Müller Industrie GmbH & Co. KG, FISCHER Spindle Technology, NSK Ltd., SKF AB, IBAG Spindle Technology, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Spindles Market Shifts & Advancements
Active magnetic bearing systems are compressing traditional mechanical maintenance models while thermal compensation algorithms rewrite precision machining economics. These shifts recalibrate supplier capabilities around sensor integration and real-time diagnostics rather than purely mechanical engineering excellence.
Direct-drive permanent magnet motor spindles are fragmenting the established belt-drive and gear-driven transmission markets. Aerospace titanium machining contractors in the US Pacific Northwest adopt these units for their instantaneous torque response and elimination of belt resonance. The technology is fragmenting aftermarket service revenue streams as sealed electromechanical cartridges reduce field-rebuild frequency.
REACH substance restrictions and the EU F-Gas Regulation are phasing out perfluorinated lubricants and specific cooling fluids used in high-speed bearing assemblies. Spindle manufacturers reformulate lubrication systems with synthetic ester bases to maintain thermal transfer coefficients. German and Swiss precision tool builders face the steepest compliance costs, accelerating their vertical integration into fluid chemistry development.
Buyer consolidation among contract manufacturers is compressing procurement cycles and unbundling after-sales service from initial equipment purchases. Tier-one automotive suppliers in Mexico's Bajío industrial corridor now source spindles through centralized global procurement functions rather than plant-level engineering decisions. This concentration forces spindle vendors to standardize configuration options and absorb customization costs into base pricing.
Industrial Spindles Market Segmentation
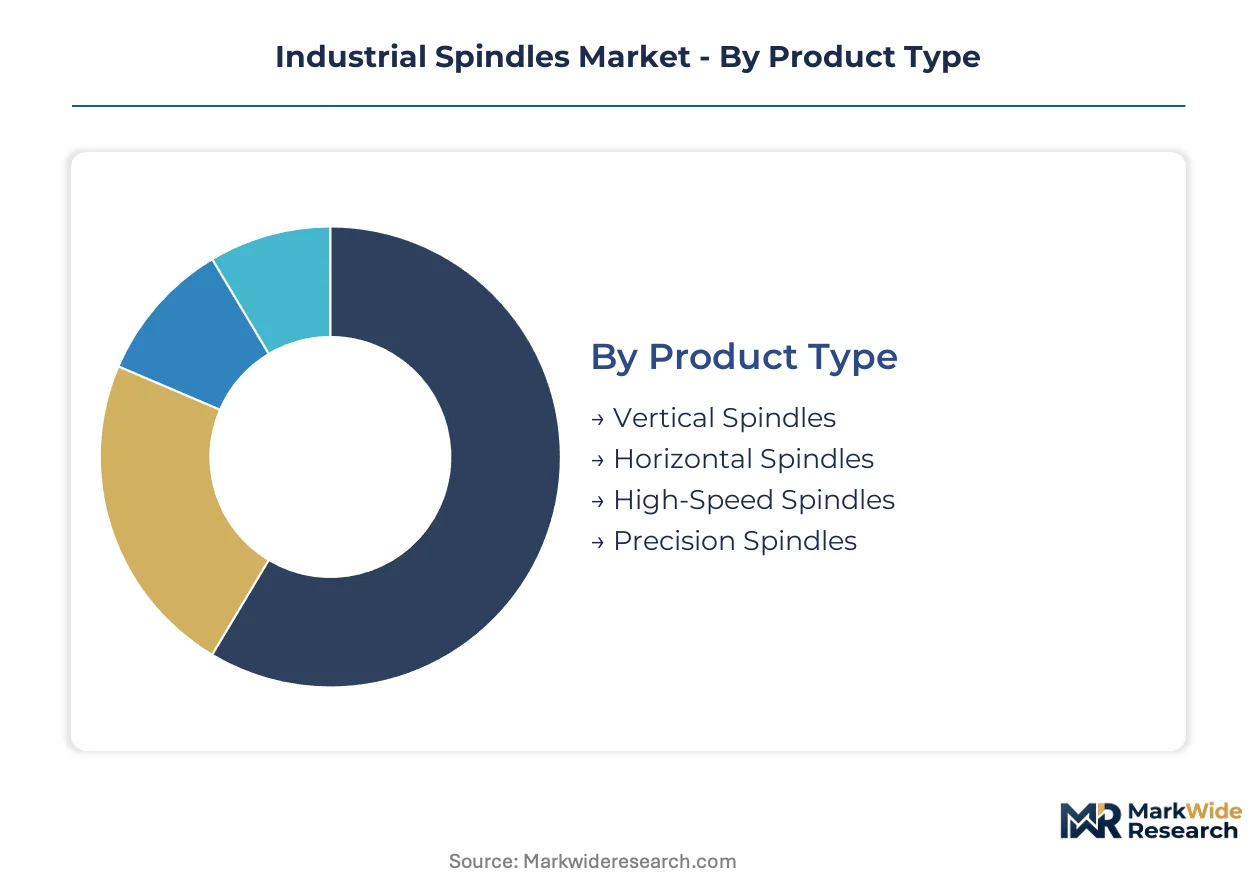
Industrial spindle procurement patterns diverge sharply across product architectures, end-use specifications, and drive technologies. Buyers calibrate capital allocation differently when specifying units for automotive powertrain machining versus aerospace titanium finishing, creating distinct margin pools and supplier qualification hurdles.
Product Type:
Magnetically driven alternatives threaten mechanical bearing architectures most acutely in the ultra-precision tier, compressing addressable demand for conventional cartridge designs in semiconductor and optics applications.
- High-Speed Spindles:These assemblies operate above 30,000 RPM with ceramic hybrid bearings and forced oil-air lubrication systems. Aerospace contractors in Germany's Baden-Württemberg cluster specify these units for Inconel turbine blade machining, paying premiums for sustained thermal stability during extended cutting cycles.
- Precision Spindles:ISO 10791-tested units with micrometer runout tolerances dominate five-axis machining center specifications. Machinery producers in China's Yangtze River Delta manufacturing corridor now mandate these certified tiers for export-qualified equipment, accelerating displacement of standard-grade alternatives.
- Vertical Spindles:Column-mounted configurations serve heavy-duty milling applications in automotive fixture production.
- Horizontal Spindles:These units enable chip evacuation in deep-cavity mold machining for consumer electronics tooling.
High-Speed Spindles retain volume leadership; Precision Spindles hold the steepest expansion curve.
End User:
Capital equipment budgets concentrate in sectors facing regulatory traceability mandates, with automotive and aerospace OEMs commanding tier-one supplier attention through multi-year framework agreements.
- Automotive Manufacturers:Electric vehicle powertrain machining drives demand for spindles capable of aluminum housing and copper winding slot operations. Tier-one suppliers in Mexico's Bajío industrial corridor now source through centralized global procurement functions, compressing vendor negotiation cycles.
- Aerospace Firms:Titanium and Inconel machining requirements specify thermal compensation algorithms and active vibration damping. US Pacific Northwest contractors adopt direct-drive permanent magnet units for instantaneous torque response in thin-wall structural component finishing.
- Machinery Producers:General-purpose machine tool builders face margin pressure from buyer consolidation among contract manufacturers.
- Textile Industries:Yarn twisting and winding applications specify lower-speed belt-drive configurations with reduced precision requirements.
Automotive Manufacturers dominate procurement volume; Aerospace Firms generate the highest per-unit margin realization.
Technology:
Electromechanical architectures are fragmenting established transmission markets, with variable frequency drive integration eliminating mechanical losses that previously constrained surface finish consistency.
- Electromechanical Drives:Permanent magnet motor integration with sealed cartridge designs reduces contamination failure rates and extends maintenance intervals. These units are displacing belt-drive configurations in milling applications where real-time speed control improves dimensional accuracy.
- Direct Drive:Elimination of mechanical transmission components enables instantaneous torque response and removes belt resonance artifacts. The technology compresses aftermarket service revenue streams as sealed electromechanical cartridges reduce field-rebuild frequency.
- Mechanical Drives:Belt and gear configurations persist in cost-sensitive drilling and turning applications with fixed speed requirements.
- Magnetically Driven:Active magnetic bearing prototypes eliminate mechanical wear entirely, threatening incumbent architectures in ultra-precision semiconductor wafer processing.
Electromechanical Drives command the largest installed base; Direct Drive is climbing the fastest among new equipment specifications.
Application:
Surface finish requirements and material removal rates create divergent spindle specification profiles, with multi-axis simultaneous operations demanding the most sophisticated thermal management engineering.
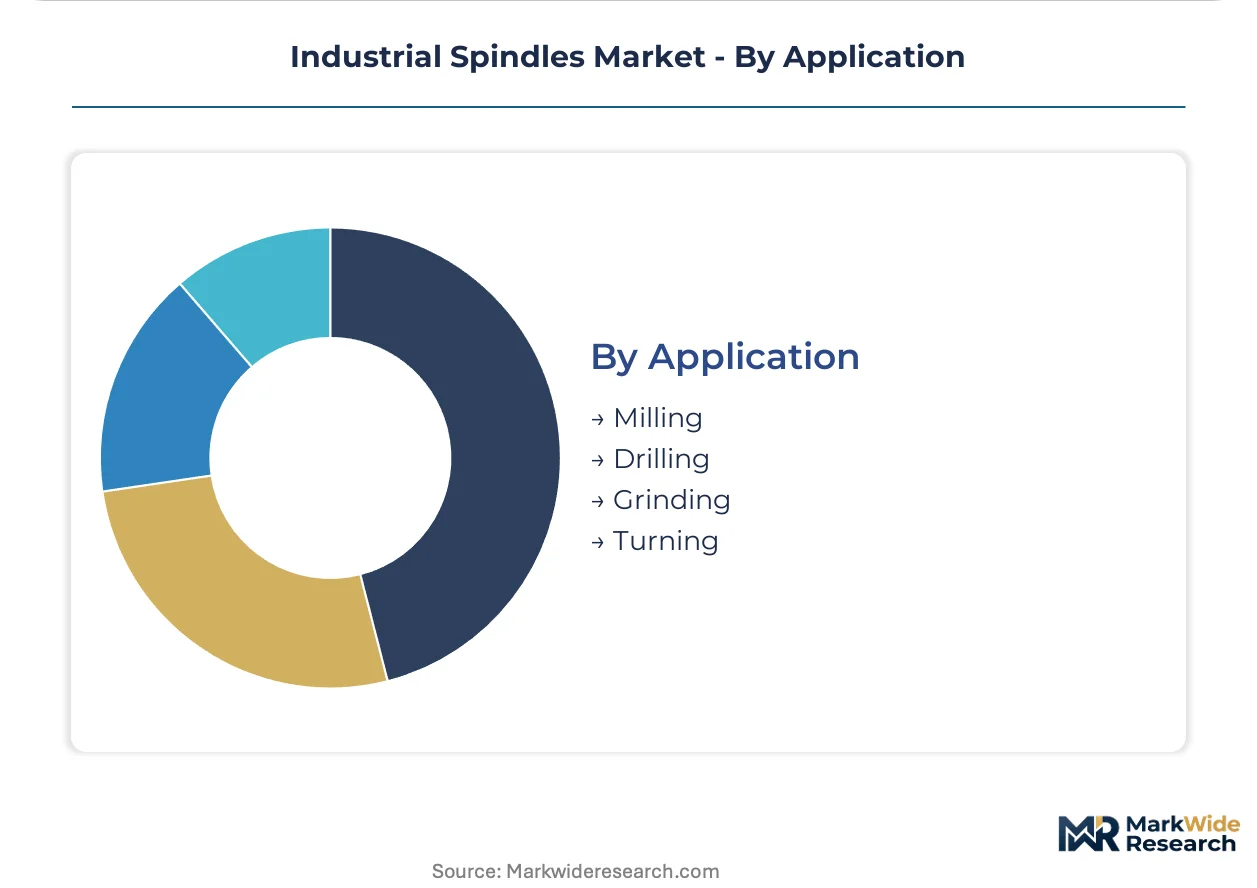
- Milling:Contour machining of complex geometries requires sustained RPM stability across varying load conditions. Five-axis applications specify sealed cartridge designs with computational fluid dynamics-optimized cooling channels to maintain dimensional accuracy during extended aluminum and titanium cutting cycles.
- Grinding:Surface and cylindrical finishing operations demand sub-micrometer runout tolerances and vibration isolation mounting. Precision bearing integration from SKF and NSK dominates this specification tier.
- Drilling:High-thrust operations in steel and cast iron favor rigid quill-mounted spindles with mechanical drive transmissions.
- Turning:Lathe applications specify integrated motor spindles with C-axis positioning capability for live tooling operations.
Milling absorbs the greatest equipment investment; Grinding commands the highest precision-grade pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Yangtze River Delta manufacturing corridor demonstrate the highest price elasticity for standard-grade belt-drive configurations, while aerospace contractors in Germany's Baden-Württemberg cluster absorb substantial premiums for ISO 10791-certified precision tiers.
Germany
Baden-Württemberg's machine tool cluster drives demand for high-speed spindles capable of Inconel turbine blade machining. CE marking requirements under the EU Machinery Directive and tightened ISO 230 vibration testing protocols filter supplier qualification. Stuttgart-based precision tool builders face steep REACH substance restriction compliance costs, accelerating captive supply of synthetic ester lubrication systems.
China
Automotive OEMs in the Yangtze River Delta specify electromechanical spindles for electric vehicle powertrain aluminum housing operations. GB/T 17421 machine tool standards enforce domestic certification for imported precision assemblies. Shanghai and Suzhou machinery producers now mandate ISO 10791-tested units for export-qualified five-axis machining centers.
United States
Aerospace titanium machining contractors in the Pacific Northwest adopt direct-drive permanent magnet units for thin-wall structural component finishing. OSHA lockout/tagout rules and NHTSA traceability requirements for automotive tooling chains add compliance layers. Boeing's supplier network in Washington State concentrates procurement of thermal-compensated spindle architectures.
Japan
Ceramic hybrid bearing production clusters create input cost volatility for tier-two spindle assemblers sourcing precision components. METI industrial policy supports machine tool builder consolidation. Nagoya-area automotive suppliers specify sealed cartridge designs with JIS-standard vibration isolation for powertrain machining lines.
India
The PLI scheme for machine tools attracts spindle component suppliers to establish localized assembly operations serving domestic automotive demand. BIS certification requirements filter imported precision assemblies. Tamil Nadu and Maharashtra manufacturing corridors concentrate five-axis machining center deployment for defense component production.
Industrial Spindles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with German and Swiss precision specialists commanding premium positioning while Asian fabricators capture volume tiers. The market structure consolidates around three strategic groupings: sealed cartridge electromechanical specialists, precision bearing integrators, and aftermarket service unbundlers. M&A activity concentrates on electromechanical drive technology acquisitions, while geographic expansion into India's PLI-subsidized manufacturing corridors represents the second dominant competitive vector.
Within the German engineering tier, SycoTec GmbH & Co. KG and GMN Paul Müller Industrie GmbH & Co. KG exemplify compact high-speed motor spindle architectures anchored in Baden-Württemberg's industrial base. SKF AB occupies a position among precision bearing integrators extending sealed cartridge designs. Setco Inc represents the North American aftermarket service archetype, with Inc.-structured entities dominating heavy-duty machine tool rebuild networks.
| Leading Market Players |
|---|
| SycoTec GmbH & Co. KG |
| Setco Inc |
| TDM Spindles SA |
| GMN Paul Müller Industrie GmbH & Co. KG |
| FISCHER Spindle Technology |
| NSK Ltd. |
| SKF AB |
| IBAG Spindle Technology |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Long-term framework agreements between tier-one automotive suppliers and sealed cartridge electromechanical specialists lock in both supply access and price visibility, compressing negotiation cycles in Mexico's Bajío industrial corridor while insulating buyers from ceramic hybrid bearing cost volatility.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across European procurement, separating ISO 10791-certified precision units from standard-grade belt-drive configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal stability benchmarks, with aerospace contractors in Germany's Baden-Württemberg cluster absorbing substantial premiums for sustained RPM tolerance. Cost compression in the standard tier is intensifying because buyer consolidation among contract manufacturers concentrates volume leverage. Textile industries in India demonstrate the highest price elasticity, while aerospace firms in the US Pacific Northwest show minimal sensitivity due to traceability mandates.
Supply Chain Analysis
Ceramic hybrid bearing production clusters in Japan and Germany create a chokepoint that underwrites input cost volatility for tier-two spindle assemblers sourcing precision components. Manufacturing gravity centers on Germany, China, and Japan, with raw material dependencies spanning silicon nitride ceramics, high-grade alloy steels, and synthetic ester lubricants. Single-source vulnerability in precision bearing supply threatens production continuity during demand spikes. Distribution runs through OEM direct channels and specialized industrial distributors serving machine tool builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical direct-drive fragmentation creates white-space opportunities across aftermarket service networks and regional assembly hubs, as sealed cartridge architectures displace rebuild-dependent legacy configurations.
For Market Incumbents: Shield precision bearing integration capabilities through captive supply of ceramic hybrid components, countering Japanese and German production concentration risks. Deepen thermal management engineering expertise to defend against magnetic levitation substitution in semiconductor wafer processing applications. Expand sealed cartridge remanufacturing programs to capture aftermarket margin pools previously held by independent rebuild specialists.
For New Entrants and Emerging Players: ISO 10791 certification fast-track through accredited testing laboratories in China's Yangtze River Delta unlocks access to export-qualified five-axis machining center specifications. Target India's PLI-subsidized machine tool corridors for localized assembly operations serving automotive and defense demand. Pursue predictive maintenance contract bundling as a go-to-market angle to differentiate from incumbent equipment-only positioning.
For Investors and Strategic Acquirers: Sealed cartridge electromechanical specialists with permanent magnet motor integration capabilities represent the most defensible acquisition target archetype for long-term viability. Monitor magnetically driven spindle prototype commercialization timelines as the critical inflection indicator threatening incumbent mechanical bearing architectures. Assess thermal compensation algorithm development pipelines as a secondary signal for technology leadership positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Bearing Supply | Captive production of silicon nitride components insulates margins from Japanese and German supply concentration. |
| Predictive Maintenance Contract Expansion | Sensor-integrated sealed cartridges enable real-time diagnostics that capture aftermarket revenue from independent rebuilders. |
| ISO 10791 Certification Investment | Third-party testing accreditation unlocks premium pricing tiers in aerospace and export-qualified machinery segments. |
| Magnetic Levitation R&D Partnership | Active bearing prototype development defends against substitution threats in semiconductor wafer processing applications. |
| India PLI Corridor Manufacturing Footprint | Localized assembly operations in Tamil Nadu and Maharashtra capture domestic automotive and defense procurement mandates. |
Research Methodology
A spread of perspectives from spindle design engineers, automotive procurement directors, aerospace manufacturing specialists, and aftermarket service heads converged on the working assumptions. Primary interviews with OEM technical teams and machine tool builder executives combined with secondary validation from customs trade data, SEC machinery filings, ISO certification registries, and regional industrial cluster reports. Bottom-up unit economics triangulated against top-down market sizing across electromechanical drive penetration curves.
Segmentation dimensions modeled include product architecture, drive technology, end-use industry, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from installed base replacement cycles and new equipment specification trends, incorporating electric vehicle powertrain machining demand curves and five-axis machining center deployment rates as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained ISO 230 enforcement and REACH substance restriction compliance costs; material deviation in magnetic levitation commercialization timelines would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation cooling fluid phase-outs and India's PLI subsidy extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Precision Engineering Machines Market