
 Precision Turned Product Manufacturing Market | 2026-2036
Precision Turned Product Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Turned Product Manufacturing Market Analytics
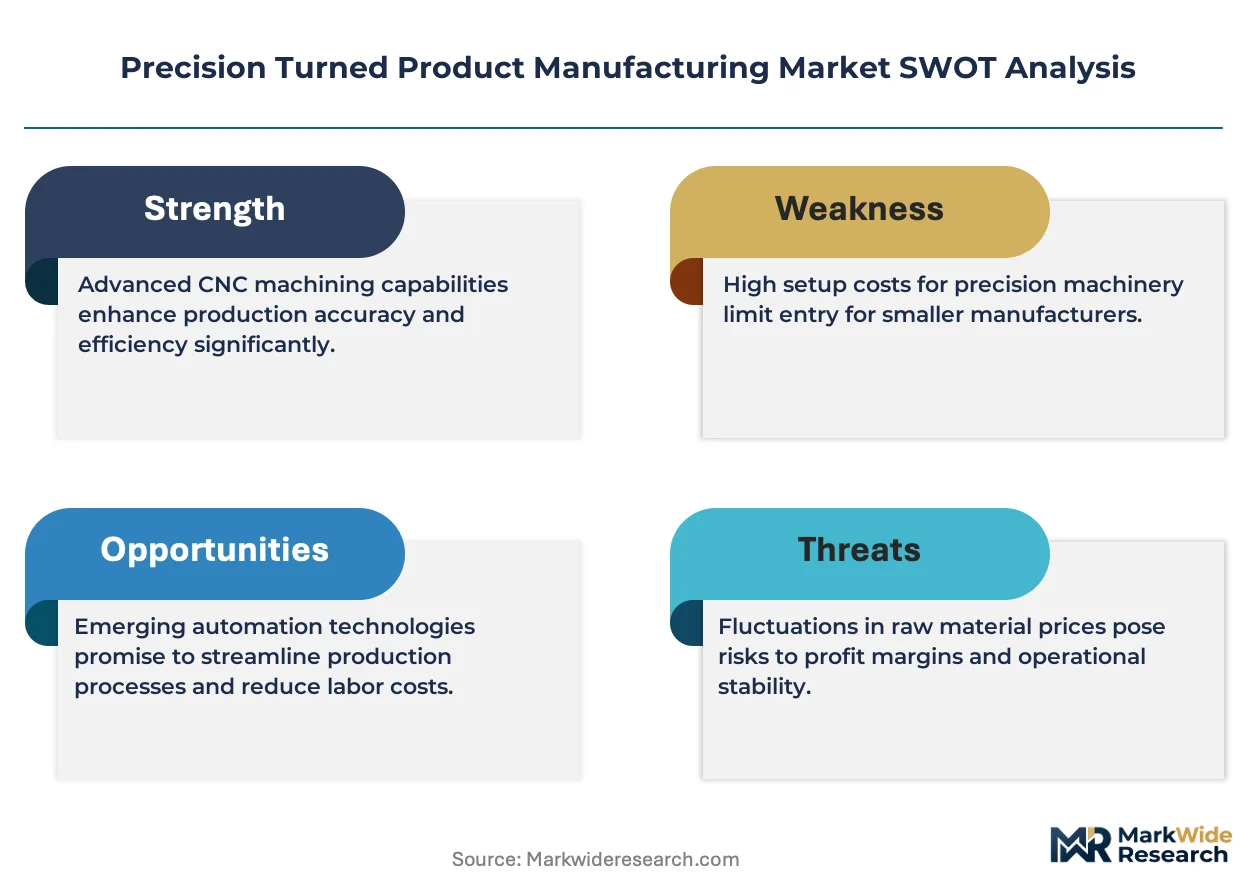
ISO 13485 medical device quality management certification is collapsing the supplier base for orthopedic implant turned components, disqualifying job shops lacking validated process documentation. GKN plc leverages its aerospace-grade superalloy turning capabilities across European engine programs. Sandvik AB anchors the tooling supply chain with cemented carbide insert geometries optimized for titanium machining. Citizen FINEDEVICE dominates high-volume medical component production through its L20 Swiss-type automatic lathe platform.
Precision turned products are cylindrical metal or polymer components produced on lathes or turning centers with dimensional tolerances typically held to ±0.005 mm, serving as critical mechanical interfaces in rotating assemblies, fluid systems, and structural joints. CNC Machining commands the largest value share due to its repeatability in aerospace fastener and hydraulic fitting production, while Laser Cutting represents the fastest-growing technology segment for pre-forming exotic alloys before finish turning. Medical Devices generates premium margin pools through small-lot validation requirements and material traceability protocols that commodity automotive suppliers cannot easily replicate.
FDA 21 CFR Part 820 quality system regulations govern U.S. medical turned product suppliers through design history file and process validation requirements, while REACH chemical restrictions in Europe constrain cutting fluid formulations and surface treatment chemistries. The EU AI Act's quality management expectations for smart manufacturing systems will soon extend to automated optical inspection stations on turning lines. Stakeholders must monitor how dual carbon goals in China and carbon border adjustments in Europe reshape raw material sourcing economics for brass and stainless steel bar stock.
Market Dynamics
Swiss-type CNC lathe automation is compressing lot-size economics while aerospace OEMs consolidate supplier panels around validated superalloy machining capabilities, forcing mid-tier job shops to choose between capital-intensive platform upgrades and exit from precision medical and aviation contracts.
Growth Catalysts
- EU Green Deal carbon-border adjustments:European suppliers are accelerating investment in energy-efficient turning operations to maintain export competitiveness against imports from regions with higher carbon intensity in bar stock production.
- Next-generation engine platforms:Aerospace OEMs are expanding procurement of titanium and Inconel turned components for advanced turbofan architectures requiring tighter dimensional tolerances at elevated operating temperatures.
- ISO 13485 certification concentration:Medical device quality management requirements are collapsing the supplier base for orthopedic implant components, concentrating contract awards among validated precision turners with documented process controls.
Market Restraints
- Tungsten and cobalt price volatility:Cemented carbide insert raw material costs fluctuate with mining supply disruptions, compressing tooling supplier margins and passing through to per-part machining economics.
- Baden-Württemberg supplier concentration:Germany's precision engineering cluster hosts a disproportionate share of mid-tier automotive and medical contract manufacturers, creating geographic risk in Tier 1 supply chains.
- REACH chemical restrictions:European cutting fluid formulations and surface treatment chemistries face constrained chemistries, limiting process latitude for high-performance alloys.
Strategic Opportunities
- EU AI Act quality management:Automated optical inspection stations on turning lines will soon require algorithmic validation protocols, creating first-mover advantage for shops integrating compliant smart manufacturing systems.
- Dual carbon goals in China:Domestic raw material sourcing economics for brass and stainless steel bar stock are reshaping, opening repositioning windows for suppliers with verified low-carbon supply chains.
- Additive-subtractive hybrid platforms:Near-net-shape pre-forms combined with finish turning operations are converging in medical implant production, enabling lot-size-one economics previously unattainable in precision machining.
Industry Challenges
- Swiss-type lathe operator scarcity:The specialized skill set for programming and tending multi-axis automatic lathes faces generational attrition, constraining capacity expansion at validated medical component suppliers.
- FDA 21 CFR Part 820 compliance timelines:Design history file and process validation requirements for U.S. medical device contracts extend new supplier qualification periods, freezing out capital-constrained job shops.
- Legacy ERP integration friction:Automated turning cells with real-time process monitoring require data architecture upgrades that conflict with decades-old shop floor management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Turned Product Manufacturing Market |
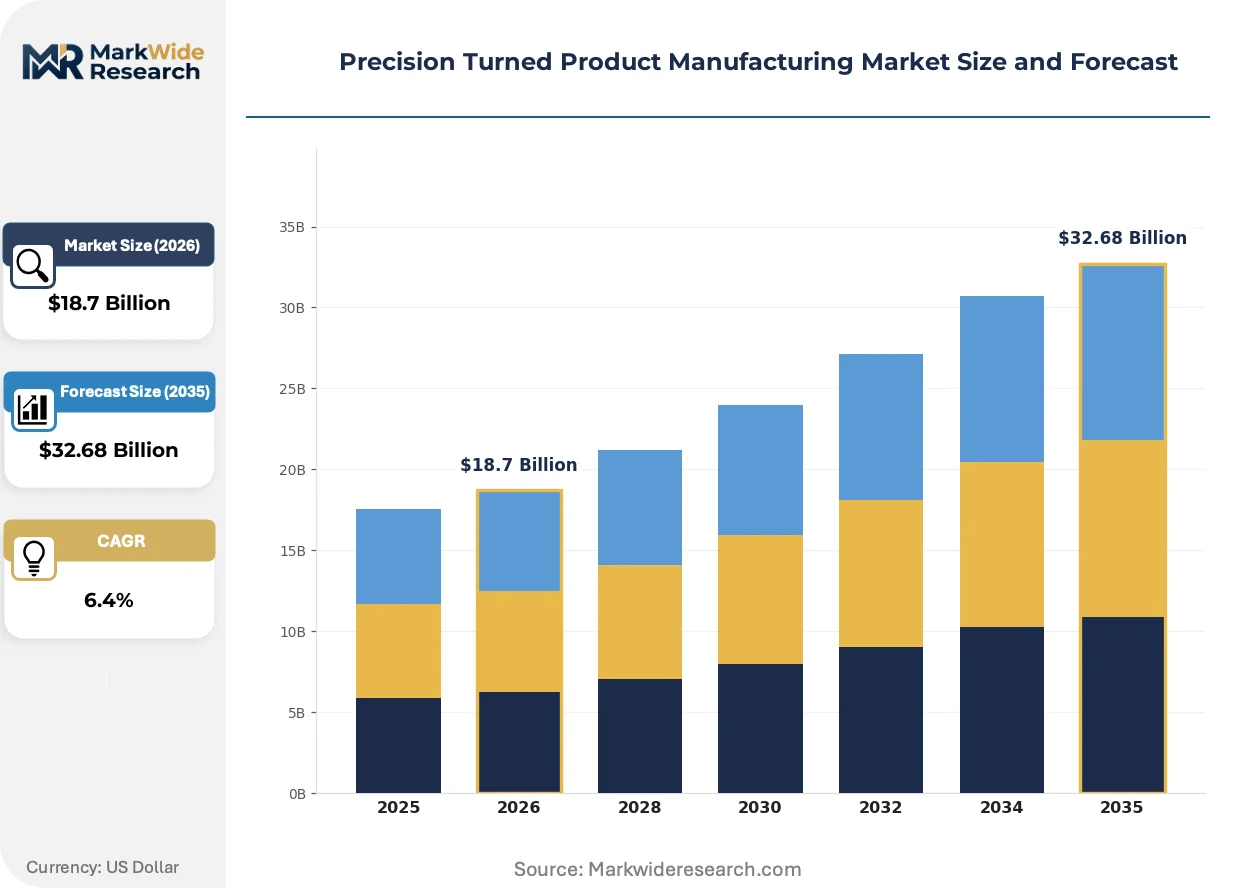
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Components, Assemblies, Fasteners, Fittings End User: Aerospace, Medical Devices, Automotive Parts, Electronics Material: Aluminum, Stainless Steel, Brass, Plastic Technology: CNC Machining, Laser Cutting, Waterjet Cutting, Manual Turning |
| Companies Covered | GKN plc, Citizen FINEDEVICE, Sandvik AB, Precision Castparts Corp., BorgWarner Inc., Kennametal Inc., Cox Manufacturing Co., Schunk Group, Mitsubishi Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Turned Product Manufacturing Market Evolving Landscape
Digital thread integration from CAD model to finished component is collapsing quality assurance cycles while regulatory mandates for material traceability are hardening data infrastructure requirements across precision machining operations.
Ultrasonic-assisted turning for nickel-based superalloys is supplanting conventional carbide machining in aerospace fastener production. Tier 1 engine contractors are adopting the technology to extend tool life and surface integrity in Inconel 718 components. The process is compressing per-part cycle times while enabling tighter dimensional control on critical rotating hardware.
REACH chemical restrictions are forcing reformulation of chlorinated and sulfurized cutting fluids across European precision turning operations. Suppliers are migrating to bio-based and synthetic alternatives with equivalent extreme-pressure performance. Medical device contract manufacturers in Germany and Switzerland face the steepest compliance timelines due to surface finish validation requirements.
Consignment inventory arrangements are displacing traditional spot purchasing for aerospace-grade bar stock. Tier 1 OEMs are pushing supply chain risk onto precision turners through vendor-managed inventory programs with 90-day rolling forecasts. The model concentrates most visibly in U.S. defense and commercial aviation supply chains where material traceability documentation requirements already mandate lot-level segregation.
Precision Turned Product Manufacturing Market Segmentation
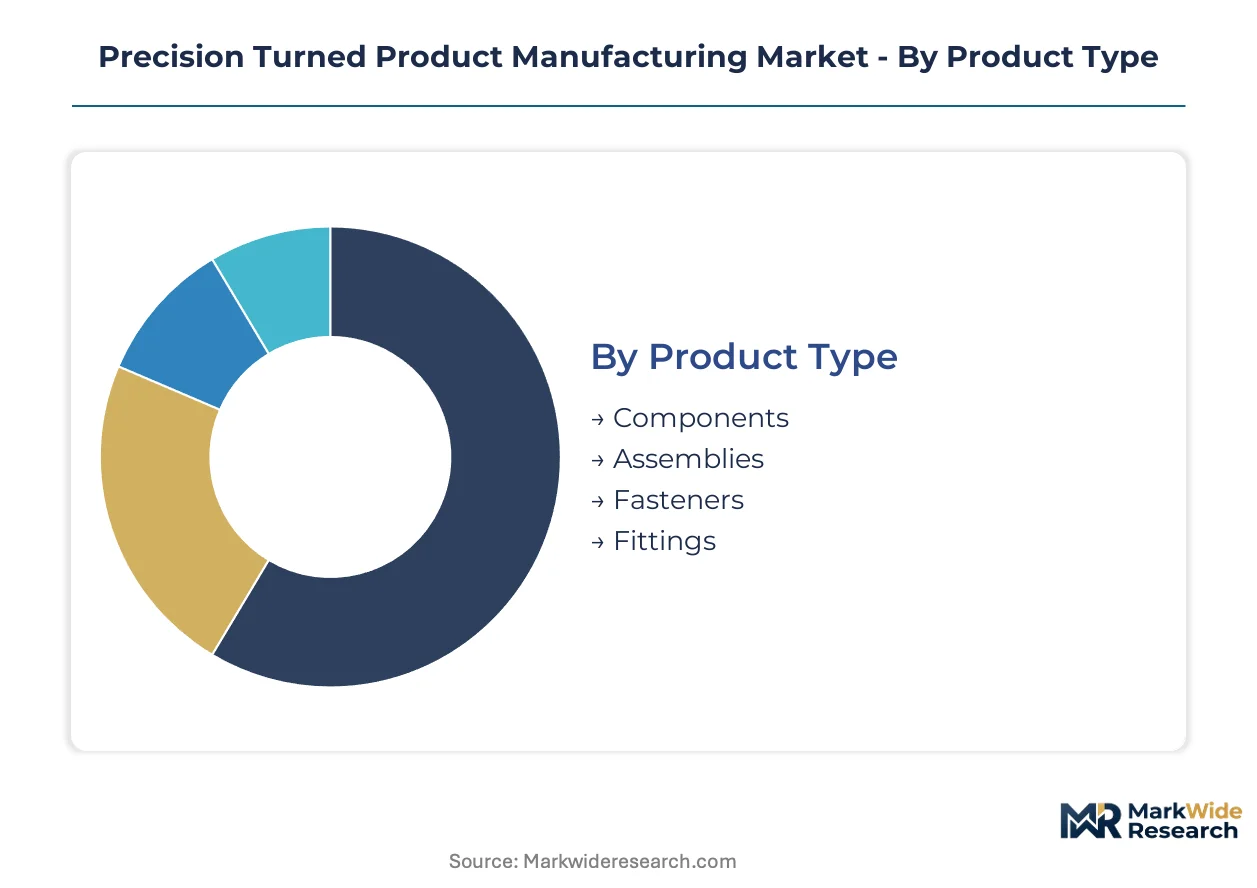
Segmentation in precision turned product manufacturing reveals how substitution pressures from additive manufacturing and cold forming reshape competitive boundaries across component categories. Distinct material, technology, and end-use fault lines determine which suppliers capture premium pricing versus commodity margin compression.
Product Type:
Substitution pressure from cold-headed fasteners and metal injection molding concentrates most intensely on standardized component categories, forcing precision turners toward geometrically complex segments where machining retains cost advantage.
- Components:Discrete cylindrical parts such as shafts, pins, and spacers requiring tight concentricity tolerances. Demand concentrates in Germany's Baden-Württemberg automotive supply cluster where Tier 1 drivetrain contracts require validated process documentation.
- Assemblies:Multi-part subsystems integrating turned elements with bearings, seals, or fasteners. Aerospace hydraulic manifold assemblies in U.S. defense supply chains drive specification tightening as OEMs consolidate supplier panels.
- Fasteners:Threaded hardware for structural and rotating joints. Cold heading captures high-volume standard threads; precision turning defends specialty aerospace fasteners in titanium and Inconel.
- Fittings:Fluid connection hardware for pneumatic and hydraulic systems. Medical device gas delivery fittings in Swiss and German orthopedic implant supply chains require ISO 13485 traceability protocols.
Components retain volume leadership; Assemblies hold the steepest expansion curve as OEM outsourcing deepens.
End User:
Cost tier stratification separates validation-intensive medical and aerospace contracts from price-sensitive automotive electronics procurement.
- Aerospace:Engine hardware, landing gear components, and airframe fasteners demanding superalloy machining expertise. Next-generation turbofan programs at U.S. and European OEMs expand titanium and Inconel turned component procurement.
- Medical Devices:Orthopedic implants, surgical instruments, and drug delivery components requiring biocompatibility certification. FDA 21 CFR Part 820 and EU MDR quality system regulations collapse the supplier base toward validated precision turners.
- Automotive Parts:Fuel injection components, transmission shafts, and chassis hardware facing electric vehicle transition pressure. Germany's mid-tier suppliers serve legacy internal combustion contracts while battery platform sourcing reorganizes.
- Electronics:Connector bodies, heat sinks, and miniature hardware for semiconductor equipment. Miniaturization trends push Swiss-type lathe demand for sub-millimeter feature machining.
Aerospace retains volume leadership; Medical Devices holds the steepest expansion curve through premium validation economics.
Material:
Supply concentration in European and Chinese bar stock production creates geographic risk exposure across alloy categories.
- Aluminum:Lightweight alloy for automotive and electronics applications where machinability enables high spindle speeds. European suppliers face EU Green Deal carbon-border adjustment pressure on primary aluminum sourcing.
- Stainless Steel:Corrosion-resistant grades for medical and food processing equipment. REACH chemical restrictions constrain European surface treatment chemistries for passivation and electropolishing.
- Brass:Free-machining copper-zinc alloy for plumbing fittings and electrical hardware. China's dual carbon goals reshape domestic raw material sourcing economics.
- Plastic:Engineering polymers for lightweight, chemically resistant components. Medical device PEEK implants require validated cleanroom turning protocols.
Stainless Steel retains volume leadership; Aluminum holds the steepest expansion curve through automotive lightweighting.
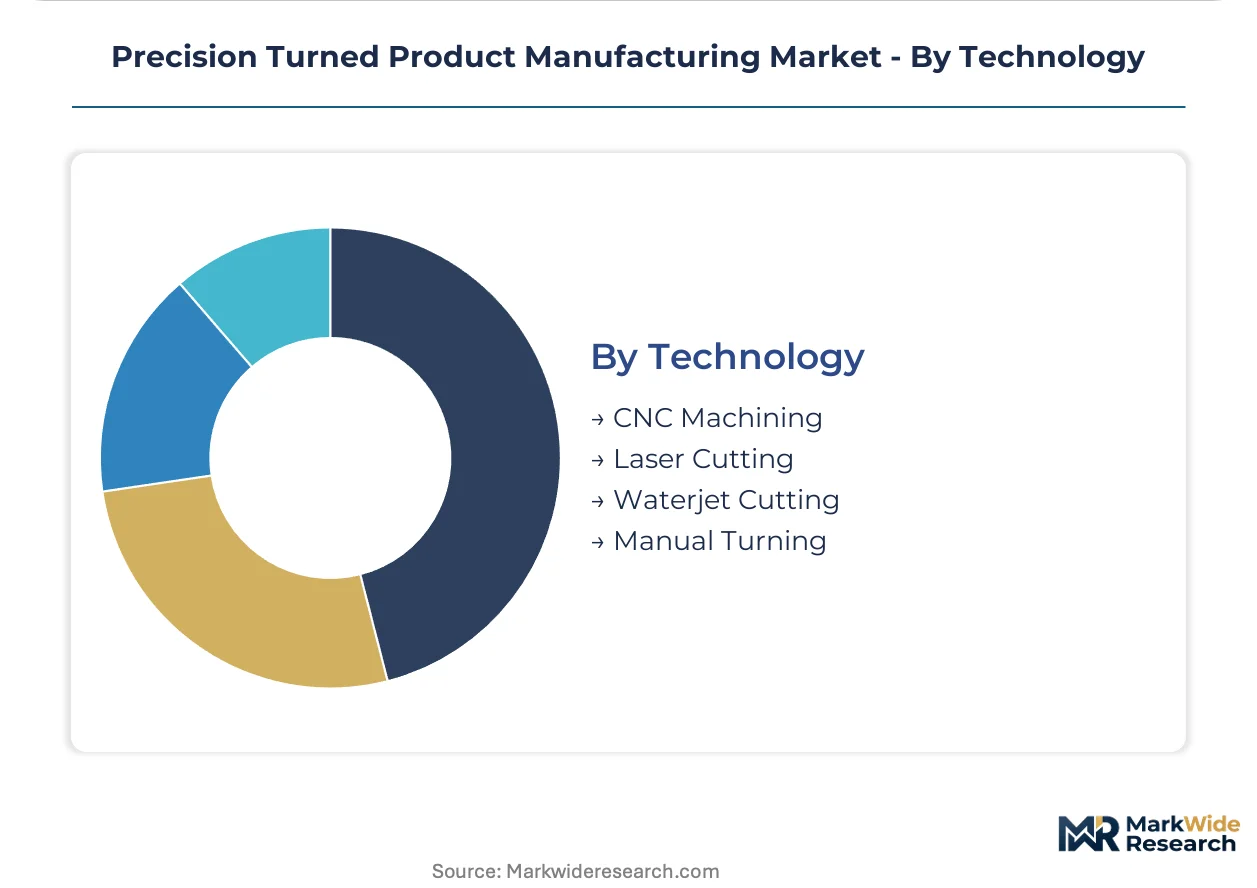
Technology:
Maturity gradients separate automated CNC platforms from legacy manual operations facing capacity exit pressure.
- CNC Machining:Computer-numerical-control turning centers with programmable multi-axis motion. Commands the largest value share through repeatability in aerospace fastener and hydraulic fitting production.
- Laser Cutting:Thermal pre-forming of exotic alloys before finish turning operations. Expands most quickly as aerospace OEMs adopt near-net-shape workflows for Inconel and titanium.
- Waterjet Cutting:Abrasive jet pre-forming without heat-affected zones. Niche adoption for thermally sensitive aerospace alloys requiring subsequent precision turning.
- Manual Turning:Operator-controlled lathe operations for prototype and repair work. Generational skill attrition compresses capacity at job shops lacking CNC migration capital.
CNC Machining retains volume leadership; Laser Cutting holds the steepest expansion curve through hybrid additive-subtractive integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace OEMs and medical device contract manufacturers concentrate procurement authority in Germany, the United States, Switzerland, Japan, and China, with supplier validation requirements tightening fastest in European and North American regulatory jurisdictions.
Germany
Baden-Württemberg's precision engineering cluster hosts mid-tier suppliers serving Tier 1 automotive drivetrain and orthopedic implant contracts. EU Green Deal carbon-border adjustments accelerate investment in energy-efficient Swiss-type lathe operations. REACH chemical restrictions constrain cutting fluid formulations across Stuttgart and Karlsruhe manufacturing zones.
United States
Defense and commercial aviation supply chains drive specification tightening for titanium and Inconel fasteners. FDA 21 CFR Part 820 quality system regulations extend new supplier qualification timelines for orthopedic implant turners. Connecticut and Arizona precision machining corridors concentrate aerospace-grade superalloy processing capacity.
Switzerland
Swissmedic medical device regulations and ISO 13485 certification requirements collapse the supplier base for orthopedic components. Geneva and Zurich precision turners dominate high-volume medical production through automated L20 Swiss-type lathe platforms. Cantonal industrial policy supports advanced manufacturing apprenticeships for multi-axis programming specialists.
Japan
METI industrial standards and PMDA quality system requirements govern precision turned products for surgical instruments and drug delivery devices. Nagoya and Osaka manufacturing belts specialize in sub-millimeter feature machining for semiconductor equipment connectors. Miniaturization trends push demand for Swiss-type lathe automation in precision electronics hardware.
China
Dual carbon goals reshape domestic raw material sourcing economics for brass and stainless steel bar stock. MIIT smart manufacturing initiatives accelerate automated optical inspection adoption on turning lines. Yangtze River Delta precision engineering clusters face repositioning pressure as carbon intensity regulations tighten on primary metal production.
Precision Turned Product Manufacturing Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive precision machining divisions alongside specialized mid-tier contract manufacturers. Consolidation pressure concentrates most intensely in aerospace superalloy processing and medical device validation tiers. Three archetypes dominate: integrated materials-to-components suppliers, pure-play precision turners with ISO 13485 certification, and tooling manufacturers extending into finished component production. M&A activity targets validated medical device suppliers, while capacity expansion focuses on Swiss-type lathe automation for lot-size compression.
Among European-based industrial groups, GKN plc and Sandvik AB occupy positions spanning materials, tooling, and precision component supply chains. Citizen FINEDEVICE exemplifies the specialized precision turner archetype with concentrated exposure to high-volume medical device production. These three entities represent distinct competitive vectors: backward integration into superalloy processing, upstream control over cemented carbide insert geometries, and captive demand for automated Swiss-type lathe platforms.
| Leading Market Players |
|---|
| GKN plc |
| Citizen FINEDEVICE |
| Sandvik AB |
| Precision Castparts Corp. |
| BorgWarner Inc. |
| Kennametal Inc. |
| Cox Manufacturing Co. |
| Schunk Group |
| Mitsubishi Materials Corporation |
| Others |
Value Network & Pricing Analysis
Swiss-type lathe capacity utilization above 85% in Baden-Württemberg and Connecticut corridors anchors price floors for validated medical and aerospace components, compressing margin headroom for mid-tier suppliers lacking ISO 13485 certification or superalloy machining platforms.
Pricing Analysis
Cost-plus contracts with tungsten and cobalt indexation dominate aerospace fastener procurement, passing raw material volatility through to Tier 1 OEMs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated orthopedic implant turners from automotive commodity suppliers. Cost compression in standard brass fittings intensifies because Chinese bar stock exports face carbon-border adjustment exposure. Automotive electronics buyers exhibit highest price sensitivity; medical device OEMs absorb premium pricing for traceability documentation.
Supply Chain Analysis
Strait of Hormuz transit risk for cobalt concentrates from the DRC underwrites European cemented carbide insert supply security concerns. Raw material sourcing draws from German stainless steel bar stock mills, Chinese brass smelters, and Japanese titanium sponge producers. Single-source vulnerability concentrates in Sandvik AB's dominance of aerospace-optimized insert geometries. Distribution runs through vendor-managed inventory programs with 90-day rolling forecasts in U.S. defense aviation supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 21 CFR Part 820 and EU MDR quality systems creates defensive moats for validated precision turners, as switching costs for OEM supplier qualification exceed 18-month timelines.
For Market Incumbents: Consolidate around aerospace superalloy machining capabilities as ultrasonic-assisted turning displaces conventional carbide platforms. Acquire ISO 13485-certified medical component suppliers in Germany and Switzerland before private equity bid premiums widen. Cemented carbide tooling backward integration anchors margin control against tungsten price volatility. For New Entrants and Emerging Players: Post-processing service gaps in additive-subtractive hybrid workflows for lot-size-one medical implants expose incumbent blind spots. Target Swiss-type lathe automation retrofit services for mid-tier job shops facing generational operator attrition. Lead with algorithmic validation protocols for EU AI Act-compliant optical inspection stations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play precision turners with captive medical device demand over diversified industrial conglomerates. Long-term viability hinges on validated process documentation assets that resist replication. Monitor FDA warning letter frequency as inflection indicator for supplier base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Swiss-Type Lathe Automation | Citizen FINEDEVICE platforms compress lot-size economics for orthopedic implant contracts. |
| EU AI Act Compliance Investment | Algorithmic validation for automated optical inspection stations creates first-mover certification advantage. |
| Superalloy Machining Capability Acquisition | Titanium and Inconel expertise defends aerospace fastener positioning against cold heading substitution. |
| Vendor-Managed Inventory Programs | Consignment arrangements concentrate supply chain risk onto precision turners with 90-day rolling forecasts. |
| Dual Carbon Supply Chain Verification | Verified low-carbon brass and stainless steel sourcing opens repositioning windows under EU carbon-border adjustments. |
Research Methodology
Initial hypotheses were tested against primary input from precision machining plant managers, aerospace Tier 1 procurement directors, orthopedic implant quality assurance leads, and cemented carbide tooling R&D specialists and refined through secondary validation against SEC 10-K filings, EU ETS carbon intensity disclosures, FDA 510(k) submission databases, and German mechanical engineering association production surveys. Bottom-up capacity modeling across Swiss-type lathe installations triangulated with top-down aerospace and medical device procurement spend analysis.
Variance-decomposition across material, technology, and end-use segmentation dimensions structured the analytical framework over the projection horizon. Modeled dimensions included superalloy grade tier, machining platform automation level, and regulatory validation cluster. CAGRs derived from installed equipment capacity curves weighted by utilization rates and contract pricing trajectories. Forecast inputs incorporated REACH chemical restriction compliance cost curves and MIIT smart manufacturing adoption timelines.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, EU MDR, and EU AI Act implementation regimes; material policy shifts would require re-modeling supplier qualification timelines and carbon-border adjustment rates. Practitioners should keep alternative scenarios live as EU Green Deal carbon intensity benchmarks and Chinese dual carbon enforcement thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market