
 Laser Surface Texturing Market | 2026-2036
Laser Surface Texturing Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Surface Texturing Market Insights
Market Context with Strategic Players
Ceramic coatings are hardening as the preferred alternative to chrome plating in automotive cylinder liners, altering the economics of laser texturing equipment procurement. TRUMPF sustains technology leadership through its dominance in ultrafast laser platforms for precision mold applications. IPG Photonics leverages vertical integration in fiber laser sources to control cost structures across industrial texturing systems. Hanan's Laser Technology Industry Group anchors manufacturing scale in Asia-Pacific supply chains for diode-pumped architectures.
Technical Definition and Structural Segments
Laser surface texturing employs focused coherent light to engineer microscale and nanoscale topographies on material substrates, typically achieving feature resolutions below ten micrometers through ablation, melting, or phase transformation processes. The technique primarily enhances tribological performance, wettability, and optical properties across precision-engineered components. Femtosecond and picosecond pulse technologies command premium positioning due to minimal heat-affected zones in medical device fabrication and optical component production. Mold texturing applications within the automotive parts segment represent mature, high-volume demand pools, while microfluidics channels in biomedical devices capture expanding margin pools from miniaturization trends.
Regulatory Frame and Forward-Looking Close
The FDA oversees surface quality validation for implantable biomedical devices, while REACH restricts hexavalent chromium processes that laser texturing replaces in European tooling operations. OSHA laser safety standards and ISO 11553 machinery directives govern workplace deployment and equipment certification across manufacturing facilities. Stakeholders must weigh capital allocation between ultrafast platform upgrades and compliance infrastructure as regulatory thresholds for surface characterization tighten across multiple jurisdictions.
Market Dynamics
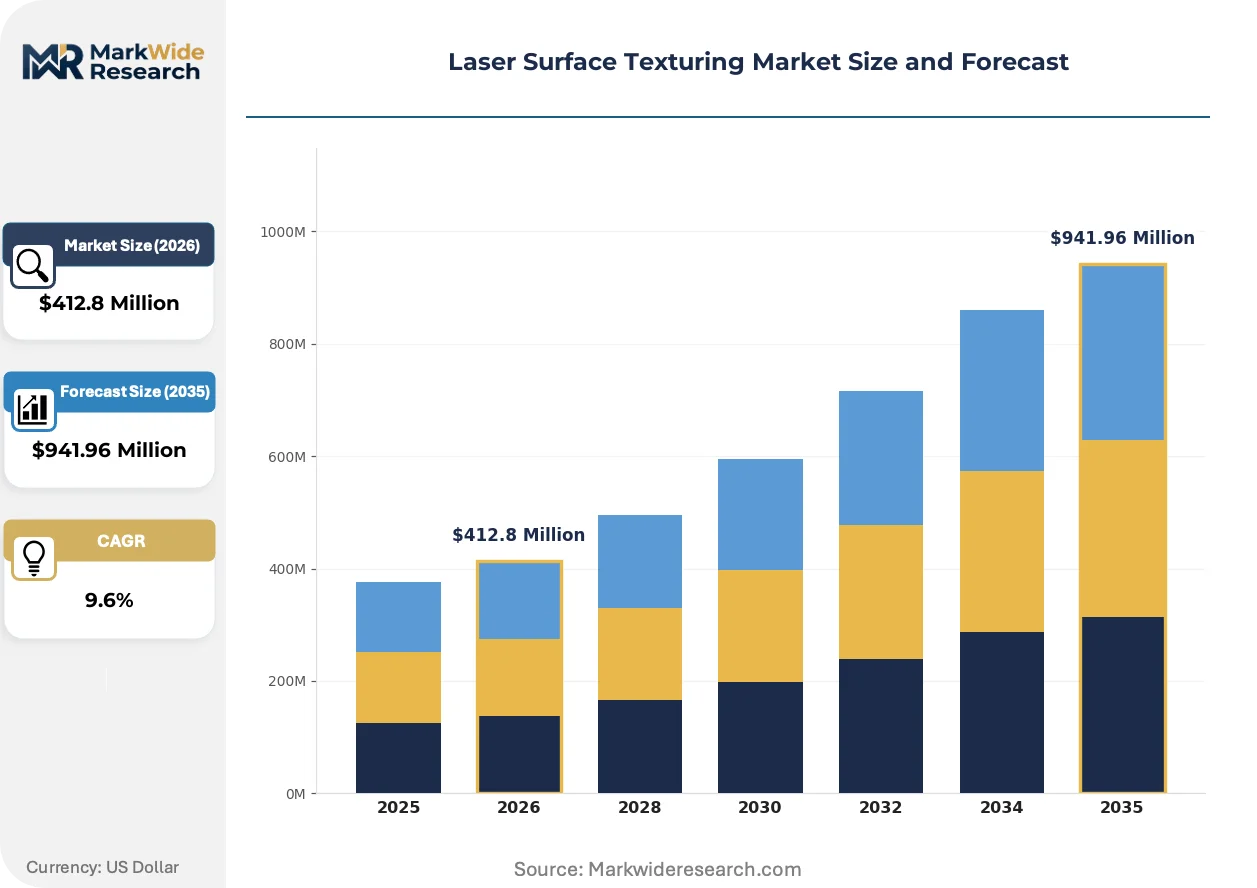
The transition from hexavalent chromium plating to laser-engineered surfaces is restructuring capital allocation across precision tooling supply chains, with femtosecond pulse systems capturing preference in medical device fabrication where heat-affected zones compromise implant performance.
Growth Catalysts
- REACH Phase-Out Mandates:The European Chemicals Agency's restrictions on hexavalent chromium processes are compelling automotive cylinder liner manufacturers to adopt laser texturing as a compliant surface engineering alternative.
- FDA Surface Quality Guidance:Evolving validation requirements for additive-manufactured implants are elevating textured surface specifications as a biocompatibility determinant in orthopedic and dental device production.
- Stuttgart Precision Cluster:Concentrated demand from Germany's tooling corridor around Stuttgart and Aachen is driving femtosecond laser platform deployment for mold and die applications.
Market Restraints
- Ultrafast Laser Source Concentration:Supply of femtosecond and picosecond oscillators concentrates among a limited set of specialized photonics suppliers, creating procurement bottlenecks for system integrators.
- Capital Intensity Threshold:Entry-level ultrafast texturing platforms require substantial fixed investment, restricting adoption among mid-tier mold shops serving automotive tier-two suppliers.
- Technical Throughput Limitations:Single-beam femtosecond processing rates lag behind mechanical texturing methods for large-area automotive interior mold surfaces, constraining volume economics.
Strategic Opportunities
- Microfluidics Channel Fabrication:Biomedical device miniaturization is creating demand for laser-etched sub-micron flow structures in diagnostic cartridge manufacturing.
- India Medical Device PLI Scheme:Production-linked incentives for domestic implant manufacturing are attracting texturing service providers to establish captive operations near Hyderabad and Ahmedabad clusters.
- Optical Component Convergence:Integration of laser texturing with direct laser interference patterning is enabling anti-reflective surface generation for augmented reality waveguide substrates.
Industry Challenges
- Femtosecond Process Engineer Scarcity:Operational expertise in pulse parameter optimization and beam delivery calibration remains concentrated among a narrow specialist cohort, constraining facility scaling.
- Multi-Jurisdiction Certification Complexity:ISO 11553 machinery safety compliance, OSHA laser workplace standards, and FDA surface validation protocols impose overlapping documentation burdens on equipment deployers.
- Legacy Mechanical Texturing Integration:Hybrid production environments require workflow reconciliation between laser and chemical etching processes, complicating quality system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Surface Texturing Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $941.96 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
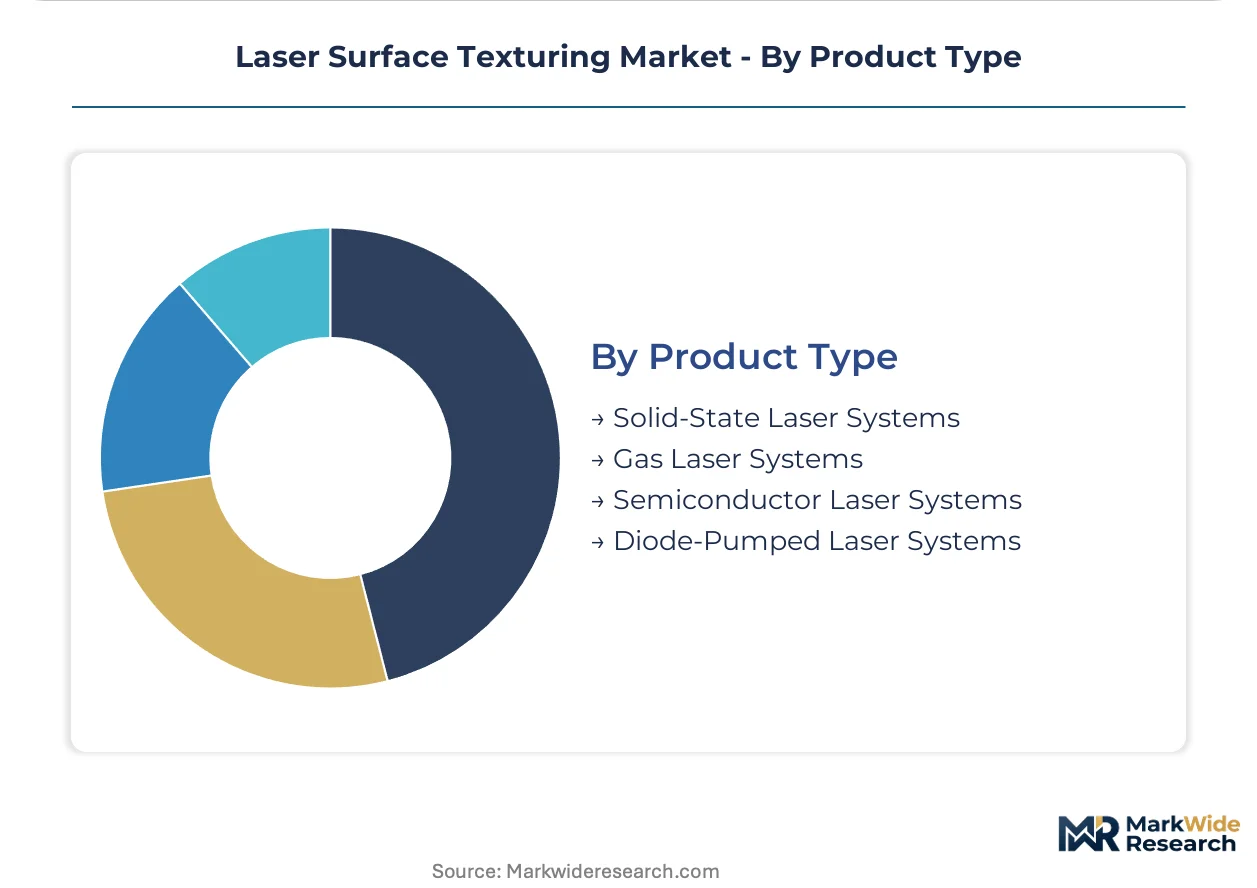
| Segmentation | Technology: Femtosecond, Picosecond, Nanosecond, Continuous Wave, Fiber Laser Application: Microfluidics, Optical Components, Mold Texturing, Biomedical Devices, Automotive Parts End User Industry: Electronics Manufacturing, Aerospace Engineering, Tooling Sector, Medical Device Fabrication, Consumer Goods Product Type: Solid-State Laser Systems, Gas Laser Systems, Semiconductor Laser Systems, Diode-Pumped Laser Systems |
| Companies Covered | Coherent, LPKF Laser & Electronics, Laserax, HT Laser, Han's Laser Technology Industry Group, Oxford Lasers, IPG Photonics, Starlink Laser Technology, TRUMPF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Surface Texturing Market Trends and Innovations
Ultrafast pulse technologies are compressing heat-affected zones below detectable thresholds, enabling surface engineering on thermally sensitive substrates previously excluded from laser processing. This capability expansion is redirecting R&D expenditure toward multi-beam parallelization and real-time process monitoring architectures.
Femtosecond laser systems are absorbing market share from picosecond platforms in medical implant applications where sub-micron precision governs cellular adhesion properties. Cardiovascular stent manufacturers and orthopedic implant fabricators are specifying femtosecond sources in procurement tenders, compressing pricing premiums for heat-minimal processing across the precision tooling segment.
REACH authorization requirements for continued chromium plating use are tightening compliance windows for European automotive suppliers. The European Chemicals Agency's sunset date enforcement is accelerating capital reallocation toward laser-based surface engineering, with cylinder liner and piston ring manufacturers in Germany and Italy restructuring coating operations to eliminate hexavalent chromium dependencies.
Equipment procurement is consolidating around performance-guaranteed service contracts rather than capital purchase models. Mold texturing houses in Japan and South Korea are shifting toward throughput-based payment structures with system suppliers, transferring operational risk while securing guaranteed uptime for automotive just-in-sequence production schedules.
Laser Surface Texturing Market Segmentation

Technology selection dictates capital deployment cycles and operational capabilities across laser surface texturing operations. Pulse duration specifications determine heat-affected zone profiles, directly constraining which substrate materials and end-use applications each platform can address.
Technology:
Equipment refresh cycles concentrate where femtosecond platforms displace legacy nanosecond systems in precision medical applications.
- Femtosecond:Ultrashort pulse durations below 350 femtoseconds enable ablation with thermal diffusion lengths under 100 nanometers. Stuttgart and Aachen tooling clusters specify these sources for mold applications requiring sub-micron edge definition.
- Picosecond:Pulse widths between 10-50 picoseconds balance throughput against heat minimization for optical component fabrication. Cardiovascular stent manufacturers in Germany and Switzerland are migrating procurement specifications toward these platforms.
- Nanosecond:Cost-effective pulse sources serve high-volume automotive interior mold texturing where thermal damage tolerance permits longer pulse durations.
- Continuous Wave:Sustained emission modes support large-area surface modification for industrial tooling refurbishment with lower precision requirements.
- Fiber Laser:Diode-pumped architectures from Asia-Pacific supply chains deliver energy efficiency for mid-tier mold shops serving automotive tier-two suppliers.
Femtosecond systems sit at the top of the volume ranking, with fiber laser configurations climbing the fastest.
Application:
End-use specifications fragment procurement patterns across margin tiers, with biomedical and optical applications commanding premium platform configurations.
- Microfluidics:Sub-micron channel geometries for diagnostic cartridge manufacturing demand femtosecond precision. Hyderabad and Ahmedabad medical device clusters under India's PLI scheme are attracting dedicated texturing service capacity.
- Optical Components:Anti-reflective surface generation for augmented reality waveguides requires direct laser interference patterning integration. Japanese and South Korean equipment suppliers are shifting toward throughput-based service contracts for this segment.
- Mold Texturing:Automotive interior and exterior component tooling represents mature, high-volume demand with established mechanical texturing replacement cycles.
- Biomedical Devices:Orthopedic and dental implant surface engineering faces tightening FDA validation requirements for additive-manufactured components.
- Automotive Parts:Cylinder liner and piston ring manufacturers in Germany and Italy are restructuring coating operations to eliminate hexavalent chromium dependencies under REACH enforcement.
Mold texturing commands the largest installed base, though microfluidics channel fabrication is gaining share fastest.
End User Industry:
Customer technical sophistication determines service contract structures and equipment deployment models across manufacturing verticals.
- Electronics Manufacturing:Semiconductor packaging and display component fabrication requires cleanroom-compatible texturing systems with real-time process monitoring architectures.
- Aerospace Engineering:Turbine blade and structural component surface engineering demands certification traceability under AS9100 quality systems.
- Tooling Sector:Mold and die manufacturers in Germany's precision clusters anchor femtosecond platform adoption for automotive and consumer goods production.
- Medical Device Fabrication:Implant biocompatibility specifications from FDA and EMA drive surface characterization investments and pulse parameter optimization expertise.
- Consumer Goods:Appliance and personal care product manufacturers prioritize cost efficiency over precision for decorative and functional surface treatments.
The tooling sector maintains the deepest equipment penetration, with medical device fabrication expanding most quickly.
Product Type:
Source architecture selection constrains beam quality, maintenance intervals, and supply chain vulnerability for system operators.
- Solid-State Laser Systems:Nd:YAG and Nd:YVO4 gain media deliver high peak powers for industrial mold texturing with established service infrastructure.
- Gas Laser Systems:CO2 sources remain relevant for polymer and organic substrate processing where infrared absorption characteristics match application requirements.
- Semiconductor Laser Systems:Direct diode architectures offer compact form factors for integration into production line environments with space constraints.
- Diode-Pumped Laser Systems:Fiber-coupled configurations from Asia-Pacific manufacturing bases provide cost-controlled alternatives to lamp-pumped alternatives for mid-volume operations.
Diode-pumped systems lead deployment volume, with solid-state platforms retaining the steepest expansion trajectory in precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision tooling corridor anchors femtosecond laser platform deployment for automotive mold applications. Germany's concentration of cylinder liner manufacturers and REACH-driven chrome plating phase-outs concentrate procurement decisions in Baden-Württemberg and North Rhine-Westphalia.
Germany
Automotive cylinder liner manufacturers and precision mold shops drive equipment procurement in Stuttgart and Aachen clusters. ECHA's REACH enforcement tightens compliance windows for hexavalent chromium processes, compelling coating operation restructuring. TRUMPF and IPG Photonics serve these tooling corridors with ultrafast laser platforms for heat-minimal surface engineering.
United States
FDA surface quality validation requirements for additive-manufactured implants elevate textured surface specifications in orthopedic device production. OSHA laser safety standards and ISO 11553 machinery directives govern workplace deployment across manufacturing facilities. Greater Boston and Minneapolis-St. Paul medical device clusters attract texturing service capacity for biocompatibility-critical applications.
China
Han's Laser Technology Industry Group anchors diode-pumped architecture manufacturing for Asia-Pacific supply chains. MIIT industrial upgrading policies and GB standards for laser equipment certification shape procurement patterns. Yangtze River Delta precision manufacturing bases absorb fiber laser systems for mid-tier mold operations serving consumer goods exporters.
India
CDSCO medical device regulations and the PLI scheme for domestic implant manufacturing attract texturing providers to Hyderabad and Ahmedabad clusters. BIS standards for industrial laser equipment create certification requirements for imported platforms. Telangana and Gujarat medical device production zones are establishing captive surface engineering capacity for export-oriented orthopedic fabrication.
Japan
METI advanced manufacturing initiatives support laser texturing adoption in automotive and electronics component production. JIS standards for laser processing equipment and PMDA quality system requirements for medical devices impose dual compliance frameworks. Kansai region mold manufacturers are shifting toward throughput-based service contracts with equipment suppliers for just-in-sequence automotive production.
Laser Surface Texturing Market Competitive Landscape
Technology licensing dominates the current landscape as specialized photonics suppliers extend platform reach through regional system integrators. The vendor base organizes around three strategic archetypes: ultrafast laser source specialists, integrated system manufacturers, and regional fabrication service providers. Consolidation pressure concentrates at the source level where femtosecond oscillator supply bottlenecks limit system integrator expansion. Portfolio diversification and geographic expansion represent the dominant competitive vectors as players seek to offset platform commoditization in nanosecond segments.
Among German-integrated manufacturers, TRUMPF exemplifies the ultrafast platform specialist archetype through its Stuttgart-rooted precision tooling focus. IPG Photonics occupies a position representing vertical control over fiber laser source architecture for cost-structured industrial systems. Han's Laser Technology Industry Group anchors the Asia-Pacific manufacturing scale archetype for diode-pumped configurations serving mid-volume operations. Coherent and LPKF Laser & Electronics sit within the precision application specialist tier, with the former representing North American photonics heritage and the latter exemplifying European electronics fabrication focus.
| Leading Market Players |
|---|
| Coherent |
| LPKF Laser & Electronics |
| Laserax |
| HT Laser |
| Han's Laser Technology Industry Group |
| Oxford Lasers |
| IPG Photonics |
| Starlink Laser Technology |
| TRUMPF |
| Others |
Pricing and Supply Chain Analysis
REACH sunset dates for hexavalent chromium processes gate qualified supply access and premium-tier pricing power for femtosecond platform providers serving European automotive tooling corridors. ECHA enforcement windows compress procurement timelines for compliant surface engineering alternatives, concentrating pricing leverage among ultrafast laser source specialists with certified heat-minimal processing capabilities.
Pricing Analysis
Femtosecond oscillator costs pass through directly to system pricing, with three-tier pricing structure across premium, standard, and economy levels separating medical-grade heat-minimal specifications from automotive interior mold applications. Price differentiation rests on FDA validation tier and ISO 11553 machinery certification grade. Pricing pressure stems from fiber laser cost compression in mid-tier mold shops serving automotive tier-two suppliers. Consumer goods manufacturers exhibit highest price sensitivity; orthopedic implant fabricators show lowest.
Supply Chain Analysis
Refurbishment flows for lamp-pumped solid-state systems extend equipment lifecycles in cost-constrained operations, delaying new platform procurement. Supply concentrates in Germany, China, and Japan for precision optics and ultrafast oscillator components. Raw material dependencies include ytterbium-doped fiber, titanium-sapphire crystals, and precision motion stages. Single-source vulnerability concentrates in femtosecond seed laser architecture. Distribution runs through regional system integrators with captive service technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser surface texturing market reads as a late-cycle quality story as FDA surface validation requirements for additive-manufactured implants shift procurement specifications toward heat-minimal femtosecond platforms with certified biocompatibility traceability.
For Market Incumbents: Cement technology leadership through captive femtosecond oscillator supply agreements that insulate against photonics supplier bottlenecks. Lock in multi-year performance-guaranteed service contracts with Stuttgart and Aachen tooling clusters before REACH enforcement accelerates competitive platform deployment. Prioritize certification investment for ISO 13485 medical device quality systems to defend margin position against emerging Asian-Pacific diode-pumped competitors. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized medical device fabrication clusters around Hyderabad and Ahmedabad where captive surface engineering capacity remains underdeveloped. Target microfluidics channel fabrication for diagnostic cartridge manufacturing as the most penetrable premium segment. Pursue technology licensing arrangements with established photonics suppliers rather than capital-intensive source development. For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication service providers because ECHA compliance deadlines are consolidating demand among qualified operators with certified REACH-compliant surface engineering capabilities. Five-to-ten year viability favors service-based models with recurring revenue over capital equipment exposure. Watch femtosecond process engineer wage inflation as the inflection signal for automation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Femtosecond Platform Upgrade | REACH sunset enforcement compels heat-minimal processing adoption in German automotive tooling. |
| Medical Device Certification Investment | FDA surface validation protocols elevate biocompatibility-critical specifications in orthopedic implant fabrication. |
| Service Contract Model Transition | Throughput-based payment structures transfer operational risk for Japanese just-in-sequence mold production. |
| India Captive Facility Establishment | PLI scheme subsidies attract texturing capacity to Hyderabad and Ahmedabad medical device clusters. |
| Multi-Beam Parallelization R&D | Throughput limitations in large-area automotive interior molds drive real-time process monitoring architecture investment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with femtosecond process engineers, automotive tooling procurement leads, medical device quality directors, and laser system integration specialists with secondary validation against SEC filings from photonics suppliers, ECHA REACH authorization databases, FDA 510(k) surface validation guidance documents, and German mechanical engineering association production statistics. Bottom-up equipment deployment counts and top-down end-use market sizing were triangulated for convergence.
Historical reference periods anchored volume and value trajectories across the modeling period, with segmentation dimensions spanning pulse duration technology, application category, end-user industry vertical, and source architecture type. CAGRs were derived from fitted growth curves calibrated to equipment refresh cycle timing and regulatory compliance deadline clustering. Industry-specific forecast inputs included ECHA sunset date enforcement schedules and FDA additive manufacturing surface quality guidance evolution.
Regulatory timeline acceleration, femtosecond source supply disruption, and medical device reimbursement policy shifts are the dominant revision risks to modeled outcomes. Practitioners should monitor ECHA authorization renewal decisions, photonics supplier capacity expansion announcements, and CMS orthopedic implant coding updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Engineering Machines Market