
 Asia-Pacific Precision Turned Product Manufacturing Market | 2026-2036
Asia-Pacific Precision Turned Product Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Precision Turned Product Manufacturing Market Outlook
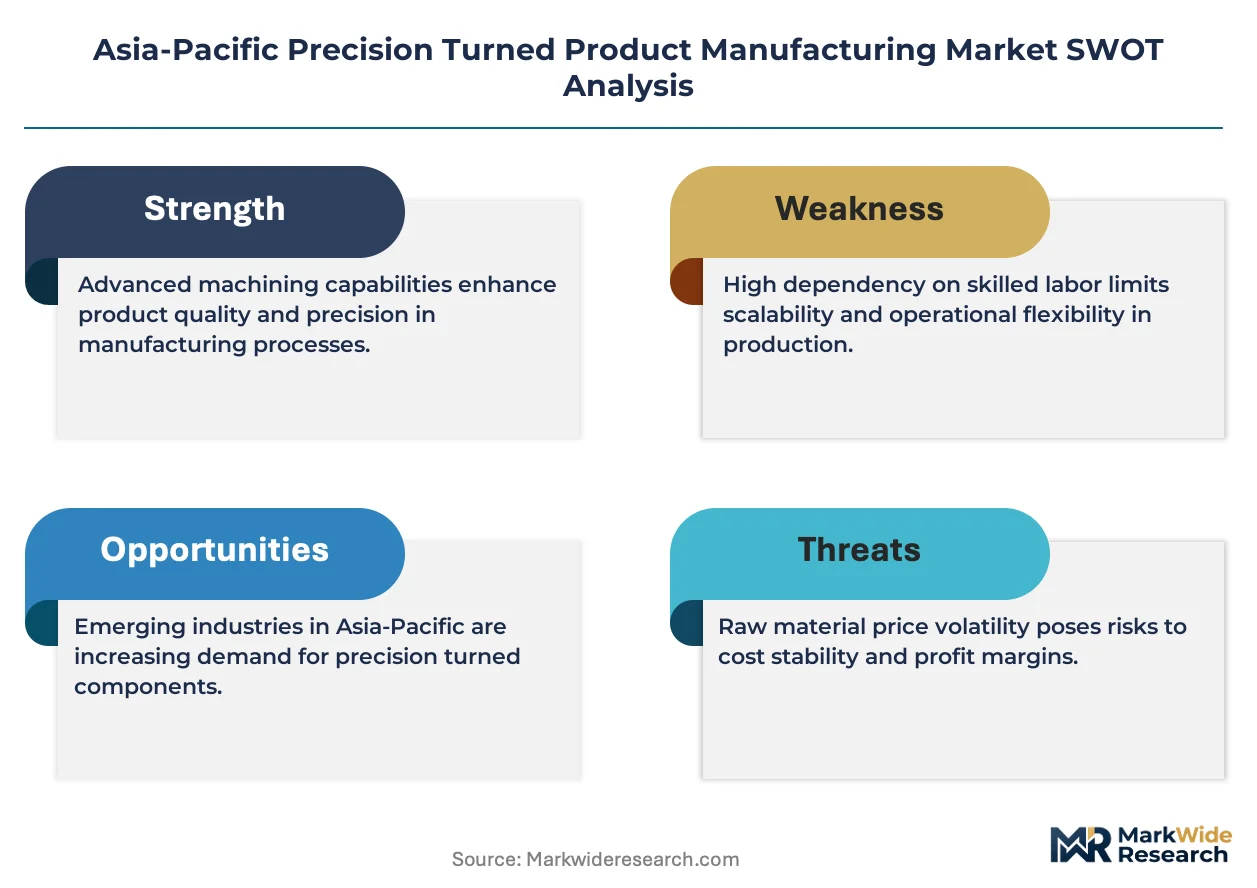
Aftermarket service revenue is narrowing as a margin pool relative to first-fit component supply across the Asia-Pacific precision turned product landscape. HAAS sustains its position through captive spindle technology and vertical control over machine-tool distribution. DMG MORI anchors premium positioning in Japan and South Korea via five-axis turning centers with integrated automation. Ningbo Sinster Machine Co Ltd competes on aluminum precision turned volumes for EV battery housing fasteners, leveraging Zhejiang province's metalworking supplier density.
Precision turned product manufacturing encompasses the computer-numerical-control machining of cylindrical components to sub-micron tolerances, typically achieving surface finishes of Ra 0.4 to 0.8 micrometers through bar-fed turning, Swiss-type machining, or multi-spindle operations. These components transmit torque, contain pressure, or locate assemblies in mechanically stressed systems. Automotive Components dominates current output value across the region, while Medical Devices represents the fastest-expanding end-use segment as PMDA and CDSCO tighten biocompatibility documentation for implantable hardware. Stainless Steel commands premium pricing due to nickel-alloy sourcing volatility, though Aluminum gains share in lightweighting-intensive aerospace and EV applications.
Japan's METI enforces JIS B 0601 surface-roughness standards that effectively filter lower-tier Chinese and Southeast Asian suppliers from precision aerospace contracts. China's SAMR administers GB/T 1804 general-tolerance rules that shape domestic procurement specifications for industrial machinery buyers. India's BIS certification requirements for automotive fasteners create compliance costs that favor established tier-1 suppliers with in-house metallurgical laboratories. Stakeholders must monitor divergence between Chinese domestic tolerance standards and export-facing AS9100 aerospace requirements, as dual-compliance investments will determine which machining houses capture cross-border OEM contracts.
Market Dynamics
Automotive OEM procurement of precision-machined drivetrain components is expanding across the Asia-Pacific region as electric vehicle platforms demand tighter tolerances on battery housing fasteners and motor shaft assemblies. China's GB/T precision machining standards and Japan's METI manufacturing quality frameworks are tightening tolerance requirements for cross-border component trade.
Growth Catalysts
- EV Battery Housing Fastener Demand:China's Yangtze River Delta precision machining cluster serves domestic EV brands requiring aluminum precision turned volumes for battery enclosures. Zhejiang province's metalworking supplier density enables rapid scaling of output.
- METI Quality Frameworks:Japan's manufacturing quality frameworks filter lower-tier suppliers from precision aerospace contracts, elevating compliant machining houses into tier-1 supplier networks for cross-border OEM programs.
- Swiss-Type Machining Adoption:Bar-fed turning and multi-spindle operations achieve sub-micron tolerances for implantable medical hardware as PMDA and CDSCO tighten biocompatibility documentation requirements.
Market Restraints
- Nickel-Alloy Sourcing Volatility:Stainless steel commands premium pricing due to nickel supply concentration in Indonesian and Philippine mining operations, compressing margins for medical-grade component producers.
- Dual-Compliance Investment Burden:Machining houses must maintain parallel quality systems for Chinese domestic GB/T 1804 tolerance rules and export-facing AS9100 aerospace requirements.
- Five-Axis Automation Cost Barriers:Premium positioning through integrated automation requires capital intensity that excludes mid-tier suppliers from Japan and South Korea aerospace contracts.
Strategic Opportunities
- India Automotive Fastener Certification Gap:BIS certification requirements for automotive fasteners create compliance costs that favor established tier-1 suppliers with in-house metallurgical laboratories in Pune and Chennai clusters.
- Medical Device Biocompatibility Documentation:PMDA and CDSCO tightening of implantable hardware standards opens white space for machining houses with captive surface-finish testing capabilities.
- Lightweighting Aerospace Applications:Aluminum gains share in aerospace applications as EV battery housing fastener expertise transfers to airframe component production.
Industry Challenges
- Multi-Spindle Operator Skill Scarcity:Swiss-type machining and bar-fed turning require specialized technicians that concentrate in Japan's Aichi prefecture and China's Jiangsu province.
- AS9100 Certification Timeline Compression:Aerospace OEMs demand compressed qualification periods that strain machining houses without existing Nadcap surface-treatment approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Precision Turned Product Manufacturing Market |
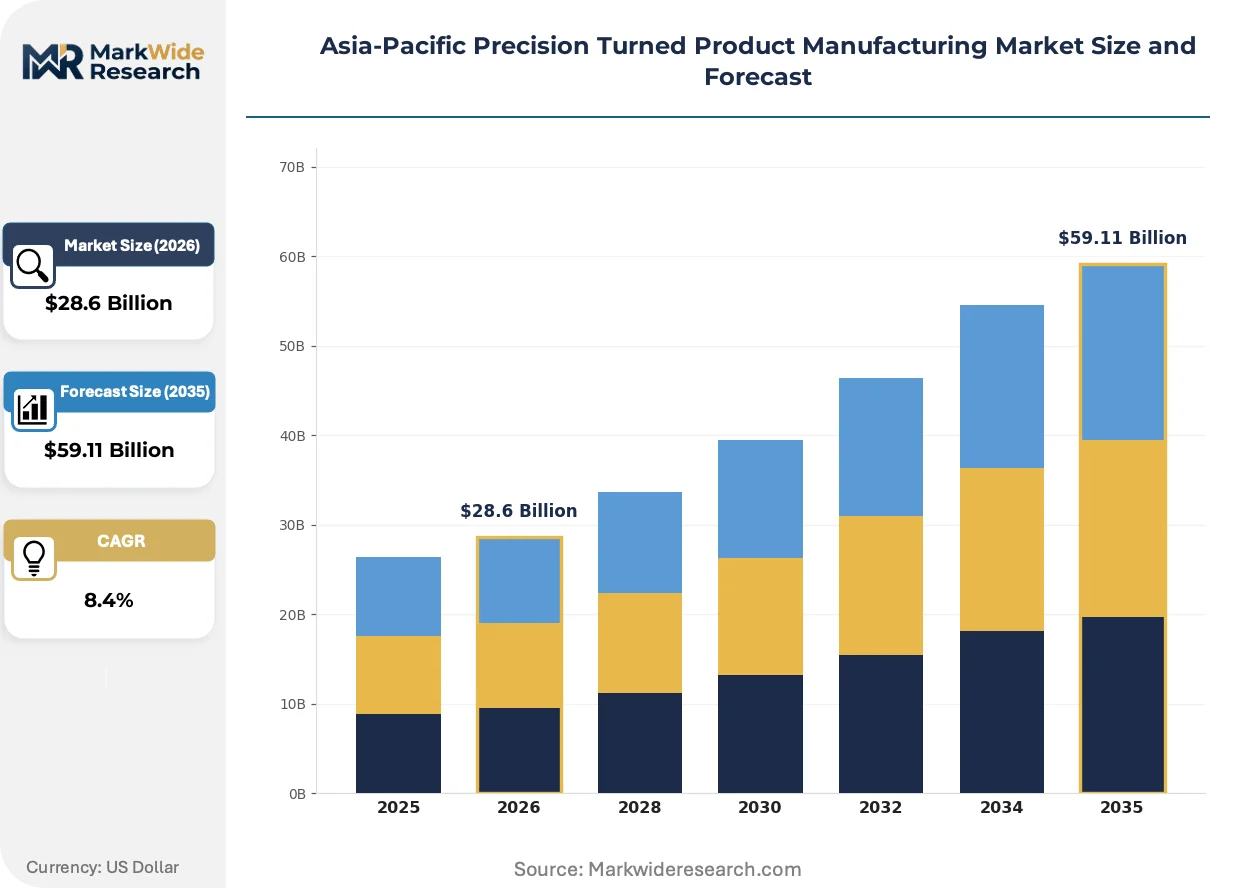
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Components, Aerospace Parts, Medical Devices, Industrial Machinery Material: Stainless Steel, Aluminum, Brass, Plastic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors Application: Precision Engineering, Custom Manufacturing, Mass Production, Assembly Processes |
| Companies Covered | HAAS, Junying Metal Manufacturing Co Limited, E&H Precision, Jiangsu Pacific Precision Forging Co. Ltd, Pacific Precision, DMG MORI, Ningbo Sinster Machine Co Ltd, APCS - Asia Precision PLC, AMADA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Precision Turned Product Manufacturing Market Strategic Shifts
Computer-numerical-control machining of cylindrical components is actively reshaping competitive positioning as precision turned product manufacturers integrate automation with legacy multi-spindle infrastructure. Surface finish capabilities of Ra 0.4 to 0.8 micrometers now serve as baseline thresholds rather than differentiators.
Hybrid manufacturing is hybridizing precision turned production by combining bar-fed turning with in-process laser surface texturing. Medical device manufacturers in Japan's Kanagawa prefecture adopt this convergence for implantable hardware requiring controlled surface roughness. The technology is hybridizing equipment investment cycles, compressing payback periods for machining houses that previously separated turning and finishing operations.
China's SAMR administration of GB/T 1804 general-tolerance rules is reshaping domestic procurement specifications for industrial machinery buyers. The industrial consequence is a bifurcation between suppliers serving domestic industrial machinery markets and those qualifying for export-facing aerospace contracts. Component machining houses in Ningbo and Suzhou are most affected, responding with parallel quality system investments.
Automotive OEM sourcing patterns are compressing supplier qualification cycles as EV platform launches accelerate. Tier-1 suppliers in China's Yangtze River Delta are displacing traditional distributor networks with direct engineering relationships. This behavioral shift is most visible in battery housing fastener procurement, where BYD and NIO engage machining houses for design-in collaboration rather than catalog purchasing.
Asia-Pacific Precision Turned Product Manufacturing Market Segmentation
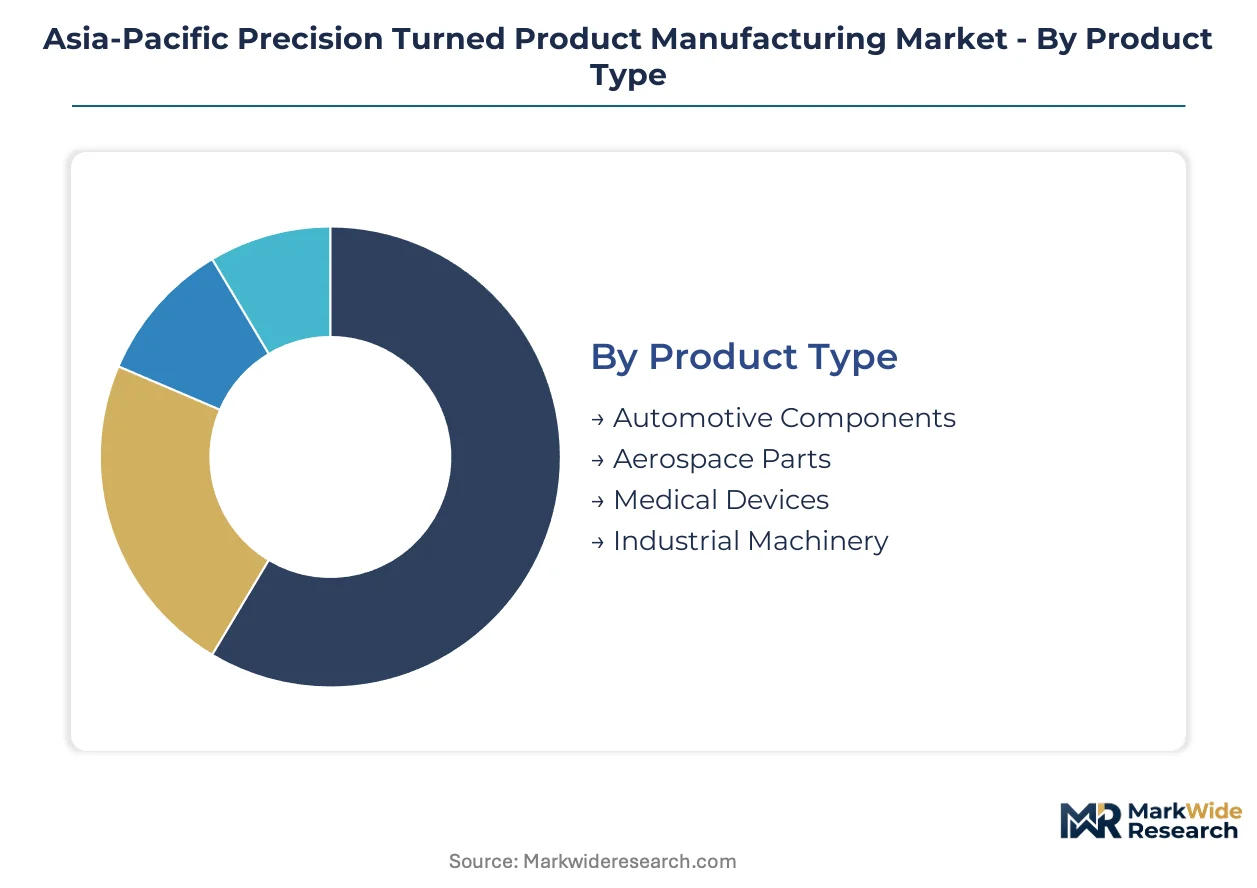
Precision turned product manufacturers configure capacity around material specifications and end-use tolerances rather than generic volume tiers. Segmentation in this market reveals how procurement patterns split between captive aerospace programs and distributed automotive supply chains across the Asia-Pacific region.
Product Type:
Application focus determines capital equipment allocation and quality system investments for machining houses.
- Automotive Components:Drivetrain shafts, transmission gears, and brake system fasteners dominate current output value. China's Yangtze River Delta cluster supplies BYD and NIO with battery housing fasteners requiring sub-micron tolerances on aluminum bar stock.
- Medical Devices:Implantable hardware and surgical instruments demand Ra 0.4 surface finishes with full biocompatibility traceability. PMDA and CDSCO documentation requirements are rotating compliant machining houses into tier-1 supplier networks for Japanese and Indian device OEMs.
- Aerospace Parts:Landing gear bushings and hydraulic actuators require AS9100 certification with Nadcap surface-treatment approvals.
- Industrial Machinery:Bearing housings and valve bodies serve domestic industrial machinery markets under GB/T 1804 tolerance rules.
Automotive Components holds installed capacity. Medical Devices is rotating up the share rankings.
Material:
Raw material sourcing geography and volatility exposure shape margin structures across supplier tiers.
- Stainless Steel:Nickel-alloy grades 316L and 17-4 PH command premium pricing for medical and aerospace applications. Indonesian and Philippine mining concentration creates margin compression for producers without long-term offtake agreements.
- Aluminum:6061-T6 and 7075-T6 alloys enable lightweighting in EV battery enclosures and aerospace airframes. Zhejiang province's metalworking density supports rapid scaling of aluminum precision turned volumes for export programs.
- Brass:Free-machining C36000 serves plumbing and electrical connector applications with lower certification burdens.
- Plastic:PEEK and PTFE components address corrosive chemical processing and medical sterilization requirements.
Stainless Steel retains pricing power. Aluminum is climbing the fastest on volume growth.
End User:
Customer type dictates contract structures, inventory liability, and engineering collaboration intensity.
- OEMs:Direct procurement from automotive and aerospace manufacturers compresses qualification cycles and demands design-in collaboration. BYD and NIO engage machining houses for concurrent engineering on battery platform fasteners rather than catalog purchasing.
- Tier-1 Suppliers:Denso, Aisin, and comparable integrators aggregate component demand across multiple OEM programs. These relationships require TS 16949 certification with captive metrology capabilities.
- Aftermarket Providers:Service part distributors source replacement fasteners and bushings with shorter lead times and lower documentation requirements.
- Distributors:Catalog houses stock standard precision turned products for maintenance and repair operations across industrial machinery segments.
OEMs concentrate strategic supplier development investment. Tier-1 Suppliers are gaining share fastest on EV platform consolidation.
Application:
Production methodology and lot size economics separate high-mix custom work from commodity volume operations.
- Precision Engineering:Low-volume, high-complexity components for aerospace and medical applications require five-axis turning centers with in-process inspection. METI quality frameworks and AS9100 requirements filter supplier participation.
- Custom Manufacturing:Engineer-to-order production serves prototype and specialty machinery markets with flexible lot sizes and compressed lead times.
- Mass Production:Multi-spindle bar-fed turning achieves unit cost minima for automotive fasteners and industrial valve components at volumes exceeding one million pieces annually.
- Assembly Processes:Kitted component sets reduce OEM line-side inventory through vendor-managed inventory programs.
Mass Production holds depreciated equipment bases. Precision Engineering is expanding most quickly on aerospace and medical qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Yangtze River Delta exhibit the highest price elasticity for aluminum precision turned volumes, while Japanese aerospace OEMs tolerate premium pricing for AS9100-certified suppliers. India's automotive tier-1 procurement sits mid-range, sensitive to BIS certification costs but less tolerant of delivery variance than Chinese buyers.
China
BYD and NIO accelerate direct engineering relationships with machining houses for battery housing fasteners, bypassing traditional distributor networks. SAMR's GB/T 1804 tolerance rules shape domestic industrial machinery procurement while export-facing suppliers maintain parallel AS9100 systems. The Yangtze River Delta cluster concentrates aluminum bar-fed turning capacity serving both EV platforms and aerospace programs.
Japan
Medical device OEMs in Kanagawa prefecture drive demand for Swiss-type machining with integrated laser surface texturing on implantable hardware. METI enforces JIS B 0601 surface-roughness standards that filter lower-tier suppliers from precision aerospace contracts. Aichi prefecture hosts the densest concentration of multi-spindle technicians capable of sub-micron tolerance work.
India
Automotive fastener demand concentrates in Pune and Chennai clusters as domestic EV production scales. BIS certification requirements create compliance costs that favor established tier-1 suppliers with captive metallurgical laboratories. CDSCO tightening of biocompatibility documentation for implantable hardware opens qualification pipelines for machining houses with surface-finish testing capabilities.
South Korea
Five-axis turning center adoption accelerates among suppliers seeking entry into aerospace tier-1 networks. MFDS alignment with international medical device standards enables Korean machining houses to serve export markets alongside domestic demand. Busan-Ulsan region concentrates precision turned capacity for shipbuilding and offshore equipment applications.
Thailand
Japanese automotive transplant operations sustain demand for TS 16949-certified precision turned drivetrain components. Board of Investment incentives attract machining houses serving regional export programs to Eastern Economic Corridor industrial zones. Bangkok-based distributors aggregate component demand across Southeast Asian aftermarket channels with shorter documentation requirements.
Asia-Pacific Precision Turned Product Manufacturing Market Competitive Environment
Capability concentration sits with premium-tier machining houses holding Nadcap surface-treatment approvals and captive five-axis automation; scale advantage sits with multi-spindle operators in China's Zhejiang province leveraging bar-fed turning for million-piece automotive volumes. The vendor base stratifies across three archetypes: integrated machine-tool manufacturers with captive spindle technology, specialized precision turned product houses with end-use certifications, and commodity volume producers serving domestic industrial machinery markets. Dominant competitive moves include backward integration into nickel-alloy sourcing and geographic expansion through qualification for cross-border OEM contracts.
Among machine-tool integrated manufacturers, DMG MORI and HAAS occupy positions defined by vertical control over spindle technology and distribution networks. HAAS exemplifies the captive-equipment archetype through its machine-tool manufacturing heritage, while DMG MORI represents premium positioning in five-axis turning centers. Within Asia-Pacific precision turned product specialists, Ningbo Sinster Machine Co Ltd anchors the aluminum volume tier serving EV battery housing applications. These three entities illustrate how competitive positioning splits between equipment-integrated and component-specialized business models across the regional landscape.
| Leading Market Players |
|---|
| HAAS |
| Junying Metal Manufacturing Co Limited |
| E&H Precision |
| Jiangsu Pacific Precision Forging Co. Ltd |
| Pacific Precision |
| DMG MORI |
| Ningbo Sinster Machine Co Ltd |
| APCS - Asia Precision PLC |
| AMADA |
| Others |
Value Chain & Pricing Dynamics
Nickel-alloy sourcing volatility from Indonesian and Philippine mining concentration determines both the premium-mid-economy pricing spreads across stainless steel grades and the geographic clustering of tier-1 suppliers with captive offtake agreements. Buyers in China's Yangtze River Delta exhibit acute price elasticity for aluminum precision turned volumes, while Japanese aerospace OEMs absorb premium pricing for AS9100-certified suppliers with Nadcap surface-treatment approvals.
Pricing Analysis
Aftermarket service revenue drives lifetime value compression as first-fit component supply captures margin pool share from maintenance and repair operations. Pricing stratifies across premium, standard, and economy tiers based on certification grade—AS9100 aerospace versus GB/T 1804 industrial machinery—and volume scale, with million-piece automotive contracts commanding unit cost minima. Cost compression in medical-grade stainless steel intensifies because nickel supply concentration limits long-term contract availability. Tier-1 automotive suppliers in China demonstrate highest price sensitivity, while Japanese medical device OEMs in Kanagawa prefecture tolerate premium positioning for JIS B 0601 surface-roughness compliance.
Supply Chain Analysis
Upstream feedstock flows from Indonesian nickel laterite mines, Philippine chromite operations, and Chinese aluminum smelters in Zhejiang province. Raw material dependencies center on 316L and 17-4 PH stainless grades, 6061-T6 and 7075-T6 aluminum alloys, and free-machining C36000 brass stock. Single-source vulnerability concentrates in nickel-alloy supply chains where Indonesian export restrictions threaten medical and aerospace component producers. Distribution runs through direct engineering relationships with BYD and NIO displacing traditional distributor networks, alongside tier-1 integrators like Denso and Aisin aggregating multi-program demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision turned product manufacturing faces substitution defense against additive manufacturing and metal injection molding for low-complexity geometries, requiring incumbents to tighten tolerance capabilities and certification moats that alternative processes cannot replicate.
For Market Incumbents: Pre-empt additive manufacturing encroachment by deepening captive five-axis automation and Nadcap surface-treatment approvals that alternative processes cannot match. Secure backward integration into nickel-alloy sourcing through long-term offtake agreements with Indonesian mining operations. Expand AS9100 certification pipelines to capture cross-border aerospace contracts before qualification timelines compress further.
For New Entrants and Emerging Players: Mid-market aluminum precision turned volumes for EV battery housing fasteners in India's Pune and Chennai clusters represent the most penetrable entry point given BIS certification gaps that favor agile machining houses with rapid qualification capabilities. Target medical device biocompatibility documentation services for CDSCO-compliant implantable hardware as PMDA standards tighten. Establish direct engineering relationships with domestic EV OEMs rather than catalog distribution channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors machining houses with parallel quality systems for both domestic GB/T and export-facing AS9100 requirements. Long-term viability over the next decade hinges on automation integration and cross-border OEM qualification pipelines. Watch for inflection in Swiss-type machining operator wage inflation across Japan's Aichi prefecture and China's Jiangsu province as a signal of capacity constraint.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Alloy Sourcing | Long-term offtake agreements with Indonesian mining operations secure medical-grade stainless supply against export restriction volatility. |
| Parallel Quality System Investment | Dual GB/T 1804 and AS9100 compliance enables machining houses to serve both domestic industrial machinery and export aerospace programs. |
| Swiss-Type Machining Automation | Bar-fed turning with integrated laser surface texturing addresses PMDA biocompatibility requirements for Kanagawa prefecture medical device OEMs. |
| Direct OEM Engineering Relationships | Design-in collaboration with BYD and NIO displaces traditional distributor networks for battery housing fastener procurement. |
| Captive Metallurgical Laboratory Certification | In-house testing capabilities satisfy BIS automotive fastener requirements that filter mid-tier competitors from Pune and Chennai clusters. |
Study Parameters
A standing panel of tier-1 supplier procurement managers, OEM platform engineers, aftermarket service heads, and multi-spindle machining technicians provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against customs and trade data, JIS and GB/T standards documentation, SEC filings from listed machine-tool manufacturers, and vehicle production databases from IHS Markit. Bottom-up capacity assessments across China's Yangtze River Delta and Japan's Aichi prefecture triangulated against top-down demand modeling from automotive and aerospace OEM programs.
Scenario-bracketing around nickel price volatility, EV platform launch acceleration, and aerospace qualification timeline compression anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material specification, end-user category, and application methodology alongside regional regulatory cluster alignment. CAGRs derived from installed capacity growth rates, equipment investment cycles, and OEM procurement pattern shifts. Industry-specific forecast inputs incorporated PMDA and CDSCO biocompatibility documentation timelines and METI quality framework enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in Chinese EV subsidy policy, Indonesian nickel export regulations, or Japanese yen exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding equipment utilization rates and operator skill availability. Cross-checking against Nadcap accreditation databases and OEM supplier qualification registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Laser Cladding Market