
 Precision Roller Levelers Market | 2026-2036
Precision Roller Levelers Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Roller Levelers Market Insights
Aftermarket maintenance contracts and remote diagnostics subscriptions are recalibrating how precision roller levelers generate lifetime value for original equipment vendors. Heinrich Georg GmbH Maschinenfabrik leverages its German engineering heritage to dominate high-tolerance applications in automotive steel processing. ARKU Maschinenbau GmbH anchors its competitive position through comprehensive service networks spanning North American and European metal fabrication corridors. Herr-Voss Stamco differentiates via deep specialization in heavy-gauge leveling systems for construction-grade plate.
Precision roller levelers are mechanical flattening systems employing multiple offset rolls—typically five to twenty-one rollers arranged in staggered configurations—to eliminate internal stresses and correct shape defects in coiled or sheet metal through repeated bending cycles, achieving flatness tolerances within millimeters per meter. Hydraulic levelers command premium positioning in high-force applications above twelve millimeter material thickness, while electric servo-driven units capture expanding share in mid-gauge automotive and appliance manufacturing where energy efficiency and programmable roll gap control prove decisive. Fully automatic operating modes with programmable logic controllers now represent the fastest-growing configuration segment, displacing manual and semi-automatic alternatives as labor costs rise and repeatability requirements tighten across metal fabrication and plastics processing verticals.
FDA equipment validation protocols influence precision roller levelers deployed in medical device component manufacturing, while EPA emissions standards for metal finishing operations shape demand for cleaner hydraulic fluid systems and electric alternatives. OSHA machine guarding requirements and EU Machinery Directive conformity assessments create compliance barriers that favor established vendors with certified safety architectures over emerging competitors. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional content requirements that threaten to fragment equipment sourcing strategies across Atlantic and Pacific supply corridors.
Market Dynamics
Automotive electrification is compressing tolerance windows for battery tray manufacturing, forcing precision roller leveler vendors to recalibrate roll gap control architectures and real-time feedback systems for aluminum and high-strength steel processing.
Growth Catalysts
- EU Machinery Directive compliance mandates:European metal fabrication facilities must retrofit legacy leveling equipment with ISO 13849-certified safety architectures, generating replacement demand for PLC-integrated automatic systems.
- China's Yangtze River Delta steel cluster expansion:Processing capacity additions in Jiangsu and Zhejiang provinces are pulling precision roller leveler installations for cold-rolled coil preparation.
- Servo-electric roll gap technology:Programmable electric drives are capturing mid-gauge automotive and appliance manufacturing where energy efficiency targets tighten operating cost structures.
Market Restraints
- Specialized alloy roll sourcing concentration:Forged steel and chilled iron roll production concentrates among German and Japanese specialty foundries, exposing buyers to extended lead times and alloy price volatility.
- Hydraulic fluid EPA compliance costs:EPA emissions standards for metal finishing operations are elevating maintenance expenditures for high-force hydraulic levelers above twelve millimeter thickness capacity.
- Mechanical substitute pressure from tension levelers:Strip processing lines above two meters width increasingly specify tension leveling for surface-critical applications, constraining precision roller leveler addressable market at the wide-gauge boundary.
Strategic Opportunities
- India PLI scheme for specialty steel:Production-linked incentive allocations for high-grade automotive steel are stimulating greenfield flatness correction capacity in Maharashtra and Gujarat industrial corridors.
- Remote diagnostics subscription models:Vendors can capture recurring revenue streams by unbundling predictive maintenance from equipment sales through IoT-enabled vibration and thermal monitoring of bearing assemblies.
- FDA validation protocol convergence:Medical device component manufacturers require documented flatness certification for implant-grade titanium and cobalt-chrome sheets, opening premium pricing tiers for validated equipment architectures.
Industry Challenges
- Roll grinding technician scarcity:Precision crowning and surface finish restoration demands journeymen with five-plus years of cylindrical grinding experience, a skill cohort shrinking across North American and European maintenance departments.
- Legacy Allen-Bradley PLC integration friction:Brownfield facilities running SLC 500 and ControlLogix architectures face protocol translation complexity when retrofitting modern servo drives onto existing electrical backplanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Roller Levelers Market |
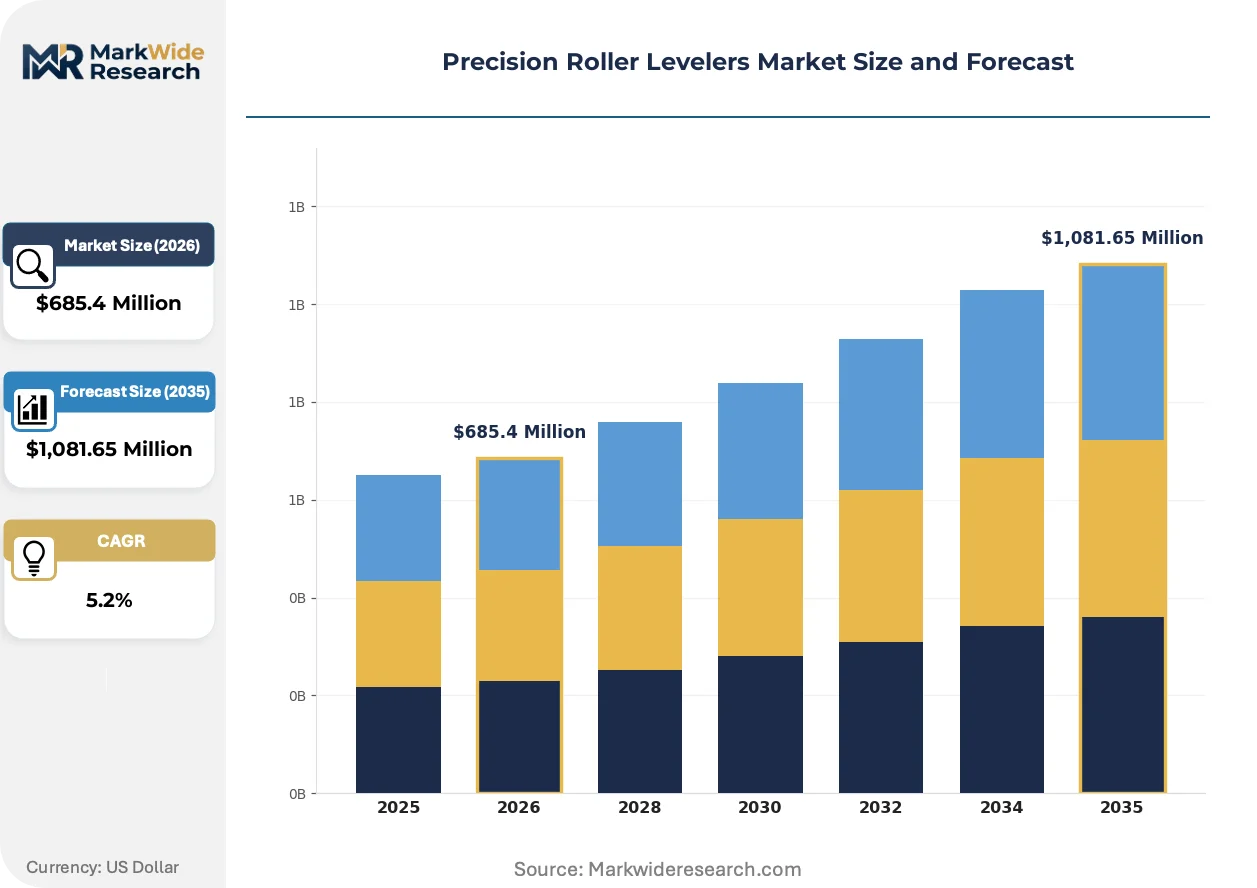
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Levelers, Hydraulic Levelers, Electric Levelers, Pneumatic Levelers End User: Manufacturers, Construction, Aerospace, Automotive Operating Mode: Manual, Semi-Automatic, Fully Automatic, Programmable Industry Vertical: Metal Fabrication, Woodworking, Plastics Processing, Others |
| Companies Covered | Bradbury Group, B&K, Heinrich Georg GmbH Maschinenfabrik, ARKU Maschinenbau GmbH, Herr-Voss Stamco, KOHLER Maschinenbau GmbH, Bruderer, Raster, Ardcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Roller Levelers Market Trends and Innovations
Digital thread integration across design, production, and service phases is compressing how precision roller leveler vendors capture and monetize operational data from installed equipment bases.
Artificial intelligence-driven roll wear prediction is unifying vibration signature analysis with production scheduling algorithms to optimize maintenance windows. Tier-one automotive stampers in Germany and Japan are piloting these systems to eliminate unplanned leveling line downtime. The technology is unifying equipment OEMs with cloud infrastructure providers in data-sharing partnerships that reshape traditional aftermarket revenue capture.
REACH substance restrictions on chromium VI compounds in metal finishing are compelling hydraulic fluid reformulation and seal material substitution across European installations. Equipment vendors must recertify wetted component compatibility with bio-based hydraulic fluids and perfluoropolymer alternatives. High-force hydraulic leveler segments face the steepest compliance cost escalation as operating pressures above three hundred bar intensify material performance requirements.
Buyer consolidation among steel service centers is compressing vendor negotiation leverage and elongating payment terms. Multi-site procurement groups in the US Southeast and German Ruhr region are centralizing capital equipment decisions, displacing distributed purchasing authority that previously favored regional distributor relationships. After-sales service contracts now function as relationship anchors as equipment margins compress under consolidated buyer price pressure.
Precision Roller Levelers Market Segmentation
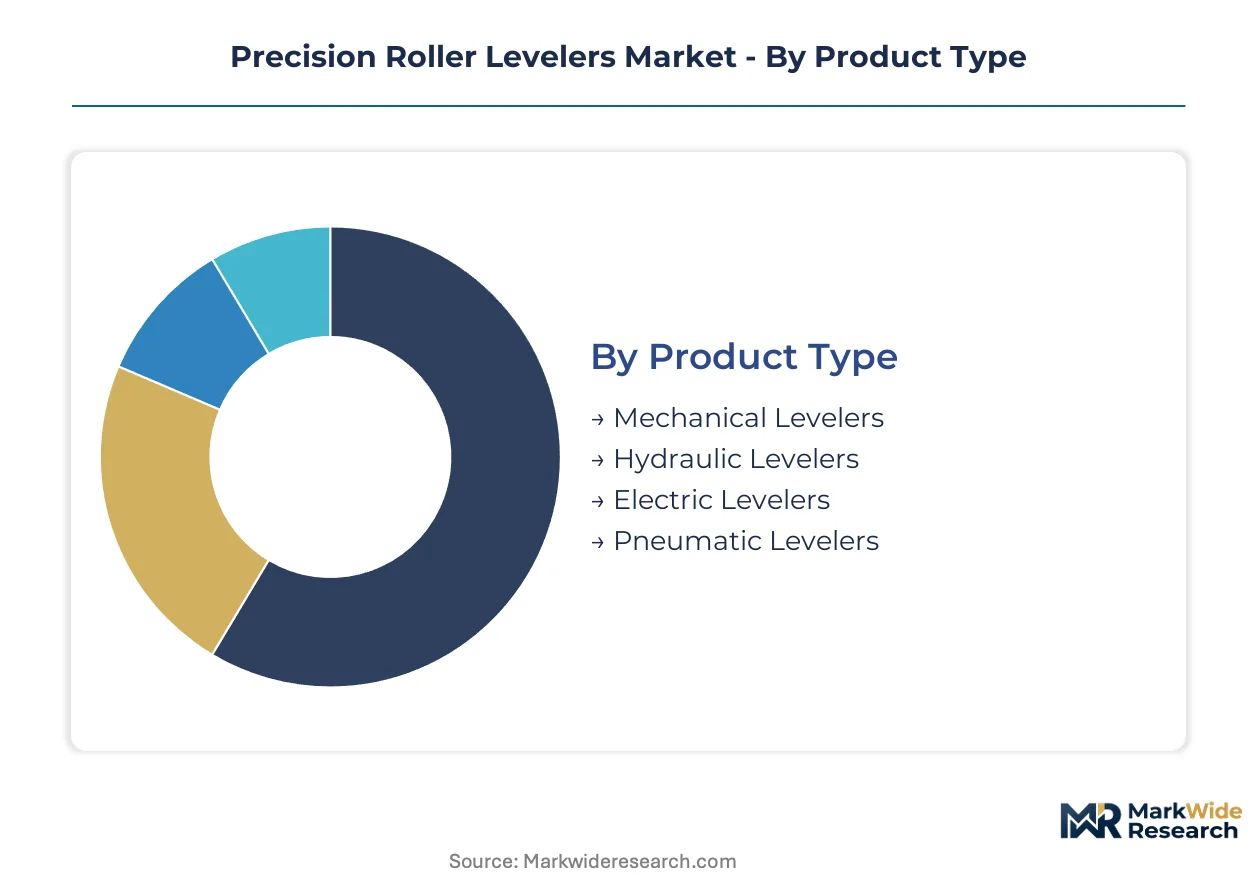
Segmentation in precision roller levelers determines capital allocation priorities across divergent force requirements, automation maturity, and end-use tolerance specifications. Equipment specifications vary dramatically between heavy-gauge plate processing and thin-gauge automotive coil applications, necessitating distinct procurement frameworks.
Product Type:
Volume deployment concentrates in mid-force electric systems, while premium positioning attaches to high-force hydraulic architectures serving thick-gauge applications.
- Mechanical Levelers:These systems employ fixed-roll arrangements with manual gap adjustment, delivering consistent bending cycles for standard-gauge carbon steel processing. Demand clusters in Eastern European metal service centers where legacy equipment replacement cycles dominate procurement budgets.
- Hydraulic Levelers:High-force architectures operating above three hundred bar pressure handle material thickness exceeding twelve millimeters. Shipbuilding yards in South Korea and construction-grade plate mills in Germany specify these systems for heavy-gauge structural steel flattening, though EPA emissions standards elevate fluid maintenance expenditures.
- Electric Levelers:Servo-driven roll gap control enables programmable bending profiles with energy efficiency advantages over hydraulic alternatives. Appliance manufacturers in Mexico and automotive stampers in Spain are migrating toward these systems as electricity costs outpace hydraulic fluid pricing.
- Pneumatic Levelers:Compressed-air actuation suits light-gauge aluminum and specialty alloy processing where contamination-free operation matters. Medical device component manufacturers in Switzerland and precision electronics metal suppliers in Taiwan deploy these for thin-strip applications.
Mature deployment sits with mechanical levelers. Newer deployment is concentrated in electric levelers with programmable servo architectures.
End User:
Application complexity separates volume purchasers from premium specification buyers across tolerance windows and throughput requirements.
- Manufacturers:OEMs and contract fabricators operating integrated production lines represent the broadest addressable base. Tier-one automotive suppliers in Germany and Japan specify precision roller levelers for electric vehicle battery tray production, where flatness tolerances compress to fractions of millimeters per meter.
- Construction:Infrastructure-grade steel processors prioritize throughput over extreme precision, favoring robust mechanical and hydraulic systems. Bridge fabrication yards in the United States and commercial building steel suppliers in Australia drive demand for heavy-gauge leveling capacity.
- Aerospace:Titanium and aluminum alloy processing for airframe components demands validated flatness certification. Boeing and Airbus supply chain participants in France and Washington State specify equipment with documented compliance to aerospace material specifications.
- Automotive:Dedicated automotive stampers operate the most demanding tolerance requirements for exposed body panel production. Battery enclosure manufacturing for electric vehicles is pulling new precision leveler installations in China and Hungary.
Procurement volume concentrates with manufacturers. Premium pricing capture sits with aerospace validation requirements.
Operating Mode:
Labor cost trajectories and repeatability requirements are accelerating automation migration across all gauge categories.
- Manual:Operator-controlled roll adjustment persists in low-volume custom fabrication shops and developing market installations. Maintenance departments in India's Maharashtra industrial corridor retain manual systems for specialty alloy prototyping.
- Semi-Automatic:Partial PLC integration with manual override capability bridges legacy operator skill bases with modern throughput demands. Steel service centers in Poland and Turkey favor this configuration during workforce transition periods.
- Fully Automatic:Complete PLC-controlled operation with recipe storage for multiple material grades now dominates new installations. ISO 13849 safety certification requirements in European facilities are mandating automatic architectures for greenfield projects.
- Programmable:Advanced servo control with real-time feedback and Industry 4.0 connectivity represents the technology frontier. German automotive stampers and Japanese appliance manufacturers pilot these systems for predictive maintenance integration.
Installed base concentration remains with semi-automatic systems. Steepest expansion trajectory belongs to fully automatic configurations with integrated safety architectures.
Industry Vertical:
Material handling characteristics and surface finish requirements differentiate vertical-specific equipment specifications.
- Metal Fabrication:The foundational vertical spanning carbon steel, stainless steel, and aluminum processing across all gauge ranges. China's Yangtze River Delta steel cluster expansion in Jiangsu and Zhejiang provinces is pulling significant cold-rolled coil preparation equipment demand.
- Woodworking:Specialized roller levelers for engineered wood panel flattening and veneer processing operate at reduced force specifications. European furniture manufacturing consolidation in Italy and Germany sustains niche equipment demand.
- Plastics Processing:Thermoplastic sheet flattening requires temperature-controlled roll configurations and non-stick surface treatments. Medical packaging film producers in Massachusetts and consumer goods sheet suppliers in Thailand specify these adaptations.
- Others:Composite material processing, rubber sheet manufacturing, and specialty material applications with custom roll configurations. Wind turbine blade fabricators in Denmark and battery separator film producers in South Korea drive specialized demand.
Revenue concentration anchors in metal fabrication. Diversification momentum is building in plastics processing for medical and electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese specialty foundries, while consumption spreads across automotive corridors and steel processing clusters. China's Yangtze River Delta absorbs the largest share of new installations for battery tray manufacturing. Regulatory divergence between EPA emissions rules in the United States and EU Machinery Directive mandates is fragmenting equipment specification standards.
Germany
Automotive OEMs in Stuttgart and Munich are retrofitting legacy leveling lines with ISO 13849-certified safety architectures for electric vehicle production. The EU Machinery Directive compels systematic replacement of manual systems in Ruhr region metal fabrication facilities. Heinrich Georg GmbH Maschinenfabrik anchors high-tolerance supply from its headquarters region while serving battery tray manufacturers across Bavaria and Baden-Württemberg.
China
Jiangsu and Zhejiang provinces in the Yangtze River Delta are adding cold-rolled coil preparation capacity that pulls precision roller leveler installations. MIIT industrial upgrading guidelines favor programmable servo architectures over hydraulic alternatives in new steel processing facilities. Battery enclosure manufacturing for domestic EV brands is concentrating demand in Shanghai's automotive supplier corridor and Ningbo's metals processing zone.
United States
Bridge fabrication yards in Pennsylvania and Ohio specify heavy-gauge hydraulic systems for infrastructure-grade plate processing. OSHA machine guarding requirements and EPA emissions standards for metal finishing operations elevate compliance costs for fluid-based systems above twelve millimeter capacity. Steel service center consolidation across the Southeast is centralizing procurement decisions and compressing vendor margins.
Japan
Tier-one automotive stampers in Toyota City and Yokohama are piloting AI-driven roll wear prediction systems to eliminate unplanned downtime. METI energy efficiency targets accelerate migration from hydraulic to electric servo architectures in mid-gauge applications. Specialty alloy roll sourcing from domestic foundries exposes buyers to extended lead times as automotive flatness tolerances compress.
India
Maharashtra and Gujarat industrial corridors are adding flatness correction capacity under PLI scheme allocations for high-grade automotive steel. BIS certification requirements for imported equipment create compliance barriers favoring vendors with established Indian service networks. Greenfield steel processing investments in Pune and Ahmedabad are specifying fully automatic PLC-integrated architectures.
Precision Roller Levelers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the precision roller leveler market. German and Japanese fabricators dominate high-tolerance applications through captive foundry relationships and multi-decade service infrastructure. Three strategic archetypes define competitive positioning: integrated engineering houses with in-house roll production, regional specialists leveraging distributor networks for aftermarket capture, and automation-focused vendors unbundling predictive maintenance through IoT subscriptions. Capacity expansion in Asian steel corridors and technology licensing for servo-electric architectures represent the dominant competitive moves.
Among German engineering houses, Heinrich Georg GmbH Maschinenfabrik and ARKU Maschinenbau GmbH exemplify the integrated archetype with comprehensive service networks spanning European and North American metal fabrication corridors. Herr-Voss Stamco occupies a position within the heavy-gauge specialization tier. These three entities represent distinct competitive vectors: heritage engineering dominance, geographic coverage breadth, and application-specific depth.
| Leading Market Players |
|---|
| Bradbury Group |
| B&K |
| Heinrich Georg GmbH Maschinenfabrik |
| ARKU Maschinenbau GmbH |
| Herr-Voss Stamco |
| KOHLER Maschinenbau GmbH |
| Bruderer |
| Raster |
| Ardcor |
| Others |
Pricing and Supply Chain Analysis
Buyer consolidation among steel service centers is compressing vendor negotiation leverage and elongating payment terms across North American and European procurement corridors. Multi-site procurement groups in the US Southeast and German Ruhr region are centralizing capital equipment decisions, forcing suppliers to absorb cost compression through after-sales bundling and extended warranty financing.
Pricing Analysis
Margin tightening in mid-gauge electric levelers reflects servo-drive component cost escalation and electricity tariff divergence across manufacturing geographies. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13849-certified automatic architectures from semi-automatic configurations and legacy mechanical systems. Cost-down pressure on hydraulic high-force units accelerates because EPA emissions compliance elevates fluid maintenance expenditures above twelve millimeter capacity. Steel service centers exhibit highest price sensitivity, while aerospace validators accept premium positioning for documented flatness certification.
Supply Chain Analysis
Journeyman roll grinding technicians with five-plus years of cylindrical grinding experience are shrinking across North American and European maintenance departments, constraining aftermarket service capacity expansion. Forged steel and chilled iron roll production concentrates among German and Japanese specialty foundries, exposing equipment buyers to extended lead times and alloy price volatility. Precision roller leveler manufacturing draws from specialty alloy bar stock, high-pressure hydraulic components, and programmable servo drive systems. Single-source vulnerability concentrates in Japanese and German foundry supply for crowned work rolls. Distribution runs through OEM-direct sales for large automotive stampers and authorized distributor networks for mid-cap metal service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision roller leveler market sits in a technology-transition phase as servo-electric roll gap architectures displace hydraulic systems in mid-gauge automotive and appliance manufacturing.
For Market Incumbents: Anchor competitive position through captive supply of specialty alloy rolls and certified safety architectures that emerging competitors cannot rapidly replicate. Tension leveler substitution threatens wide-gauge precision roller leveler addressable market; defend through vertical integration into predictive maintenance subscriptions and IoT-enabled remote diagnostics. Capacity addition in China's Yangtze River Delta and India's Maharashtra corridor secures proximity to fastest-growing demand clusters. For New Entrants and Emerging Players: Launch via asset-light design partnerships with Indian and Southeast Asian fabricators seeking programmable servo architectures without legacy hydraulic infrastructure burden. Medical device component manufacturing presents underpenetrated white space requiring FDA validation protocol compliance that incumbents have not fully exploited. Target India's PLI scheme-stimulated greenfield steel processing investments in Gujarat and Pune for automatic PLC-integrated system penetration. For Investors and Strategic Acquirers: Re-rating potential sits with automation-focused vendors unbundling predictive maintenance through IoT subscriptions given recurring revenue model durability against equipment margin compression. Long-term viability across the analysis window favors vendors with demonstrated ISO 13849 certification pathways and established service networks in European and North American metal fabrication corridors. Monitor AI-driven roll wear prediction pilot adoption among German and Japanese Tier-one automotive stampers as inflection indicator for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Roll Production | German and Japanese foundry relationships secure supply continuity for high-tolerance automotive applications. |
| Remote Diagnostics Subscription Launch | IoT-enabled vibration monitoring transforms aftermarket economics for original equipment vendors. |
| Servo-Electric Architecture Licensing | Technology transfer agreements accelerate penetration in Mexico and Spain appliance manufacturing corridors. |
| ISO 13849 Safety Certification Investment | EU Machinery Directive compliance mandates displace manual systems across Ruhr region metal fabrication. |
| India PLI Scheme Joint Venture Formation | Maharashtra and Gujarat greenfield steel capacity requires automatic leveling line partnerships with local fabricators. |
Research Methodology
Multi-period observation of servo-electric adoption rates, safety certification timelines, and aftermarket contract attach rates anchored the trend analysis, supplemented by interviews with plant engineers at automotive stampers, maintenance directors at steel service centers, aftermarket service heads at OEMs, and procurement leads at battery tray manufacturers. Secondary validation incorporated customs data for precision leveling equipment trade flows, SEC filings for capital equipment vendors, MIIT industrial upgrading guidelines, and EU Machinery Directive implementation reports. Bottom-up equipment installation tracking and top-down steel processing capacity expansion modeling were triangulated against primary field intelligence.
Segment-weighting across product type, operating mode, end user, and industry vertical dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from installed base turnover analysis and greenfield capacity addition pipelines across automotive and steel processing verticals. Forecast inputs incorporated battery enclosure manufacturing capacity expansion for electric vehicles and REACH substance restriction compliance cost trajectories for hydraulic fluid systems.
The model assumes a particular technology adoption path; alternative pathways for servo-electric displacement of hydraulic architectures would alter the outlook if electricity cost trajectories diverge from current regional patterns. Forecasts reflect assumptions regarding alloy price stability, certification timeline adherence, and buyer consolidation velocity in North American steel service centers. Material deviation in carbon border adjustment implementation or regional content requirement enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Right Angle Fastener Market