
 Plush Toy Market | 2026-2036
Plush Toy Market Size, Share, and Industry Trends Forecast 2026-2036
Plush Toy Market Analysis
Chinese textile manufacturers is expanding plush toy production capacity to serve licensed entertainment properties and collector segments. Jellycat leverages British design heritage to dominate premium gift positioning across specialty retail channels. Steiff sustains artisan manufacturing credibility through hand-finished construction and limited-edition releases. CustomPlushMaker competes in the bespoke segment through direct-to-consumer digital configuration tools.
Plush toys are soft, textile-based play objects constructed from woven or knitted outer fabrics with synthetic or natural fiber filling, typically incorporating embroidered or plastic safety eyes and reinforced seam construction for durability. These items serve dual commercial purposes as developmental tools for infant sensory stimulation and as licensed merchandise vehicles for entertainment franchise monetization. Stuffed Animals anchors volume demand through evergreen appeal to toddlers and persistent licensing partnerships with film studios. Organic Fabric represents the fastest-growing material segment as parental purchasing shifts toward hypoallergenic and sustainably certified textile options. Online Retail captures margin expansion through direct brand relationships and subscription-based collectible releases.
REACH in Europe and CPSIA in the United States enforce phthalate limits and flammability standards that elevate compliance costs for polyester-dominant supply chains. ISO 8124 toy safety standards govern physical and chemical testing protocols across export-oriented manufacturing hubs. Stakeholders must monitor evolving extended producer responsibility frameworks for textile waste recovery that will reshape material selection and end-of-life product design obligations.
Market Dynamics
Licensed entertainment properties are pulling production capacity toward character-driven SKUs, compressing lead times for seasonal releases while elevating minimum order quantities for independent designers.
Growth Catalysts
- REACH and CPSIA convergence:Harmonized phthalate testing protocols reduce duplicate certification costs for cross-border suppliers serving European and American retail channels simultaneously.
- Collector segment maturation:Adult purchasers now drive limited-edition pre-orders through direct brand channels, expanding average transaction values beyond traditional children's gifting occasions.
- Polyester recycling infrastructure:Post-consumer PET flake availability is scaling rPET fiber production for plush fillings, aligning with retailer sustainability procurement mandates.
Market Restraints
- Concentrated synthetic fiber supply:Zhejiang and Jiangsu provinces control over 70% of global polyester staple fiber output, exposing brands to single-region disruption risk.
- Flammability testing bottlenecks:ISO 8124-2 compliance queues at accredited laboratories extend product launch timelines by 8-12 weeks during peak Q3 certification periods.
- Digital entertainment substitution:Screen-based character engagement through streaming and gaming platforms captures discretionary spending that previously flowed to physical merchandise.
Strategic Opportunities
- India specialty retail expansion:Organized toy retail penetration remains below 15% in tier-2 and tier-3 cities, creating first-mover positioning for branded plush assortments.
- EU Green Deal textile requirements:Mandatory recycled content thresholds for consumer products will favor early movers with established rPET supply agreements.
- Voice commerce integration:Smart speaker-enabled reordering is capturing replenishment purchases for comfort objects and sleep aids, bypassing traditional shelf competition.
Industry Challenges
- Licensed IP negotiation complexity:Entertainment studios are consolidating exclusive manufacturing agreements, raising barriers for mid-tier brands seeking character partnerships.
- Artisan skill attrition:Hand-finishing expertise for premium collectible construction is contracting as veteran workers exit without structured apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plush Toy Market |
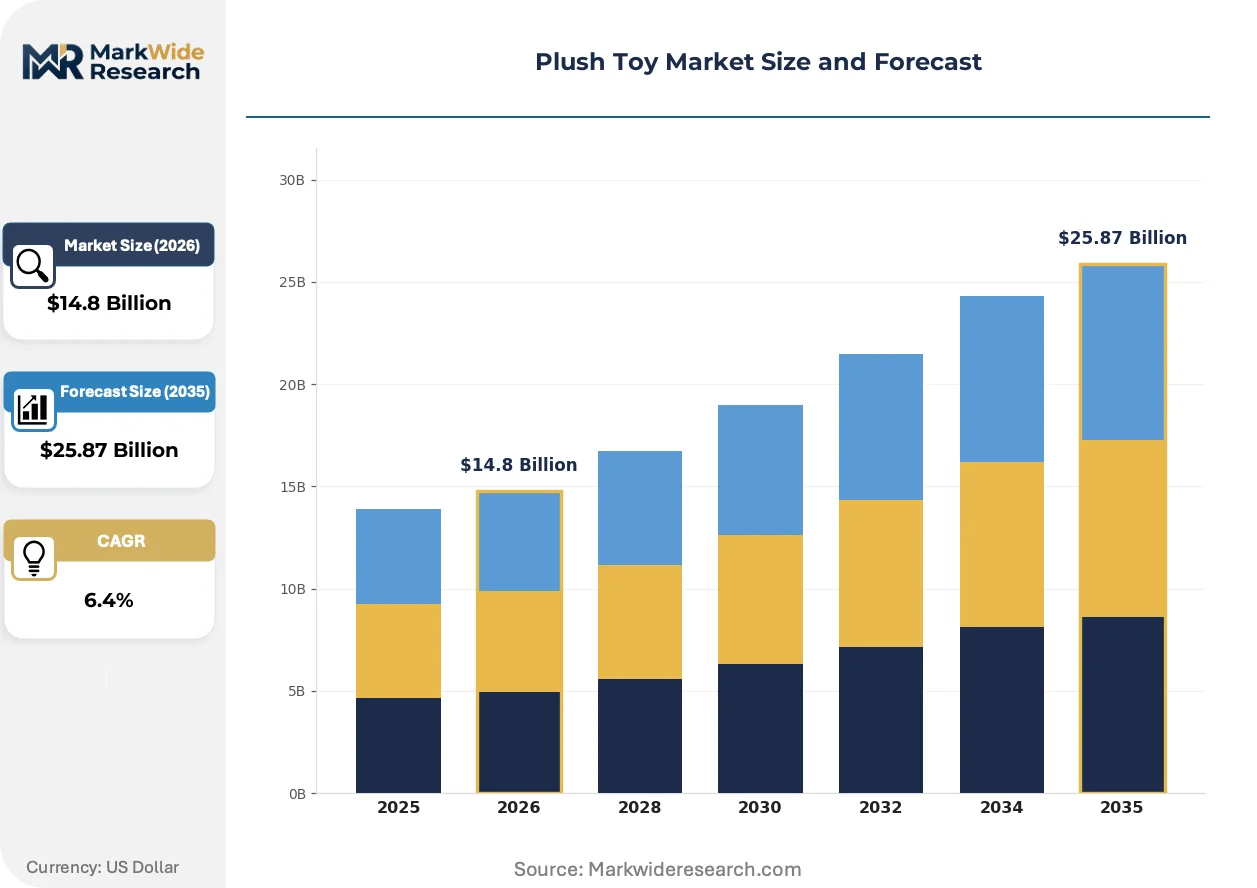
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stuffed Animals, Plush Dolls, Cushions, Pillows Material: Cotton, Polyester, Acrylic, Organic Fabric Age Group: Infants, Toddlers, Children, Teens Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Stores |
| Companies Covered | Aurora World, CustomPlushMaker, GUND, FAO Schwarz, Hansightoy, Jellycat, Ty Inc., Aokuma Toy, Steiff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plush Toy Market Emerging Trajectories
Digital configuration tools are fragmenting the traditional wholesale model, enabling direct relationships between manufacturers and end-consumers that bypass conventional retail markup structures.
Blockchain-based provenance tracking is decentralizing authentication for limited-edition releases. Collector communities in Germany and Japan are adopting tokenized ownership records to verify hand-numbered artisan pieces. This distributed verification model is compressing secondary market friction and reducing reliance on centralized certificate-of-authenticity systems.
REACH Annex XVII updates are tightening restrictions on allergenic disperse dyes used in polyester coloration. European manufacturers are accelerating migration to GOTS-certified organic cotton shells and natural latex fillings. Specialty retailers in France and the Netherlands are responding by segmenting shelf space toward certified sustainable assortments.
Gifting occasions are fragmenting across micro-celebrations rather than traditional holidays. Subscription box services and social media-triggered impulse purchases are displacing calendar-driven retail buying patterns. This behavioral shift is most pronounced among millennial and Gen-Z purchasers in urban United States markets, where unboxing content drives viral demand spikes for specific SKUs.
Plush Toy Market Segmentation
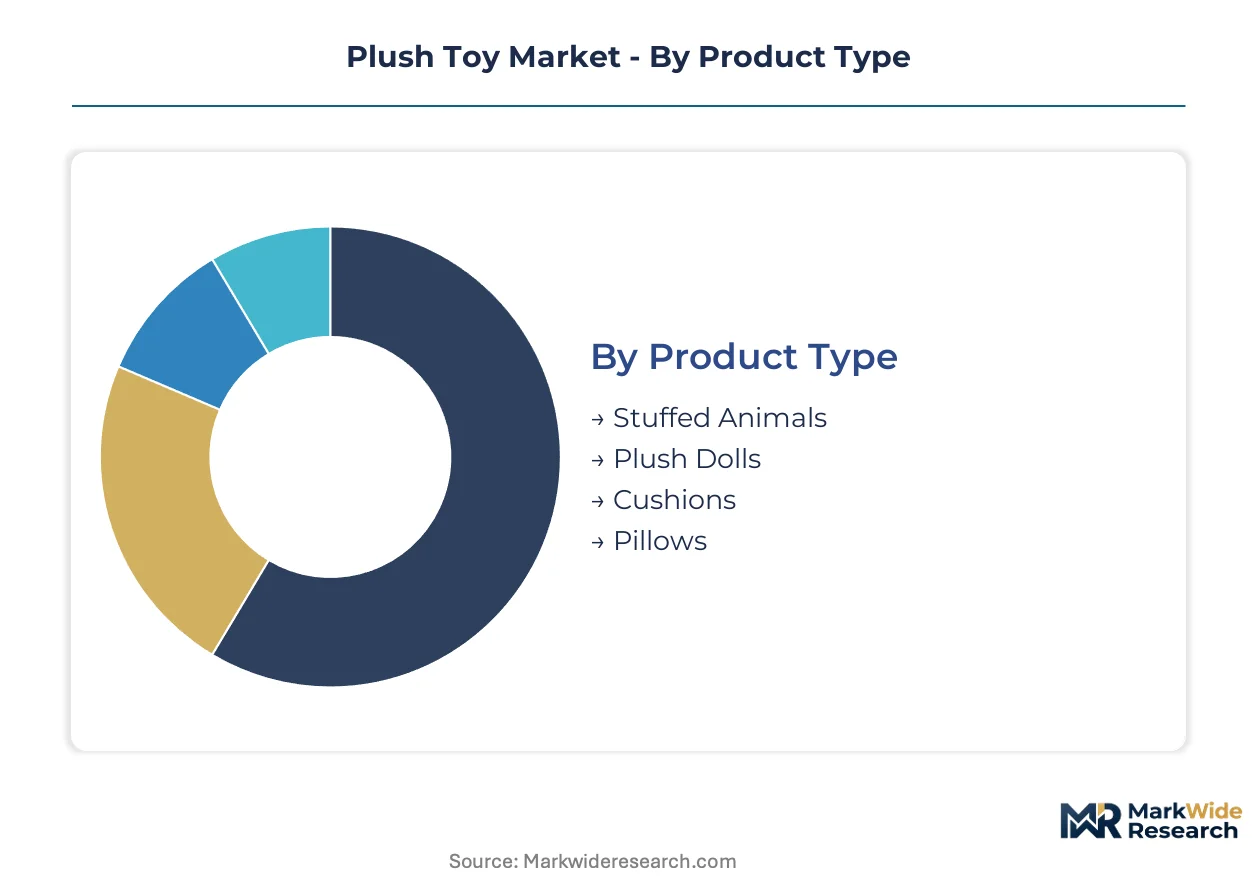
Segmentation in the plush toy market reveals how manufacturing capabilities, safety certifications, and channel economics concentrate value capture across distinct product configurations. Understanding these divisions exposes where supply bottlenecks and margin expansion opportunities align.
Product Type:
Production capacity clusters around formats that balance licensing economics with manufacturing repeatability, leaving artisan-construction segments supply-constrained.
- Stuffed Animals:Three-dimensional forms with embroidered features and reinforced seam construction dominate volume manufacturing. Demand concentrates in toddler gifting occasions across the United States and Germany, where licensed character partnerships with film studios drive seasonal replenishment cycles and minimum order quantity compression for independent designers.
- Plush Dolls:Humanoid forms with articulated limbs and detailed facial embroidery command premium positioning in collector segments. Adult purchasers in Japan and the United Kingdom now drive limited-edition pre-orders through direct brand channels, expanding average transaction values beyond traditional children's retail.
- Cushions:Flat-profile decorative forms with simplified construction serve interior styling applications through home goods retailers.
- Pillows:Ergonomic sleep support designs with hypoallergenic fillings capture replenishment demand via voice commerce integration for comfort objects.
Today's leader: Stuffed Animals. Tomorrow's challenger: Plush Dolls.
Material:
Raw material sourcing decisions increasingly pivot on REACH Annex XVII dye restrictions and CPSIA phthalate compliance timelines.
- Polyester:Synthetic staple fiber derived from petroleum feedstocks remains the dominant filling and shell material due to cost efficiency and dye affinity. Zhejiang and Jiangsu provinces control over 70% of global output, exposing brands to single-region disruption risk during peak certification periods.
- Organic Fabric:GOTS-certified cotton and natural latex combinations serve parental purchasing shifts toward hypoallergenic and sustainably certified textile options. Specialty retailers in France and the Netherlands are responding by segmenting shelf space toward certified sustainable assortments.
- Cotton:Conventional natural fiber shells face margin pressure from organic certification premiums and water-intensive cultivation scrutiny.
- Acrylic:Synthetic alternative with superior colorfastness properties serves budget-tier positioning through discount retail channels.
Polyester retains volume dominance. Organic Fabric is climbing the fastest as EU Green Deal recycled content mandates reshape procurement specifications.
Age Group:
Safety standard stringency varies dramatically by developmental stage, with ISO 8124 testing protocols governing physical and chemical requirements for infant-directed products.
- Infants:Products for children under 12 months require embroidered rather than plastic safety eyes and reinforced seam construction for durability. REACH and CPSIA convergence on phthalate testing protocols reduces duplicate certification costs for cross-border suppliers serving European and American retail channels simultaneously.
- Toddlers:The 1-3 year segment anchors evergreen demand through sensory stimulation requirements and persistent licensing partnerships.
- Children:The 4-12 year bracket captures character-driven SKU concentration from entertainment property releases.
- Teens:Collector-oriented limited editions with blockchain-based provenance tracking serve maturing adult purchaser segments in Germany and Japan.
Infant safety requirements create the highest compliance barrier. Teen collector segments offer the steepest expansion trajectory for direct-to-consumer margin capture.
Distribution Channel:
Channel economics fragment as digital configuration tools enable manufacturer-direct relationships that bypass conventional retail markup structures.
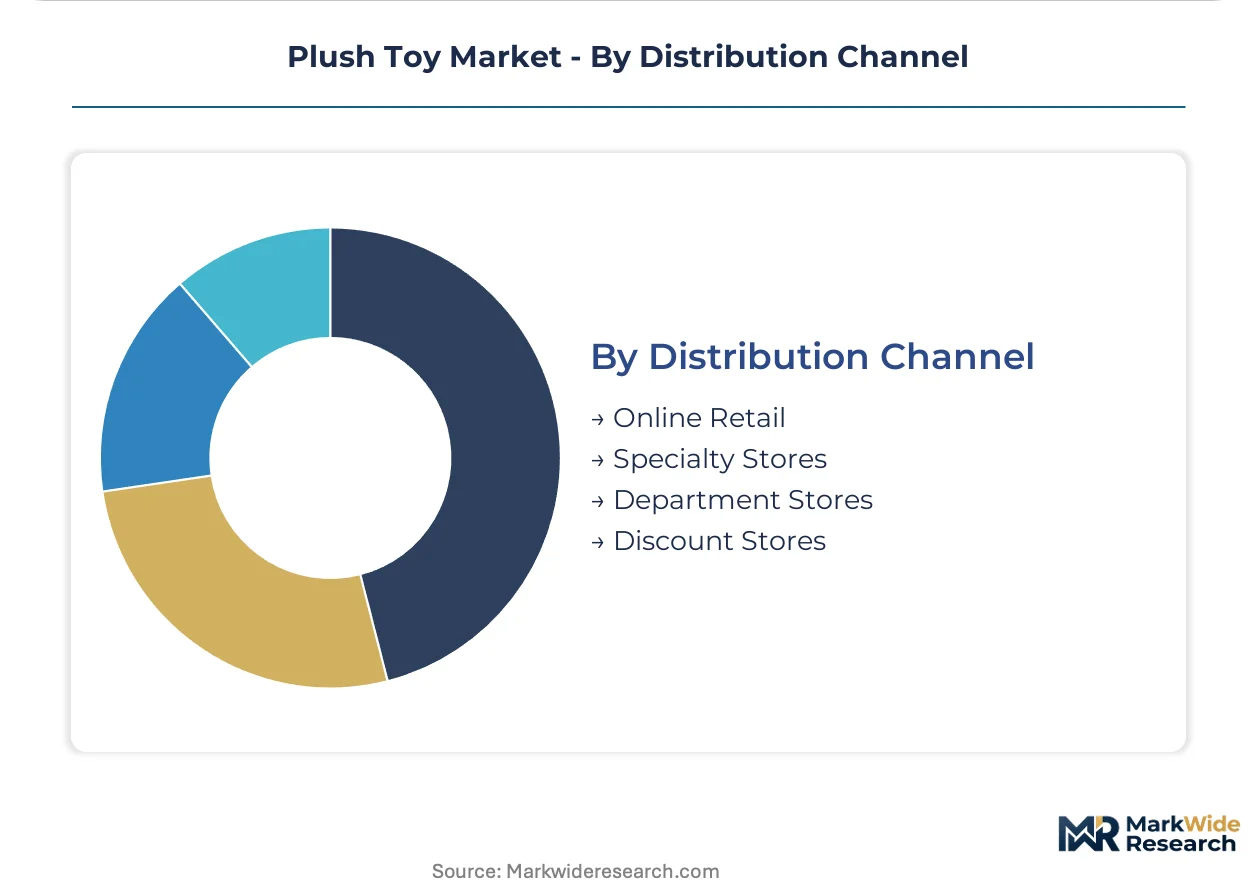
- Online Retail:Direct brand relationships and subscription-based collectible releases capture margin expansion through bypassed wholesale layers. Smart speaker-enabled reordering is capturing replenishment purchases for comfort objects and sleep aids, bypassing traditional shelf competition.
- Specialty Stores:Curated assortments with British design heritage positioning serve premium gift occasions across urban United States markets.
- Department Stores:Calendar-driven holiday merchandising faces displacement from micro-celebration gifting patterns and social media-triggered impulse purchases.
- Discount Stores:Price-sensitive volume positioning concentrates in polyester-dominant SKUs with simplified construction.
Online Retail commands margin expansion. Specialty Stores defend positioning through curation authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Annex XVII dye restrictions and CPSIA phthalate compliance costs are diverting production capacity between jurisdictions, with manufacturers relocating finishing operations to exploit regulatory-arbitrage gaps in testing and certification timelines.
China
Zhejiang and Jiangsu provinces control over 70% of global polyester staple fiber output for plush fillings. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy costs for synthetic fiber production. Yangtze River Delta manufacturers are expanding rPET fiber capacity to serve EU Green Deal recycled content mandates.
United States
Collector segments and subscription-based collectible releases drive direct-to-consumer margin expansion. The Consumer Product Safety Commission enforces CPSIA flammability standards that extend ISO 8124-2 certification queues by 8-12 weeks during peak periods. California and New York Metro anchor specialty retail penetration for premium British design heritage positioning.
Germany
Blockchain-based provenance tracking for limited-edition artisan pieces concentrates in collector communities. ECHA REACH compliance creates entry barriers for polyester-dominant imports. Bavaria and North Rhine-Westphalia sustain hand-finishing expertise pipelines for premium collectible construction.
Japan
Adult purchasers drive limited-edition pre-orders for articulated plush dolls through direct brand channels. METI product safety standards align with ISO 8124 protocols for cross-border export manufacturing. Kanto and Kansai regions host specialized retail networks for character-driven SKU releases.
India
Organized toy retail penetration below 15% in tier-2 and tier-3 cities creates first-mover positioning for branded plush assortments. BIS toy safety standards govern domestic market entry requirements. Maharashtra and Gujarat textile clusters are expanding capacity to serve licensed entertainment property demand.
Plush Toy Market Vendor Landscape
Chinese producers anchor the volume tier through polyester-dominant manufacturing scale; British and German specialists hold premium positioning through design heritage and artisan credibility. The vendor base splits between consolidated entertainment-licensing giants and fragmented bespoke configurators. Three archetypes dominate: scale-driven commodity suppliers, heritage-positioned premium houses, and digital-native customization platforms. Competitive moves concentrate on exclusive IP manufacturing agreements and direct-to-consumer channel bypass of wholesale layers.
Within the heritage-positioned tier, Jellycat and Steiff exemplify geographic design-origin differentiation, while CustomPlushMaker occupies a position in the bespoke segment through digital configuration tools. These three anchors illustrate how competitive positioning fragments across manufacturing scale, artisan credibility, and consumer-direct technology adoption.
| Leading Market Players |
|---|
| Aurora World |
| CustomPlushMaker |
| GUND |
| FAO Schwarz |
| Hansightoy |
| Jellycat |
| Ty Inc. |
| Aokuma Toy |
| Steiff |
| Others |
Supply Flow & Price Mechanics
EU Green Deal recycled content mandates gate qualified supply for premium-tier plush toy positioning, compressing margins for polyester-dependent manufacturers while elevating certified organic fabric premiums. Buyers seeking REACH-compliant and GOTS-certified assortments face constrained supplier pools that concentrate pricing power among early-movers with established rPET fiber agreements.
Pricing Analysis
Retailer markup layers separate mass-market discount channels from specialty store premiums, with direct-to-consumer subscription models capturing margin expansion through bypassed wholesale structures. Price differentiation rests on certification tier—GOTS organic commands premiums over conventional cotton—and volume scale, with licensed character SKUs resisting compression through exclusive IP agreements. Cost compression in synthetic fiber tiers is intensifying because Zhejiang energy cost elevations and dual carbon enforcement squeeze polyester staple margins. Discount store buyers exhibit highest price sensitivity, while collector segment purchasers show lowest elasticity for limited-edition artisan releases.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium British and German heritage brand distribution, while mass-market volume flows through wholesale importers serving big-box retailers. Raw material sourcing draws from Zhejiang and Jiangsu polyester fiber clusters, Indian cotton cultivation regions, and emerging Maharashtra textile expansion for licensed entertainment demand. Component dependencies include synthetic staple fiber, GOTS-certified organic cotton shells, and natural latex fillings for hypoallergenic positioning. Single-source vulnerability concentrates in Yangtze River Delta synthetic fiber production, where Ministry of Ecology and Environment enforcement elevates disruption risk. Distribution runs through Yangshan Port consolidation for European REACH compliance finishing and Los Angeles-Long Beach entry for CPSIA certification queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH Annex XVII dye restrictions and EU Green Deal mandates continuously reshape qualified supplier pools and premium access.
For Market Incumbents: Lock in exclusive licensed IP manufacturing agreements before entertainment studio consolidation raises partnership barriers. Secure backward integration into rPET fiber production through Yangtze River Delta capacity partnerships, insulating margin position against Zhejiang energy cost volatility and dual carbon enforcement.
For New Entrants and Emerging Players: Begin with India tier-2 and tier-3 city specialty retail whitespace, where organized toy penetration below 15% offers first-mover positioning for branded plush assortments. Deploy digital configuration tools for bespoke collector segments, bypassing wholesale markup structures that compress independent designer economics.
For Investors and Strategic Acquirers: Roll-up economics work for digital-native customization platforms because fragmented bespoke configurators lack scale to negotiate exclusive IP agreements independently. Target platform acquisitions with established direct-to-consumer channels and GOTS-certified supply relationships. Watch blockchain-based provenance adoption rates in German and Japanese collector communities as inflection signal for authentication technology value capture.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Supply Agreement | Secures recycled fiber access ahead of EU Green Deal mandatory thresholds. |
| GOTS Certification Investment | Unlocks premium shelf placement at French and Dutch specialty retailers. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale margin compression for collector segment pre-orders. |
| Licensed IP Exclusive Partnership | Blocks mid-tier competitors from character-driven seasonal SKU releases. |
| Blockchain Provenance Integration | Authenticates limited-edition artisan pieces for German and Japanese collectors. |
Methodological Framework
Direct dialogue with plush toy brand managers, category buyers at specialty retailers, Yangtze River Delta manufacturing operations heads, and ECHA regulatory compliance officers grounded qualitative findings. Secondary validation drew from customs trade databases, SEC filings of listed toy manufacturers, REACH Annex XVII update notices, and EU Green Deal implementation guidance documents. Bottom-up shipment data triangulated against top-down retail audit estimates across the analysis window.
Bottom-up volume modeling aggregated manufacturer capacity declarations by product type, material grade, and distribution channel, while top-down expenditure analysis tracked consumer gifting occasion patterns. Segmentation dimensions included stuffed animal versus plush doll formats, polyester versus organic fabric material tiers, infant through teen age brackets, and online versus specialty retail channels. CAGRs derived from regression against licensed entertainment release calendars and sustainability procurement mandate diffusion curves.
Several conditions sit outside the modeled scope, including unforeseen REACH chemical restriction expansions, entertainment studio licensing strategy pivots, and artisan skill attrition acceleration beyond current apprenticeship pipeline contraction. Forecasts reflect assumptions about rPET fiber cost parity achievement and voice commerce adoption for comfort object replenishment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Blind Box Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
Male Sex Toys Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Air Hockey Table Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Wooden Toys Market
Toys and Games
Table Top Games Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Smart Toys Market
Toys and Games
Decompression Toys Market
Toys and Games
Construction Toys Market
Toys and Games
Global Educational Toy Market