
 Clothing E-Commerce Platform Market | 2026-2036
Clothing E-Commerce Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Clothing E-Commerce Platform Market Insights
Modular product bundling is decoupling traditional seasonal collections into mix-and-match capsule offerings that let buyers curate personal wardrobes. Shopify leverages its app ecosystem to let merchants assemble customized storefront toolkits for apparel sellers. Zalando sustains competitive density through its connected retail program that integrates offline stock into online availability. BigCommerce anchors mid-market clothing brands with open-SaaS architecture that reduces platform lock-in.
A clothing e-commerce platform is a software infrastructure enabling online transactions for apparel, typically integrating inventory management, payment gateways, size recommendation algorithms, and returns processing into a unified merchant-consumer interface. These systems serve the primary commercial purpose of reducing friction between distributed clothing suppliers and digitally native shoppers across geographies. The direct-to-consumer sales channel leads structural margin capture by eliminating intermediary fees, while same-day delivery models represent the fastest-growing delivery dimension as urban logistics networks mature. Subscription channels remain nascent in clothing relative to other retail verticals, with churn rates reflecting fit uncertainty rather than price sensitivity.
The EU Green Deal's CSRD disclosure mandates and ECHA REACH chemical restrictions compel platform operators to verify supplier compliance across extended textile supply chains. The US FTC's Green Guides and state-level California SB 657 transparency laws shape how platforms market sustainability claims and disclose labor practices. Stakeholders must monitor whether regulatory fragmentation between jurisdictions forces platform architecture toward modular compliance stacks or consolidated global standards.
Market Dynamics
Live-stream commerce integration with inventory management systems is compressing purchase cycles from discovery to checkout, forcing platform architectures toward real-time synchronization between content feeds and stock databases.
Growth Catalysts
- EU Green Deal textile directives:Extended producer responsibility mandates are compelling platforms to deploy circular economy modules that track garment lifecycle data and enable resale marketplace integration.
- Size recommendation algorithms:Machine learning models trained on body-scan datasets are reducing return rates by predicting fit across diverse sizing standards, cutting logistics costs for merchants.
- China's tier-one city clusters:Dense urban logistics networks in Shanghai, Beijing, and Guangzhou enable same-day delivery fulfillment that anchors consumer expectations for immediacy.
Market Restraints
- Cotton price volatility:Input cost swings in natural fiber markets compress merchant margins and complicate dynamic pricing engine calibration.
- Cross-border data localization:China's PIPL and Russia's data sovereignty rules fragment customer analytics architectures, raising compliance overhead for multi-territory platforms.
- Secondhand platform substitution:Dedicated resale apps like Depop and Vinted capture younger demographics seeking lower price points, diverting volume from primary retail channels.
Strategic Opportunities
- India's tier-two urbanization:Rising disposable incomes in cities like Indore and Coimbatore create first-mover advantage for localized payment integration and vernacular interfaces.
- Digital Product Passport mandates:EU CSRD-aligned traceability requirements position compliant platforms as preferred partners for sustainability-focused brand portfolios.
- AR-virtual try-on convergence:Computer vision and 3D rendering technology fusion enables immersive fitting rooms that reduce fit-related returns in footwear and accessories categories.
Industry Challenges
- Legacy ERP integration:Merchant migration from on-premise inventory systems to cloud-native platforms demands costly middleware development and staff retraining.
- Algorithmic bias in fit prediction:Training data gaps for non-Western body types generate systematic sizing errors that damage platform credibility in Asian and African markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothing E-Commerce Platform Market |
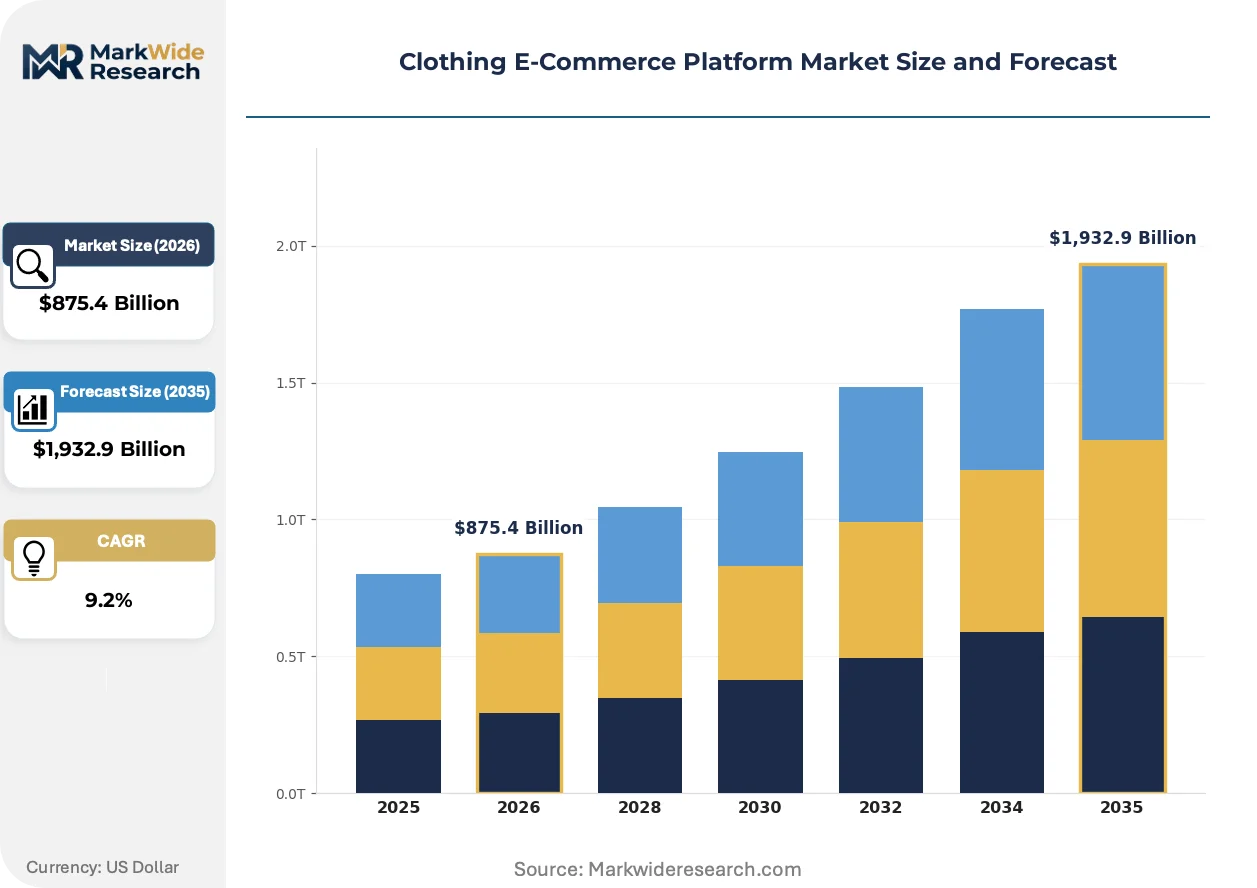
| Market Size in 2026 | $875.4 Billion |
| Market Size in 2035 | $1,932.9 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Jackets, Pants Customer Type: Men, Women, Kids, Unisex Sales Channel: Direct-to-Consumer, Marketplace, Subscription, Wholesale Delivery Model: Standard Shipping, Express Delivery, Click-and-Collect, Same-Day Delivery |
| Companies Covered | Shopify, BigCommerce, WooCommerce, Adobe Commerce, Magento, Wix, Squarespace, SCAYLE, Zalando, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothing E-Commerce Platform Market Trends and Innovations
Generative AI tools are rewriting how clothing platforms produce visual merchandising, compressing content creation timelines while raising new authenticity concerns among consumers.
Virtual try-on technology is expanding into footwear and accessories categories after proving conversion lift in apparel. Mid-market retailers in South Korea and the United Arab Emirates are deploying smartphone-based AR fitting at scale. The technology is compressing return rates by letting shoppers visualize drape and proportion before purchase commitment.
The EU AI Act's risk classification framework is forcing platforms to audit recommendation algorithms for manipulative pattern detection. High-risk systems must maintain human oversight logs and transparency disclosures. Fashion marketplaces deploying personalized styling engines face the steepest compliance costs as regulators scrutinize impulse purchase amplification.
Subscription rental models are displacing ownership patterns among urban professionals in Germany and the Netherlands. Wardrobe rotation services from platforms like HURR and By Rotation capture consumers seeking variety without storage burden. The shift is most pronounced among women aged 25-34 in metropolitan areas with limited closet space.
Clothing E-Commerce Platform Market Segmentation
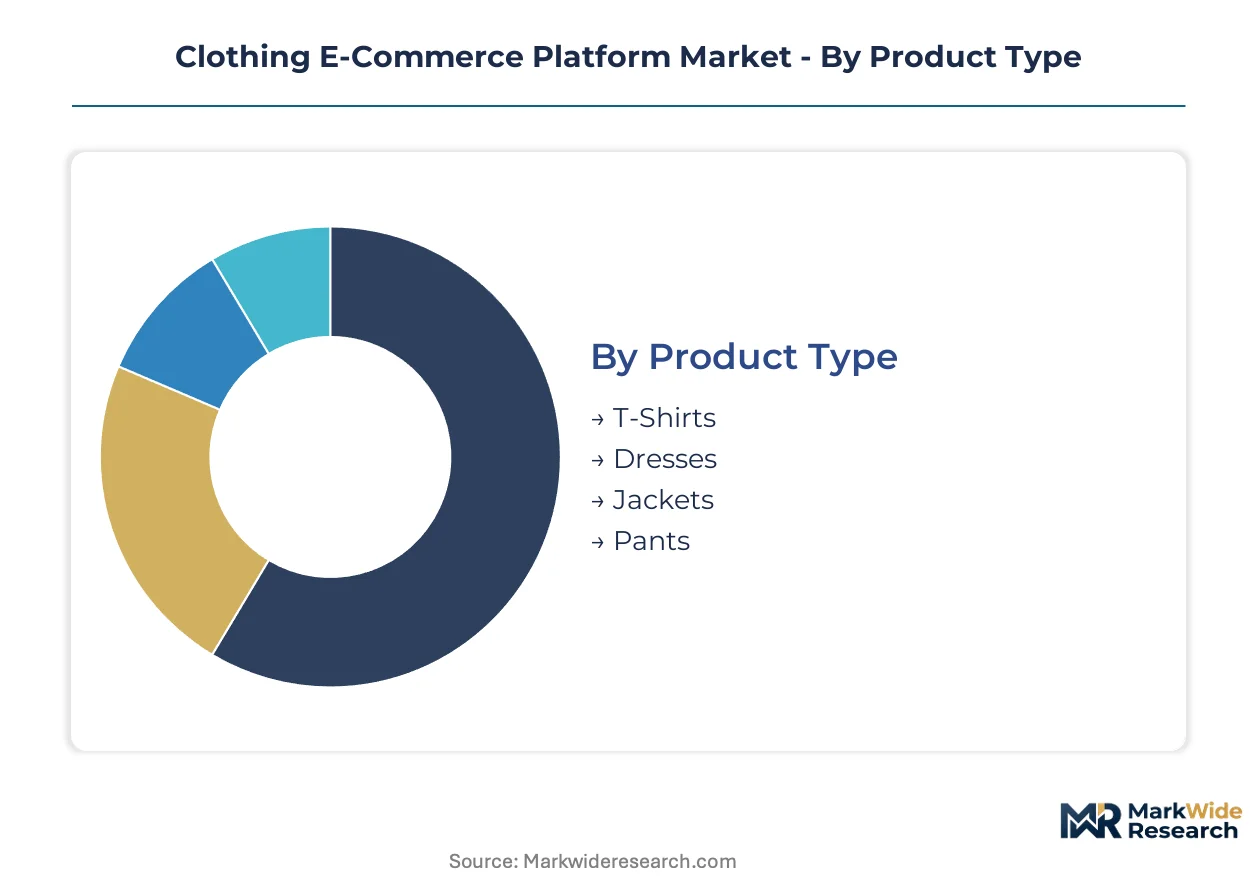
Segmentation in clothing e-commerce platforms reveals how architectural choices in inventory systems, recommendation engines, and fulfillment networks align with distinct purchasing behaviors. Platform operators configure modular technology stacks differently for each segment combination, optimizing conversion rates against return probability profiles.
Product Type:
Standardization intensity varies sharply across garment categories, with basic separates demanding minimal customization while outerwear requires complex size-matrix configurations.
- T-Shirts:High-velocity basics with standardized sizing across brands minimize fit prediction algorithm complexity. Demand clusters in direct-to-consumer channels where margin capture offsets logistics costs, though cotton price volatility compresses merchant profitability during commodity spikes.
- Dresses:Silhouette diversity and occasion-specific styling drive higher return rates, compelling platforms to deploy AR visualization tools and detailed measurement guides. Fit uncertainty concentrates returns processing in urban fulfillment hubs with garment inspection capacity.
- Jackets:Seasonal inventory cycles and size layering requirements strain warehouse management systems.
- Pants:Waist-to-hip ratio variations demand sophisticated size recommendation engines trained on regional body-scan datasets.
Most installed capacity flows through T-Shirts. Expansion is steepest in Dresses as occasion-wear platforms capture event-driven purchasing.
Customer Type:
Purchasing frequency and average order value diverge across demographic cohorts, shaping platform investment in loyalty programs versus acquisition spend.
- Women:Higher basket diversity and browsing intensity drive recommendation algorithm sophistication, with platforms deploying personalized styling engines and curated capsule collections. Frequency concentrates in tier-one Chinese cities where live-stream commerce integrates with social discovery.
- Men:Lower return rates and higher brand loyalty reduce customer service overhead, though fit prediction gaps in athletic and tailored categories generate systematic sizing errors in non-Western markets.
- Kids:Rapid size turnover and gift-purchasing patterns create demand for subscription-based replenishment services with predictive growth algorithms.
- Unisex:Sizing standardization and marketing efficiency appeal to sustainability-focused brands seeking inventory consolidation.
Transaction volume concentrates in Women. Growth velocity peaks in Kids as parental demand for circular economy options accelerates.
Sales Channel:
Margin structure and data ownership terms differentiate channel strategies, with direct relationships enabling first-party analytics against marketplace scale advantages.
- Direct-to-Consumer:Full margin capture and customer data sovereignty justify higher technology investment in proprietary size recommendation and virtual try-on capabilities. Shopify and BigCommerce anchor this segment with open-SaaS architectures reducing platform lock-in.
- Marketplace:Aggregated demand density enables logistics network optimization, though commission structures and listing fee pressure merchant unit economics. Zalando's connected retail program exemplifies inventory integration across distributed sellers.
- Subscription:Wardrobe rotation models displace ownership in German and Dutch metropolitan markets, with churn driven by fit uncertainty rather than price sensitivity.
- Wholesale:Bulk order workflows and B2B payment terms require distinct platform modules for tiered pricing and volume-based fulfillment.
Merchant adoption concentrates in Direct-to-Consumer. Marketplace expansion accelerates fastest as cross-border trade protocols mature.
Delivery Model:
Fulfillment speed expectations stratify urban versus suburban demand, with infrastructure density determining economically viable service tiers.
- Same-Day Delivery:Dense logistics networks in Shanghai, Beijing, and Guangzhou anchor consumer expectations for immediacy, requiring real-time inventory synchronization between dark stores and platform interfaces. EU Green Deal emissions reporting mandates complicate last-mile vehicle fleet configurations.
- Express Delivery:Premium positioning captures urgent occasion-based purchasing, with carrier integration APIs becoming competitive differentiators.
- Click-and-Collect:Returns reduction and foot traffic generation drive hybrid retail deployment.
- Standard Shipping:Cost-sensitive segments sustain volume through consolidated batch processing.
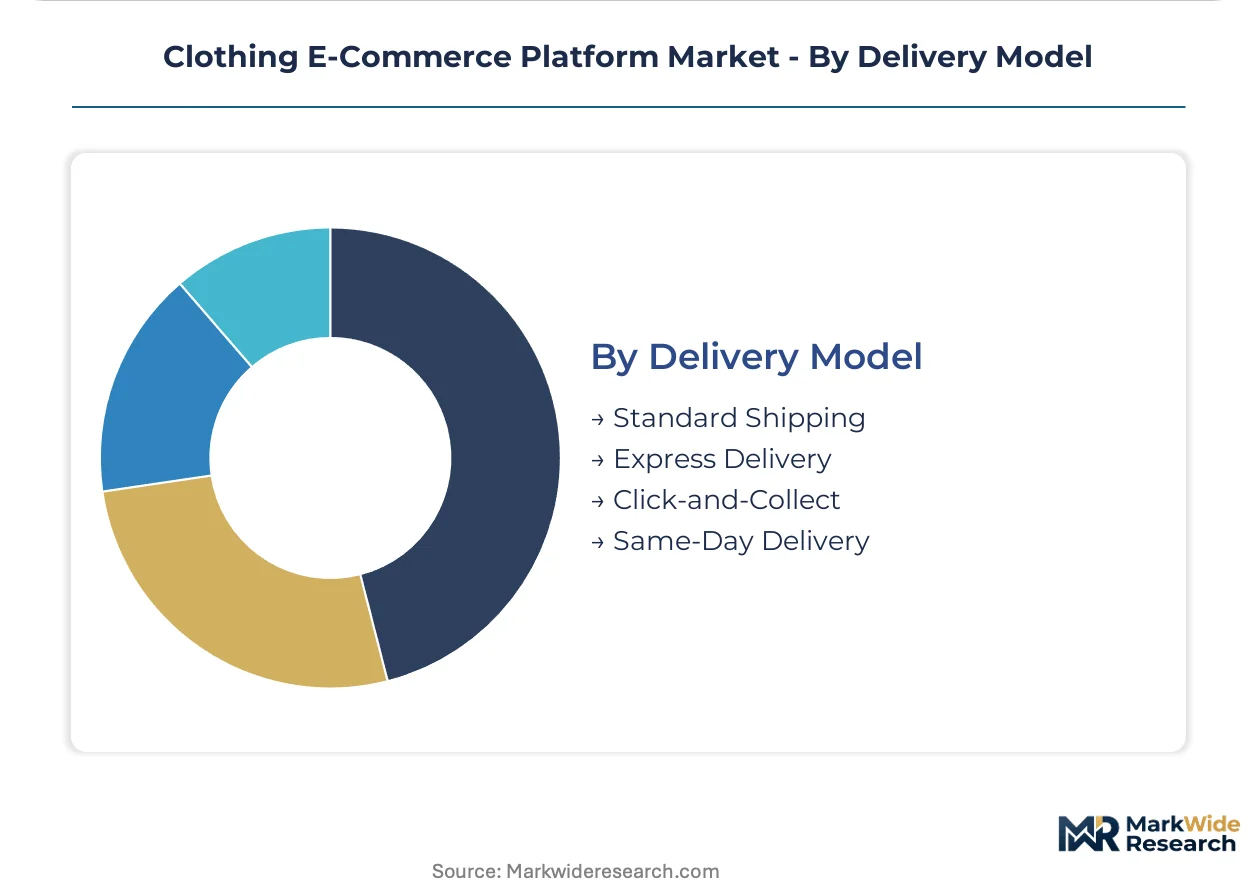
Fulfillment infrastructure concentrates in Standard Shipping. Same-Day Delivery climbs the fastest as urban micro-fulfillment networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The clothing e-commerce platform industry traces its commercial origins to Silicon Valley garage startups and Nordic early-adopter markets, with infrastructure scaling first through US venture capital and later through China's mobile-first consumer base.
United States
Direct-to-consumer brand proliferation and Shopify's merchant ecosystem expansion drive platform adoption. The FTC's Green Guides constrain how sustainability claims appear in product listings. Los Angeles and New York anchor fulfillment network density where same-day delivery partnerships with urban micro-fulfillment operators proliferate.
China
Live-stream commerce integration with inventory systems compresses purchase cycles in Shanghai and Beijing. SAMR's platform governance rules and PIPL data localization requirements fragment analytics architectures. Guangzhou's garment manufacturing clusters feed real-time stock synchronization into platform backends.
Germany
Subscription rental models displace ownership patterns among Berlin and Hamburg urban professionals. The EU Green Deal's extended producer responsibility mandates compel circular economy module deployment. Munich's logistics technology vendors supply warehouse management systems to pan-European fashion marketplaces.
United Kingdom
Cross-border trade friction post-Brexit redirects platform investment toward domestic fulfillment infrastructure. The UK's modern slavery disclosure requirements shape supplier verification protocols. London's fintech ecosystem enables embedded payment solutions for mid-market clothing merchants.
India
Tier-two urbanization in Indore and Coimbatore creates demand for vernacular interfaces and localized payment integration. RBI's digital payment regulations and DGFT's e-commerce policy framework govern cross-border data flows. Bangalore's SaaS development hubs build size recommendation algorithms trained on South Asian body-scan datasets.
Clothing E-Commerce Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across merchant sophistication tiers, with enterprise-grade customization capabilities commanding higher subscription yields than self-serve SMB tools. The vendor base stratifies between full-stack commerce platforms, modular storefront builders, and vertical-specialist fashion marketplaces. Three archetypes dominate: open-SaaS infrastructure providers, closed ecosystem aggregators, and hybrid retail integrators. Consolidation pressure manifests through API acquisition strategies and connected retail partnership networks rather than horizontal mergers.
Within the open-SaaS archetype, Shopify and BigCommerce exemplify merchant sovereignty models that reduce platform lock-in through portable data architectures. Zalando occupies a position representing hybrid retail integration, bridging offline inventory pools with online demand aggregation. These three entities anchor competitive positioning across the direct-to-consumer, mid-market brand, and fashion marketplace vectors respectively.
| Leading Market Players |
|---|
| Shopify |
| BigCommerce |
| WooCommerce |
| Adobe Commerce |
| Magento |
| Wix |
| Squarespace |
| SCAYLE |
| Zalando |
| Others |
Pricing and Supply Chain Analysis
Gen Z procurement preferences for sustainability-verified inventory are compelling platform operators to absorb supplier compliance costs into subscription tiers, compressing margins for non-certified merchants while creating premium pricing power for circular-economy-aligned vendors. This demand shift is restructuring how platforms bundle compliance overhead into merchant fee schedules.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates SaaS platform subscriptions, with price differentiation driven by API call volumes and dedicated support tiers. Pricing pressure stems from cotton price volatility compressing merchant margins and forcing downward pressure on platform take rates. Fast-fashion merchants exhibit highest price sensitivity, while luxury direct-to-consumer brands demonstrate lowest sensitivity due to full margin capture.
Supply Chain Analysis
Single-source vulnerability sits with China's Guangzhou garment manufacturing clusters, where real-time stock synchronization hinges on concentrated production capacity. Platform supply chains draw from Bangladesh, Vietnam, and India for cut-and-sew operations, with dependencies on cotton futures, synthetic fiber polymers, and logistics APIs. Tariff exposure on US-China apparel trade creates margin risk, while distribution runs through urban micro-fulfillment networks and cross-border bonded warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU Green Deal compliance investments separate sustainable platform architectures from commodity competitors. Premium merchant acquisition now depends on circular economy module deployment and extended producer responsibility tracking capabilities.
For Market Incumbents: Deploy connected retail partnerships as the primary lever to defend against dedicated resale platform substitution from Depop and Vinted. Integrate offline inventory pools into online availability to capture hybrid commerce demand. Invest in EU CSRD-aligned traceability modules to maintain preferred partner status with sustainability-focused brand portfolios.
For New Entrants and Emerging Players: Enter via India's tier-two urbanization corridor, where vernacular interfaces and localized payment integration remain underpenetrated in Indore and Coimbatore. Target mid-market clothing brands migrating from legacy ERP systems with middleware-light onboarding. Position around size recommendation algorithms trained on South Asian body-scan datasets to differentiate fit prediction accuracy.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertical-specialist fashion marketplaces possessing hybrid retail integration capabilities and circular economy infrastructure. Long-term viability favors platforms with defensible logistics network density in tier-one Chinese cities and EU Green Deal compliance architecture. Monitor churn rate divergence between subscription rental models and traditional ownership channels as the key inflection signal for business model displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Circular Economy Module Deployment | EU Green Deal extended producer responsibility mandates require garment lifecycle tracking and resale marketplace integration. |
| Live-Stream Commerce Integration | Real-time inventory synchronization with content feeds compresses purchase cycles in Shanghai and Beijing urban clusters. |
| AR Virtual Try-On Scale-Up | Computer vision deployment reduces fit-related returns in footwear and accessories categories across South Korean retailers. |
| Size Recommendation Algorithm Investment | Machine learning models trained on regional body-scan datasets cut logistics costs by predicting fit across diverse sizing standards. |
| Connected Retail Partnership Network | Offline stock integration into online availability captures hybrid commerce demand and defends against dedicated resale platforms. |
Research Methodology
Bottom-up merchant adoption modeling reconciled against top-down platform infrastructure tracking forms the analytical core of this study. Primary interviews with platform engineering directors, merchant success managers, logistics technology vendors, and apparel brand CTOs were validated against secondary sources including SEC SaaS company filings, EU regulatory directive texts, and customs trade data for textile imports. Triangulation between supply-side capacity buildouts and demand-side subscription metrics ensures segmentation integrity.
Historical trendline analysis of platform merchant counts and average revenue per user established baseline growth trajectories across the projection horizon. The forecast framework models deployment model, merchant size tier, geographic adoption cluster, and integration complexity as primary segmentation dimensions. CAGRs were derived from fitted growth curves incorporating live-stream commerce penetration rates and circular economy module adoption as clothing-specific inputs.
Inputs from platform operator disclosures and regulatory filing databases were available through the study window; gaps in private merchant churn data and unreported API transaction volumes introduce uncertainty bands around subscription revenue forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Indonesia E-Services Market