
 GCC Fitness Ring Market | 2026-2036
GCC Fitness Ring Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Fitness Ring Market Insights
Market Context with Strategic Players
Saudi Arabia's industrial capacity build-out in wearable electronics assembly is rewriting supply dynamics for Gulf-bound fitness rings. Oura Health Ltd leverages its Nordic design heritage to anchor premium positioning across Dubai and Abu Dhabi retail channels. Xiaomi Corporation competes aggressively on manufacturing scale, extending cost-optimized smart ring variants through Saudi e-commerce platforms. Fitbit, operating under Google LLC, controls health data integration capabilities that differentiate its ecosystem lock-in across UAE corporate wellness contracts.
Technical Definition and Structural Segments
A fitness ring is a finger-worn wearable device integrating photoplethysmography sensors, accelerometers, and temperature monitors to track heart rate variability, sleep architecture, and activity metrics with medical-grade precision. Its primary commercial purpose centers on continuous biometric monitoring without the bulk of wrist-worn alternatives, serving users requiring unobtrusive health data collection during sleep and exercise. Smart rings dominate product type revenue owing to their semiconductor miniaturization and Bluetooth Low Energy connectivity, while biometric sensors represent the fastest-growing technology segment as manufacturers integrate multi-wavelength PPG and galvanic skin response modules. Distribution through online retail channels captures the largest volume share, though specialty stores in Dubai Mall and Riyadh Park retain margin concentration through personalized fitting services and after-sales support.
Regulatory Frame and Forward-Looking Close
Saudi Arabia's SFDA medical device regulations, UAE's MOHAP digital health product standards, and Qatar's Ministry of Public Health consumer electronics safety frameworks collectively shape market access requirements and clinical claim substantiation across the GCC. These regulators mandate electromagnetic compatibility testing and biocompatibility certification for skin-contacting sensors, creating compliance barriers that favor established manufacturers with dedicated Gulf regulatory affairs teams. Stakeholders must monitor evolving medical device classification thresholds that could reclassify certain fitness rings from consumer wellness to regulated health equipment, fundamentally altering registration timelines and channel strategies.
Market Dynamics
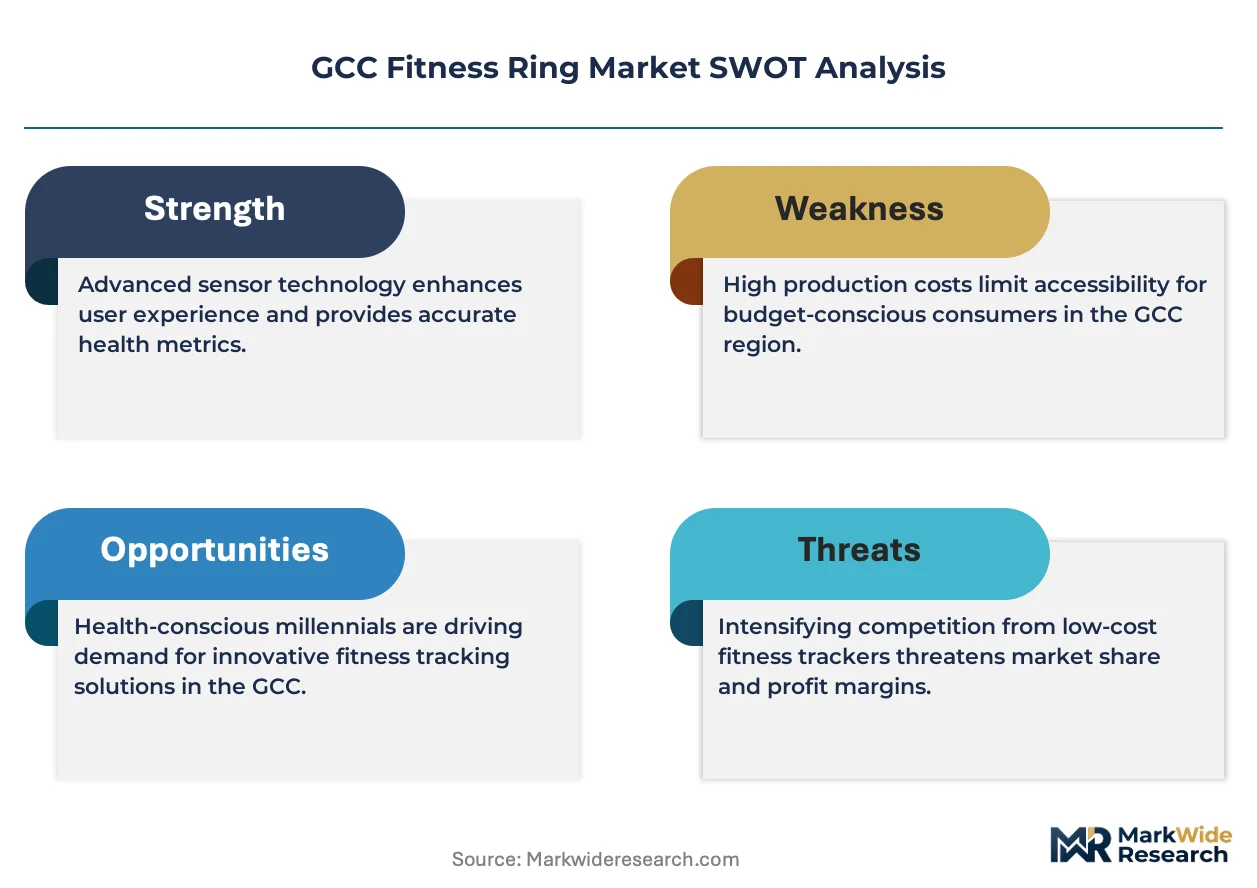
The GCC Fitness Ring Market is concentrating around medical-grade certification requirements as Saudi Arabia's SFDA tightens classification thresholds for biometric wearables, forcing manufacturers to choose between consumer wellness positioning and regulated health device pathways.
Growth Catalysts
- Corporate wellness mandates:Large employers across Dubai International Financial Centre and Riyadh's King Abdullah Financial District are subsidizing fitness ring purchases for knowledge workers, embedding biometric monitoring into occupational health programs.
- SFDA medical device pathways:Saudi Arabia's streamlined registration framework for Class I wellness devices accelerates product entry timelines compared to neighboring Gulf states, drawing regional distribution headquarters to Riyadh.
- Photoplethysmography miniaturization:Advances in multi-wavelength PPG sensor integration enable continuous SpO2 and heart rate variability tracking in ring form factors previously limited to wrist-worn devices.
Market Restraints
- Semiconductor supply concentration:Bluetooth Low Energy chipsets and MEMS accelerometers for Gulf-bound rings depend heavily on East Asian foundry capacity, exposing manufacturers to lead time volatility and input cost spikes.
- Biocompatibility certification costs:ISO 10993 skin-contact testing and electromagnetic compatibility validation for MOHAP compliance add fixed costs that disproportionately burden smaller entrants without dedicated regulatory affairs teams.
- Smartwatch substitution pressure:Multi-function wrist-worn devices from established consumer electronics ecosystems capture overlapping health-monitoring use cases, compressing addressable market expansion for single-purpose rings.
Strategic Opportunities
- Qatar's underpenetrated corporate sector:Doha's emerging fintech and energy headquarters clusters present first-mover potential for wellness program vendors before competitive saturation reaches UAE and Saudi levels.
- Telehealth integration partnerships:Fitness ring data streams feeding into UAE-licensed telemedicine platforms create recurring revenue models beyond hardware sales, with MOHAP digital health incentives reducing provider integration friction.
- Galvanic skin response convergence:Combining GSR stress indicators with existing PPG and temperature sensors opens employer-funded mental wellness applications targeting high-pressure finance and aviation sectors.
Industry Challenges
- Biomedical firmware engineering scarcity:The Gulf region lacks sufficient embedded systems specialists capable of optimizing signal processing algorithms for medical-grade accuracy in constrained ring architectures.
- Multi-jurisdiction certification timelines:Separate SFDA, MOHAP, and Qatar Ministry of Public Health approval processes force sequential rather than parallel market entry, stretching working capital requirements for inventory staging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Fitness Ring Market |
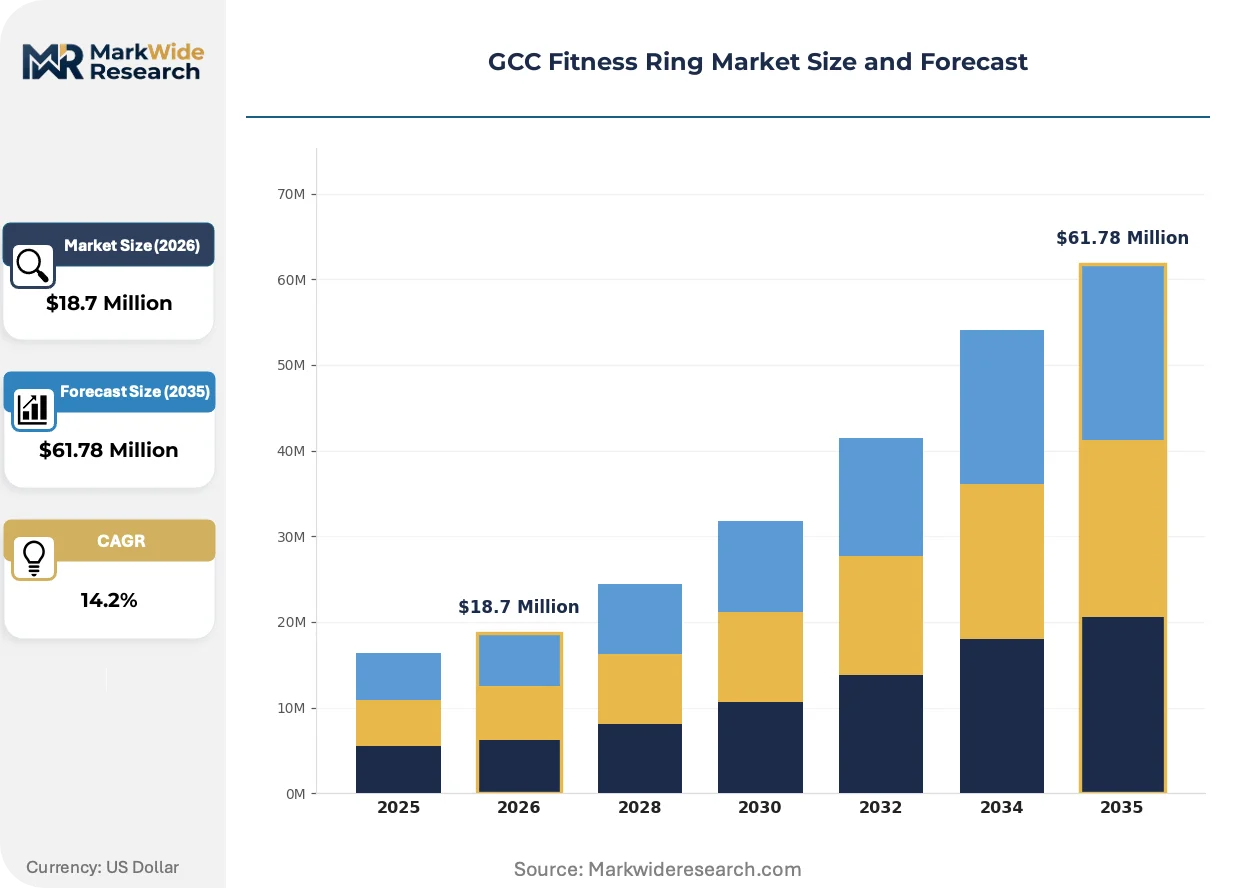
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Rings, Traditional Fitness Bands, Hybrid Wearables, Health Monitoring Devices End User: Athletes, Fitness Enthusiasts, Health Conscious Individuals, Casual Users Technology: Bluetooth, NFC, GPS, Biometric Sensors Distribution Channel: Online Retail, Specialty Stores, Fitness Centers, Direct Sales |
| Companies Covered | Oura Health Ltd, Fitbit (Google LLC), Xiaomi Corporation, Motiv Inc, GO Devices, Circular Ring, McLEAR Ltd, Bellabeat, SLEEPON, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Fitness Ring Market Trends and Innovations
Biometric sensor fusion is compressing the gap between consumer wellness accessories and clinical monitoring equipment across Gulf metropolitan markets, with implications for regulatory classification and channel strategy.
Multi-wavelength photoplethysmography is migrating from research laboratory configurations to mass-market ring architectures. Cardiology departments at Dubai's private hospital networks are piloting these devices for post-discharge patient monitoring. This migration is compressing the traditional boundary between consumer wearables and prescribed remote patient monitoring equipment, forcing manufacturers to architect products for dual regulatory pathways from initial design stages.
MOHAP's digital health product incentive framework is accelerating clinical claim substantiation requirements for wearable devices marketed in the UAE. Manufacturers must now generate Gulf-specific validation data rather than relying on European CE mark documentation. Specialty retailers in Abu Dhabi's Yas Mall and Dubai Mall are responding by hiring trained staff capable of explaining regulatory-grade accuracy distinctions to health-conscious consumers.
Employer procurement of fitness rings is fragmenting from centralized HR wellness budgets to departmental line-item purchasing. Individual division heads in Saudi Aramco and Emirates Group subsidiaries are acquiring biometric monitoring tools for specific high-stress teams without enterprise-wide standardization. This fragmentation is most visible in Dubai's aviation and logistics corridors, where operational managers prioritize immediate crew wellness metrics over IT department integration preferences.
GCC Fitness Ring Market Segmentation
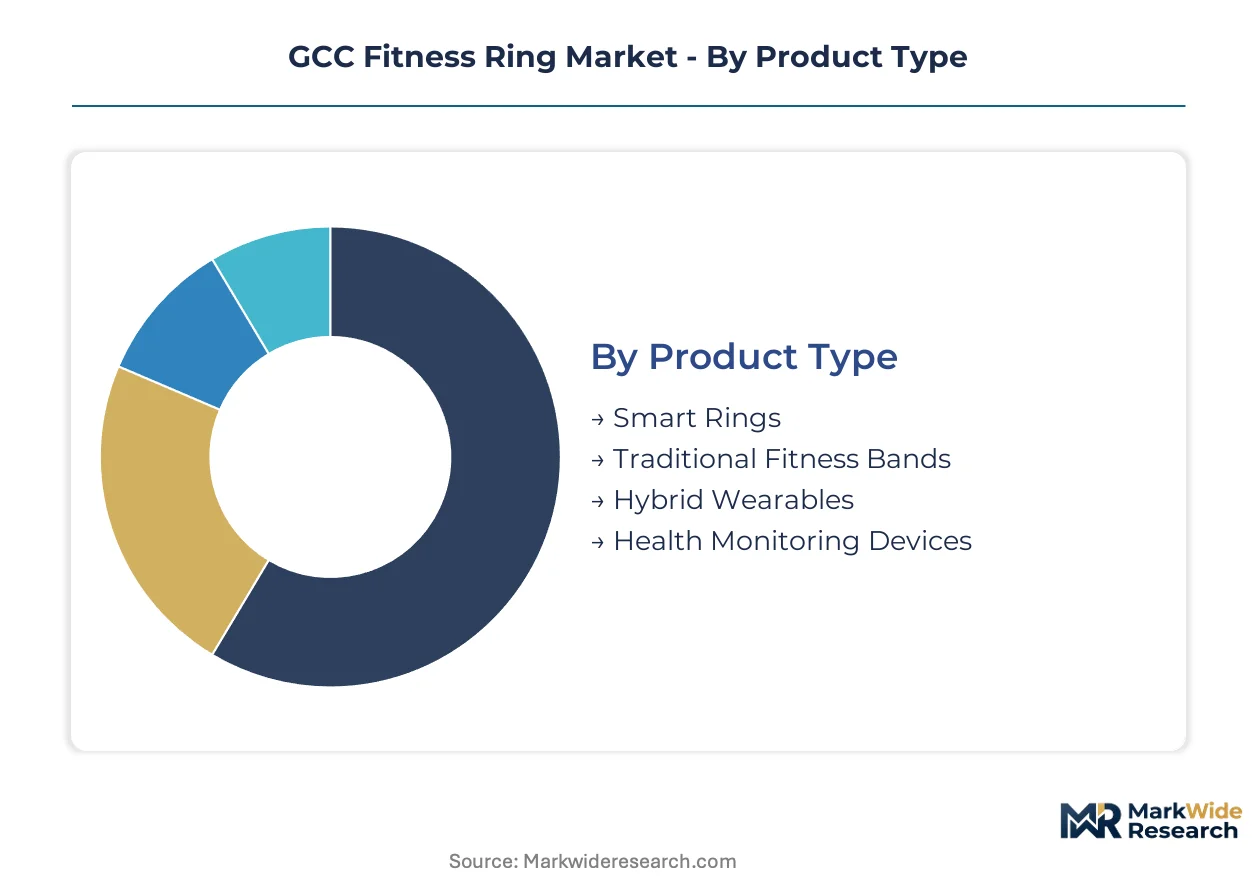
Fitness ring manufacturers in the GCC must architect products for divergent user expectations across product sophistication, health literacy, and purchasing behavior. Segmentation discipline determines whether vendors capture premium positioning in Dubai's luxury retail corridors or volume scale through Saudi e-commerce platforms.
Product Type:
Mature semiconductor miniaturization has compressed development cycles across all form factors, though commercial outcomes diverge sharply by integration depth.
- Smart Rings:Photoplethysmography and accelerometer arrays embedded in titanium or ceramic housings enable continuous heart rate and sleep staging without wrist-worn bulk. Demand concentrates in Dubai International Financial Centre and Riyadh's King Abdullah Financial District, where corporate wellness subsidies prioritize unobtrusive biometric monitoring for knowledge workers.
- Traditional Fitness Bands:Wrist-worn accelerometer-based step counters and basic sleep timers dominate unit volume through Saudi hypermarket chains. Price compression from Xiaomi manufacturing scale has repositioned these devices as entry-level gateway products rather than ring substitutes.
- Hybrid Wearables:Modular systems combining ring sensors with detachable wrist straps address users transitioning between formal and athletic contexts. Abu Dhabi's government sector procurement favors these configurations for dual-use scenarios.
- Health Monitoring Devices:Prescription-grade remote patient monitoring rings with FDA or SFDA clearance target post-discharge cardiac rehabilitation. Cleveland Clinic Abu Dhabi pilots these for Gulf-specific hypertension management protocols.
Smart Rings handle the majority of throughput; Health Monitoring Devices are gaining share fastest as SFDA relaxes Class II wellness device pathways.
End User:
Cost tier stratification separates subsidized corporate procurement from discretionary consumer spending across Gulf metropolitan markets.
- Athletes:Professional and semi-professional competitors in Qatar's Aspire Academy and UAE football academies require HRV-derived recovery metrics and training load quantification. Device durability under sand and humidity exposure drives titanium housing preferences over resin alternatives.
- Fitness Enthusiasts:Gym members in Dubai's Fitness First and Riyadh's Body Masters networks track workout intensity and caloric expenditure through integrated club management platforms. Subscription revenue models attach to hardware sales through these partnerships.
- Health Conscious Individuals:Preventive health adopters prioritize sleep architecture analysis and stress indicator trending over athletic performance metrics.
- Casual Users:Gift purchasers and technology trialists respond to seasonal promotional cycles in Dubai Mall electronics retailers.
Fitness Enthusiasts anchor volume absorption; Athletes show the steepest expansion trajectory as national sports investment escalates across Qatar and Saudi Arabia.
Technology:
Application-specific connectivity requirements force hard choices between battery longevity and functional breadth in constrained ring architectures.
- Bluetooth:Low Energy 5.3 protocols enable smartphone-tethered data synchronization with minimal power draw. MOHAP electromagnetic compatibility certification mandates specific Gulf-frequency band testing that extends validation timelines.
- NFC:Contactless payment and access control integration targets Dubai's transit-integrated lifestyle and Riyadh's cashless retail transformation. Saudi Payment Network compatibility requires additional certification layers.
- GPS:Standalone location tracking for outdoor activity mapping drains battery capacity unsuitable for 24-hour form factors.
- Biometric Sensors:Multi-wavelength PPG, galvanic skin response, and temperature arrays represent the frontier of medical-grade accuracy in consumer wearables.
Bluetooth manages the bulk of installed base connectivity; Biometric Sensors are climbing the fastest on vendor R&D allocation.
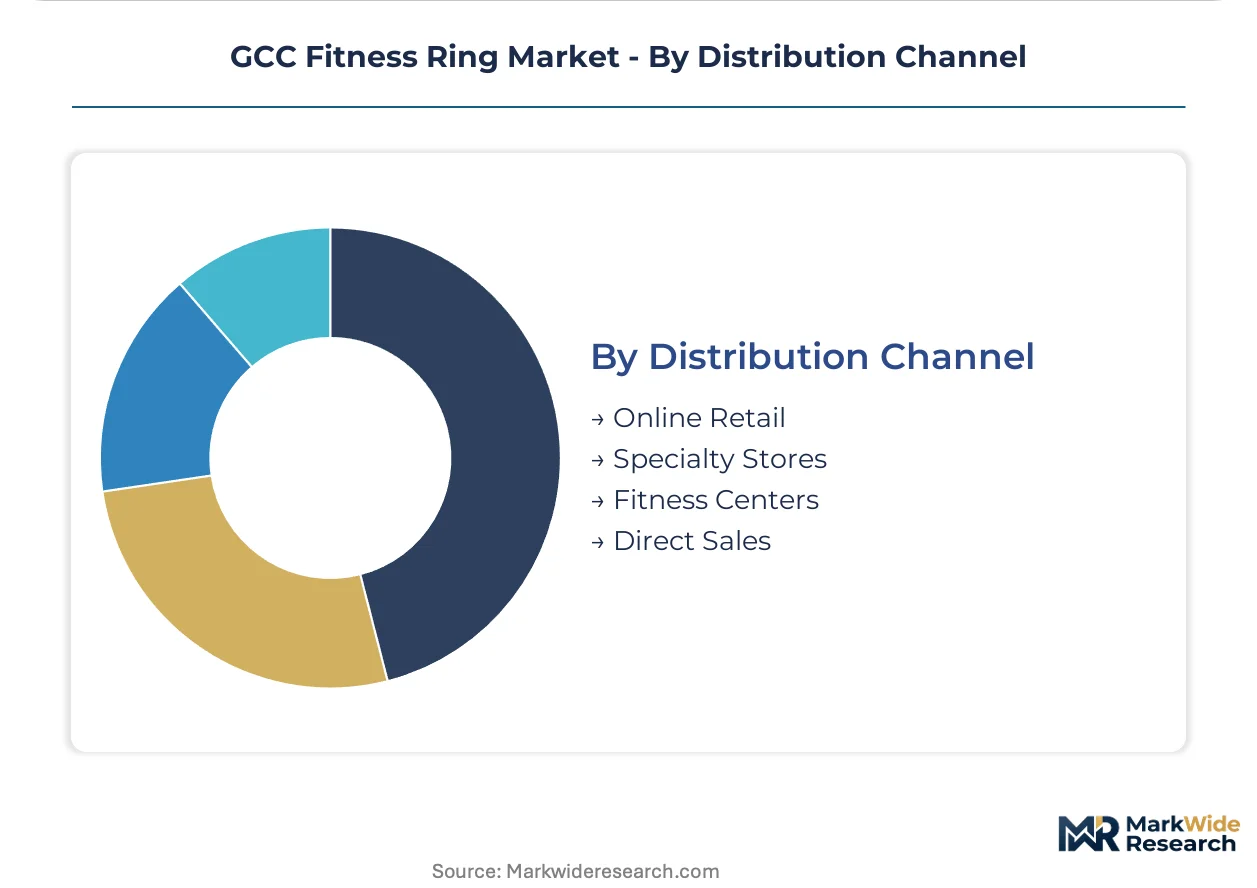
Distribution Channel:
Volume concentration in digital channels contrasts with margin capture through physical retail's fitting and education services.
- Online Retail:Amazon.ae, Noon.com, and Saudi e-commerce platforms capture scale through price transparency and subscription bundling. Return rates exceed physical retail due to sizing uncertainty, compressing net margins despite lower customer acquisition costs.
- Specialty Stores:Dubai Mall and Riyadh Park electronics retailers employ trained staff for finger measurement and feature explanation. Personalized fitting justifies 15-20% price premiums over identical online SKUs.
- Fitness Centers:Corporate wellness program distribution through gym partnerships embeds devices in employer-funded health initiatives.
- Direct Sales:Manufacturer-owned flagship experiences in Abu Dhabi's Yas Mall control brand positioning and capture first-party customer data.
Online Retail processes the highest transaction velocity; Specialty Stores retain the strongest margin position through service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA regulatory leadership in Saudi Arabia concentrates Gulf fitness ring market gravity toward Riyadh and Jeddah, while MOHAP digital health incentives in the UAE create parallel demand nodes in Dubai and Abu Dhabi.
Saudi Arabia
Corporate wellness mandates at Saudi Aramco and King Abdullah Financial District employers drive bulk procurement of biometric monitoring devices. SFDA Class I wellness device registration pathways accelerate product entry timelines compared to neighboring states. Riyadh's King Abdulaziz City for Science and Technology hosts wearable electronics assembly partnerships that localize Gulf-bound production.
United Arab Emirates
MOHAP digital health incentives reduce friction for telemedicine platform integration with fitness ring data streams. Dubai International Financial Centre employers subsidize unobtrusive health monitoring for knowledge workers. Abu Dhabi's Cleveland Clinic pilots prescription-grade rings for post-discharge cardiac rehabilitation protocols.
Qatar
Aspire Academy athletes and emerging fintech clusters in Doha's Lusail district generate concentrated demand for recovery metrics and stress monitoring. Qatar's Ministry of Public Health consumer electronics safety frameworks mandate electromagnetic compatibility testing for skin-contacting sensors. Education City and Energy City headquarters present first-mover opportunities before competitive saturation reaches UAE levels.
Kuwait
Health-conscious professionals in Kuwait City's financial district adopt sleep architecture tracking as occupational wellness benefits expand. The country's national medical device regulator requires biocompatibility certification for wearable sensors, creating compliance barriers favoring established manufacturers. Salmiya retail corridors concentrate specialty electronics distribution with personalized fitting services.
Bahrain
Bahrain FinTech Bay and Gulf Air operational headquarters drive employer-funded biometric monitoring for high-pressure aviation and finance teams. The national health regulator aligns device classification with SFDA frameworks, streamlining multi-jurisdiction market entry for Saudi-registered products. Manama's City Centre mall anchors regional distribution for hybrid wearable configurations.
GCC Fitness Ring Market Competitive Landscape
Capability concentration sits with Nordic and North American design heritage players; scale advantage sits with East Asian manufacturing conglomerates. The vendor base organizes around three strategic tiers: premium medical-grade specialists, ecosystem-integrated consumer electronics platforms, and cost-optimized mass-market fabricators. Dominant competitive moves include telehealth partnership formations and Gulf-specific regulatory affairs team buildouts.
Within the premium design tier, Oura Health Ltd exemplifies Nordic heritage positioning across Dubai and Abu Dhabi retail channels. Fitbit, operating under Google LLC, occupies the ecosystem lock-in position through health data integration capabilities. Xiaomi Corporation anchors the scale-driven end with manufacturing-optimized variants distributed through Saudi e-commerce platforms.
| Leading Market Players |
|---|
| Oura Health Ltd |
| Fitbit (Google LLC) |
| Xiaomi Corporation |
| Motiv Inc |
| GO Devices |
| Circular Ring |
| McLEAR Ltd |
| Bellabeat |
| SLEEPON |
| Others |
Pricing and Supply Chain Analysis
East Asian semiconductor foundry concentration determines both tiered pricing spreads and supply chain resilience across Gulf-bound fitness ring manufacturing. SFDA medical device classification thresholds and MOHAP electromagnetic compatibility mandates compound input cost volatility with compliance expenditure, compressing margins for manufacturers lacking dedicated Gulf regulatory affairs infrastructure.
Pricing Analysis
Dubai Mall specialty retailers command 15-20% premiums over identical online SKUs due to personalized fitting services and after-sales support. Three-tier pricing structure across premium, standard, and economy levels separates Oura Health's Nordic-designed titanium housings from Xiaomi's cost-optimized resin variants and entry-level fitness bands. Price differentiation hinges on certification grade—SFDA Class I wellness pathways versus unregulated consumer accessories—and brand heritage positioning. Cost compression in the economy tier intensifies because Saudi e-commerce platforms prioritize volume scale over margin retention. Casual gift purchasers in Dubai Mall electronics retailers exhibit highest price sensitivity; corporate wellness procurement managers at Saudi Aramco and Emirates Group subsidiaries show lowest sensitivity due to subsidized occupational health budgets.
Supply Chain Analysis
Extended payment terms from East Asian foundry partners strain working capital for Gulf-bound ring manufacturers navigating multi-jurisdiction certification timelines. Bluetooth Low Energy chipsets and MEMS accelerometers draw from Taiwan, South Korea, and China; titanium housings and ceramic substrates source from Japan and Germany. Raw material dependencies center on multi-wavelength PPG sensors, galvanic skin response modules, and biocompatible coatings requiring ISO 10993 validation. Single-source vulnerability concentrates in BLE semiconductor fabrication, where foundry capacity allocation favors smartphone and automotive contracts over wearable electronics. Distribution runs through Amazon.ae, Noon.com, and Saudi e-commerce platforms for volume, with Dubai Mall and Riyadh Park specialty stores capturing margin through service differentiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoplethysmography miniaturization and SFDA Class II wellness device pathway relaxation are compressing the boundary between consumer accessories and clinical monitoring equipment, creating a high-growth disruption window for vendors architecting dual regulatory products from initial design stages.
For Market Incumbents: Pre-empt smartwatch substitution pressure by deepening telehealth platform integration partnerships with UAE-licensed providers before Google LLC's Fitbit ecosystem lock-in consolidates corporate wellness contracts. Fortify Gulf regulatory affairs teams to accelerate parallel SFDA, MOHAP, and Qatar Ministry of Public Health submissions rather than sequential approval processes that stretch inventory staging requirements. Prioritize backward integration into titanium housing fabrication to offset East Asian foundry pricing volatility and capture margin compression resilience.
For New Entrants and Emerging Players: Qatar's underpenetrated corporate sector presents first-mover white-space before competitive saturation reaches UAE and Saudi levels, particularly among Aspire Academy athletes and Lusail fintech clusters seeking recovery metrics and stress monitoring. Target mental wellness applications combining galvanic skin response with existing PPG sensors for high-pressure aviation and finance sectors in Bahrain FinTech Bay and Gulf Air operational headquarters. Pursue direct-to-employer sales bypassing IT department procurement gatekeepers through operational manager relationships in Dubai's logistics corridors.
For Investors and Strategic Acquirers: SFDA's evolving medical device classification thresholds reshape the acquisition landscape by revaluing consumer wellness positioning against regulated health device pathways. Long-term viability centers on vendors with Gulf-specific validation data generation capabilities and embedded systems firmware engineering teams capable of optimizing signal processing algorithms for medical-grade accuracy. Target acquisition archetypes include Nordic design heritage players with established Dubai retail presence and telehealth integration infrastructure. The signal to watch is MOHAP digital health incentive expansion beyond pilot programs into sustained reimbursement frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Creates recurring revenue models beyond hardware sales through UAE-licensed provider partnerships. |
| SFDA Class II Certification Investment | Accelerates prescription-grade remote patient monitoring access for post-discharge cardiac rehabilitation protocols. |
| Gulf Regulatory Affairs Team Buildout | Enables parallel rather than sequential multi-jurisdiction market entry, compressing working capital requirements. |
| Multi-Wavelength PPG Sensor R&D | Closes accuracy gaps with wrist-worn devices while maintaining ring form factor unobtrusiveness advantages. |
| Specialty Retail Partnership Expansion | Captures margin premiums through personalized fitting services in Dubai Mall and Riyadh Park corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with biomedical firmware engineers, Gulf regulatory affairs specialists, corporate wellness procurement managers at Saudi Aramco and Emirates Group subsidiaries, and specialty retail operations heads in Dubai Mall and Riyadh Park. Secondary validation drew from SFDA medical device registration databases, MOHAP digital health product incentive filings, Cleveland Clinic Abu Dhabi pilot study disclosures, and hyperscaler wearable electronics capex announcements. Bottom-up segment sizing triangulated against top-down macroeconomic absorption models.
Calibration approaches anchored volume and value outputs to observed procurement patterns across employer-funded wellness programs and discretionary retail channels throughout the projection horizon. Segmentation dimensions modeled include product sophistication tier, end-user health literacy level, certification pathway classification, and metropolitan cluster adoption intensity. CAGRs derived from regression analysis against corporate wellness mandate expansion rates and semiconductor miniaturization cost curves. Industry-specific forecast inputs incorporated SFDA registration timeline data and MOHAP electromagnetic compatibility certification throughput.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ecosystem-locked consumer electronics platforms or vertically integrated East Asian manufacturing conglomerates would shift outcomes. Macroeconomic deviation in Gulf hydrocarbon revenues, regulatory reclassification of fitness rings to regulated health equipment, or breakthrough battery technology enabling standalone GPS form factors would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Yoga and Exercise Mats Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Home Fitness Market
Fitness Equipment
Ergometer Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
BMI Machine Market