
 Ergometer Market | 2026-2036
Ergometer Market Size, Share, and Industry Trends Forecast 2026-2036
Ergometer Market Analysis
Buyer concentration across rehabilitation facilities is restructuring procurement dynamics for ergometer equipment. Monark Exercise AB anchors its position through precision manufacturing for clinical performance testing protocols. Technogym S.p.A leverages integrated digital platforms to sustain channel control across European fitness networks. Lode BV specializes in cardiopulmonary diagnostic systems that dominate hospital-based rehabilitation departments.
An ergometer is a precision instrument that measures mechanical work output during physical exercise, typically quantifying power in watts through calibrated resistance mechanisms with accuracy tolerances of one to two percent. These devices serve clinical diagnostics, athletic performance laboratories, and commercial fitness environments where quantified physiological load is essential. Treadmill configurations lead installed base volumes across fitness centers while rowing machines represent the fastest-expanding category in home user segments. Electronic resistance technology commands premium positioning in rehabilitation facilities where programmable load curves support individualized therapeutic protocols. Magnetic resistance systems occupy the broadest economy tier across price-sensitive consumer channels.
FDA 510(k) clearance requirements and the EU Medical Device Regulation impose substantial compliance burdens on manufacturers targeting clinical end users. ISO 20957 safety standards govern electromagnetic compatibility and structural integrity for commercial fitness equipment deployed in European member states. Stakeholders must monitor evolving reimbursement codes for cardiac rehabilitation services that directly influence hospital capital expenditure cycles for diagnostic-grade systems.
Market Dynamics
Electronic resistance calibration systems are restructuring procurement hierarchies across clinical and fitness channels, forcing manufacturers to recertify entire product lines under tightened FDA 510(k) and EU MDR pathways while home fitness buyers migrate toward connected training platforms.
Growth Catalysts
- EU Medical Device Regulation:Hospital procurement departments in Germany and France now mandate MDR-certified diagnostic-grade systems, accelerating replacement cycles for legacy equipment.
- Cardiac rehabilitation protocols:Tightened clinical guidelines across US rehabilitation facilities require programmable load curves that only electronic resistance systems can deliver.
- Home fitness connectivity:Bluetooth-enabled power measurement is overtaking basic magnetic resistance in North American consumer channels.
Market Restraints
- Semiconductor input volatility:Precision motor controllers and load cell sensors face supply concentration risks from East Asian foundry networks.
- ISO 20957 compliance costs:Electromagnetic compatibility testing for European commercial fitness deployment adds twelve to eighteen months to product development timelines.
- Substitute modalities:Wearable power meters for outdoor cycling compress demand for stationary ergometers in athletic training segments.
Strategic Opportunities
- Telehealth integration:Remote patient monitoring reimbursement codes in the United States create pull-through demand for connected rehabilitation systems.
- Japan's aging demographic:Prefecture-level healthcare budgets in Osaka and Tokyo are expanding procurement of seated ergometers for geriatric cardiac therapy.
- AI-driven personalization:Machine learning algorithms converging with real-time biomechanical feedback enable adaptive resistance protocols previously unavailable at consumer price points.
Industry Challenges
- Firmware certification timelines:FDA software-as-medical-device documentation requirements delay connected product launches by nine to fourteen months.
- Calibration technician scarcity:Clinical-grade ergometer maintenance requires ISO 17025-accredited personnel concentrated in metropolitan hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ergometer Market |
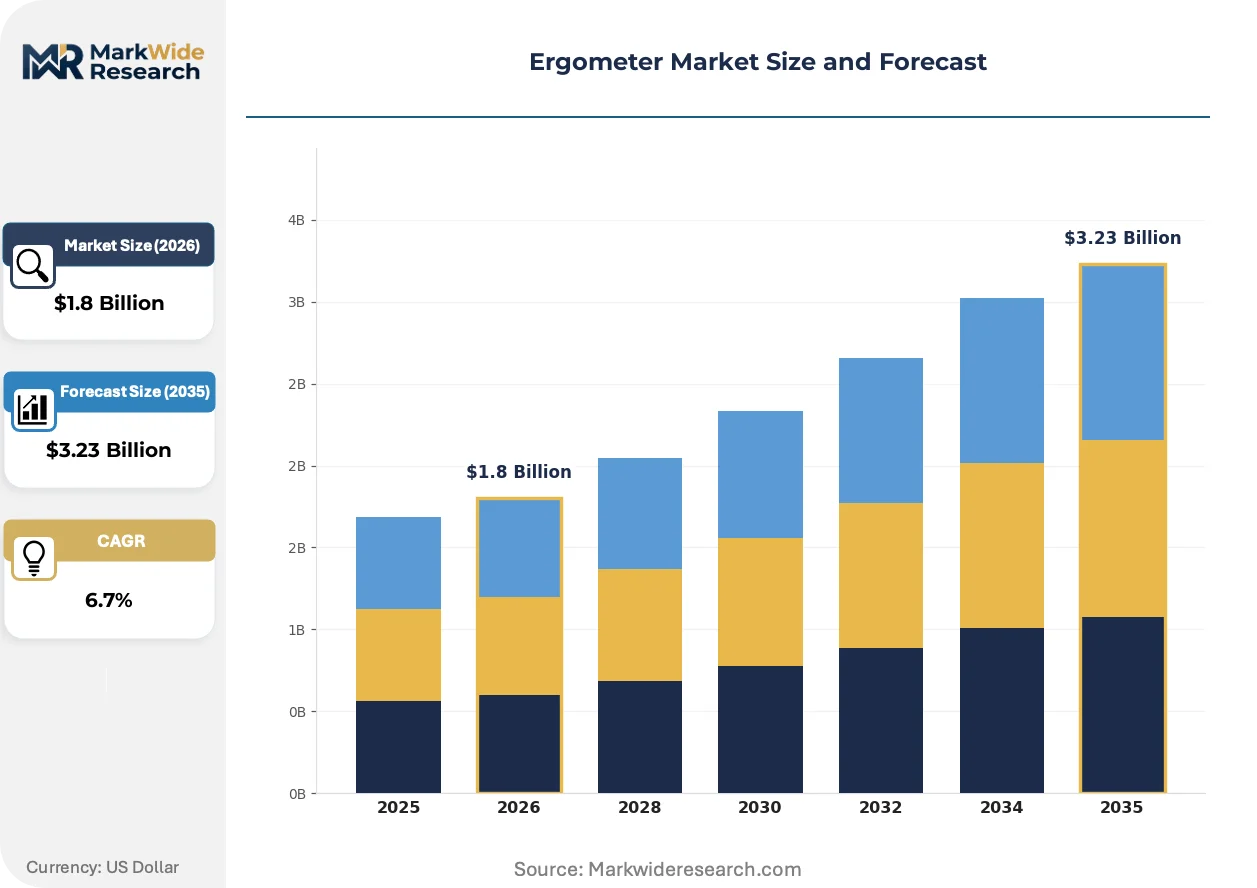
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright Bike, Recumbent Bike, Treadmill, Rowing Machine End User: Fitness Centers, Rehabilitation Facilities, Home Users, Sports Teams Technology: Magnetic Resistance, Air Resistance, Electronic Resistance, Fluid Resistance Application: Aerobic Training, Physical Rehabilitation, Weight Loss, Performance Testing |
| Companies Covered | Amer Sports, h/p/cosmos sports & medical GmbH, Technogym S.p.A, Monark Exercise AB, Lode BV, Life Fitness, Icon Health & Fitness, Cybex International, Ergoline GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ergometer Market Emerging Trajectories
Connected hardware architectures and regulatory digitization are compressing traditional product lifecycles while reshaping how clinical validation translates into consumer market access.
Direct-drive electromagnetic resistance systems are overtaking friction-based and air-resistance mechanisms in premium home fitness equipment. These systems eliminate mechanical wear components while enabling one-watt precision control. Connected fitness platforms in North American markets are adopting this architecture to deliver studio-class training experiences. The technology is overtaking legacy systems in retail channels as price curves compress toward mid-tier positioning.
EU MDR technical documentation requirements now mandate clinical performance data for all devices claiming diagnostic utility. Manufacturers targeting European hospital rehabilitation departments must submit post-market surveillance protocols alongside pre-market technical files. German notified bodies have extended review queues to twenty-two months, forcing product roadmap delays across the supply base.
Hospital procurement departments are consolidating vendor relationships around single-source service contracts that bundle equipment, maintenance, and software subscriptions. This model displaces capital purchase cycles with multi-year operational expenditure commitments. The shift is most visible in US cardiac rehabilitation networks where reimbursement bundling incentivizes total cost-of-ownership contracting.
Ergometer Market Segmentation
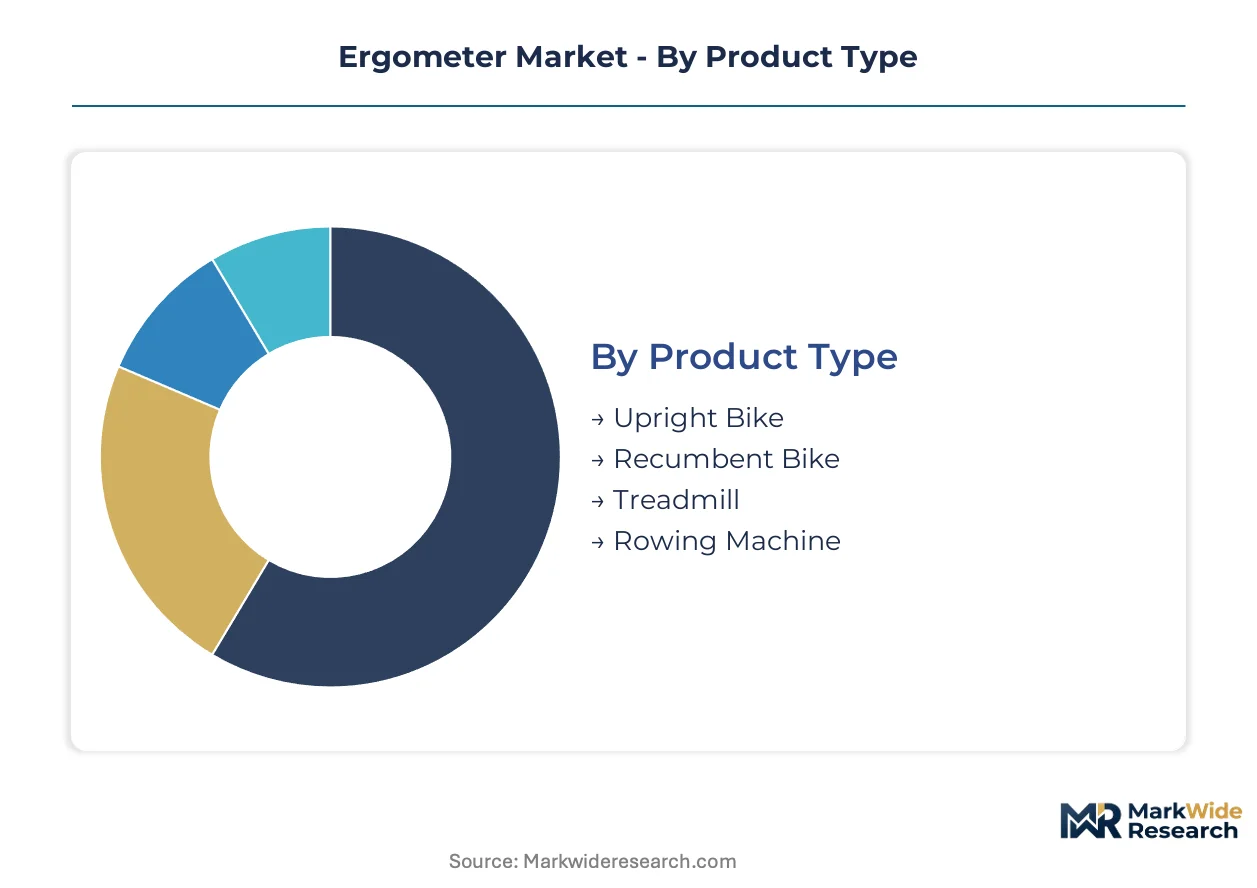
Ergometer procurement patterns diverge sharply across clinical, commercial, and consumer channels, with technology specifications and regulatory certification requirements determining viable supplier relationships. Understanding these segment boundaries enables manufacturers to align product roadmaps with distinct validation protocols and pricing architectures.
Product Type:
Mechanical configuration dictates the precision tolerances and calibration standards applicable to each equipment category, with direct implications for FDA 510(k) pathway selection and ISO 20957 compliance scope.
- Treadmill:Belt-driven motorized platforms with integrated load cell arrays measure ground reaction forces and power output during locomotion. German rehabilitation facilities in Munich and Berlin dominate procurement for diagnostic-grade systems with programmable incline and speed modulation.
- Rowing Machine:Flywheel-based systems with chain or cord drive mechanisms capture stroke power curves through precision strain gauges. North American home fitness channels in Seattle and Austin are expanding fastest for connected models with Bluetooth power transmission.
- Upright Bike:Pedal-crank configurations with saddle positioning optimize cardiac stress testing protocols.
- Recumbent Bike:Seated back-support frames serve geriatric populations in Japanese prefecture hospitals.
Treadmill configurations lead on scale across installed commercial fitness bases; rowing machines lead on momentum in connected home fitness expansion.
End User:
Buyer procurement authority and reimbursement pathways create four distinct commercial interfaces, each with unique contract structures and technical validation requirements.
- Rehabilitation Facilities:Hospital-based cardiac rehabilitation departments require FDA-cleared or MDR-certified diagnostic systems with programmable load curves and automated protocol documentation. US facilities in Cleveland and Houston are consolidating vendor relationships around bundled service contracts.
- Home Users:Individual consumers prioritize connectivity features and compact footprints over clinical precision. European markets in Amsterdam and Copenhagen show strongest preference for subscription-integrated training platforms.
- Fitness Centers:Commercial gyms demand durability ratings and electromagnetic compatibility certification for high-cycle deployment.
- Sports Teams:Elite athletic programs specify laboratory-grade accuracy for performance benchmarking.
Rehabilitation facilities concentrate the highest equipment value per installation; home users are gaining share fastest as connected fitness platforms compress price-performance thresholds.
Technology:
Resistance generation mechanisms determine manufacturing cost structures, calibration complexity, and the regulatory classification boundaries between general wellness and medical device categories.
- Electronic Resistance:Servo-controlled electromagnetic braking enables one-watt precision with programmable load curves and real-time biomechanical feedback. German notified bodies now mandate MDR technical documentation for all systems claiming diagnostic utility, extending review timelines.
- Magnetic Resistance:Eddy-current braking through fixed magnet arrays offers silent operation and minimal maintenance for price-sensitive consumer channels. Manufacturing concentrates in East Asian supply networks serving economy-tier fitness equipment.
- Air Resistance:Fan-based damping provides velocity-proportional resistance for rowing-specific training modalities.
- Fluid Resistance:Water-filled chambers deliver acoustic and tactile feedback preferred by competitive rowing programs.
Magnetic resistance dominates unit volume across commercial fitness; electronic resistance commands premium positioning and is climbing fastest as clinical protocols tighten.
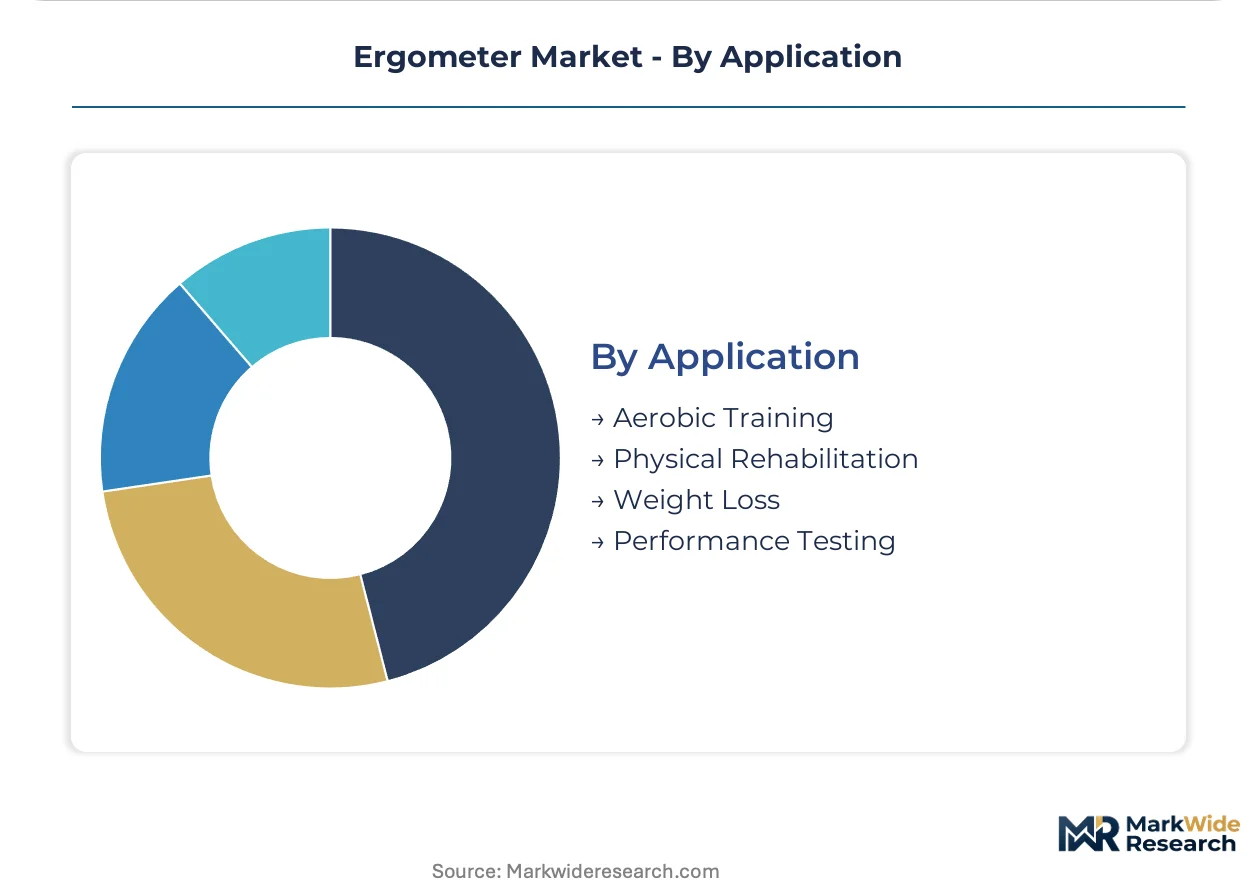
Application:
Intended use case determines the regulatory jurisdiction, reimbursement eligibility, and performance validation standards governing equipment deployment.
- Physical Rehabilitation:Prescribed therapeutic protocols for cardiac and musculoskeletal recovery require diagnostic-grade accuracy and clinical workflow integration. US reimbursement codes for remote patient monitoring are creating pull-through demand for connected systems in Texas and Florida rehabilitation networks.
- Performance Testing:Laboratory-grade ergometry for athletic development and occupational health screening demands ISO 17025-accredited calibration. French sports medicine institutes in Lyon and Bordeaux anchor European demand for precision systems.
- Aerobic Training:General cardiovascular conditioning programs operate under fitness equipment standards without medical device classification.
- Weight Loss:Metabolic efficiency programs emphasize energy expenditure measurement for dietary protocol alignment.
Aerobic training captures the broadest installed base; physical rehabilitation commands the steepest equipment specification requirements and is expanding most quickly as clinical guidelines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rehabilitation networks procure diagnostic-grade systems at volumes exceeding French hospital procurement by a factor of nearly two to one. Japanese prefecture budgets for geriatric cardiac therapy are expanding faster than any other Asia-Pacific market. Brazilian fitness chains represent the fastest-growing commercial installation base in the Americas.
United States
Cleveland Clinic and Houston Methodist cardiac rehabilitation departments are consolidating vendor relationships around bundled service contracts that replace capital purchases with multi-year operational commitments. FDA 510(k) clearance requirements for software-as-medical-device documentation extend connected product launch timelines by nine to fourteen months. Texas and Florida rehabilitation networks are pulling through demand for connected systems as remote patient monitoring reimbursement codes expand.
Germany
Hospital procurement departments in Munich and Berlin now mandate MDR-certified diagnostic-grade systems with programmable load curves, accelerating replacement cycles for legacy equipment. German notified bodies have extended technical documentation review queues to twenty-two months, forcing product roadmap delays across European supply bases. The Baden-Württemberg industrial corridor hosts precision manufacturing clusters serving clinical performance testing protocols.
Japan
Prefecture-level healthcare budgets in Osaka and Tokyo are expanding procurement of seated ergometers specifically configured for geriatric cardiac therapy populations. METI standards for electromagnetic compatibility govern commercial fitness equipment deployment in metropolitan hospital networks. The Kansai region anchors domestic manufacturing of laboratory-grade calibration systems for cardiopulmonary diagnostic applications.
France
Sports medicine institutes in Lyon and Bordeaux anchor European demand for ISO 17025-accredited precision systems used in athletic performance benchmarking. ANSM oversight of medical device clinical performance data requirements shapes post-market surveillance protocols for diagnostic utility claims. The Auvergne-Rhône-Alpes cluster concentrates rehabilitation equipment distribution networks serving both domestic and export channels.
Brazil
Commercial fitness chains in São Paulo and Rio de Janeiro are expanding installed bases of electromagnetic resistance systems as studio-class training experiences penetrate mid-tier price points. ANVISA regulatory pathways for imported diagnostic equipment create compliance bottlenecks that favor established distributor relationships over direct manufacturer entry. The Southeast region concentrates equipment financing networks that enable lease-based procurement for independent gym operators.
Ergometer Market Vendor Landscape
Swedish and Dutch producers anchor the clinical precision tier; Italian and German specialists hold integrated platform and rehabilitation equipment positions. The vendor base separates into three strategic archetypes: laboratory-grade calibration specialists, connected fitness platform integrators, and economy-tier volume manufacturers. M&A activity concentrates on acquiring ISO 17025-accredited service networks; portfolio diversification drives expansion from clinical diagnostics into consumer-connected hardware.
Within the clinical precision tier, Monark Exercise AB and Lode BV exemplify manufacturers whose positioning derives from diagnostic-grade accuracy requirements and hospital-based rehabilitation department relationships. Technogym S.p.A occupies a position bridging commercial fitness networks and integrated digital platform control across European markets. These three companies represent distinct competitive vectors: precision manufacturing specialization, cardiopulmonary system dominance, and connected training ecosystem integration.
| Leading Market Players |
|---|
| Amer Sports |
| h/p/cosmos sports & medical GmbH |
| Technogym S.p.A |
| Monark Exercise AB |
| Lode BV |
| Life Fitness |
| Icon Health & Fitness |
| Cybex International |
| Ergoline GmbH |
| Others |
Supply Flow & Price Mechanics
Hospital procurement departments in Germany and the United States now dominate demand concentration for diagnostic-grade ergometer systems, locking in multi-year service contracts that bundle equipment, calibration, and software subscriptions into operational expenditure frameworks rather than capital purchases.
Pricing Analysis
Capacity additions in East Asian manufacturing clusters are reshaping price floors for magnetic resistance systems serving economy-tier consumer channels. Pricing stratifies across electronic resistance premium tiers, ISO 17025 calibration certification levels, and basic magnetic economy offerings. Cost compression in consumer-grade equipment intensifies as Bluetooth-enabled connected platforms standardize power measurement features. Home fitness buyers in North American markets exhibit highest price sensitivity, while German rehabilitation facilities prioritize diagnostic accuracy over unit cost.
Supply Chain Analysis
Calibration technician scarcity in German metropolitan hospital networks constrains service capacity expansion for clinical-grade system deployments. Manufacturing draws from precision motor controller supply networks in Taiwan, load cell sensor production in Japan, and electromagnetic assembly operations in China. Single-source vulnerability concentrates in East Asian foundry networks for semiconductor inputs. Distribution runs through hospital GPO contracts in the United States, specialized medical device distributors in Europe, and direct-to-consumer retail channels for home fitness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
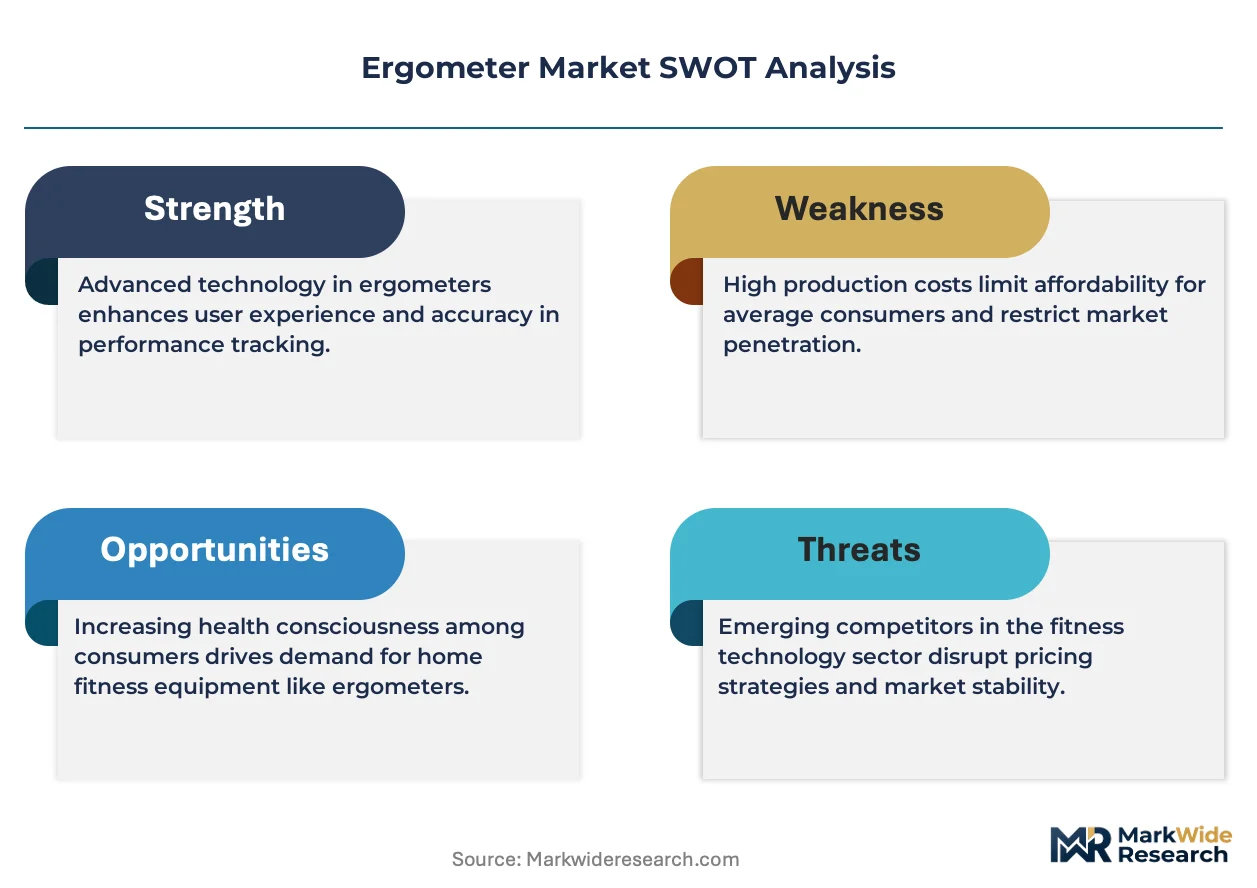
The ergometer market functions as a stable compounder anchored by tightening cardiac rehabilitation protocols that mandate programmable load curves and automated documentation across clinical networks.
For Market Incumbents:To counter wearable power meter substitution threatening stationary ergometer demand in athletic training segments, incumbents should deepen ISO 17025-accredited service network coverage and accelerate FDA 510(k) software-as-medical-device certification for connected rehabilitation platforms. Backward integration into precision electromagnetic resistance manufacturing secures component supply stability.
For New Entrants and Emerging Players:Enter via Japan's prefecture-level geriatric cardiac therapy expansion, where seated recumbent ergometer demand outpaces domestic manufacturing capacity. White-space opportunity concentrates in AI-driven adaptive resistance protocols for consumer price points and telehealth-integrated remote patient monitoring systems in Texas and Florida rehabilitation networks. Go-to-market positioning should emphasize subscription-integrated training platforms over hardware-only sales.
For Investors and Strategic Acquirers:Connected fitness platform operators represent the most active acquirer category in this space, seeking ISO 17025-accredited calibration service networks to complete vertical capability stacks. Long-term viability frames around 5-10 year clinical protocol digitization cycles. Acquisition target archetypes include precision manufacturing specialists with MDR technical documentation capabilities. Monitor FDA software-as-medical-device clearance timelines as inflection signal for connected product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | German notified body review queues now extend twenty-two months, forcing roadmap synchronization. |
| Telehealth Platform Integration | Remote patient monitoring reimbursement codes in US cardiac rehabilitation networks create pull-through demand. |
| ISO 17025 Service Network Acquisition | Calibration technician scarcity in metropolitan hospital networks concentrates maintenance value capture. |
| AI-Driven Personalization Development | Machine learning convergence with real-time biomechanical feedback enables consumer-tier adaptive protocols. |
| East Asian Manufacturing Footprint Expansion | Magnetic resistance assembly concentration in Taiwan and China supports economy-tier cost positioning. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with hospital procurement managers, biomedical engineers, rehabilitation clinicians, and GPO contracts specialists alongside secondary validation. Sources include FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital capital expenditure records, and ISO 17025 accreditation registries. Bottom-up equipment shipment analysis triangulates against top-down reimbursement code expansion metrics.
Rate-of-change decomposition separates volume growth from value expansion across electronic resistance, magnetic resistance, air resistance, and fluid resistance technology tiers. Segmentation dimensions encompass product type, end user archetype, resistance mechanism, and application purpose. CAGR derivation rests on installed base replacement cycles, clinical protocol adoption curves, and connected platform penetration rates. Forecast inputs incorporate semiconductor supply availability and notified body review timeline projections.
Inputs from German hospital procurement departments and US cardiac rehabilitation networks were available through the study window; gaps in Japanese prefecture-level budget allocation detail introduce uncertainty bands around Asia-Pacific demand trajectories. Forecasts reflect documented assumptions regarding MDR certification timeline normalization and FDA software-as-medical-device pathway efficiency. Material deviation in FDA review velocity or EU notified body capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Exercise Bike Market
Fitness Equipment
Cardio Fitness Trampolines Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Gymnastic Springboard Market