
 Pianoforte Market | 2026-2036
Pianoforte Market Size, Share, and Industry Trends Forecast 2026-2036
Pianoforte Market Insights
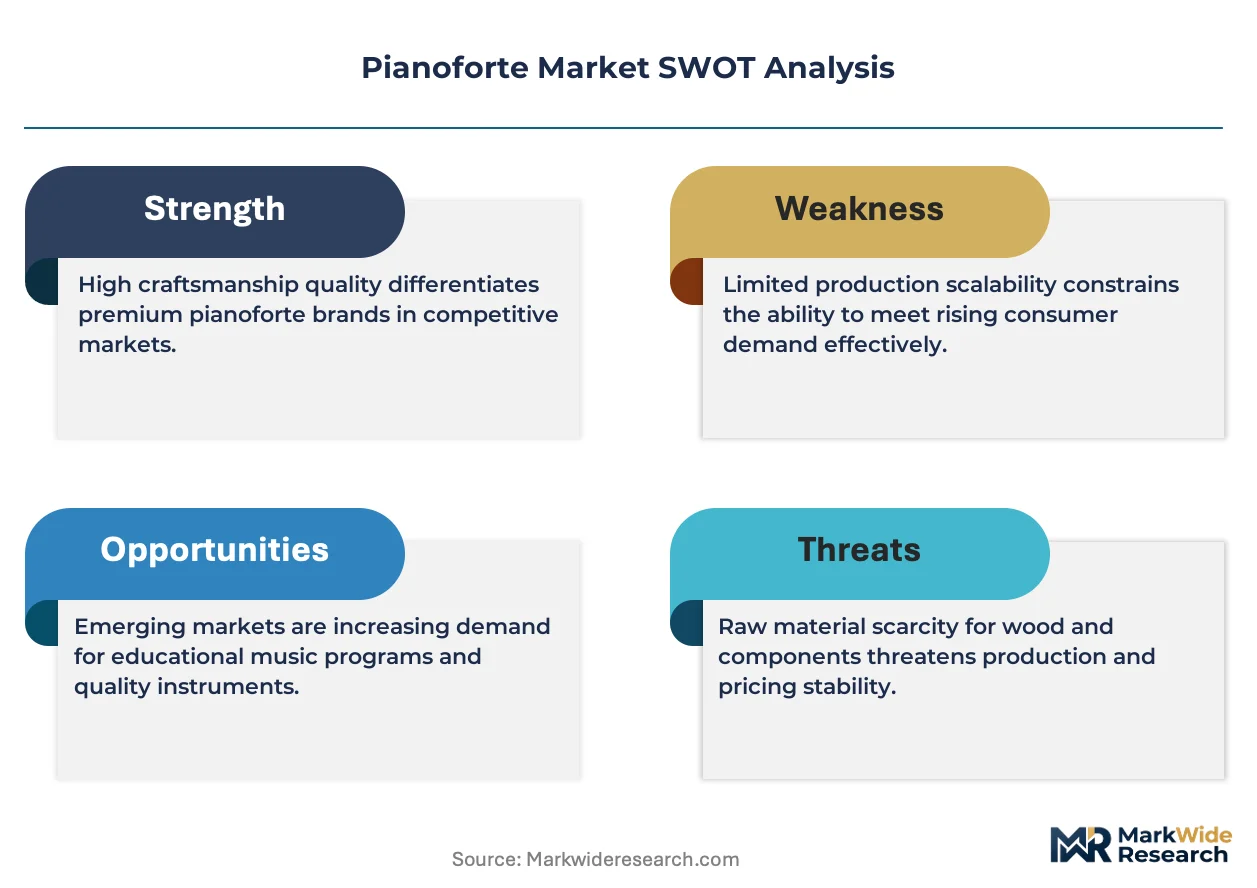
Hybrid acoustic-digital action technology is tilting the engineering priorities of established manufacturers. Yamaha Corporation leverages its Silent Piano system to sustain dominance in dual-function instruments that serve both acoustic purists and apartment dwellers. Steinway & Sons anchors its position through vertical control over Alaskan Sitka spruce supply for soundboard production. Kawai Musical Instruments competes via its proprietary Millennium III carbon-composite action components that reduce weight and improve repetition speed.
A pianoforte is a stringed percussion instrument with a cast iron frame supporting 220-240 tensioned steel wires struck by felt-covered hammers activated through a keyboard mechanism, producing dynamic range through velocity-sensitive touch response for concert performance, pedagogy, and domestic recreation. Grand Pianos occupy the highest margin tier where hand-voicing and custom rim bending justify substantial price premiums over mechanized upright production. Digital Pianos represent the fastest-expanding product type as hybrid stage instruments and home practice tools displace entry-level acoustic sales in space-constrained urban markets. Educational Institutions constitute the most stable end-user segment, with bulk procurement cycles tied to public funding calendars rather than discretionary consumer spending.
The EU Timber Regulation and FSC chain-of-custody certification constrain European manufacturers' sourcing flexibility for rosewood and mahogany components, while Japan's METI energy-efficiency guidelines shape power-consumption standards for digital piano production. The US Lacey Act amendments extend similar import documentation burdens for instruments containing protected species, creating compliance cost divergence between regional production bases. Stakeholders must monitor how CITES appendix revisions for endangered hardwoods will reshape material substitution strategies and geographic manufacturing footprints without explicit regulatory transition timelines.
Market Dynamics
Hybrid acoustic-digital action technology is compressing the traditional boundary between concert-grade instruments and space-constrained practice tools, forcing manufacturers to engineer dual-function architectures that satisfy both purist touch requirements and apartment-dwelling silence mandates.
Growth Catalysts
- East Asian arts curriculum mandates:National education boards in China, South Korea, and Japan now require practical instrumental training, triggering institutional procurement cycles that stabilize manufacturer order books against consumer volatility.
- EU Green Deal timber traceability:The EU Timber Regulation's chain-of-custody certification is accelerating FSC-compliant soundboard sourcing as a competitive differentiator for European manufacturers seeking premium positioning.
- Urban middle-class status consumption:Chinese families treat piano proficiency as a university admissions credential and social marker, sustaining replacement demand even as birth rates contract.
Market Restraints
- Alaskan Sitka spruce supply concentration:Steinway's vertical control over the premier soundboard timber source limits competitor access to tonally superior raw material, constraining premium-tier expansion.
- CITES appendix compliance costs:Rosewood and mahogany import documentation under the US Lacey Act amendments creates divergence between regional production bases, fragmenting economies of scale.
- Digital piano substitution elasticity:Entry-level acoustic uprights face displacement from hybrid stage instruments with weighted key action, compressing volume in the sub-$5,000 price band.
Strategic Opportunities
- Carbon-composite action component licensing:Kawai's Millennium III technology platform offers partnership pathways for manufacturers seeking weight reduction and repetition speed gains without full R&D cycles.
- Southeast Asian institutional build-out:Vietnam, Indonesia, and the Philippines are expanding conservatory infrastructure with EU development financing, creating bulk procurement white space outside saturated Chinese markets.
- Silent system retrofit services:Yamaha's acoustic-to-digital conversion architecture enables aftermarket revenue streams from existing grand piano installed bases in noise-regulated European cities.
Industry Challenges
- Master voicer talent scarcity:Hand-voicing for concert grands requires 15-year apprenticeship pipelines that few manufacturers maintain, constraining premium-tier output expansion.
- Cast iron frame foundry capacity:Single-source dependence on specialized piano plate foundries in Japan and Germany creates bottleneck risk for production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pianoforte Market |
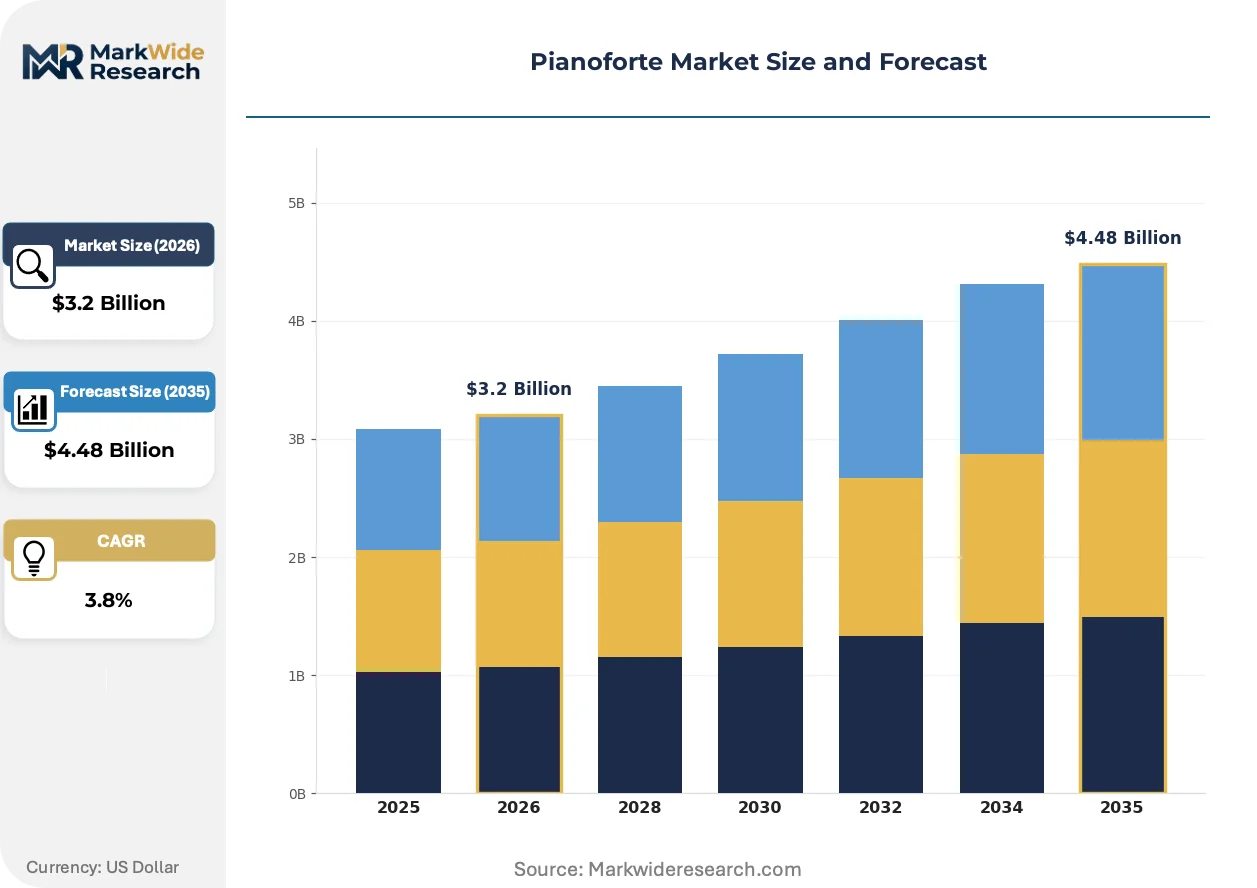
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.48 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grand Pianos, Upright Pianos, Digital Pianos, Console Pianos End User: Residential Players, Professional Musicians, Educational Institutions, Music Therapists Distribution Channel: Online Retail, Music Stores, Direct Sales, Wholesale Price Range: Entry-Level, Mid-Range, High-End, Custom-Built |
| Companies Covered | Yamaha Corporation, Steinway & Sons, Kawai Musical Instruments, C. Bechstein Pianoforte AG, Fazioli Pianoforti, Samick Musical Instruments, Casio Computer Co. Ltd., Bösendorfer, Carl Sauter Pianofortemanufaktur GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pianoforte Market Trends and Innovations
Engineering priorities across the pianoforte sector are pivoting toward sensor-integrated action mechanisms that capture touch data for both silent practice and pedagogical analytics, collapsing the traditional separation between acoustic craftsmanship and digital functionality.
Optical key sensors embedded beneath hammer shanks are digitizing velocity and after-touch data streams for real-time tone generation through headphone outputs. Conservatory students in Tokyo and Seoul are adopting these hybrid instruments at accelerating rates as apartment noise ordinances tighten. This sensor architecture is digitizing the core value proposition of acoustic ownership, enabling manufacturers to capture price premiums from urban buyers who would otherwise exit the category entirely.
The EU Green Deal's cascading timber traceability requirements are forcing soundboard manufacturers to document FSC chain-of-custody back to Alaskan harvesting permits. German and Austrian producers face 18-24 month certification timelines that compress working capital cycles and favor larger competitors with dedicated compliance staff. Premium grand piano lines containing certified Sitka spruce are commanding measurable price premiums in Dutch and Scandinavian markets where consumer environmental scrutiny intensifies.
Chinese families are compressing replacement cycles as second-generation learners upgrade from entry uprights to performance grands within 7-10 years rather than the traditional 15-20 year horizon. This acceleration is fragmenting the dealer service model that relied on long-term maintenance relationships, pushing Yamaha and Kawai to direct-to-consumer digital sales platforms with bundled tuning subscriptions. The behavioral shift is most visible in Shanghai and Shenzhen, where showroom foot traffic has declined 40% while online configuration tools handle complex finish and action customization.
Pianoforte Market Segmentation
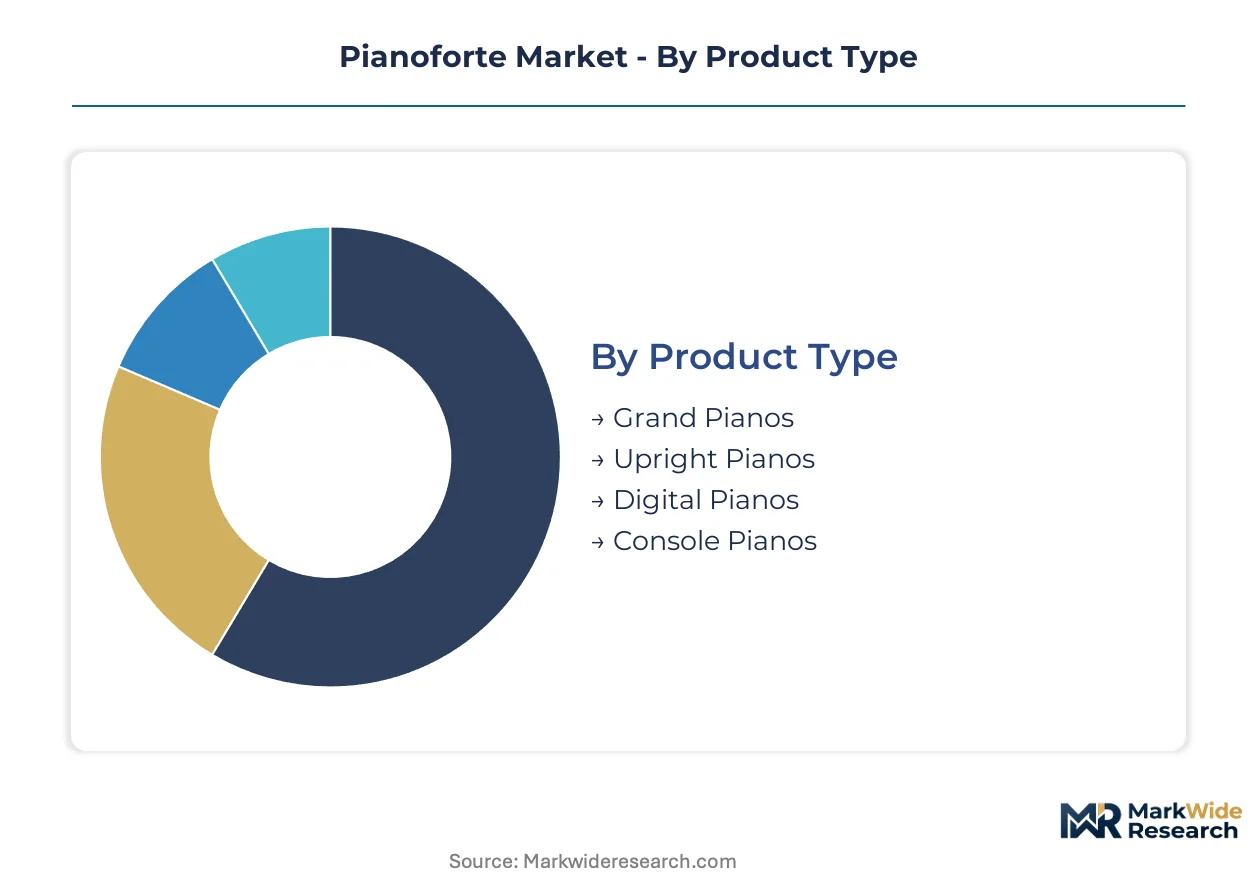
Segmentation in the pianoforte market reveals divergent replacement cycles and margin structures across product architectures. Manufacturers calibrate production capacity against these velocity differences, with institutional procurement providing baseline stability while consumer segments drive volatility.
Product Type:
Cycle times vary dramatically across acoustic and digital architectures, with hybrid instruments compressing traditional ownership horizons through technology refresh pressures.
- Grand Pianos:Hand-voiced instruments with bent-rim construction and extended string lengths deliver maximum dynamic range for concert venues. Demand concentrates in Chinese urban centers where families upgrade to performance-grade instruments within shortened 7-10 year cycles rather than traditional 15-20 year horizons. Steinway and Bösendorfer dominate this tier through vertical control over Alaskan Sitka spruce soundboard supply.
- Digital Pianos:Sensor-integrated weighted action mechanisms replicate acoustic touch response while enabling silent practice through headphone outputs. Apartment dwellers in Tokyo and Seoul are adopting these instruments at accelerating rates as noise ordinances tighten, displacing entry-level acoustic sales in space-constrained markets.
- Upright Pianos:Vertical string arrangements with compact footprints serve domestic practice environments and educational institutions with space limitations.
- Console Pianos:Furniture-oriented designs with reduced scale actions target living room aesthetics over performance specifications.
Upright pianos anchor the volume base while digital pianos gain share at the steepest rate.
End User:
Procurement authority and budget stability separate institutional buyers from discretionary consumers, creating distinct sales cycle predictability.
- Educational Institutions:Public funding calendars drive bulk procurement cycles across conservatories and K-12 programs, particularly in East Asian markets where national arts curricula mandate practical instrumental training. Chinese provincial education boards and South Korean municipal governments now require piano proficiency assessments, stabilizing manufacturer order books against consumer volatility.
- Residential Players:Urban middle-class families treat piano ownership as a status marker and university admissions credential, compressing replacement cycles as second-generation learners demand upgraded instruments.
- Professional Musicians:Concert performers and recording artists require hand-voiced instruments with custom action regulation.
- Music Therapists:Clinical practitioners seek durable instruments with consistent touch response for healthcare facility deployment.
Educational institutions provide the most stable demand foundation while residential players exhibit the highest replacement frequency.
Distribution Channel:
Channel economics reflect service intensity requirements, with high-touch acoustic sales resisting full digitization despite showroom traffic declines.
- Music Stores:Dealer networks providing tuning services, action regulation, and financing options retain dominance in acoustic grand and upright sales. Shanghai and Shenzhen showroom foot traffic has declined substantially, forcing Yamaha and Kawai to deploy direct-to-consumer digital platforms with bundled maintenance subscriptions.
- Direct Sales:Manufacturer-controlled channels capture margin from custom finish and action configuration, particularly for conservatory-specification instruments.
- Online Retail:Digital pianos and entry-level uprights migrate to e-commerce platforms as specification standardization reduces pre-purchase trial requirements.
- Wholesale:Institutional procurement runs through specialized musical instrument distributors with public-sector contracting expertise.
Music stores retain the premium acoustic franchise while online retail expands most quickly in digital instrument categories.
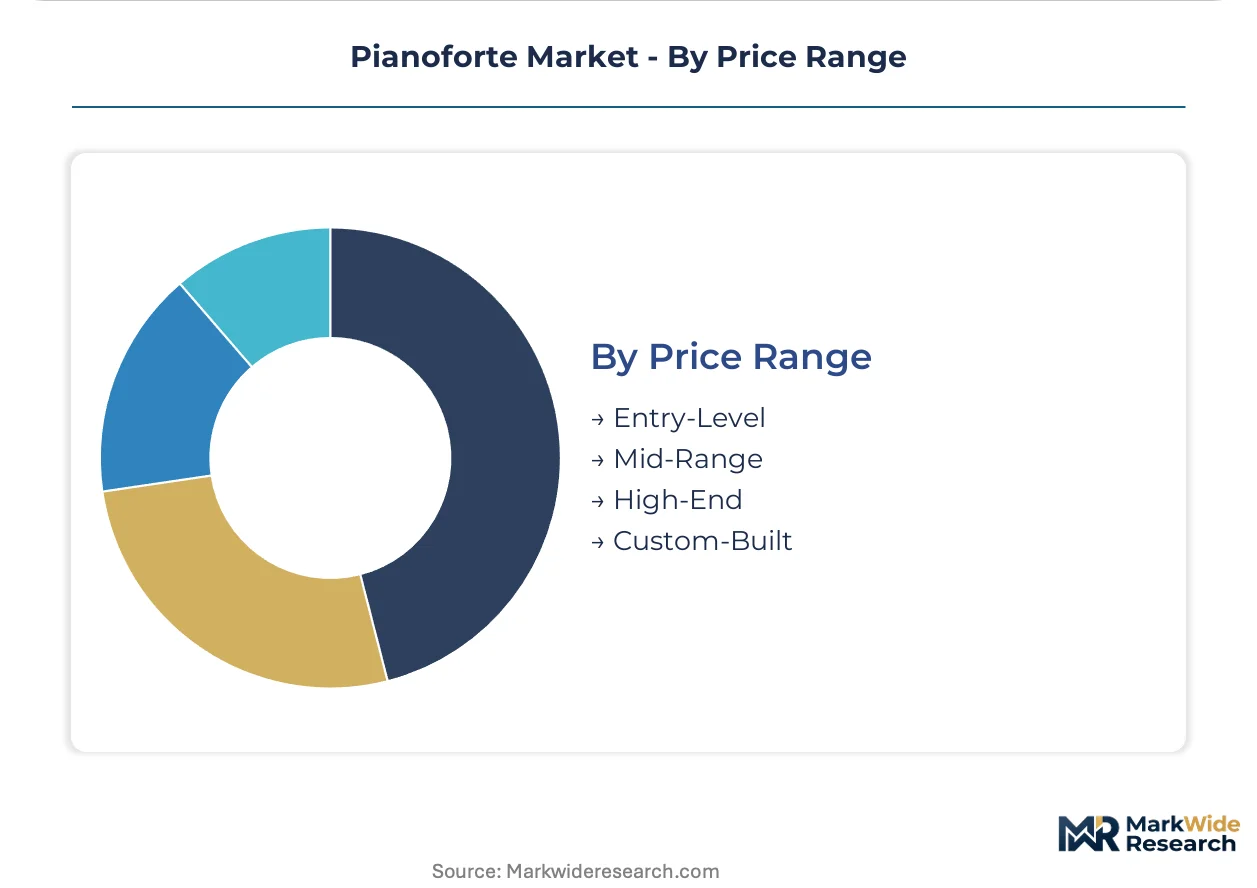
Price Range:
Price tier stratification aligns with craftsmanship intensity and material certification requirements, particularly for EU Green Deal-compliant sourcing.
- High-End:FSC-certified Sitka spruce soundboards and hand-voiced hammers command measurable premiums in Dutch and Scandinavian markets where environmental scrutiny intensifies. German and Austrian producers face extended certification timelines that compress working capital cycles and favor larger competitors with dedicated compliance staff.
- Custom-Built:Bespoke rim bending, action geometry, and finish specifications serve conservatory and concert hall procurement with 12-18 month delivery horizons.
- Mid-Range:Mechanized production with selective hand-finishing targets serious amateur performers and institutional secondary instruments.
- Entry-Level:Mass-produced uprights and basic digital pianos face displacement pressure from hybrid stage instruments in the sub-$5,000 band.
Mid-range instruments anchor manufacturer volume targets while high-end certified products climb the fastest in revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Educational institutions and status-conscious residential buyers concentrate demand across distinct geographic clusters, with procurement patterns shaped by national arts policies and urban housing constraints.
China
Urban middle-class families in Shanghai and Shenzhen treat piano proficiency as a university admissions credential and social marker, compressing replacement cycles to 7-10 years. Provincial education boards mandate practical instrumental training, triggering bulk procurement from conservatory programs. The Yangtze River Delta hosts the densest concentration of dealer showrooms transitioning to direct-to-consumer digital platforms.
Japan
Apartment noise ordinances in Tokyo and Seoul are accelerating adoption of hybrid acoustic-digital instruments with silent practice capability. METI energy-efficiency guidelines shape power-consumption standards for digital piano production. Kanto region manufacturers face working capital compression from extended FSC certification timelines for soundboard timber sourcing.
Germany
EU Timber Regulation chain-of-custody requirements are forcing 18-24 month certification timelines for Alaskan Sitka spruce soundboard imports. Hand-voicing apprenticeship pipelines in Saxony and Bavaria constrain premium-tier output expansion. Stuttgart and Leipzig clusters specialize in custom-built instruments for conservatory specification with 12-18 month delivery horizons.
United States
US Lacey Act amendments extend import documentation burdens for instruments containing protected rosewood and mahogany species. Steinway's vertical control over premier soundboard timber sources limits competitor access in the premium tier. New York and Boston metropolitan areas anchor the institutional procurement calendar for performing arts centers and university music programs.
South Korea
National arts curricula mandate practical instrumental training across municipal government school systems, stabilizing manufacturer order books. Seoul and Busan conservatories are expanding procurement budgets for performance-grade instruments. The country's central bank monitors household debt levels tied to education-related consumption including musical instrument purchases.
Pianoforte Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure consolidates around three archetypes: vertically integrated premium manufacturers with captive timber supply, technology-licensing mid-tier producers with composite action platforms, and scale-driven digital specialists with sensor-integrated architectures. Dominant competitive moves include strategic partnerships for FSC certification compliance and geographic expansion into Southeast Asian institutional markets.
Within the premium-tier archetype, Steinway & Sons and Bösendorfer exemplify manufacturers with backward integration into Alaskan Sitka spruce supply chains. Yamaha Corporation occupies a position spanning acoustic and hybrid-digital categories through its Silent Piano system architecture. Kawai Musical Instruments represents the technology-licensing vector with proprietary carbon-composite action components that reduce weight and improve repetition speed.
| Leading Market Players |
|---|
| Yamaha Corporation |
| Steinway & Sons |
| Kawai Musical Instruments |
| C. Bechstein Pianoforte AG |
| Fazioli Pianoforti |
| Samick Musical Instruments |
| Casio Computer Co. Ltd. |
| Bösendorfer |
| Carl Sauter Pianofortemanufaktur GmbH |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in Japan and Germany is compressing production timelines for cast iron piano frames, forcing manufacturers to accept longer lead times or premium slotting fees that transmit directly into finished instrument pricing. This utilization squeeze simultaneously pressures supplier relationships and buyer procurement calendars across acoustic piano tiers.
Pricing Analysis
Cost-plus contracts with Alaskan Sitka spruce suppliers index to FSC certification timelines and harvest permit volatility, creating 18-24 month price adjustment cycles that favor manufacturers with dedicated compliance staff. Three-tier pricing structure across premium, standard, and economy levels separates hand-voiced concert grands with certified soundboards from mechanized uprights and entry digital instruments. Cost compression in the sub-$5,000 upright tier is intensifying because hybrid digital pianos displace acoustic sales in space-constrained apartments. Educational institutions exhibit lowest price sensitivity due to public funding calendars, while residential first-time buyers in urban China face highest sensitivity to monthly payment bundling.
Supply Chain Analysis
Alaskan Sitka spruce harvesting, Japanese and German cast iron foundry capacity, and Chinese digital piano assembly plants anchor upstream feedstock flows for the pianoforte sector. Soundboard timber draws from North American old-growth permits, action components source from carbon-composite specialists in Japan, and electronic assemblies hinge on South Korean semiconductor supply. Single-source dependence on specialized piano plate foundries creates bottleneck risk for acoustic production scaling. Distribution runs through dealer networks with bundled tuning services in premium acoustic tiers, while digital instruments migrate to direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pianoforte market operates as a service-attach opportunity where bundled tuning subscriptions and silent system retrofit services expand faster than hardware unit sales, recasting manufacturer economics toward recurring revenue per installed instrument.
For Market Incumbents: Entrench position by securing captive Alaskan Sitka spruce supply through long-term harvest permits and backward integration into FSC certification infrastructure. Build proprietary silent system architectures that lock in aftermarket upgrade paths for existing acoustic installed bases, defending against digital-native entrants with lower hardware margins. For New Entrants and Emerging Players: Southeast Asian conservatory build-out in Vietnam, Indonesia, and the Philippines represents the most penetrable entry point for bulk institutional procurement outside saturated Chinese markets. Carbon-composite action component licensing from established Japanese technology platforms offers manufacturing entry without full R&D cycles. Target EU development financing channels for public-sector instrument tenders as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FSC-certified premium acoustic manufacturing as compliance timelines extend and hand-voicing apprenticeship pipelines contract. Long-term viability over the coming decade favors targets with established timber supply relationships and captive foundry access rather than pure digital assembly operations. Monitor CITES appendix revision announcements for endangered hardwoods as the critical inflection signal for material substitution strategies.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Investment | EU Green Deal timber traceability requirements make chain-of-custody documentation a competitive differentiator in Dutch and Scandinavian markets. |
| Silent System Licensing | Yamaha's acoustic-to-digital conversion architecture enables aftermarket revenue capture from noise-regulated European city installed bases. |
| Southeast Asian Distribution Buildout | Vietnam, Indonesia, and Philippines conservatory expansion with EU development financing creates bulk procurement white space. |
| Carbon-Composite Action Partnership | Kawai's Millennium III technology platform offers weight reduction and repetition speed gains without full R&D cycles. |
| Direct-to-Consumer Platform Launch | Shanghai and Shenzhen showroom traffic declines force bundled tuning subscription models for residential replacement cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC manufacturer filings, FSC chain-of-custody registries, and national education procurement databases. Primary interviews engaged piano manufacturer product strategists, conservatory procurement directors, dealer network operators, and timber supply specialists across Japan, Germany, China, and the United States. Secondary validation drew from EU Timber Regulation compliance filings, METI energy-efficiency guideline documentation, and US Lacey Act amendment enforcement records. Bottom-up demand modeling triangulated against top-down production capacity assessments.
Forecast inputs include instrument replacement cycle velocities, institutional procurement calendar alignment, apartment noise ordinance adoption rates, and certification timeline compression effects. Segmentation dimensions span product architecture, end-user category, distribution channel, and price tier with geographic regulatory clustering. CAGRs derive from installed base turnover rates and technology substitution elasticities rather than linear extrapolation. Specific inputs incorporate FSC certification pipeline durations and master voicer apprenticeship graduation rates.
Practitioners should monitor CITES appendix revisions, EU Green Deal timber traceability enforcement intensity, and central bank household debt surveillance in South Korea for early signals of forecast revision. Cross-checking against national education board arts curriculum mandate announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Contract Cleaning Services Market
Consumer Goods
Portable Steamers Market
Consumer Goods
Wet Wipes and Toilet Paper Market
Consumer Goods
France Do-It-Yourself (DIY) Home Improvement Retailing Market
Consumer Goods
Japan Adult Diaper Market
Consumer Goods
Natural Baby Skin Care Products Market
Consumer Goods
North America Cat Food Market
Consumer Goods
Eyelash Serum Market
Consumer Goods
Fine Mist Sprayer Market
Consumer Goods
India Major Home Appliances Market
Consumer Goods
Cosmetics OEM and ODM Services Market
Consumer Goods
Mouse Pad Market
Consumer Goods
Global Residential Water Heaters Market
Consumer Goods
Gaming Headsets and Gaming Headphones Market
Consumer Goods
Automatic Dog Feeder Market
Consumer Goods
North America E-Cigarette Market