
 Japan Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
Japanese home improvement retail is consolidating around large-format operators with national distribution networks. DCM Holdings leverages its supercenter footprint to dominate suburban trade areas across Honshu. Komeri Co.,Ltd. anchors rural markets with localized inventory tailored to agricultural-adjacent households. Joyful Honda Co. Ltd differentiates through experiential store layouts that blend showroom displays with hands-on workshop zones.
Japan Do-It-Yourself (DIY) Home Improvement Retailing encompasses the sale of tools, paints, hardware, and garden supplies through physical and digital channels to consumers and trade buyers performing residential maintenance, renovation, and decoration. Product specifications follow JIS standards for hand tools and METI labeling rules for volatile organic compounds in coatings. Tools and hardware command the largest revenue pool due to repeat purchase cycles among homeowner segments. Online retail represents the fastest-growing sales channel as logistics networks now support same-day delivery of bulky items to dense metropolitan addresses.
METI enforces building energy codes that mandate thermal insulation performance in renovation materials, while the Consumer Affairs Agency monitors product safety labeling under the Household Goods Quality Labeling Act. JIS standards for power tools and chemical content restrictions on interior paints shape procurement requirements for all major retailers. Stakeholders must monitor how prefectural retrofit subsidy programs redirect demand toward certified efficiency products versus conventional alternatives.
Market Dynamics
METI's tightening energy efficiency standards for building retrofits are forcing retailers to reconfigure inventory toward certified insulation and low-VOC coatings, while logistics networks race to support same-day delivery of bulky renovation materials to dense metropolitan addresses.
Growth Catalysts
- Prefectural retrofit subsidies:Local governments in Kanto and Kansai regions redirect homeowner spending toward certified thermal insulation products, expanding addressable demand for compliant retailers.
- Power tool electrification:Lithium-ion battery platforms are displacing corded equipment in residential renovation, shortening replacement cycles and expanding accessory attach rates.
- Aging housing stock:Japan's 50-year-plus residential inventory requires continuous maintenance, generating recurring demand for waterproofing, structural repair, and exterior refresh materials.
Market Restraints
- Import dependency for lithium cells:Battery-powered tool supply chains concentrate in East Asian cell manufacturers, exposing margins to raw material volatility and currency fluctuation.
- Limited rural logistics density:Same-day delivery economics fail outside metropolitan prefectures, constraining online channel penetration in Hokkaido and Tohoku.
- JIS certification timelines:New product introductions face 6-12 month approval cycles for hand tools and power equipment, delaying seasonal inventory positioning.
Strategic Opportunities
- Workshop-service hybrid formats:Retailers blending showroom space with hands-on skill training capture higher-margin project-based spending from novice renovators.
- Chūgoku and Shikoku expansion:Underserved prefectures in western Honshu present whitespace for localized inventory models tailored to agricultural-adjacent maintenance needs.
- METI ZEB subsidies:Net-zero energy building incentives accelerate demand for high-performance windows, heat pumps, and integrated building envelope systems.
Industry Challenges
- Skilled installer scarcity:Declining construction workforce participation lengthens project timelines and shifts demand toward simpler DIY solutions that retailers must support with instructional content.
- Legacy ERP integration:Wholesale distributors struggle to synchronize inventory visibility between physical supercenters and emerging direct-to-consumer platforms.
- Chemical labeling compliance:The Consumer Affairs Agency's evolving VOC disclosure requirements demand continuous reformulation of coatings and adhesives, complicating supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Do-It-Yourself (DIY) Home Improvement Retailing Market |
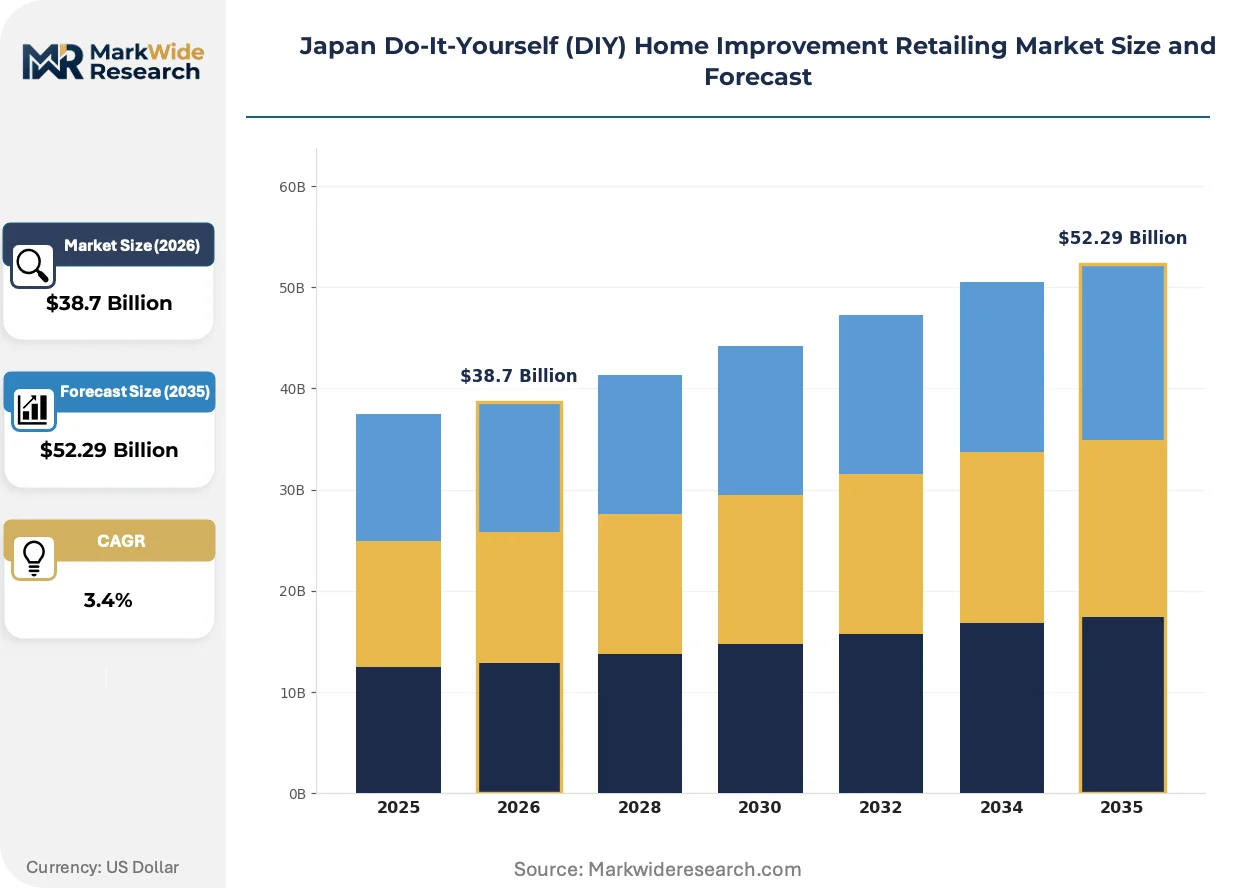
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $52.29 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paints, Hardware, Garden Supplies Customer Type: Homeowners, Renters, Contractors, DIY Enthusiasts Sales Channel: Online Retail, Brick-and-Mortar, Wholesale, Pop-Up Stores Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | DCM Holdings, Alleanza Holdings Co.,Ltd., Komeri Co.,Ltd., Ochi Holdings Co. Ltd, Watahan & Co.,Ltd., Joyful Honda Co. Ltd, NAFCO Co. Ltd, Sunday Co.,Ltd., Kohnan Shoji Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Japanese home improvement retail is converging around three vectors: battery-powered equipment platforms, regulatory pressure on building materials chemistry, and the unbundling of professional installation from product purchase.
Brushless motor technology paired with standardized 18V and 40V battery ecosystems is electrifying the residential power tool category. Homeowners in Tokyo and Osaka are adopting these platforms for deck construction and interior renovation, compressing the replacement cycle for corded equipment and expanding demand for cross-compatible accessories.
METI's 2022 amendments to the Act on the Rational Use of Energy mandate thermal performance disclosures for renovation materials. Retailers must now stock insulation and window systems with verified U-value ratings, while coatings face parallel pressure from the Consumer Affairs Agency to reduce VOC content below 400g/L thresholds.
Digital channels are capturing project-planning and material-quoting functions previously handled in-store. Younger homeowners in metropolitan prefectures now research specifications online before visiting showrooms for tactile validation, forcing retailers to unify pricing and availability across physical and digital touchpoints.
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
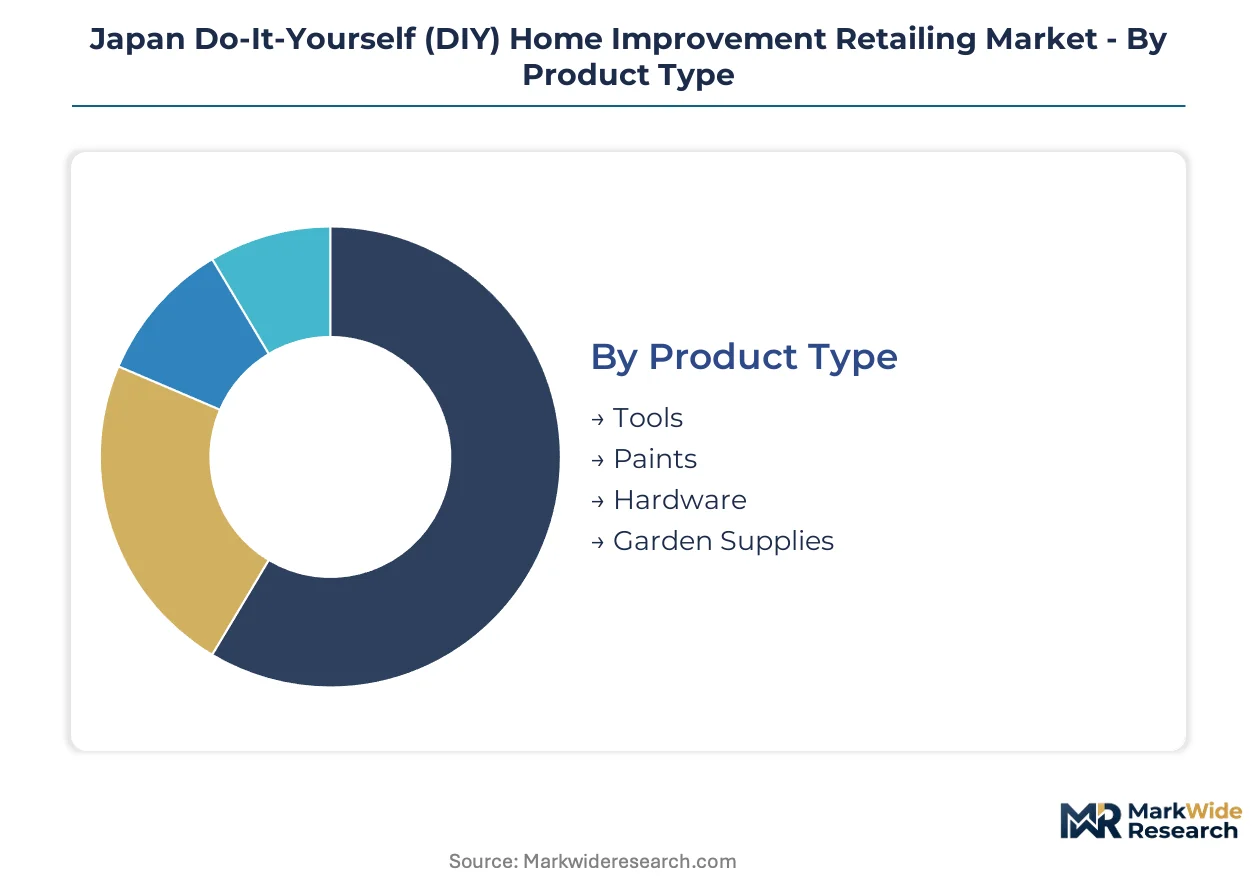
Japan's DIY retail market fragments along product specialization, customer sophistication, and channel economics. Each dimension carries distinct inventory, margin, and service implications for operators navigating METI efficiency mandates and prefectural subsidy programs.
Product Type:
Supply concentration in Japanese manufacturing clusters around Osaka and Nagoya shapes product availability and certification timelines across this category.
- Tools:Hand tools follow JIS B 4635 standards for hardness and dimensional tolerance, while power tools increasingly adopt 18V and 40V lithium-ion platforms. Tokyo and Osaka homeowners drive replacement cycles as brushless motors displace corded equipment in residential renovation.
- Paints:Interior and exterior coatings face Consumer Affairs Agency VOC limits below 400g/L, forcing continuous reformulation. Kanto prefectures absorb the largest volumes as METI retrofit subsidies redirect demand toward certified low-emission products.
- Hardware:Fasteners, hinges, and structural connectors serve maintenance of Japan's 50-year-plus housing stock.
- Garden Supplies:Agricultural-adjacent households in rural prefectures sustain demand for tillers, pruning equipment, and soil amendments.
Tools absorb the bulk of installed retail capacity; Paints is expanding most quickly under regulatory pressure.
Customer Type:
Cost tier differentiation separates professional-grade procurement from amateur project spending across this dimension.
- Homeowners:Owner-occupiers in aging Tokyo and Osaka condominiums execute bathroom refreshes and kitchen upgrades, purchasing mid-range power tools and certified insulation materials.
- DIY Enthusiasts:Hobbyist renovators in metropolitan prefectures favor experiential retail formats with workshop training, spending premium prices for cross-compatible battery platforms.
- Contractors:Small installation crews source bulk fasteners and structural repair materials through wholesale channels.
- Renters:Leaseholders concentrate purchases on portable, non-permanent solutions like freestanding shelving and temporary lighting.
Homeowners absorb the bulk of installed capacity; DIY Enthusiasts is climbing the fastest as workshop-service hybrid formats proliferate.
Sales Channel:
Volume concentration in metropolitan logistics networks determines same-day delivery feasibility and online penetration rates.
- Brick-and-Mortar:Supercenters and specialized outlets across Honshu provide tactile validation for coatings and power tools, with suburban locations capturing trade-area renovation spending.
- Online Retail:Digital platforms capture project-planning and material-quoting functions previously handled in-store, though bulky-item economics fail outside Kanto and Kansai density.
- Wholesale:Distributors serve contractor segments with pallet-quantity fasteners and structural materials, struggling to synchronize ERP visibility with direct-to-consumer platforms.
- Pop-Up Stores:Temporary formats test localized demand in underserved Chūgoku and Shikoku prefectures.
Brick-and-Mortar absorbs the bulk of installed capacity; Online Retail is gaining share fastest where logistics density permits.
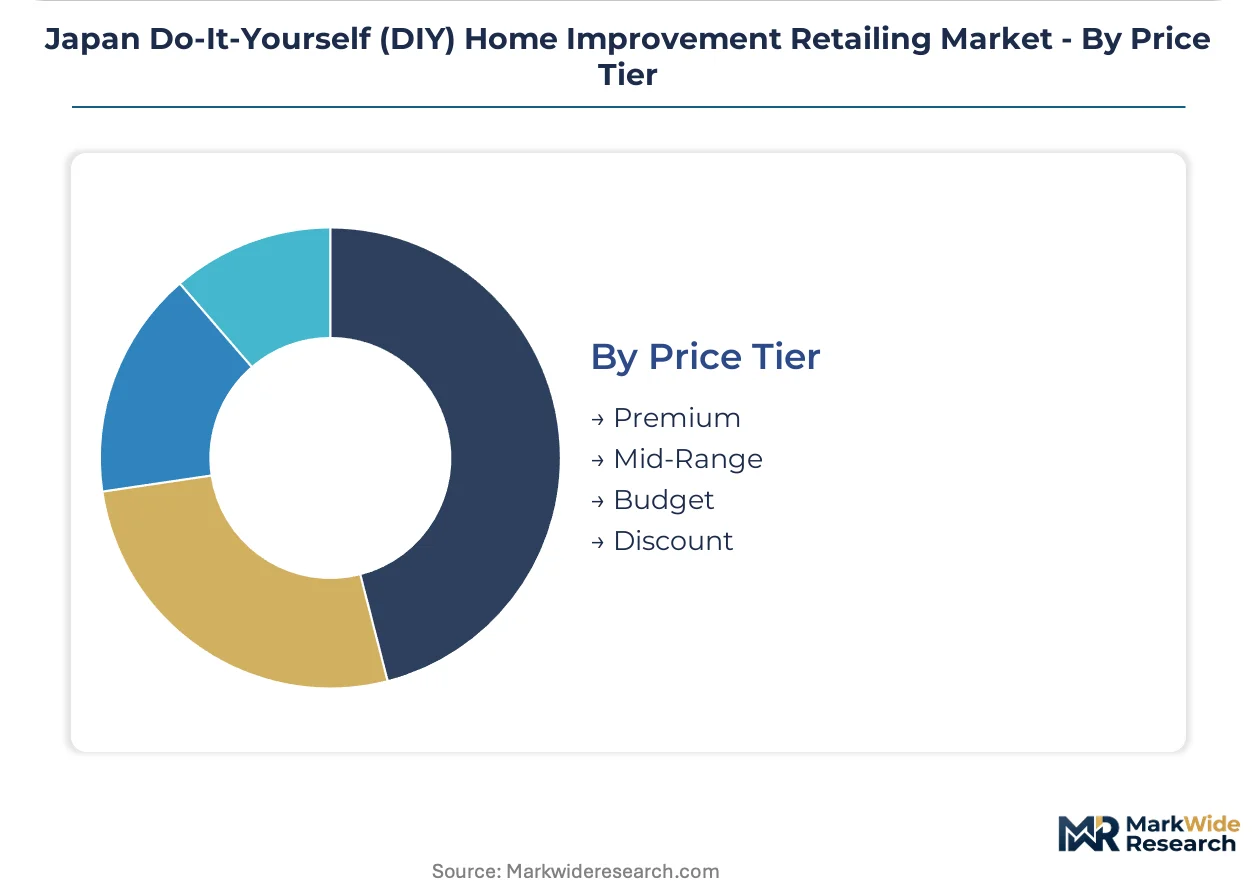
Price Tier:
Margin structure separates certified efficiency products from conventional alternatives under METI and Consumer Affairs Agency compliance costs.
- Premium:Brushless motor platforms, low-VOC certified coatings, and verified U-value insulation systems command higher prices in Tokyo and Osaka renovation markets.
- Mid-Range:Standard lithium-ion tools and conventional thermal insulation serve mainstream homeowner projects in Kanto prefectures.
- Budget:Entry-level hand tools and basic fasteners address price-sensitive maintenance in rural agricultural-adjacent households.
- Discount:Closeout inventory and private-label alternatives capture opportunistic purchasing.
Mid-Range absorbs the bulk of installed capacity; Premium is expanding most quickly under tightening efficiency standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lumber supply chains from Hokkaido and timber processing clusters in Tohoku anchor Japan's building materials distribution network, with finished goods flowing southward through Honshu's coastal logistics corridors to metropolitan demand centers.
Kanto/Tokyo
Tokyo's aging condominium stock drives waterproofing and interior refresh demand among owner-occupiers. METI's 2022 energy efficiency amendments mandate thermal performance disclosures for renovation materials sold across the capital region. Saitama and Chiba prefectures concentrate supercenter distribution hubs that supply the metropolitan renovation market.
Kansai/Osaka
Osaka's commercial property renovation cycle generates trade buyer procurement of structural repair materials. The Consumer Affairs Agency enforces VOC disclosure requirements on coatings distributed through Kansai retail channels. Kyoto and Hyogo prefectures host manufacturing clusters for JIS-certified hand tools serving western Honshu.
Chubu/Nagoya
Nagoya's automotive-adjacent workforce sustains DIY tool demand for residential garage projects and vehicle maintenance. METI ZEB subsidies redirect homeowner spending toward certified insulation products in Aichi and Gifu prefectures. Toyota City anchors a logistics corridor connecting manufacturing supply chains to retail distribution.
Kyushu
Fukuoka's younger homeowner demographic favors online channel penetration for project planning and material quoting. Prefectural retrofit programs in Saga and Kumamoto expand addressable demand for low-VOC coatings and thermal insulation. Kitakyushu maintains port infrastructure for imported lithium cells powering cordless tool platforms.
Hokkaido
Sapporo's harsh climate drives seasonal demand for exterior waterproofing and snow-load structural materials. Limited rural logistics density constrains same-day delivery economics outside the capital region. Asahikawa timber processing clusters supply lumber derivatives to northern Honshu renovation markets.
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-native formats and experiential retail concepts. The vendor base concentrates around three operational models: national supercenter networks, rural-focused localized inventory specialists, and hybrid workshop-service concepts. Three strategic archetypes dominate: scale-driven distribution platforms, regional density specialists, and experiential format innovators. Competitive moves center on geographic whitespace expansion and ERP integration across physical-digital touchpoints.
Among Japan-based retailers, DCM Holdings, Komeri Co.,Ltd., and Joyful Honda Co. Ltd exemplify the three dominant operational archetypes. DCM Holdings anchors the scale-driven tier with national supercenter coverage. Komeri Co.,Ltd. occupies the rural density specialist position. Joyful Honda Co. Ltd represents the experiential format innovation vector. Each sits within a distinct competitive space shaped by trade-area demographics and inventory specialization.
| Leading Market Players |
|---|
| DCM Holdings |
| Alleanza Holdings Co.,Ltd. |
| Komeri Co.,Ltd. |
| Ochi Holdings Co. Ltd |
| Watahan & Co.,Ltd. |
| Joyful Honda Co. Ltd |
| NAFCO Co. Ltd |
| Sunday Co.,Ltd. |
| Kohnan Shoji Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Homeowner concentration in Tokyo and Osaka condominium districts anchors project-based pricing for renovation materials, with bundled installation services commanding premiums over unbundled product sales. METI efficiency certifications and JIS compliance tiers stratify price positioning across battery-powered tool platforms and thermal insulation systems.
Pricing Analysis
Warranty and after-sales service bundling separates premium brushless motor platforms from standard lithium-ion alternatives in Japanese DIY retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under METI energy codes and JIS B 4635 tool standards. Pricing pressure stems from raw material volatility in East Asian lithium cell supply chains. Rural agricultural-adjacent households exhibit highest price sensitivity, while metropolitan DIY enthusiasts absorb premium positioning for cross-compatible battery ecosystems.
Supply Chain Analysis
JIS certification timelines and METI labeling requirements gate supplier qualification, extending new product onboarding to 6-12 months for hand tools and power equipment. Manufacturing concentrates in China, South Korea, and domestic Japanese clusters around Osaka and Nagoya. Lithium cells, brushless motor components, and low-VOC resin feedstocks constitute critical input dependencies. Single-source vulnerability in East Asian battery cell production elevates margin risk. Distribution runs through Honshu supercenter networks and regional wholesale distributors serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's DIY retail landscape is consolidating around captive supply of certified building materials and in-house workshop-service delivery. Players securing upstream control over JIS-compliant tool sourcing and downstream integration of skill-training formats capture structural margin expansion.
For Market Incumbents: Deepen backward integration into certified insulation and low-VOC coating supply chains to defend against direct-to-consumer platform erosion. Expand supercenter workshop footprints in Saitama and Chiba distribution hubs to lock in metropolitan renovation spending. Prioritize ERP synchronization between physical inventory and emerging digital quoting channels.
For New Entrants and Emerging Players: Battery-platform compatibility tools offer a technology-first wedge against entrenched cordless ecosystems. Target Chūgoku and Shikoku prefectures where localized inventory gaps persist for agricultural-adjacent maintenance categories. Deploy pop-up formats to test demand density before fixed-asset commitment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor rural-focused inventory specialists with embedded agricultural customer relationships in Tohoku and Hokkaido. Long-term viability hinges on METI subsidy alignment and ZEB-certified product mix expansion. Monitor prefectural retrofit program enrollment rates as inflection signal for certified efficiency product demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Workshop-Service Hybrid Expansion | Hands-on training formats capture higher-margin project spending from novice renovators in metropolitan prefectures. |
| Backward Integration into Certified Materials | In-house sourcing of METI-compliant insulation secures margin control against volatile supplier pricing. |
| Battery Platform Standardization | Cross-compatible 18V and 40V ecosystems lock in accessory attach rates and compress replacement cycles. |
| Chūgoku and Shikoku Geographic Expansion | Underserved western Honshu prefectures present whitespace for localized inventory models. |
| Digital-Physical ERP Integration | Unified inventory visibility across supercenters and direct-to-consumer platforms reduces stockout-driven revenue leakage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with supercenter category managers, regional wholesale distributors, METI policy officers, and construction contractor procurement leads validated demand assumptions. Japan Customs trade statistics, METI building material efficiency disclosures, and JIS certification databases supplied secondary triangulation. Bottom-up prefectural demand modeling and top-down national retail audit reconciliation ensured cross-verification.
Granularity-level modeling operated at prefecture-by-product tier resolution across tools, paints, hardware, and garden supplies. Customer archetype segmentation captured homeowners, DIY enthusiasts, contractors, and renters with distinct channel preferences and price sensitivity profiles. CAGRs derived from logistic penetration curves for online retail and replacement cycle compression for battery-powered equipment. METI ZEB subsidy trajectories and JIS certification queue lengths informed supply-side constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium cell supply disruption or abrupt METI efficiency standard acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
France Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Germany DIY Home Improvement Market
DIY Home Improvement Products
Sweden DIY Home Improvement Market
DIY Home Improvement Products
Netherlands DIY Home Improvement Market