
 Asia-Pacific Beauty and Personal Care Products Market | 2026-2036
Asia-Pacific Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Beauty and Personal Care Products Market Outlook
Travel-sized bundles and modular skincare kits is broadening consumer trial behavior across the Asia-Pacific region. L'Oréal SA leverages its extensive R&D network in China and Japan to localize active ingredients for humid climates. Amorepacific Group anchors its premium positioning through fermented botanical formulations and dedicated flagship channels in Seoul and Shanghai. Kao Corporation differentiates via polymer science expertise that underpins its haircare and skin-conditioning portfolios.
Asia-Pacific beauty and personal care products encompass topical formulations with specified pH ranges, active concentrations, and dermatological testing protocols designed for cleansing, protection, or aesthetic enhancement of skin, hair, and body surfaces. Manufacturing employs emulsification, fermentation, and encapsulation processes to stabilize bioactive compounds including niacinamide, retinoids, and plant-derived extracts for consumer daily-use regimens. Skincare commands the largest revenue pool given sustained per-capita spending on serums and sun protection in Japan and Australia, while sachet packaging within the haircare segment posts the fastest volume climb among mass-market buyers in Indonesia and Vietnam. The unisex end-user category is gaining shelf space as gender-neutral fragrance and skincare lines expand beyond niche positioning into mainstream supermarket and online retail assortments.
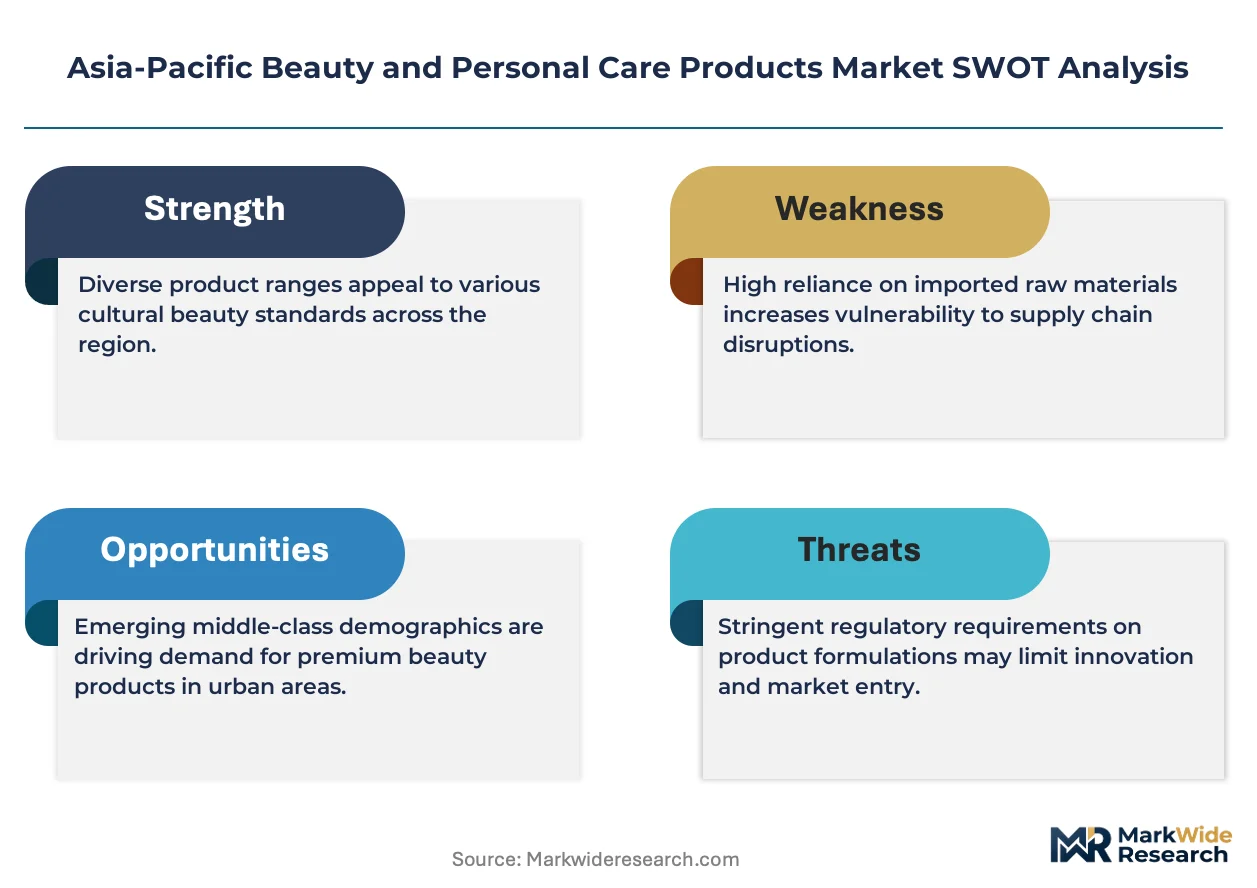
China's NMPA and SAMR enforce pre-market registration and ingredient disclosure rules that determine which formulations enter the world's second-largest cosmetics market. Japan's MHLW and PMDA maintain stringent quasi-drug classifications for whitening and anti-aging claims, creating compliance barriers that favor established players with dedicated regulatory affairs teams. South Korea's MFDS operates a color-code system for functional cosmetics that shapes both domestic innovation and export credibility across Southeast Asia. Stakeholders must weigh regulatory lag times against formulation pipeline investments when sequencing market entry across multiple Asia-Pacific jurisdictions.
Market Dynamics
China's tightening GB standards for cosmetic ingredient disclosure and safety testing are forcing multinational formulators to restructure regional R&D and compliance operations around pre-market registration timelines.
Growth Catalysts
- Fermentation biotechnology:South Korean biotech platforms enable novel active delivery systems that command premium shelf positioning across Southeast Asian duty-free channels.
- Sachet packaging innovation:Indonesia and Vietnam's urban mass-market buyers drive volume expansion through single-use formats that lower trial barriers for price-sensitive demographics.
- NMPA registration harmonization:China's streamlined pre-market pathways for imported functional cosmetics accelerate cross-border brand entry from Japan and South Korea.
Market Restraints
- Palm oil derivative volatility:Surfactant and emollient input costs fluctuate with Malaysian and Indonesian commodity board pricing, compressing mass-market margin structures.
- Quasi-drug classification barriers:Japan's MHLW whitening and anti-aging claim requirements extend product development cycles by 18-24 months for non-established entrants.
- Water-stressed formulation constraints:India's groundwater extraction regulations in manufacturing clusters limit production scaling for rinse-off categories.
Strategic Opportunities
- Philippines secondary cities:Cebu and Davao retail infrastructure gaps present first-mover positioning for localized sachet distribution networks.
- Gender-neutral fragrance expansion:Australia's clean beauty retailers are carving dedicated shelf space for unisex SKUs previously confined to niche e-commerce.
- Biodegradable polymer mandates:Thailand's MEE packaging regulations create preferential procurement channels for brands with certified compostable sachet materials.
Industry Challenges
- Regulatory affairs talent scarcity:China's NMPA and South Korea's MFDS parallel filing requirements demand bilingual specialists with dual-jurisdiction experience that outstrips supply.
- Legacy ERP integration:Japanese and Australian parent companies face system fragmentation when consolidating batch-level traceability data across Southeast Asian contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Beauty and Personal Care Products Market |
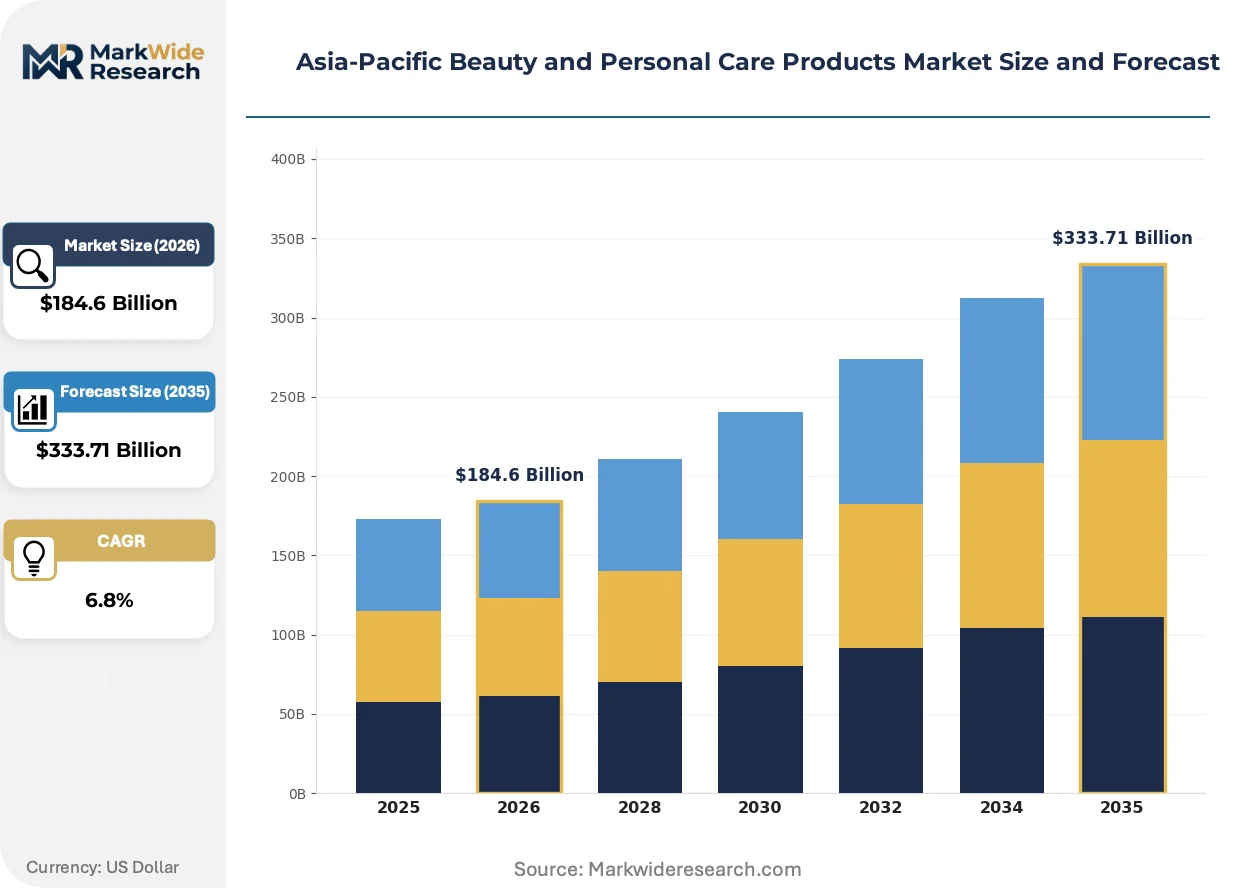
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $333.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance End User: Women, Men, Children, Unisex Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Packaging Type: Tubes, Bottles, Jars, Sachets |
| Companies Covered | The Estée Lauder Companies Inc., Amorepacific Group, L'Oréal SA, Beiersdorf AG, The Procter & Gamble Company, Shiseido Co., Ltd., Kao Corporation, LG Household & Health Care Ltd., Unilever PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Beauty and Personal Care Products Market Strategic Shifts
Biotechnology-derived actives and climate-adaptive formulations are displacing conventional synthetic chemistry in premium positioning strategies across humid Asian markets.
Encapsulation technology for niacinamide and retinoid stabilization is consolidating formulation R&D priorities as Japanese and South Korean labs compete for humidity-resistant delivery patents. Amorepacific and Kao licensing teams are filing cross-border to secure regional exclusivity on polymer-shell technologies. This intellectual property concentration is compressing independent brand access to proven active stability platforms.
China's GB standards for cosmetic safety are tightening ingredient disclosure thresholds that exceed legacy ASEAN harmonization frameworks. Formulators must now submit complete supply chain documentation for preservatives and UV filters before NMPA clearance. Premium brands with captive testing facilities in Shanghai and Guangzhou are absorbing compliance costs faster than import-reliant competitors.
Urban Indian and Indonesian buyers are compressing purchase cycles for trial-sized skincare through quick-commerce platforms that bypass traditional modern trade distribution. Blinkit and Zepto in India, alongside GrabMart in Indonesia, are capturing serum and sunscreen volume previously routed through Watsons and Guardian. This channel rotation is most visible in Mumbai, Bangalore, Jakarta, and Surabaya where 30-minute delivery promises override brand loyalty.
Asia-Pacific Beauty and Personal Care Products Market Segmentation
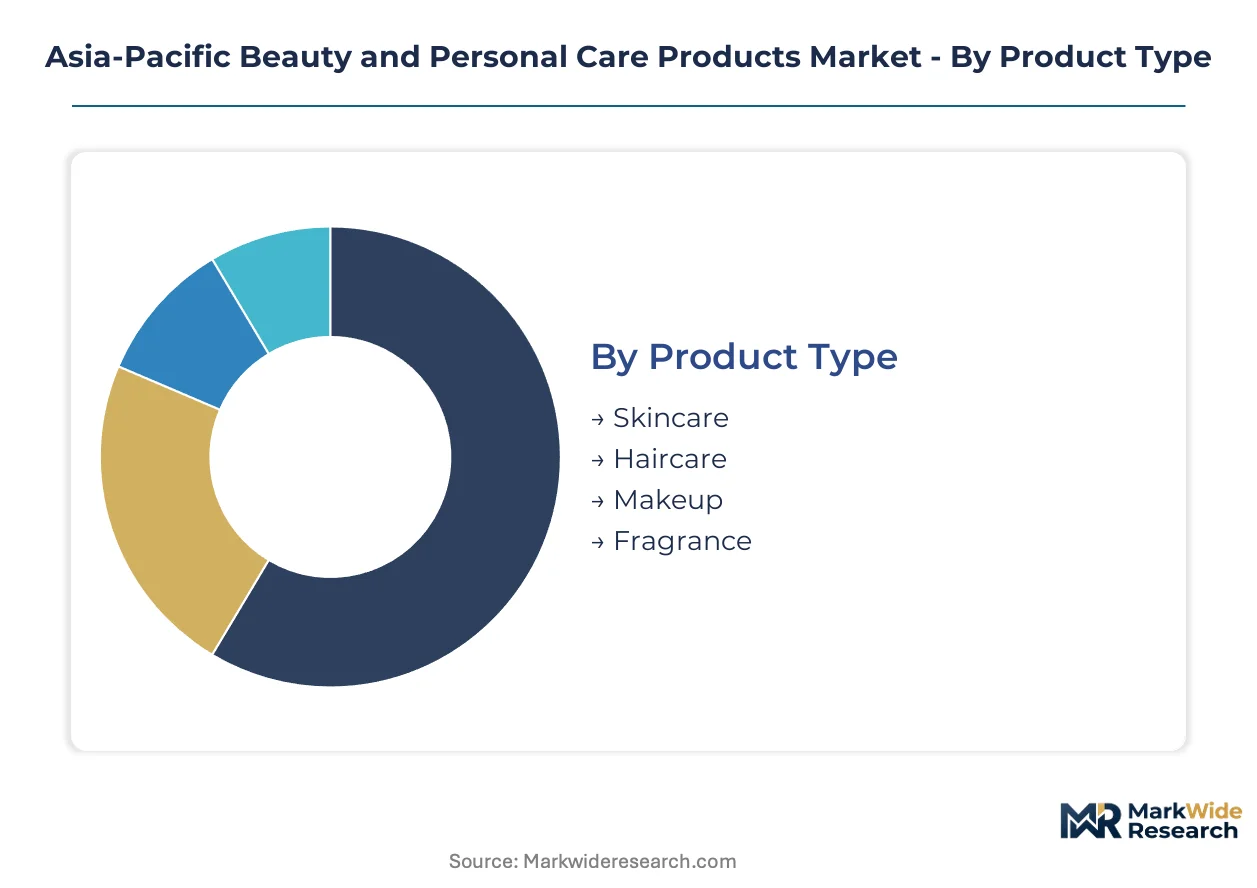
Segmentation in the Asia-Pacific beauty and personal care products market reveals how consumer upgrade cycles vary dramatically across product categories and distribution channels. Understanding these replacement patterns allows manufacturers to align R&D pipelines with the renewal frequencies that drive recurring revenue in humid tropical climates versus temperate urban centers.
Product Type:
Upgrade cycles in Asia-Pacific beauty and personal care products range from rapid replenishment for daily-use rinse-off items to extended replacement timelines for color cosmetics with slower consumption rates.
- Skincare:Formulations with specified pH ranges and active concentrations including niacinamide and retinoids dominate per-capita spending in Japan and Australia. Serum and sun protection SKUs command premium shelf positioning through dedicated flagship channels in Seoul and Shanghai, where consumers replace core products every 4-6 weeks.
- Haircare:Polymer science expertise underpins conditioning portfolios that respond to humidity-resistant delivery demands across Southeast Asian duty-free channels. Sachet packaging within this segment posts the steepest expansion trajectory among mass-market buyers in Indonesia and Vietnam, driven by single-use trial formats that lower entry barriers for price-sensitive urban demographics.
- Makeup:Color cosmetics with slower consumption cycles concentrate demand in China's tier-one cities where NMPA registration requirements filter import access.
- Fragrance:Gender-neutral lines expand beyond niche positioning into mainstream supermarket and online retail assortments across Australian clean beauty retailers.
Volume placements concentrate in Skincare; the faster expansion belongs to Haircare.
End User:
Cost tier differentiation shapes formulation complexity and channel strategy across demographic segments in the Asia-Pacific region.
- Women:Multifunctional skincare routines drive the largest revenue pool, with millennial and Gen Z consumers in South Korea demanding fermented botanical formulations that anchor premium positioning.
- Unisex:Gender-neutral fragrance and skincare lines gain dedicated shelf space as clean beauty retailers in Australia carve space for SKUs previously confined to niche e-commerce, expanding most quickly among end-user categories.
- Men:Specialized grooming products concentrate demand in China's urban centers where SAMR disclosure rules apply equally across gendered marketing claims.
- Children:Mild formulation requirements with dermatological testing protocols limit active ingredient concentrations, compressing margin structures for manufacturers serving this segment.
Revenue concentration sits with Women; Unisex segments are climbing the fastest as gender-neutral positioning mainstreams.
Distribution Channel:
Application-specific channel strategies determine how formulation stability requirements align with last-mile delivery speeds across Asia-Pacific urban markets.
- Online Retail:Quick-commerce platforms including Blinkit, Zepto, and GrabMart capture serum and sunscreen volume previously routed through Watsons and Guardian, with 30-minute delivery promises overriding brand loyalty in Mumbai, Bangalore, Jakarta, and Surabaya.
- Specialty Stores:Dedicated flagship channels in Seoul and Shanghai enable premium positioning through immersive brand experiences that justify fermented botanical price premiums.
- Supermarkets:Mass-market assortments concentrate sachet distribution for price-sensitive buyers in India's secondary cities and Southeast Asian urban centers.
- Pharmacies:Quasi-drug classification requirements in Japan extend product development cycles for whitening and anti-aging claims, favoring established players with dedicated regulatory affairs teams.
Transaction velocity peaks in Online Retail; Specialty Stores maintain the highest margin per unit.
Packaging Type:
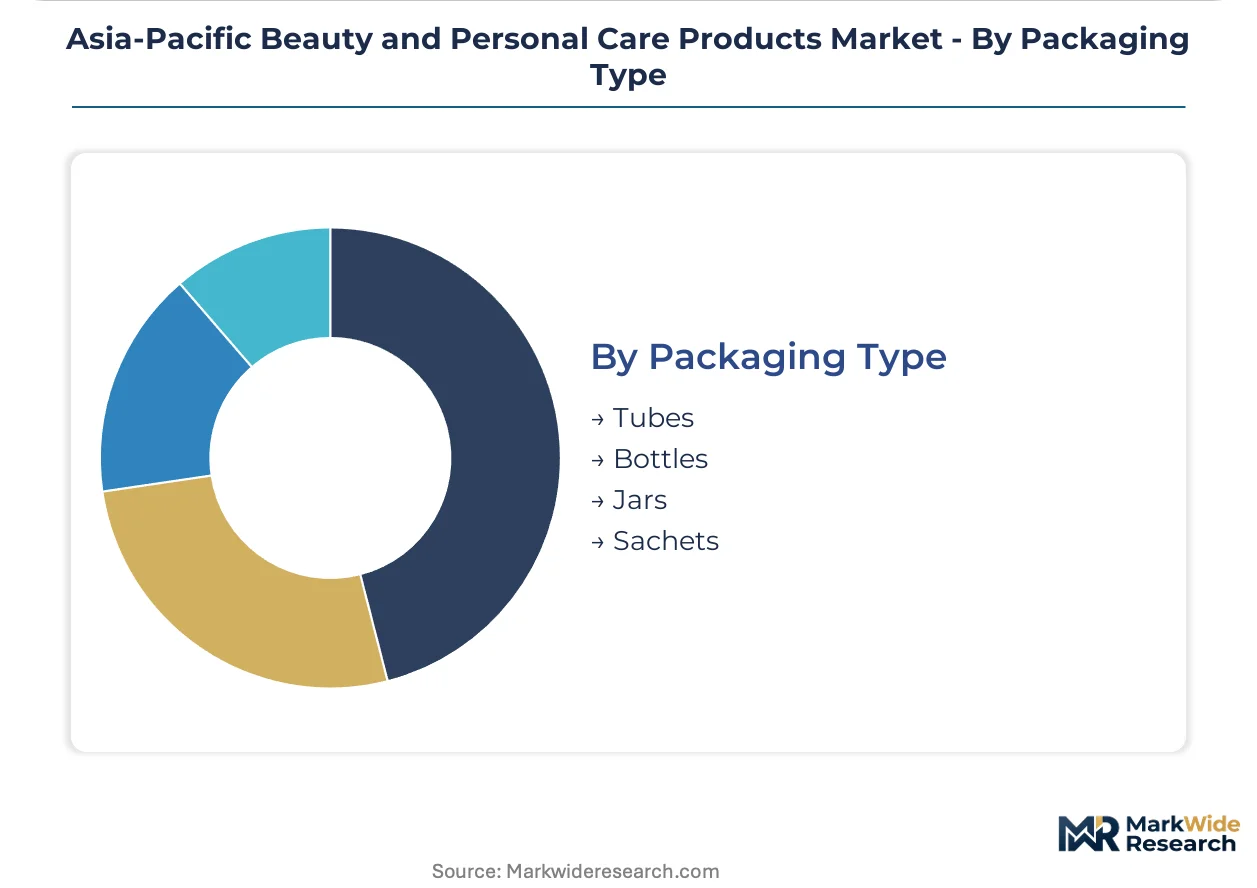
Supply concentration in polymer and biodegradable material sourcing determines which formats capture regulatory preference across Asia-Pacific manufacturing clusters.
- Sachets:Single-use formats with certified compostable materials gain preferential procurement channels under Thailand's MEE packaging regulations, while Indonesia and Vietnam's urban mass-market buyers drive volume expansion through lowered trial barriers.
- Tubes:Laminate structures with barrier properties suit emulsion stability for humid climate distribution, concentrating production in Malaysian and Thai manufacturing clusters.
- Bottles:Rigid PET and glass formats dominate serum and fragrance categories where premium perception justifies higher material costs.
- Jars:Wide-mouth containers concentrate in skincare categories requiring finger-dispensed application, though water-stressed formulation constraints in India's manufacturing clusters limit production scaling for rinse-off categories in this format.
Unit economics favor Sachets in mass-market penetration; Jars retain premium positioning despite slower volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation output concentrates in South Korea and Japan while consumption volume spreads across Southeast Asian urban centers. China's regulatory gatekeeping reshapes which products reach secondary markets.
China
NMPA pre-market registration requirements filter import access for whitening and anti-aging claims. GB standards for cosmetic safety tighten ingredient disclosure thresholds beyond legacy ASEAN frameworks. Shanghai and Guangzhou host captive testing facilities where premium brands absorb compliance costs faster than import-reliant competitors.
South Korea
Millennial and Gen Z consumers drive demand for multifunctional skincare routines with fermented botanical formulations. MFDS operates a color-code system for functional cosmetics that shapes export credibility across Southeast Asia. Seoul anchors premium positioning through dedicated flagship channels that justify price premiums for biotech-derived actives.
Japan
Quasi-drug classification requirements for whitening and anti-aging claims extend product development cycles by 18-24 months. MHLW and PMDA standards favor established players with dedicated regulatory affairs teams. Osaka and Nagoya manufacturing clusters concentrate polymer science expertise for humidity-resistant delivery systems.
India
Quick-commerce platforms capture serum and sunscreen volume previously routed through Watsons and Guardian in Mumbai and Bangalore. BIS standards intersect with state-level groundwater extraction regulations that limit production scaling for rinse-off categories. Secondary cities present first-mover positioning for localized sachet distribution networks.
Indonesia
Urban mass-market buyers drive volume expansion through single-use sachet formats that lower trial barriers. National standards for cosmetic safety operate alongside emerging biodegradable packaging mandates. Jakarta and Surabaya retail infrastructure supports 30-minute delivery promises that override brand loyalty for sunscreen and haircare SKUs.
Asia-Pacific Beauty and Personal Care Products Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base clusters around three strategic archetypes: multinational CPG giants with captive R&D networks, regional champions leveraging fermentation biotechnology, and independent brands accessing contract manufacturing. Competitive moves concentrate on NMPA registration harmonization and sachet packaging innovation for Southeast Asian quick-commerce channels.
Within the fermentation biotechnology tier, Amorepacific Group and Kao Corporation exemplify science-driven positioning. L'Oréal SA represents diversified scale advantages through localized active ingredient development. These three entities occupy positions that illustrate how R&D concentration and regulatory expertise create defensive moats in China's pre-market clearance environment.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc. |
| Amorepacific Group |
| L'Oréal SA |
| Beiersdorf AG |
| The Procter & Gamble Company |
| Shiseido Co., Ltd. |
| Kao Corporation |
| LG Household & Health Care Ltd. |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Palm oil derivative costs transmit downstream through surfactant and emollient formulations, compressing mass-market margin structures in Indonesia and Vietnam while premium tiers in Seoul and Shanghai absorb volatility through captive R&D networks. Malaysian and Indonesian commodity board pricing fluctuations force sachet manufacturers to recalibrate unit economics quarterly.
Pricing Analysis
Margin tightening in mass-market haircare reflects palm oil derivative volatility and quick-commerce platform commission structures. Three-tier pricing structure across premium, standard, and economy levels separates fermented botanical SKUs in flagship channels from polymer-science conditioners in modern trade and single-use sachets in traditional retail. Price differentiation hinges on certification grade under Thailand's MEE packaging regulations and brand heritage in South Korea's duty-free corridors. Urban Indian buyers through Blinkit and Zepto exhibit highest price sensitivity; Japanese quasi-drug positioning commands lowest.
Supply Chain Analysis
Returns of expired sachet inventory flow through informal collection networks in Jakarta and Surabaya, diverting biodegradable materials from certified composting facilities. Manufacturing concentrates in South Korea, Japan, and China's Guangdong province for fermentation biotechnology and polymer encapsulation. Formulation inputs draw from Malaysian palm oil derivatives, Chinese niacinamide feedstocks, and Australian botanical extracts. Single-source vulnerability clusters around Indonesian sachet converting capacity. Distribution runs through quick-commerce platforms, specialty flagship channels, and supermarket mass-market tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's NMPA pre-market registration requirements erect a cost-of-compliance barrier that favors established players with Shanghai and Guangzhou testing facilities, filtering import-reliant competitors from functional cosmetics positioning.
For Market Incumbents: Cement regulatory affairs capabilities through bilingual NMPA-MFDS filing specialists in Seoul and Shanghai. Deepen backward integration into fermentation biotechnology platforms to secure humidity-resistant delivery patents before Kao Corporation and Amorepacific Group consolidate regional exclusivity. Absorb compliance costs faster than import-reliant challengers facing 18-24 month quasi-drug cycles in Japan. For New Entrants and Emerging Players: Enter via biodegradable sachet formats under Thailand's MEE preferential procurement channels, bypassing saturated premium serum positioning. Target Cebu and Davao retail infrastructure gaps with localized distribution networks ahead of multinational modern trade expansion. Leverage GrabMart and Blinkit quick-commerce velocity to override incumbent brand loyalty in Jakarta, Surabaya, Mumbai, and Bangalore. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap contract manufacturers with captive testing facilities in China's coastal clusters as NMPA registration timelines stretch competitor cash reserves. Monitor NMPA filing queue lengths as inflection indicator for regulatory capacity constraints. Long-term viability hinges on dual-jurisdiction compliance expertise spanning China's SAMR disclosure rules and South Korea's MFDS color-code system.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Biotechnology Patent Filing | Secures regional exclusivity on humidity-resistant active delivery systems against Kao and Amorepacific licensing teams. |
| NMPA Registration Harmonization | Accelerates cross-border entry from Japan and South Korea through streamlined pre-market pathways for functional cosmetics. |
| Biodegradable Sachet Certification | Unlocks preferential procurement under Thailand's MEE packaging regulations for compostable materials. |
| Quick-Commerce Platform Integration | Captures serum and sunscreen volume in Mumbai, Bangalore, Jakarta, and Surabaya through 30-minute delivery promises. |
| Dual-Jurisdiction Regulatory Talent Acquisition | Addresses scarce bilingual specialists with NMPA and MFDS parallel filing experience across China and South Korea. |
Study Parameters
Document review covered NMPA registration filings, MFDS color-code functional cosmetics databases, and ASEAN harmonization frameworks, complemented by interviews with regulatory affairs directors at multinational CPG headquarters, fermentation biotechnology R&D leads in Seoul and Osaka, quick-commerce category managers at Blinkit and GrabMart, and sachet converting plant managers in Jakarta and Surabaya. Secondary validation drew from customs trade data on palm oil derivative flows, BIS standards documentation, and MEE packaging regulation drafts. Bottom-up unit economics on sachet manufacturing triangulated against top-down market sizing across the analysis window.
Segmentation outputs modeled product type tiers, end-user demographic splits, distribution channel velocity, and packaging format regulatory compliance across the projection horizon. CAGRs derived from replacement cycle frequencies in humid tropical versus temperate urban climates, cross-referenced with per-capita serum and sunscreen spending patterns. Forecast inputs incorporated NMPA registration queue lengths, groundwater extraction regulation enforcement in Indian manufacturing clusters, and quick-commerce penetration rates in secondary Southeast Asian cities.
Revisions become necessary when China's GB standards tighten ingredient disclosure thresholds beyond current NMPA pathways, when Malaysian and Indonesian palm oil boards impose export restrictions, or when Thailand's MEE mandates accelerate biodegradable material conversion timelines. Practitioners should monitor NMPA filing approval velocities, quick-commerce commission structure changes, and fermentation biotechnology patent grant rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market