
 Public Cloud Business Process Services Market | 2026-2036
Public Cloud Business Process Services Market Size, Share, and Industry Trends Forecast 2026-2036
Public Cloud Business Process Services Market Intelligence
Enterprise procurement channels for cloud business process services is narrowing as direct vendor relationships replace traditional systems integrator intermediaries. Amazon Web Services dominates infrastructure provisioning for mission-critical workloads across Fortune 500 accounts. Microsoft Corporation leverages its Office 365 and Dynamics ecosystem to anchor bundled process automation contracts. IBM Corporation specializes in regulated industry verticals where hybrid cloud orchestration meets legacy system modernization.
Public Cloud Business Process Services encompass the outsourcing of standardized business functions—finance operations, customer support workflows, human capital management, and supply chain coordination—to third-party providers operating on shared cloud infrastructure, typically delivered through multi-tenant SaaS architectures with API-driven integration to client ERP systems. These services eliminate capital expenditure on proprietary data centers while enabling elastic scaling of transaction volumes during seasonal demand peaks. Finance & Accounting and Customer Interaction Management segments lead current revenue contribution due to their quantifiable ROI metrics and mature automation toolchains. Procurement & Supply Chain and Data Analytics offerings represent the fastest-expanding categories as enterprises seek real-time visibility across distributed supplier networks. Risk & Compliance services command premium pricing structures driven by mandatory audit trails and cross-border data residency requirements.
GDPR enforcement by European data protection authorities and the EU AI Act's risk-classification framework are reshaping vendor qualification criteria for cross-border process outsourcing. In the United States, SEC cybersecurity disclosure rules and HIPAA safeguards for healthcare business associates constrain cloud architecture choices and drive demand for sovereign cloud deployments. Stakeholders must evaluate provider certifications against evolving jurisdictional requirements before committing to long-term process migration contracts.
Market Dynamics
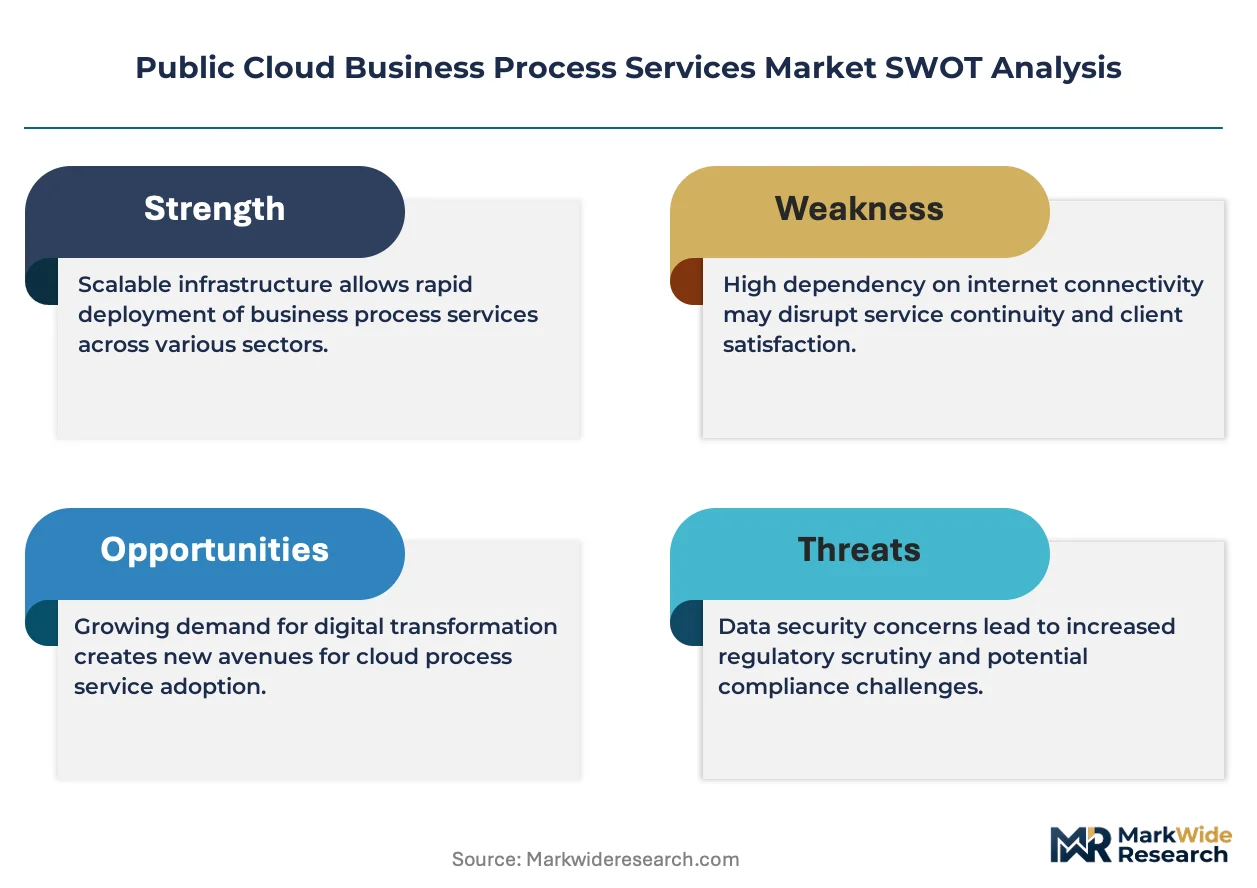
Enterprise migration from on-premise ERP to API-orchestrated cloud platforms is compressing procurement cycles and forcing incumbent providers to reprice legacy outsourcing contracts. This structural shift toward multi-tenant SaaS architectures is eliminating capital-intensive data center commitments while creating winner-take-most dynamics among hyperscale infrastructure operators.
Growth Catalysts
- Federal cloud mandates:United States government procurement directives now require civilian agencies to default to commercial cloud for non-classified business process workloads, accelerating vendor certification pipelines and sovereign cloud investments.
- GDPR Article 28 processor agreements:European enterprises facing data protection authority enforcement are outsourcing compliance-heavy functions to certified cloud providers with pre-audited subprocessors, reducing internal legal overhead.
- Generative AI orchestration layers:Large language model integration into customer interaction and finance workflows is virtualizing document processing and first-line support, creating measurable efficiency gains that justify contract renewals.
Market Restraints
- Cross-border data residency:Schrems II rulings and emerging national data localization laws in India and China fragment cloud architecture choices, forcing redundant infrastructure deployments that inflate total cost of ownership.
- Hyperscale supply concentration:Three infrastructure providers control mission-critical compute and storage provisioning, creating single-source vulnerability for enterprise business continuity planning.
- Legacy system integration debt:Mainframe-based core banking and insurance policy administration systems resist API abstraction, extending migration timelines and preserving hybrid complexity.
Strategic Opportunities
- EU AI Act compliance services:Risk-classification frameworks for automated decision-making create premium advisory and technical implementation revenue streams for providers with pre-certified governance toolchains.
- Industry-specific sovereign clouds:Germany, France, and Saudi Arabia are mandating in-country data processing for financial services and healthcare, opening localized infrastructure partnerships with domestic telecom operators.
- Edge-to-cloud orchestration:Convergence of 5G network slicing with containerized microservices enables real-time supply chain visibility applications that bypass centralized latency constraints.
Industry Challenges
- Certified cloud architect scarcity:Multi-cloud security and FinOps skill sets command 40-60% salary premiums, constraining provider scaling and inflating service delivery costs.
- API versioning complexity:Continuous deployment pipelines for ERP connectors break downstream integrations, forcing expensive regression testing cycles and client-specific customization backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Cloud Business Process Services Market |
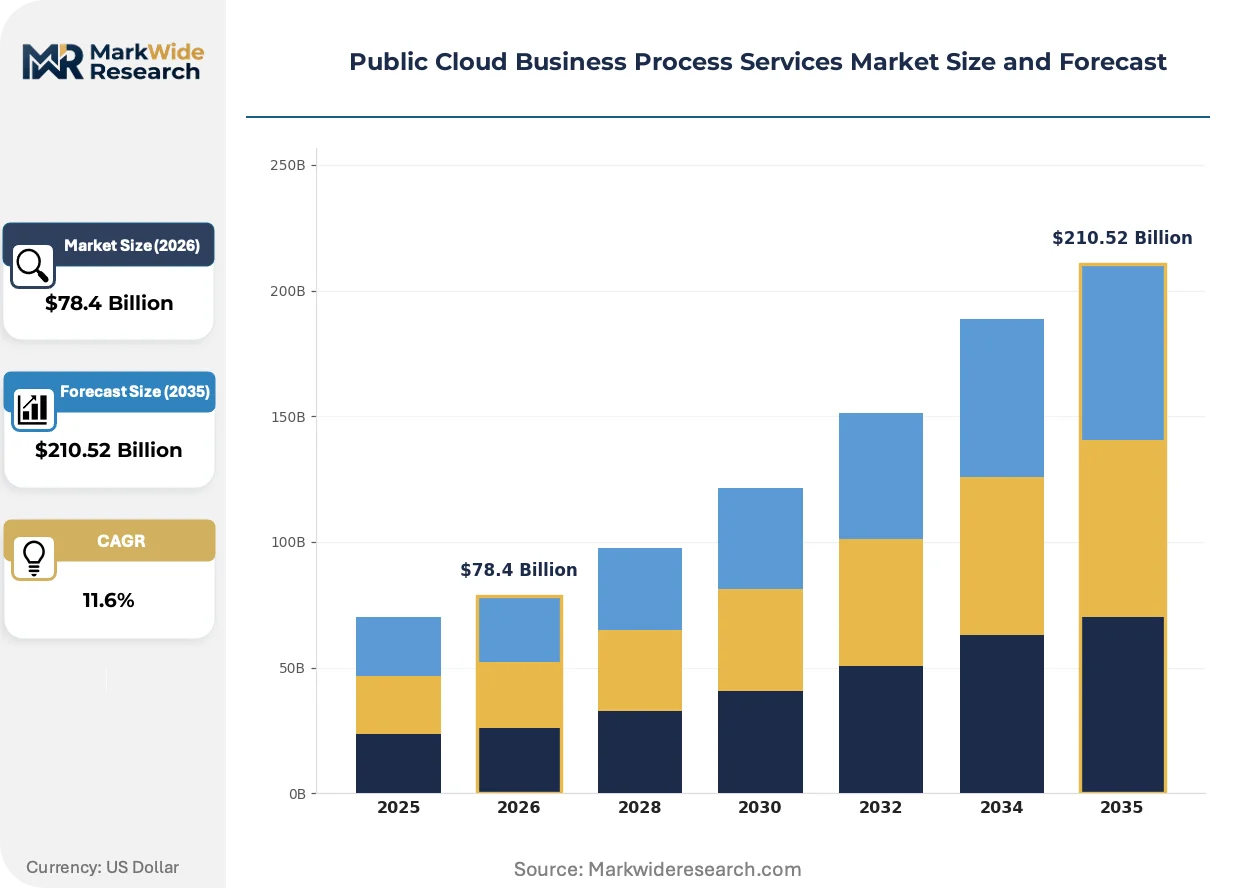
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $210.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Finance & Accounting, Customer Interaction Management, Human Resource Management, Procurement & Supply Chain, Data Analytics, Risk & Compliance Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Industry Vertical: BFSI, Telecommunications, Manufacturing, Energy, Government, Education Client Size: Small Enterprises, Medium Enterprises, Large Enterprises, Multinational Corporations |
| Companies Covered | Amazon Web Services, Microsoft Corporation, IBM Corporation, Google, Accenture, Deloitte, PwC, EY, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Cloud Business Process Services Market Strategic Shifts & Innovations
Containerization and serverless execution models are collapsing the distinction between infrastructure and application layers, enabling granular consumption billing that aligns vendor revenue with actual transaction volumes rather than provisioned capacity.
Agentic AI workflow engines are virtualizing exception handling and approval routing in finance operations, allowing mid-market enterprises to access automation capabilities previously reserved for Fortune 500 implementations with dedicated robotics teams. Early adopters in commercial banking and insurance claims processing report 30-50% reduction in manual touchpoints, though hallucination risk requires human-in-the-loop governance frameworks that partially offset labor savings.
CSRD sustainability disclosure requirements in Europe are mandating granular carbon accounting for cloud workloads, pushing providers to publish location-specific emissions data and offer renewable energy matching certificates. Financial services institutions with Scope 3 reporting obligations are now weighting provider selection toward hyperscalers with verified 24/7 carbon-free energy matching in specific grid regions, particularly Ireland, Sweden, and Spain where wind and hydro resources concentrate.
Enterprise buyers are consolidating vendor relationships around integrated platform ecosystems rather than best-of-breed point solutions, trading functional specialization for reduced integration overhead and unified security posture management. This concentration dynamic favors providers with pre-built connectors to SAP, Oracle, and Workday environments, particularly in manufacturing and healthcare verticals where ERP heterogeneity previously supported multi-vendor strategies. German automotive suppliers and US hospital systems exemplify this shift, with procurement teams now prioritizing ecosystem breadth over feature depth in RFP evaluations.
Public Cloud Business Process Services Market Segmentation
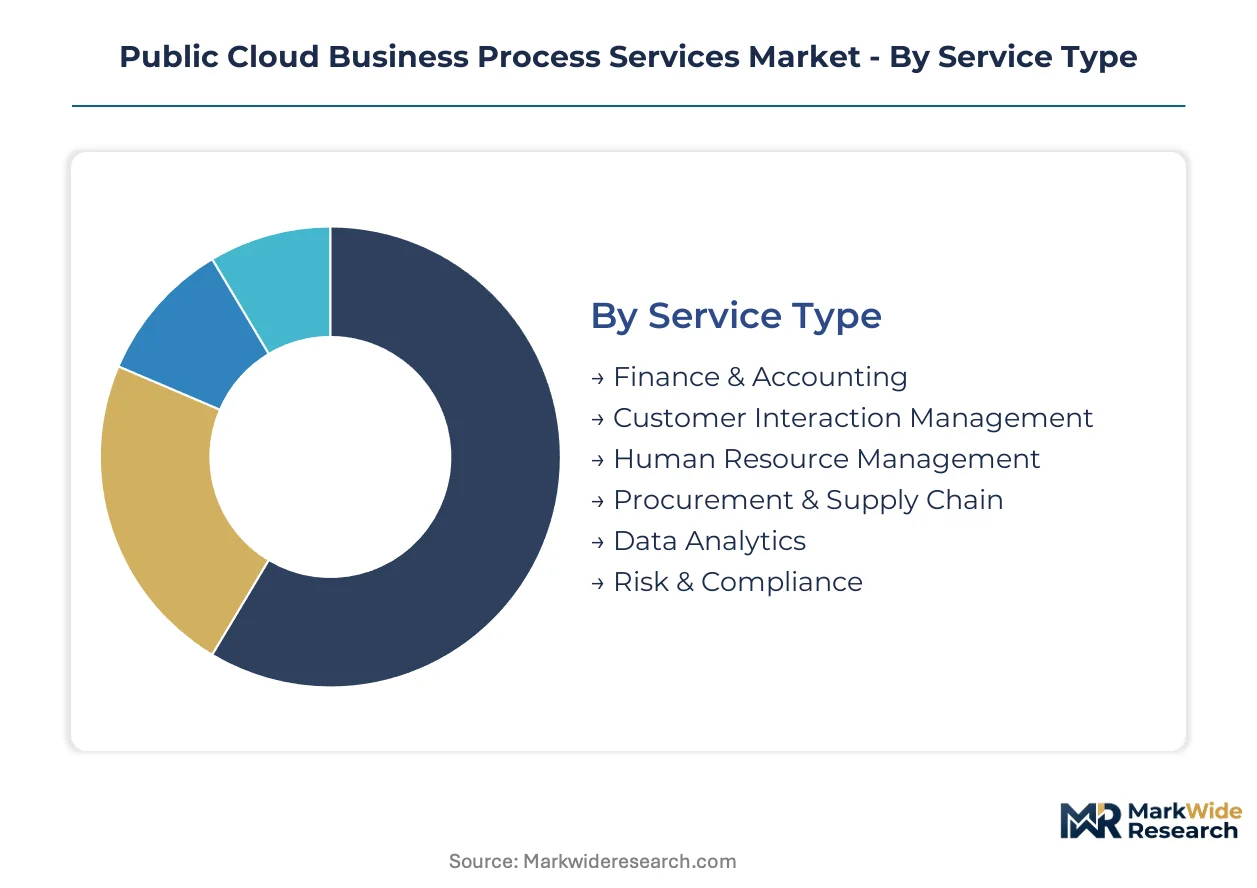
Segmentation in Public Cloud Business Process Services reveals divergent procurement rhythms and margin profiles across service categories, deployment architectures, and client tiers. Understanding these structural differences enables vendors to calibrate sales cycles, implementation methodologies, and pricing frameworks to specific buyer contexts.
Service Type:
Finance & Accounting and Customer Interaction Management command the shortest sales cycles due to quantifiable ROI metrics and mature automation toolchains, while Risk & Compliance extends procurement timelines through mandatory audit trail verification and cross-border data residency negotiations.
- Finance & Accounting:Multi-tenant SaaS platforms automate accounts payable, receivable, and general ledger reconciliation through API-driven ERP integration. US financial services institutions drive concentrated demand as SEC cybersecurity disclosure rules mandate granular transaction logging and immutable audit trails.
- Customer Interaction Management:Omnichannel contact center platforms with embedded generative AI orchestration virtualize first-line support and sentiment analysis. European enterprises under GDPR Article 28 processor agreements prioritize certified providers with pre-audited subprocessors to reduce internal legal overhead.
- Human Resource Management:Cloud-native talent acquisition and payroll platforms with localized tax engine configurations.
- Procurement & Supply Chain:Real-time supplier visibility applications leveraging 5G network slicing and containerized microservices.
- Data Analytics:Consumption-billed data lakehouse architectures enabling granular billing aligned with actual query volumes rather than provisioned capacity.
- Risk & Compliance:Sovereign cloud deployments with EU AI Act risk-classification frameworks for automated decision-making governance.
Finance & Accounting anchors the volume base while Procurement & Supply Chain gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates hyperscale public infrastructure from premium-priced sovereign and community alternatives, with hybrid architectures occupying the mid-market optimization zone.
- Public Cloud:Shared multi-tenant infrastructure with elastic scaling of compute and storage resources eliminates capital expenditure on proprietary data centers. US federal cloud mandates accelerate civilian agency procurement of non-classified business process workloads through pre-certified vendor pipelines.
- Private Cloud:Single-tenant dedicated environments with customizable security postures for classified or mission-critical workloads. German automotive suppliers and financial institutions mandate in-country data processing under national banking directives.
- Hybrid Cloud:Orchestrated workload portability between on-premise legacy systems and cloud-native platforms. Mainframe-based core banking systems resist API abstraction, extending migration timelines and preserving hybrid complexity.
- Community Cloud:Sector-specific shared infrastructure for healthcare, defense, or energy verticals with common compliance requirements.
Public Cloud dominates transaction volume while Community Cloud climbs the fastest as sector-specific sovereign mandates proliferate.
Industry Vertical:
Application intensity varies sharply, with BFSI and Telecommunications driving API-orchestrated platform adoption while Government and Education lag due to extended procurement cycles and legacy system integration debt.
- BFSI:Core banking, insurance policy administration, and wealth management platforms migrating from mainframe to cloud-native architectures. HIPAA safeguards for healthcare business associates constrain architecture choices and drive demand for sovereign cloud deployments in the United States.
- Telecommunications:Customer billing, network operations, and 5G service orchestration with real-time latency requirements.
- Manufacturing:ERP-integrated supply chain coordination with SAP and Oracle connector ecosystems.
- Energy:Asset management and regulatory reporting with CSRD sustainability disclosure requirements mandating granular carbon accounting.
- Government:Citizen service portals and back-office modernization under federal procurement directives.
- Education:Student information systems and research administration with FERPA privacy constraints.
BFSI anchors the volume base while Energy expands most quickly under sustainability reporting mandates.
Client Size:
Customer type determines contract structure complexity, with Multinational Corporations demanding bespoke multi-region deployments and Small Enterprises accepting standardized SaaS configurations.
- Large Enterprises:Integrated platform ecosystems with unified security posture management and pre-built connectors to SAP, Oracle, and Workday environments. US hospital systems prioritize ecosystem breadth over feature depth in RFP evaluations to reduce integration overhead.
- Multinational Corporations:Multi-region sovereign cloud deployments with redundant infrastructure across India, China, and EU jurisdictions to satisfy data localization laws.
- Medium Enterprises:Agentic AI workflow engines virtualizing exception handling previously reserved for Fortune 500 implementations.
- Small Enterprises:Standardized SaaS configurations with rapid deployment templates and minimal customization.
Large Enterprises anchor the volume base while Medium Enterprises gain share at the steepest rate as AI-orchestrated automation democratizes enterprise-grade capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States providers extract 35-40% pricing premiums over Indian counterparts for equivalent finance automation workloads, reflecting compliance certification scarcity and sovereign cloud infrastructure costs. European buyers under GDPR Article 28 processor agreements absorb additional 15-20% overhead for pre-audited subprocessor chains. This asymmetry concentrates procurement decisions in jurisdictions with regulatory clarity.
United States
Federal cloud mandates and SEC cybersecurity disclosure rules drive civilian agency migration to commercial platforms. HIPAA safeguards for healthcare business associates constrain architecture choices toward sovereign deployments. Dallas-Fort Worth and Northern Virginia host concentrated hyperscale data center clusters serving Fortune 500 finance automation contracts.
Germany
Automotive suppliers and financial institutions mandate in-country data processing under national banking directives. CSRD sustainability disclosure requirements weight provider selection toward verified carbon-free energy matching. Munich and Frankfurt anchor sovereign cloud infrastructure partnerships between domestic telecom operators and global platforms.
United Kingdom
Post-Brexit data adequacy negotiations with the EU reshape cross-border processor agreement structures. Financial services institutions in the City of London prioritize pre-certified governance toolchains for automated decision-making workflows. London and Edinburgh concentrate advisory services supporting EU AI Act compliance implementation.
India
Emerging data localization requirements fragment cloud architecture choices for multinational back-office operations. RBI guidelines on data storage for financial services accelerate domestic sovereign cloud investments. Bangalore and Hyderabad host delivery centers supporting global finance and accounting process outsourcing at compressed cost structures.
France
CNIL enforcement actions against inadequate processor agreements elevate vendor qualification barriers. ANSM pharmaceutical traceability requirements extend cloud migration timelines through mandatory audit trail verification. Paris and Lyon anchor industry-specific community cloud deployments for healthcare and defense verticals.
Public Cloud Business Process Services Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in API connectivity and compliance tooling. The vendor base stratifies across three tiers: hyperscale infrastructure operators with bundled SaaS ecosystems, professional services firms with vertical process expertise, and niche automation vendors with industry-specific connectors. Strategic archetypes include ecosystem bundlers anchoring unified security posture management, compliance-first specialists targeting regulated verticals, and AI-orchestration layer providers virtualizing exception handling. Dominant competitive moves encompass geographic expansion through sovereign cloud partnerships and portfolio diversification into adjacent risk-classification advisory services.
Within the hyperscale infrastructure tier, Amazon Web Services, Microsoft Corporation, and IBM Corporation occupy positions reflecting distinct competitive vectors. Amazon Web Services anchors mission-critical workload provisioning across Fortune 500 accounts. Microsoft Corporation leverages its productivity ecosystem to capture bundled process automation contracts. IBM Corporation exemplifies the regulated-industry specialist archetype, with its positioning reflecting hybrid cloud orchestration capabilities intersecting legacy system modernization requirements.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| Accenture |
| Deloitte |
| PwC |
| EY |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Hyperscale infrastructure concentration in the United States and Western Europe anchors margin capture downstream in sovereign cloud deployments and compliance-certified service tiers. This upstream geography directly shapes where procurement teams absorb premium pricing for data residency guarantees and pre-audited subprocessor chains.
Pricing Analysis
The customization-premium spread separates standard multi-tenant SaaS configurations from sovereign cloud deployments with jurisdictional data processing guarantees. Subscription-based tiered pricing dominates, with differentiation driven by certification level (GDPR Article 28, EU AI Act risk-classification) and geographic delivery cost (sovereign infrastructure premiums). Pricing pressure stems from hyperscale supply concentration compressing margins at the infrastructure layer while compliance requirements sustain premiums at the governance layer. Small enterprises exhibit highest price sensitivity, accepting standardized configurations; multinational corporations absorb 35-40% premiums for bespoke multi-region sovereignty.
Supply Chain Analysis
Upstream feedstock for cloud business process services centers on compute infrastructure, specialized compliance tooling, and certified cloud architect labor pools concentrated in the United States, Ireland, and India. Critical inputs include GPU clusters for AI orchestration, API gateway technologies, and pre-audited subprocessor networks. Single-source vulnerability in hyperscale infrastructure creates systemic continuity risk. Distribution runs through direct vendor relationships that are displacing traditional systems integrator intermediaries, with enterprise procurement teams consolidating around integrated platform ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public Cloud Business Process Services sits in early-cycle expansion as federal cloud mandates and GDPR enforcement accelerate migration from legacy outsourcing contracts to API-orchestrated platforms.
For Market Incumbents: Insulate core revenue streams by deepening certification investments in EU AI Act risk-classification frameworks and GDPR Article 28 processor agreements. Defensive consolidation around pre-built ERP connectors to SAP, Oracle, and Workday environments protects against emerging vertical specialists. Sovereign cloud partnerships with domestic telecom operators in Germany, France, and Saudi Arabia anchor localized infrastructure control. For New Entrants and Emerging Players: Build out edge-to-cloud orchestration capabilities targeting manufacturing supply chain visibility applications where 5G network slicing enables real-time latency bypass. The most penetrable white space sits in medium enterprises seeking agentic AI workflow engines for finance operations automation previously reserved for Fortune 500 implementations. A channel partnership strategy with hyperscaler marketplaces accelerates customer acquisition without direct infrastructure investment. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-first specialists with pre-certified governance toolchains and vertical-specific connectors in regulated BFSI and healthcare segments. Long-term viability hinges on sustained regulatory fragmentation across data residency requirements. The signal to watch is sovereign cloud mandate proliferation in emerging markets, particularly India and Saudi Arabia, as inflection indicators for geographic expansion returns.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Localized infrastructure deployments satisfy Germany's national banking directives and France's CNIL enforcement thresholds. |
| EU AI Act Compliance Certification | Pre-certified risk-classification frameworks unlock premium advisory revenue from automated decision-making governance. |
| ERP Connector Ecosystem Expansion | Pre-built integrations to SAP and Oracle environments reduce procurement friction in manufacturing verticals. |
| Agentic AI Workflow Engine Launch | Virtualized exception handling democratizes enterprise-grade automation for mid-market finance operations. |
| Carbon-Free Energy Matching Program | Verified 24/7 renewable certificates satisfy CSRD Scope 3 reporting obligations for European financial services. |
Research Approach
Desk research of hyperscaler capex disclosures, federal procurement databases, and regulatory filing repositories preceded structured interviews with cloud procurement officers, compliance leads at financial institutions, platform engineers, and systems integrator account directors. Primary fieldwork combined with secondary validation from GDPR enforcement records, SEC cybersecurity disclosure filings, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated against top-down infrastructure spend analysis.
Assumptions held fixed include prevailing data localization requirements and hyperscale infrastructure concentration; variables tested included sovereign cloud mandate proliferation rates and generative AI adoption curves across finance workflows. Segmentation dimensions encompassed service type, deployment architecture, industry vertical, and client size tier. CAGRs derived from regression analysis against historical migration velocity and regulatory enforcement intensity, with inputs weighted toward federal procurement cycle timing and GDPR penalty escalation patterns.
Sensitivities concentrate around Schrems II ruling evolution and emerging national data localization laws fragmenting architecture choices. Forecasts reflect documented assumptions on compliance cost trajectories and hyperscaler pricing discipline. Cross-checking against vendor certification pipeline disclosures and sovereign cloud partnership announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Contract Management Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market