
 China Toys Market | 2026-2036
China Toys Market Size, Share, and Industry Trends Forecast 2026-2036
China Toys Market Intelligence
Buyer concentration across China's toy sector is broadening as live-streaming commerce platforms fragment traditional retail procurement while kindergarten chains consolidate volume. Haivivi leverages its robotics expertise to anchor premium positioning in programmable educational toys. Guangdong Hayidai Toys Co., Ltd. sustains manufacturing scale across plastic injection and assembly operations in the Pearl River Delta. Shenzhen HuanYu Intelligent Play Co., Ltd. differentiates through AI-integrated hardware that responds to voice commands and tactile feedback.
Toys comprise play objects engineered from plastic polymers, timber, metal alloys, or textile composites, designed to developmental milestones across motor, cognitive, and social dimensions; manufacturing employs rotational molding, CNC wood routing, and electronic component integration to meet GB 6675 mechanical and flammability specifications. Educational toys command margin pools as parental spending shifts toward STEAM skill-building products for the preschool segment. Building sets attract sustained demand from the teens age group where complex assembly aligns with robotics competitions and maker culture. Online retail channels capture volume leadership as Douyin and Taobao Live restructure discovery-to-purchase pathways for younger parent demographics.
GB standards administered by SAMR enforce chemical migration limits and small-part choking hazard protocols that manufacturers must clear before domestic distribution. The country's dual carbon goals pressure plastic-dependent producers toward bio-based ABS alternatives and recycled content verification. PLI scheme extensions for advanced manufacturing subsidize automation upgrades in Dongguan and Ningbo export zones. Stakeholders must monitor evolving MEE environmental compliance deadlines and SAMR labeling requirements to secure shelf access across supermarket and discount store networks.
Market Dynamics
Live-streaming commerce platforms are fragmenting traditional toy procurement channels while kindergarten chains consolidate volume, forcing manufacturers to rebuild distribution strategies around Douyin and Taobao Live algorithms rather than wholesale relationships.
Growth Catalysts
- STEAM-aligned procurement:Preschool education institutions are expanding purchases of programmable educational toys following tightened GB standards for child product safety. Dongguan and Shenzhen manufacturing clusters feed this demand through domestic e-commerce channels.
- Dual carbon goals:The country's dual carbon goals pressure plastic-dependent producers toward bio-based ABS alternatives, accelerating material innovation in Guangdong Province's manufacturing belt.
- Cross-border live-streaming:Cross-border live-streaming sales channels enable direct-to-consumer export models, bypassing traditional import distributors in target markets.
Market Restraints
- Petrochemical input volatility:Crude oil price swings directly compress margins for ABS-dependent toy manufacturers, with limited hedging instruments available to mid-scale producers.
- GB compliance friction:SAMR-administered GB 6675 mechanical and flammability specifications create certification bottlenecks that delay product launches by several months.
- Digital entertainment substitution:Mobile gaming and short-form video platforms capture increasing screen time from children, compressing demand for traditional physical play objects.
Strategic Opportunities
- AI-integrated hardware convergence:Voice command and tactile feedback technologies are creating premium positioning opportunities in the programmable educational segment.
- Recycled content verification:MEE environmental compliance deadlines are creating first-mover advantages for manufacturers with verified recycled content supply chains.
- Maker culture alignment:Complex assembly building sets align with robotics competitions and maker culture, opening sustained demand from the teens age group.
Industry Challenges
- Automation capex intensity:PLI scheme extensions for advanced manufacturing require substantial upfront investment in Dongguan and Ningbo export zones, straining balance sheets.
- Labeling compliance complexity:Evolving SAMR labeling requirements demand continuous packaging redesigns to secure shelf access across supermarket and discount store networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Toys Market |
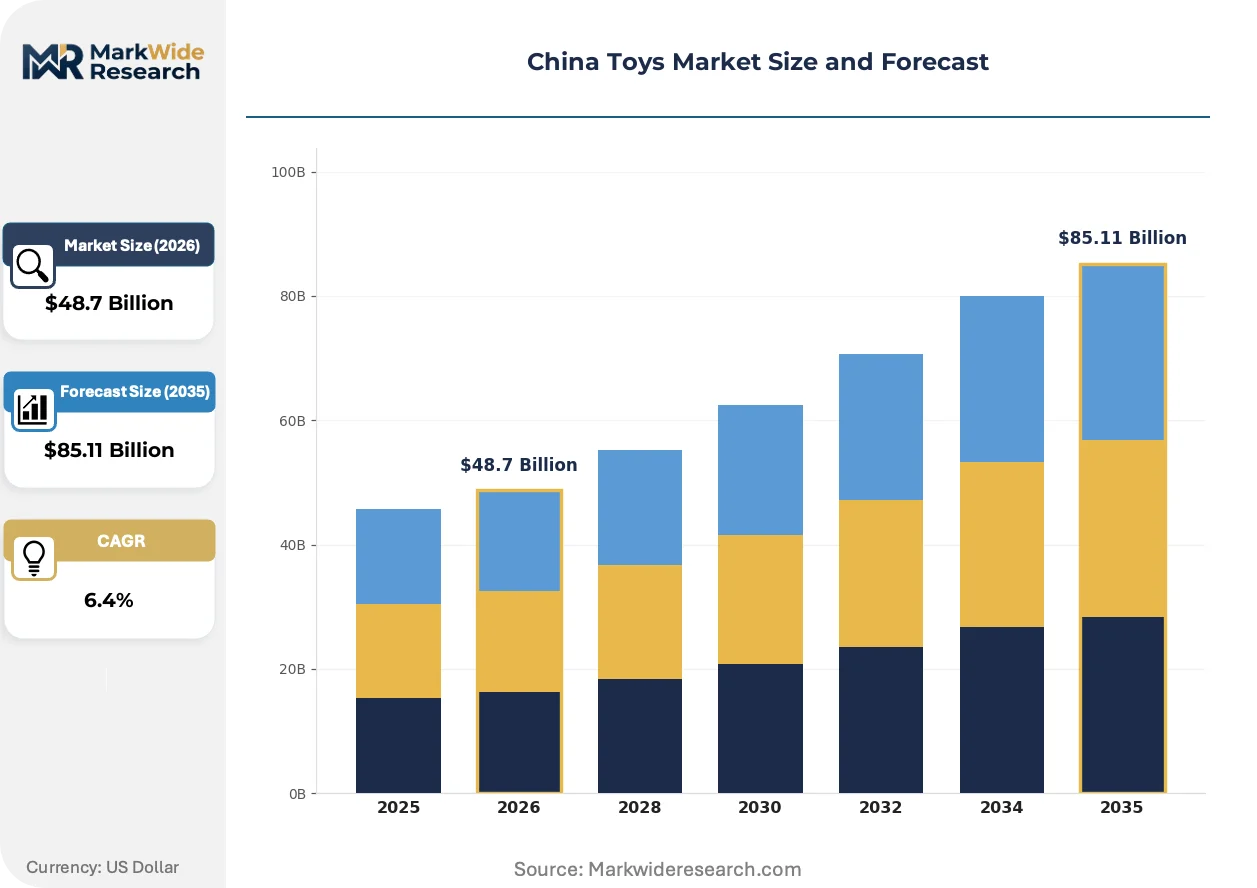
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Educational Toys, Dolls, Building Sets Material: Plastic, Wood, Metal, Fabric Age Group: Infants, Toddlers, Preschool, Teens Sales Channel: Online Retail, Supermarkets, Toy Stores, Discount Stores |
| Companies Covered | Guangzhou LingYue Robotics, Haivivi, Shenzhen HuanYu Intelligent Play Co., Ltd., Qianji Technology, FoloToy, Ningbo Starlight EcoToys Group, Suzhou Harmony, Guangdong Hayidai Toys Co., Ltd., Dongguan BrightPath, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Toys Market Strategic Shifts & Innovations
Educational toys are absorbing digital capabilities while manufacturing processes pivot toward environmental compliance, reshaping how products reach younger parent demographics through algorithm-driven discovery platforms.
Programmable robotics is absorbing AI-driven personalization features that adapt difficulty levels to individual child development trajectories. Preschool education institutions are adopting these systems at accelerated procurement cycles. This convergence is absorbing premium price points away from static construction sets toward adaptive learning hardware.
GB standards administered by SAMR are tightening chemical migration limits and small-part choking hazard protocols. Manufacturers must clear these specifications before domestic distribution, compressing time-to-market for new product introductions. The preschool segment bears the heaviest compliance burden as educational toys face dual scrutiny under both toy safety and educational equipment classifications.
Parental discovery behavior is compressing traditional retail intermediation as Douyin and Taobao Live restructure discovery-to-purchase pathways. Younger parent demographics now encounter toy recommendations through algorithm-curated live streams rather than physical store browsing. This channel shift is most visible in first-tier cities where same-day delivery infrastructure supports impulse conversion from stream to purchase.
China Toys Market Segmentation

Segmentation in China's toy market reveals divergent capital requirements and margin profiles across product categories. Manufacturers must align production footprints with the specific compliance burdens and channel economics of each segment to capture value in this fragmented landscape.
Product Type:
Educational toys demand the heaviest upfront investment due to embedded electronics, firmware development, and dual GB 6675 plus educational equipment certification requirements.
- Educational Toys:Programmable robotics and STEAM-aligned kits integrate microcontrollers, sensors, and adaptive learning software. Preschool institutions in Guangdong Province's manufacturing belt are expanding procurement following tightened SAMR safety standards, though firmware iteration cycles extend development timelines.
- Building Sets:Complex assembly products targeting robotics competitions and maker culture require precision molding tolerances and interlocking mechanism patents. Teens in first-tier cities drive sustained demand as these products align with competitive engineering programs and parental skill-building preferences.
- Action Figures:Licensed character merchandise dominates this segment, with IP royalty structures compressing manufacturer margins.
- Dolls:Fashion and baby dolls concentrate in lower-margin mass production, though premium collectible sub-lines are gaining traction.
Building sets absorb the bulk of installed molding capacity; educational toys are expanding most quickly as institutional procurement accelerates.
Material:
Material selection determines regulatory exposure and carbon compliance trajectory, with petroleum-derived inputs facing the steepest substitution pressure under MEE environmental deadlines.
- Plastic:ABS and polypropylene formulations dominate volume production, though dual carbon goals are forcing bio-based alternatives and recycled content verification. Dongguan clusters are retrofitting injection lines for rABS compatibility to maintain supermarket and discount store shelf access.
- Wood:CNC routing and sustainable forestry certification command premium positioning in European export channels. Guangdong Hayidai Toys Co., Ltd. sustains scale across timber operations in the Pearl River Delta, though humidity control adds processing cost.
- Metal:Die-cast alloys concentrate in vehicle and mechanical toy subsegments, with weight restrictions limiting infant and toddler applications.
- Fabric:Textile composites face GB 18401 textile safety standards alongside toy-specific mechanical testing, complicating compliance for plush and soft toy manufacturers.
Plastic retains dominant volume share; wood is climbing fastest on export premiumization and domestic sustainability signaling.
Age Group:
Target age determines safety protocol stringency, with younger segments facing the most restrictive small-part and chemical migration limits under SAMR administration.
- Preschool:Children aged 3-5 years represent the focal point for STEAM toy adoption, with parental spending concentrating on skill-building products. This segment bears the heaviest compliance burden as educational toys face dual scrutiny under both GB 6675 toy safety and educational equipment classifications.
- Teens:Complex assembly and programmable robotics align with maker culture and competitive engineering programs. Demand concentrates in first-tier cities where same-day delivery infrastructure supports higher price point conversion.
- Infants:Products for 0-12 months face the strictest phthalate and chemical migration limits, limiting supplier pools to certified specialists.
- Toddlers:The 1-3 year bracket bridges safety-critical infant standards and more permissive preschool categories, creating product development complexity.
Preschool commands the largest revenue pool; teens are gaining share fastest on robotics competition alignment and extended play lifecycles.
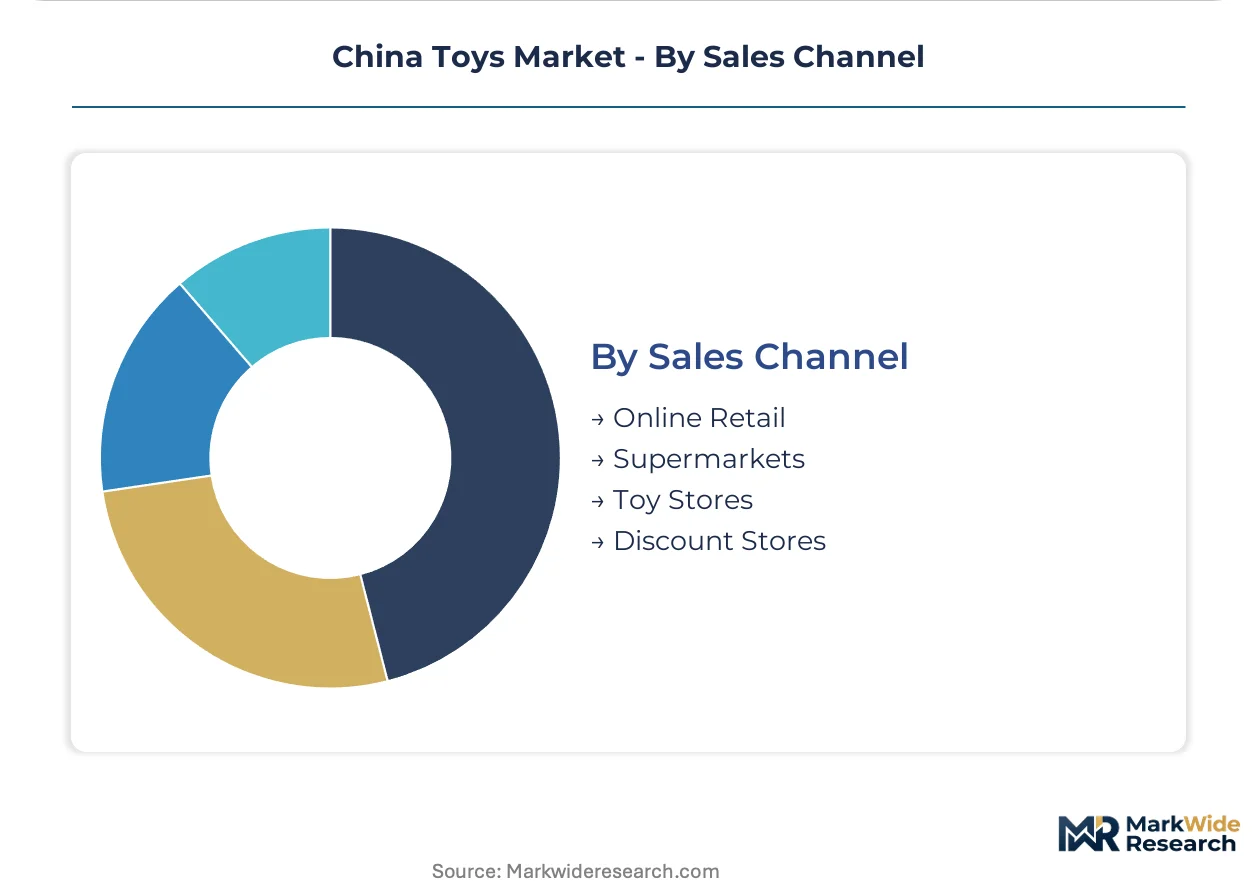
Sales Channel:
Channel economics are restructuring around algorithmic discovery, with live-streaming platforms fragmenting traditional wholesale relationships and demanding new fulfillment capabilities.
- Online Retail:Douyin and Taobao Live restructure discovery-to-purchase pathways for younger parent demographics. Same-day delivery infrastructure in first-tier cities supports impulse conversion from algorithm-curated streams, though returns processing adds logistical cost.
- Supermarkets:Mass-market volume depends on SAMR labeling compliance and slotting fee negotiations, with seasonal purchasing cycles driving inventory risk.
- Toy Stores:Specialty retail maintains premium positioning through experiential merchandising, though foot traffic compression from digital entertainment substitution pressures this channel.
- Discount Stores:Price-sensitive volume concentrates here, with thin margins demanding scale efficiencies and simplified SKU portfolios.
Online retail captures dominant volume flow; toy stores are contracting fastest as discovery behavior shifts to algorithmic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parental spending concentrates in China's coastal provinces where disposable income and STEAM education penetration run highest. Provincial manufacturing clusters in Guangdong and Zhejiang feed both domestic e-commerce and cross-border live-streaming channels. SAMR-administered GB standards create compliance friction that favors established producers with certification infrastructure.
Guangdong Province
Dongguan and Shenzhen manufacturing clusters anchor domestic toy production volume. MEE environmental compliance deadlines pressure plastic-dependent producers toward bio-based ABS alternatives. Shenzhen HuanYu Intelligent Play Co., Ltd. exemplifies the AI-integrated hardware specialization emerging in this belt.
Zhejiang Province
Ningbo export zones absorb PLI scheme subsidies for advanced manufacturing automation upgrades. The province's dual carbon goals implementation runs ahead of national timelines, accelerating recycled content verification systems. Ningbo Starlight EcoToys Group occupies a position within this sustainability-driven tier.
Jiangsu Province
Suzhou industrial parks concentrate precision molding capacity for complex assembly building sets. SAMR labeling requirements demand continuous packaging redesigns from manufacturers serving supermarket and discount store networks. Suzhou Harmony sits within this compliance-intensive segment.
Beijing-Tianjin-Hebei
Preschool education institutions in the capital region drive procurement of programmable educational toys following tightened GB standards. Qianji Technology represents the robotics-focused archetype serving this institutional demand. The cluster's logistics infrastructure supports same-day delivery conversion from live-streaming platforms.
Shanghai Yangtze River Delta
Cross-border live-streaming sales channels enable direct-to-consumer export models from this logistics hub. Haivivi leverages robotics expertise to anchor premium positioning in programmable educational toys. The municipality's free-trade zone status facilitates bonded warehousing for international fulfillment.
China Toys Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-integrated hardware and sustainability certification. The vendor base spans robotics specialists, eco-material fabricators, and traditional plastic injection operators. Three strategic archetypes dominate: programmable educational toy developers, recycled-content manufacturers, and live-streaming-optimized fulfillment players. Competitive moves concentrate on automation capex deployment and cross-border e-commerce platform partnerships.
Among Guangdong-based fabricators, Guangdong Hayidai Toys Co., Ltd. and Dongguan BrightPath exemplify the scale-driven manufacturing archetype serving domestic retail channels. Haivivi and Shenzhen HuanYu Intelligent Play Co., Ltd. occupy positions within the premium-tier AI-integrated segment. Guangzhou LingYue Robotics, FoloToy, and Qianji Technology represent the programmable educational specialization vector. Ningbo Starlight EcoToys Group and Suzhou Harmony sit within the sustainability-certification tier. The collective positioning reveals a market bifurcating between commodity volume producers and technology-differentiated specialists.
| Leading Market Players |
|---|
| Guangzhou LingYue Robotics |
| Haivivi |
| Shenzhen HuanYu Intelligent Play Co., Ltd. |
| Qianji Technology |
| FoloToy |
| Ningbo Starlight EcoToys Group |
| Suzhou Harmony |
| Guangdong Hayidai Toys Co., Ltd. |
| Dongguan BrightPath |
| Others |
Cost & Logistics Intelligence
Robotics firmware engineers clustered in Shenzhen and Dongguan widen labor-cost spreads across premium programmable tiers versus mass-market plastic assembly, compressing mid-tier margins as certification burdens accumulate faster than price premiums.
Pricing Analysis
Volume concentrates in mass-market plastic toys while margins pool in AI-integrated educational hardware. Three-tier pricing structure across premium, standard, and economy levels separates firmware-enabled robotics from static building sets from unbranded commodity injection molding. Cost compression in standard tiers intensifies because petrochemical input volatility transfers directly to ABS-dependent producers. Kindergarten chains exhibit lowest price sensitivity due to institutional procurement budgets; discount store consumers drive hardest bargain negotiations.
Supply Chain Analysis
Domestic-content mandates under China's dual carbon goals and MEE environmental deadlines are reshaping sourcing toward verified recycled ABS and bio-based polymer alternatives. Manufacturing concentrates in China, Vietnam, and Indonesia; Dongguan and Shenzhen clusters feed domestic e-commerce while Ningbo and Ho Chi Minh City absorb export automation upgrades. Raw material dependencies center on petroleum-derived ABS, electronic microcontrollers, and lithium-ion cells for programmable segments. Single-source vulnerability runs through Guangdong's injection molding concentration. Distribution runs through Douyin and Taobao Live algorithms rather than wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified recycled-content capacity bottlenecks prop pricing premiums as MEE deadlines compress compliant supplier pools, creating supply-constrained conditions favoring early movers with verified bio-based ABS supply chains.
For Market Incumbents: To counter digital entertainment substitution eroding physical play demand, Haivivi and Guangdong Hayidai Toys Co., Ltd. should deepen backward integration into captive microcontroller sourcing while accelerating SAMR pre-certification pipelines to compress time-to-market for firmware iterations.
For New Entrants and Emerging Players: Cross-border live-streaming commerce offers the most penetrable route for direct-to-consumer export models bypassing traditional import distributors, with white-space concentration in European sustainability-certified segments and Middle East STEAM education procurement where verified recycled content commands shelf access premiums.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-integrated hardware specialists given firmware personalization capabilities and institutional preschool procurement acceleration, with long-term viability hinging on sustained R&D conversion from static construction to adaptive learning systems; watch for SAMR labeling requirement tightening as inflection signal for compliance-infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Verification | MEE environmental deadlines create first-mover shelf access across supermarket networks. |
| Firmware Personalization Investment | Adaptive learning algorithms capture premium positioning from institutional preschool procurement. |
| Live-Streaming Platform Partnership | Douyin and Taobao Live algorithms restructure discovery-to-purchase pathways for younger parents. |
| Backward Integration into Microcontrollers | Captive chip supply hedges against semiconductor input volatility compressing margins. |
| Cross-Border E-Commerce Infrastructure | Bonded warehousing in Shanghai free-trade zone enables direct-to-consumer export fulfillment. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with toy manufacturing executives, SAMR compliance officers, kindergarten procurement directors, and Douyin channel operators validated demand-side assumptions. Bottom-up triangulation against top-down macroeconomic indicators ensured segmentation coherence across product type, material, age group, and sales channel dimensions.
Data-stream reconciliation between production volume surveys and e-commerce transaction audits informed the analytical framework across the projection horizon. Segmentation modeling incorporated product type, material composition, target age bracket, and channel economics with CAGRs derived from trend extrapolation and elasticity calibration. Firmware iteration cycle lengths and institutional procurement lead times served as industry-specific forecast inputs.
The model holds under stable petrochemical input costs and unchanged SAMR enforcement intensity; deviation in crude oil volatility or GB standard tightening would shift volume-mix assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toy Collectibles Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Ride-Ons Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Wooden Toys Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Coaster Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Toy Cars Market
Toys and Games
Glow Sticks Market
Toys and Games
Global Educational Toy Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Model Train Market
Toys and Games
Construction Toys Market