
 Toy Building Blocks Market | 2026-2036
Toy Building Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Building Blocks Market Insights
The educational toy sector is pivoting toward STEM-aligned construction sets as schools and parents prioritize spatial reasoning and engineering fundamentals. LEGO Group leverages its proprietary clutch-power system and extensive licensing portfolio to sustain premium positioning across age tiers. Mattel anchors its construction presence through the Mega Bloks brand, competing aggressively in the infant and preschool segments where compatibility and safety certification dominate purchase decisions.
Toy building blocks are interlocking modular components, typically manufactured through precision injection molding of ABS plastic or CNC-milled hardwood, designed to develop fine motor skills and cognitive sequencing in children aged six months to twelve years. Specialty Sets and Themed Kits command disproportionate margin pools due to licensed intellectual property and collector-driven repeat purchases, while Electronic Sets represent the fastest-growing product type as embedded sensors and programmable elements merge physical play with digital interaction. The Biodegradable Materials segment remains nascent but attracts sustainability-focused buyers willing to absorb price premiums for plant-based polymers certified under compostability standards.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety requirements, while the EU applies CE marking and EN 71 mechanical testing protocols that restrict small-part geometries for children under three. China's SAMR implements GB 6675 national standards that align with ISO 8124 but impose additional migration limits on heavy metals in colored plastics. Stakeholders must monitor evolving chemical disclosure mandates and circular economy packaging rules that will reshape material sourcing and regional manufacturing footprints.
Market Dynamics
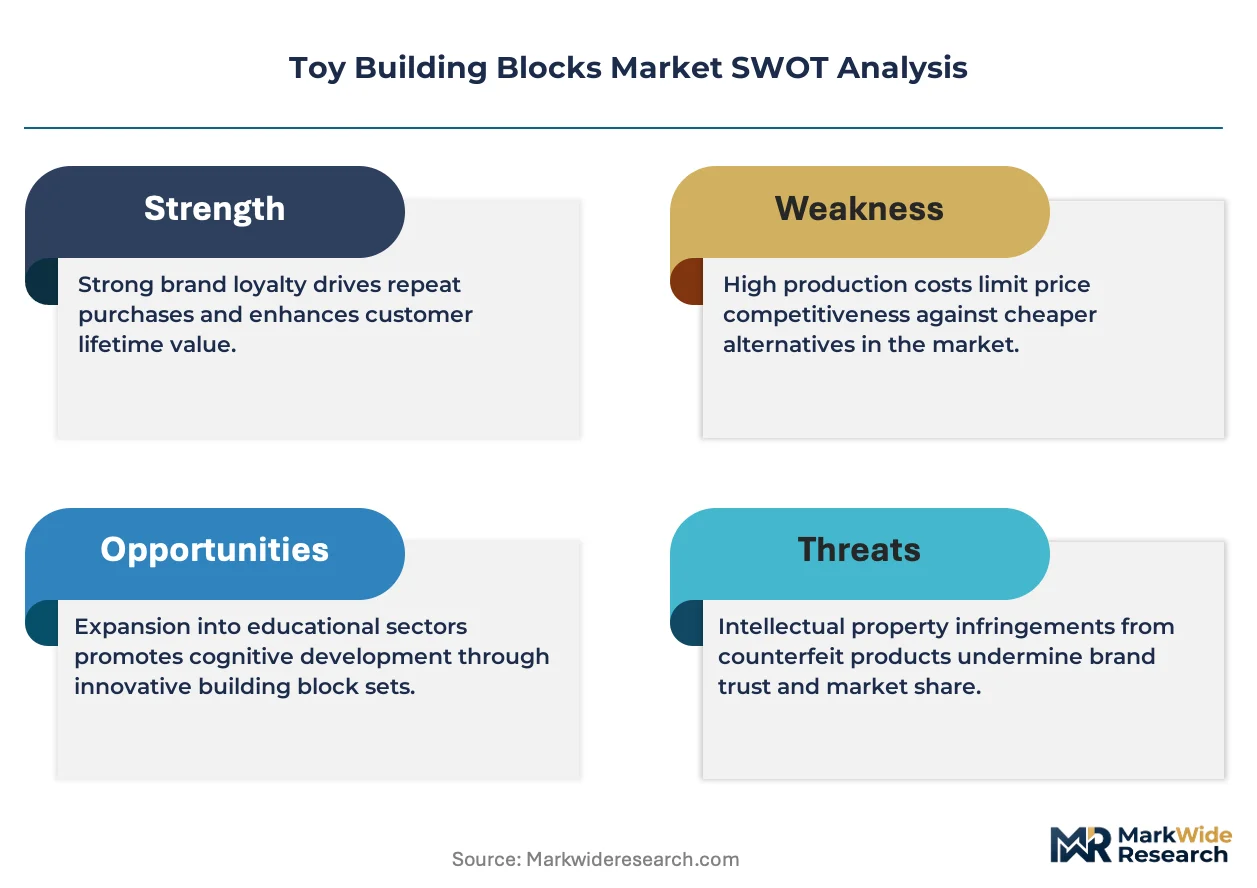
The toy building blocks market is compressing around two converging forces: STEAM curriculum mandates in primary education systems and mounting regulatory pressure on petrochemical-based ABS plastics. Manufacturers now face simultaneous demands for programmable, sensor-embedded construction sets and certified biodegradable material alternatives.
Growth Catalysts
- STEAM Curriculum Integration:Primary schools across Germany, South Korea, and Australia have mandated hands-on construction modules in science and mathematics coursework. District procurement budgets now explicitly allocate for classroom-scale building sets.
- REACH Chemical Disclosure:The EU's expanded SVHC candidate list forces manufacturers to document plasticizer content and heavy metal migration rates. Compliance-certified suppliers gain preferential shelf placement in European retail chains.
- Programmable Elements:Embedded microcontrollers and Bluetooth connectivity modules transform static blocks into robotics platforms. Parents and educators purchase these sets for progressive skill-building across age cohorts.
Market Restraints
- ABS Resin Price Volatility:Acrylonitrile-butadiene-styrene pellet costs fluctuate with crude oil indices and styrene monomer availability. Margins compress unpredictably for injection-molding operations without long-term supply contracts.
- Mold Fabrication Concentration:Precision steel tooling for interlocking geometries concentrates among specialized fabricators in Guangdong Province and Osaka Prefecture. New entrants face 14-18 month lead times for production-qualified molds.
- Small-Part Choking Hazards:ASTM F963 and EN 71 mechanical testing protocols strictly dimension components for children under 36 months. Design freedom narrows for infant-targeted product lines.
Strategic Opportunities
- India Tier-2 City Penetration:Organized retail and e-commerce logistics now reach Surat, Indore, and Coimbatore. Local language packaging and price-tiered assortments unlock first-time construction toy purchases.
- Compostable Polymer Certification:TÜV Austria and BPI industrial compostability standards validate plant-based PLA and starch-blend formulations. Premium positioning commands 40-60% price absorption among sustainability-motivated buyers.
- Subscription Replenishment Models:Direct-to-consumer channels bypass wholesale margin stacking. Monthly themed kit deliveries generate predictable recurring revenue and reduce customer acquisition costs.
Industry Challenges
- Dual-Certification Timelines:Simultaneous GB 6675, ASTM F963, and EN 71 testing cycles extend product launch windows by 8-12 months. Parallel regulatory submissions strain quality assurance staffing.
- Licensing Agreement Complexity:Entertainment property holders demand minimum guarantees, royalty floors, and category exclusivity clauses. Negotiation overhead consumes senior management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Building Blocks Market |
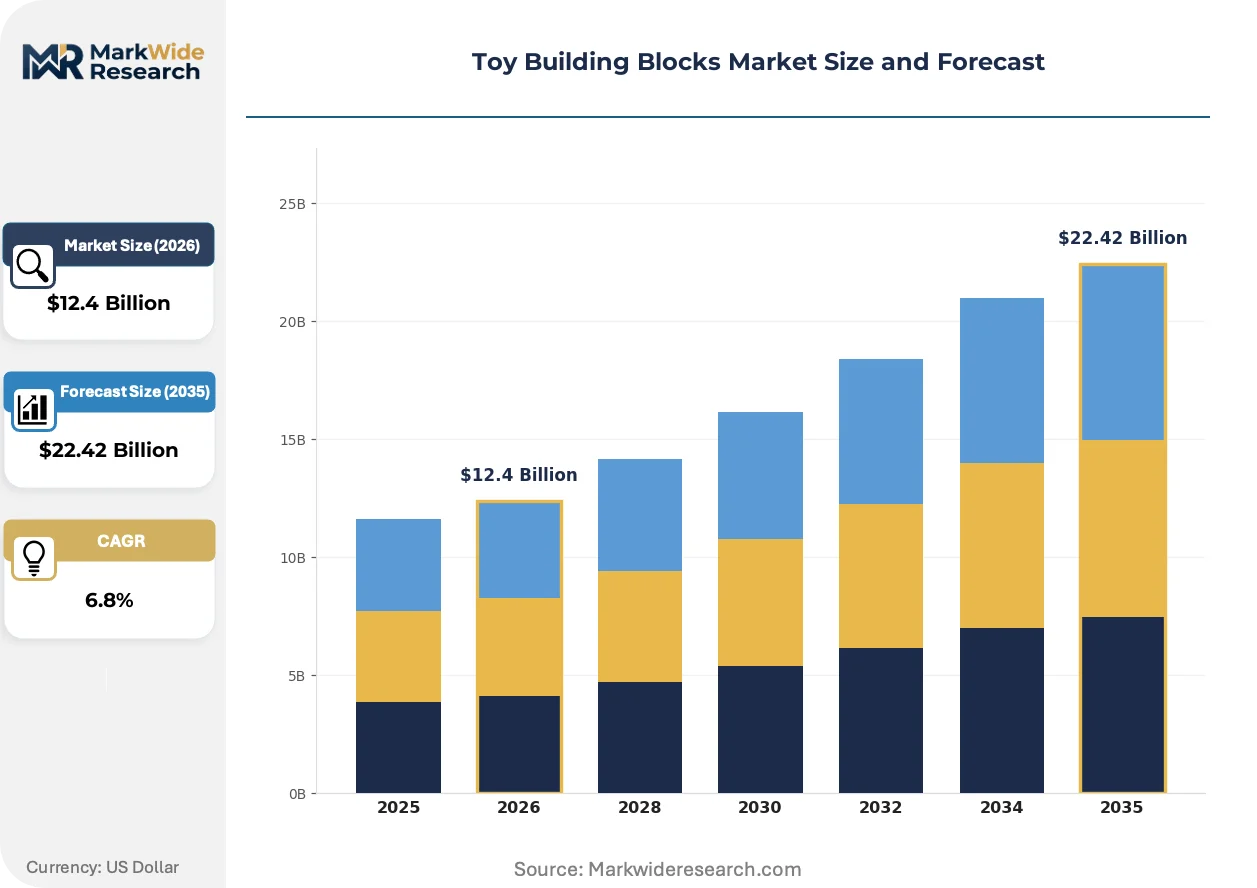
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Blocks, Specialty Sets, Themed Kits, Electronic Sets Age Group: Infants, Toddlers, Preschool, Early School Age Material: Plastic, Wood, Foam, Biodegradable Materials Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | LEGO Group, Mattel, Hasbro, Spin Master, Magna-Tiles, Magformers, Melissa & Doug, Ravensburger, Haba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Building Blocks Market Trends and Innovations
Physical-digital hybrid play experiences are redefining product architecture across age segments. Three interconnected developments are compressing traditional category boundaries and reshaping how construction toys are engineered, certified, and distributed.
Embedded sensor arrays and drag-and-drop coding interfaces are unifying tactile block manipulation with computational thinking curricula. Elementary STEAM programs in Ontario, Canada and Victoria, Australia now specify programmable construction sets as standard equipment. This convergence collapses the historical separation between construction toys and educational robotics, forcing manufacturers to recruit software engineering talent alongside industrial designers.
The EU Toy Safety Directive's 2024 amendment on chemical migration limits tightens testing protocols for phthalate plasticizers and flame retardants in colored ABS compounds. Laboratories in Rotterdam and Milan report 15-20% failure rates in initial screening rounds for legacy formulations. Suppliers are accelerating transitions to bio-based colorants and mineral-filled polypropylene blends to secure CE marking without reformulation delays.
Parental purchasing has gravitated toward modular systems with documented longevity across developmental stages. Retail buyers in France and Japan now prioritize SKUs with explicit age-extension pathways over single-use themed kits. This behavioral pivot rewards manufacturers publishing clear skill-progression matrices and interoperable component standards.
Toy Building Blocks Market Segmentation
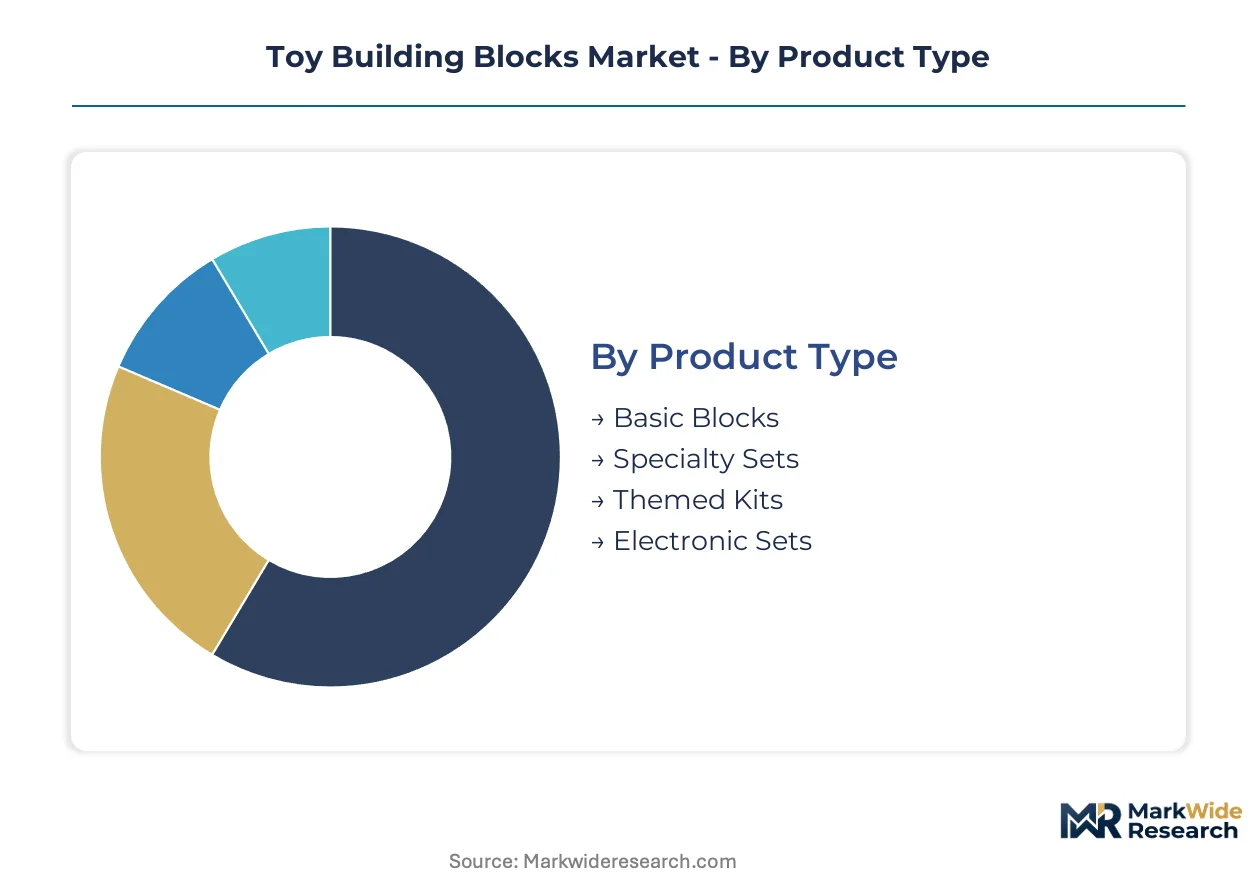
Construction toy manufacturers segment offerings across four intersecting dimensions to align procurement budgets, safety certifications, and developmental milestones. Each axis carries distinct margin profiles and regulatory requirements that shape portfolio investment decisions.
Product Type:
Interlocking geometry precision and embedded electronics capability differentiate product architectures.
- Basic Blocks:Standardized ABS or polypropylene cubes and plates with uniform clutch power. Procurement concentrates in German and Australian primary schools for classroom-scale STEAM modules where interoperability and replacement part availability dominate vendor selection.
- Specialty Sets:Purpose-engineered components—gears, pulleys, axles—enabling mechanical function demonstration. Collector-driven repeat purchases in Japan and South Korea sustain premium positioning through limited-production architectural and engineering-themed releases.
- Themed Kits:Licensed intellectual property constructions featuring entertainment franchise imagery. Demand clusters around gift-giving occasions in North American and European retail with seasonal purchase spikes dictating inventory planning cycles.
- Electronic Sets:Embedded microcontrollers, Bluetooth modules, and drag-and-drop coding interfaces merging physical manipulation with computational logic. These sets are expanding most quickly as Ontario and Victoria education departments specify programmable construction equipment for elementary robotics curricula.
Basic Blocks leads on scale; Electronic Sets leads on momentum.
Age Group:
Safety geometry constraints and cognitive complexity thresholds govern design specifications across developmental windows.
- Infants:Oversized, single-piece geometries exceeding 3cm minimum dimension to eliminate choking hazards under ASTM F963 and EN 71 protocols. Soft, rounded edges predominate in products targeting 6-12 month motor exploration stages.
- Toddlers:Simple stacking configurations with high-contrast coloration supporting hand-eye coordination development. Chinese domestic brands compete aggressively in this tier through price-optimized manufacturing in Guangdong Province.
- Preschool:Alphabet, numeral, and shape-sorting integrations aligning with early literacy milestones. French and Japanese retail buyers prioritize SKUs with documented skill-progression pathways over single-use configurations.
- Early School Age:Complex architectural and engineering challenges with 500+ piece counts and detailed instruction manuals. This cohort commands the highest per-unit pricing and generates significant collector aftermarket activity.
Early School Age generates peak revenue per unit; Electronic Sets integration is climbing the fastest across all age thresholds.
Material:
Supply chain sourcing and end-of-life disposal regulations determine material selection trade-offs.
- Plastic:Injection-molded ABS and polypropylene delivering dimensional stability and colorfastness. ABS resin price volatility tied to crude oil indices compresses margins unpredictably for manufacturers lacking long-term supply contracts.
- Wood:CNC-milled hardwoods—beech, maple, rubberwood—with natural oil or water-based lacquer finishes. Premium positioning in German and Nordic markets where parental preferences favor tactile warmth and biodegradability.
- Foam:EVA and polyurethane soft construction for indoor active play and noise-dampening environments. Concentrated in institutional purchases for daycare and therapy settings requiring impact absorption.
- Biodegradable Materials:Plant-based PLA and starch-blend polymers certified under TÜV Austria and BPI industrial compostability standards. Sustainability-motivated buyers in France and Benelux absorb 40-60% price premiums for validated formulations.
Plastic dominates manufacturing volume; Biodegradable Materials gains share fastest on regulatory pressure and consumer preference shifts.
Price Tier:
Certification grade, component count, and intellectual property licensing fees stratify pricing architecture.
- Budget:Unlicensed, domestic-brand assortments with simplified geometries and reduced color palettes. Volume concentrates in Indian tier-2 cities—Surat, Indore, Coimbatore—where organized retail penetration is unlocking first-time construction toy purchases.
- Mid-Range:Balanced feature sets with limited licensing and moderate piece counts. This tier captures the broadest household penetration across North American mass retail channels.
- Premium:Proprietary interlocking systems with extensive licensing portfolios and age-extension pathways. LEGO Group anchors this tier through clutch-power precision and entertainment property exclusivity.
- Luxury:Limited editions, precious material variants, and architectural collector pieces. Artisan woodcraft and precious metal accents target adult collector demographics in Japanese and Gulf state markets.
Premium captures disproportionate margin pools; Budget tier shows steepest expansion trajectory on emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers relocate to jurisdictions with streamlined certification pathways and lower compliance overhead. Cost-of-compliance gaps between REACH-aligned Europe and GB-standard China are accelerating mold-fabrication concentration in Guangdong Province while European brands outsource injection-molding to Southeast Asian contract manufacturers.
China
Domestic brands compete aggressively with multinational suppliers in toddler and preschool segments through price-optimized manufacturing in Guangdong Province. SAMR enforces GB 6675 national standards that align with ISO 8124 but impose additional migration limits on heavy metals in colored plastics. Shenzhen and Dongguan host precision steel tooling fabricators serving 14-18 month mold production cycles for interlocking geometries.
Germany
Primary schools mandate hands-on construction modules in science and mathematics coursework, driving district procurement budgets for classroom-scale STEAM sets. The EU Toy Safety Directive and ECHA's expanded SVHC candidate list force plasticizer documentation and heavy metal migration testing. Bavaria's woodworking clusters supply CNC-milled hardwood construction toys with natural oil finishes for premium positioning.
United States
Seasonal gift-giving occasions concentrate demand for licensed intellectual property construction sets in mass retail channels. The Consumer Product Safety Commission enforces ASTM F963 toy safety requirements that strictly dimension small-part geometries for children under 36 months. California's consumer protection frameworks add state-level chemical disclosure mandates beyond federal baselines.
India
Organized retail and e-commerce logistics penetration into Surat, Indore, and Coimbatore unlocks first-time construction toy purchases in tier-2 cities. BIS certification requirements for imported toys create compliance barriers that domestic manufacturers exploit for market share. Maharashtra's plastics processing hubs near Mumbai supply injection-molding capacity for budget-tier unlicensed assortments.
Japan
Collector-driven repeat purchases sustain premium positioning for limited-production architectural and engineering-themed specialty sets. METI oversees product safety standards that align with international ISO 8124 frameworks while maintaining additional mechanical testing protocols. Osaka Prefecture retains concentrated precision mold-fabrication expertise for interlocking component systems.
Toy Building Blocks Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance programmable electronics integration against biodegradable material transitions. The vendor base stratifies across three tiers: multinational conglomerates with entertainment licensing portfolios, mid-cap specialists in precision interlocking systems, and regional fabricators serving price-sensitive emerging markets. Three archetypes define competitive positioning: clutch-power precision specialists, STEAM-curriculum solution providers, and sustainability-certified niche players. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire software engineering capabilities and secure exclusive entertainment property rights.
Within the multinational conglomerate tier, LEGO Group and Mattel occupy positions as archetype anchors for clutch-power precision and infant-preschool segment coverage respectively. Among specialty manufacturers, Magna-Tiles and Magformers exemplify magnetic construction system specialists competing on geometric versatility and spatial reasoning development. Melissa & Doug represents the wooden construction toy archetype, sitting within the premium tactile-materials segment where parental preferences favor biodegradability and developmental longevity. Ravensburger and Haba occupy positions as European family-owned specialists with heritage positioning in educational play.
| Leading Market Players |
|---|
| LEGO Group |
| Mattel |
| Hasbro |
| Spin Master |
| Magna-Tiles |
| Magformers |
| Melissa & Doug |
| Ravensburger |
| Haba |
| Others |
Pricing and Supply Chain Analysis
Precision mold fabrication expertise concentrated in Guangdong Province and Osaka Prefecture creates labor-cost differentials that directly widen pricing-tier spreads between premium clutch-power systems and budget-tier unlicensed assortments.
Pricing Analysis
Distributor margin stacking and retailer markup differentials separate premium-tier proprietary interlocking systems from mid-range limited-licensing assortments and budget domestic-brand offerings. Price differentiation hinges on certification grade—GB 6675, ASTM F963, and EN 71 compliance tiers—and intellectual property licensing fees. Pricing pressure stems from ABS resin cost volatility tied to crude oil indices, compressing margins for injection-molding operations lacking long-term supply contracts. Budget-tier buyers in Indian tier-2 cities exhibit highest price sensitivity, while Japanese collector demographics absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements for classroom-scale procurement in German and Australian primary schools mandate multi-supplier qualification for STEAM curriculum vendors. Manufacturing concentrates in China, Germany, and India, with precision steel tooling anchored in Guangdong Province and Osaka Prefecture. Raw material dependencies center on ABS and polypropylene resin, plant-based PLA formulations, and CNC-milled hardwood feedstock. Single-source vulnerability concentrates in mold-fabrication lead times extending 14-18 months. Distribution runs through mass retail chains in North America, organized retail in European urban centers, and direct-to-consumer subscription channels bypassing wholesale margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biodegradable material transitions commanding sustainability premiums and programmable electronics integration justifying tier-climb pricing.
For Market Incumbents: Deepen proprietary clutch-power system refinement and entertainment property exclusivity to defend against magnetic construction system substitutes. Anchor capacity addition in Southeast Asian contract manufacturing to offset REACH compliance overhead in European production. Certification investment in TÜV Austria and BPI compostability standards secures preferential shelf placement against emerging plant-based polymer entrants. For New Entrants and Emerging Players: Sustainability-motivated buyers in France and Benelux represent an underserved buyer archetype willing to absorb 40-60% price premiums for validated biodegradable formulations. Tier-2 Indian cities—Surat, Indore, Coimbatore—offer the most penetrable geography with first-time construction toy demand unlocking through local language packaging. Direct-to-consumer subscription replenishment models bypass entrenched wholesale relationships and reduce customer acquisition costs. For Investors and Strategic Acquirers: Entertainment conglomerates with toy licensing portfolios are the most active acquirer in this space, seeking construction toy capabilities to complement existing play pattern coverage. Five-to-ten year viability favors targets with software engineering integration and programmable electronics expertise. The signal to watch is STEAM curriculum mandate acceleration in additional primary education systems, indicating demand inflection for classroom-scale procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Certification | TÜV Austria and BPI validation unlocks premium positioning in sustainability-motivated European retail channels. |
| Programmable Electronics Integration | Embedded microcontrollers align product architecture with Ontario and Victoria elementary robotics curriculum specifications. |
| Direct-to-Consumer Subscription Launch | Monthly themed kit deliveries generate predictable recurring revenue and bypass wholesale margin stacking. |
| Southeast Asian Manufacturing Footprint | Contract manufacturing relocation streamlines REACH compliance pathways for European brand owners. |
| Entertainment Property Licensing Agreement | Exclusive franchise rights sustain collector-driven repeat purchases and seasonal gift-giving demand spikes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with toy manufacturer R&D directors, retail category buyers, primary school procurement officers, and sustainability certification auditors with secondary validation against customs trade records, GB 6675 and ASTM F963 regulatory filings, and STEAM curriculum policy documents. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting approaches distributed value across product type, age group, material composition, and price tier dimensions throughout the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking policy impact assessment incorporated classroom procurement budget allocations, biodegradable polymer adoption curves, and programmable electronics penetration rates across primary education systems.
Underlying measurement precision varies by segment; Electronic Sets and Biodegradable Materials carry tighter precision than Basic Blocks given definitional clarity and certification documentation availability. Forecasts reflect documented assumptions on curriculum mandate expansion, resin cost trajectories, and regulatory amendment timelines. Deviation in REACH chemical disclosure enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toys and Games Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Model Train Market
Toys and Games
Coaster Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Toy Cars Market
Toys and Games
Kids Toys Market
Toys and Games
Kid's Microphone Market
Toys and Games
Robot Toys for Children Market
Toys and Games
Games and Puzzles Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
US Sex Toys Market
Toys and Games
Fabric Toys Market