
 Irish Moss Extract Market | 2026-2036
Irish Moss Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Irish Moss Extract Market Insights
EU Novel Food Regulation is broadening the cost-of-entry calculus for Irish moss extract suppliers seeking approval in European markets. CP Kelco leverages its integrated red seaweed supply chain to sustain consistent carrageenan-grade output. Cargill anchors its position through controlled sourcing relationships with Atlantic coastal harvesters. Gelymar competes on specialized refined extracts for clean-label food applications.
Irish moss extract is a hydrocolloid derived from Chondrus crispus, containing 55-65% carrageenan by dry weight and processed through alkali modification or alcohol precipitation to yield gelling, thickening, and stabilizing functionalities for industrial use. Powder formulations dominate current volume flows due to extended shelf stability and ease of bulk handling in manufacturing settings. Nutritional Supplements represents the fastest-expanding application segment, driven by collagen-alternative positioning and prebiotic fiber claims in functional wellness products.
EFSA and FDA frameworks govern extract purity thresholds and food-additive classifications, while EU REACH compliance shapes chemical processing standards for European market access. BIS standards in India and China's GB food safety codes add layered certification requirements for exporters targeting Asian manufacturing hubs. Stakeholders must monitor evolving Novel Food dossier requirements and coastal harvesting quotas as dual constraints on scalable supply.
Market Dynamics
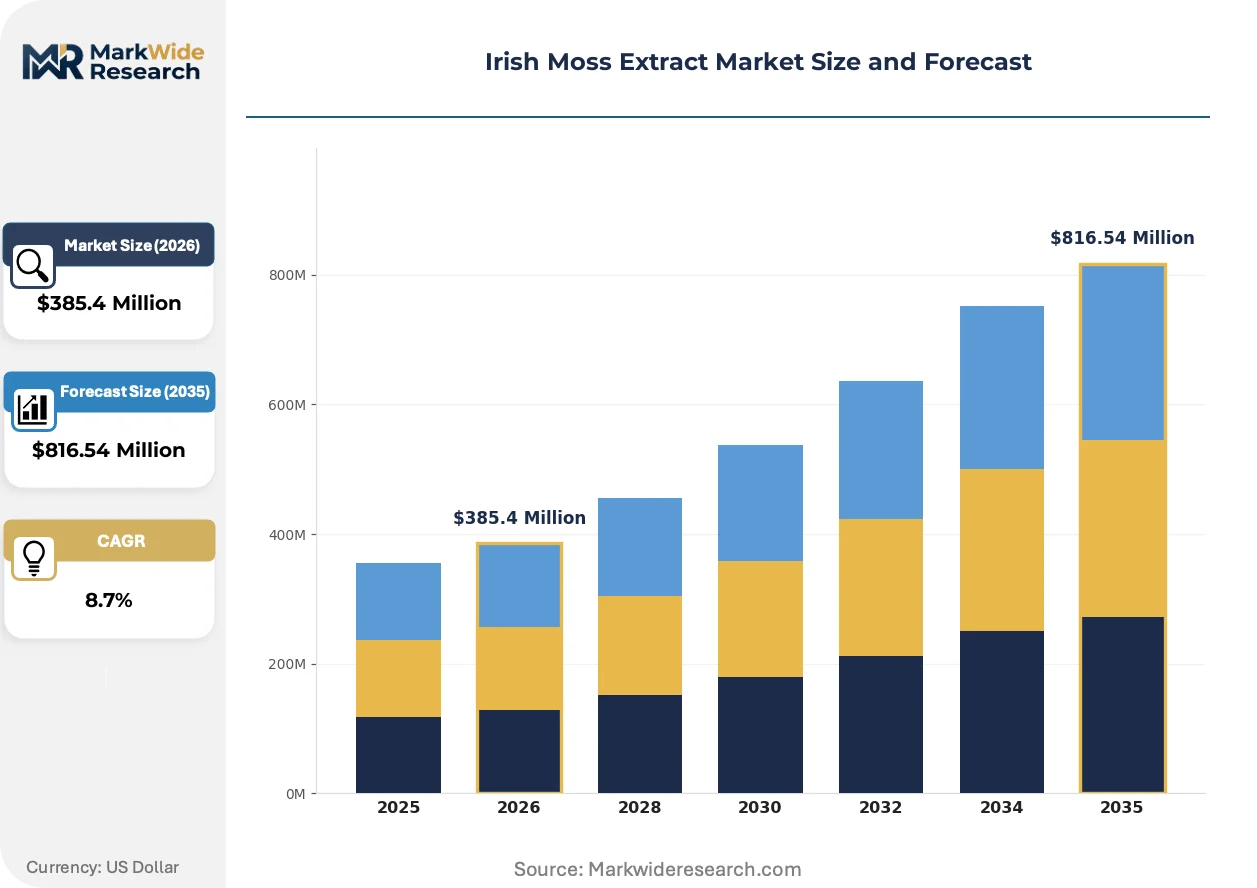
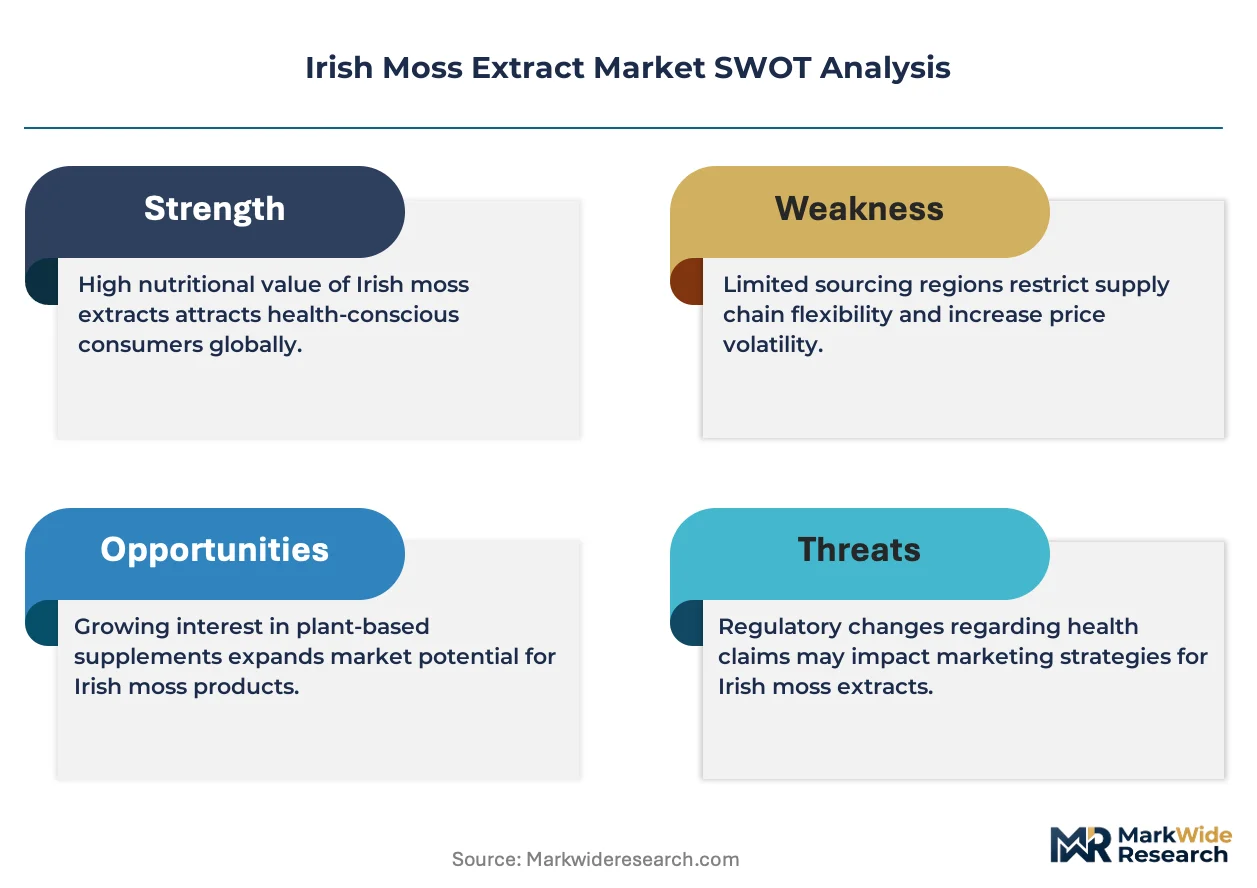
The Irish Moss Extract Market pivots on tightening coastal harvesting quotas and the EU Novel Food Regulation's dossier requirements, which together compress supply elasticity while elevating compliance costs for new market entrants.
Growth Catalysts
- EFSA Novel Food pathways:Approved dossiers for Chondrus crispus extracts in functional foods unlock formulation opportunities across continental Europe. Food manufacturers gain ingredient flexibility.
- Nutritional Supplements demand:Collagen-alternative positioning and prebiotic fiber claims drive formulator uptake in wellness products. Clean-label positioning accelerates trial.
- Atlantic coastal harvesting communities:Traditional knowledge sustains wild-stock access in Ireland and Scotland. Seasonal labor pools anchor supply continuity.
Market Restraints
- Wild harvest dependency:Chondrus crispus biomass fluctuates with Atlantic salinity and temperature cycles. Climate stress compounds yield unpredictability.
- Alkali processing input costs:Potassium hydroxide and sodium carbonate prices track energy markets. Margin compression hits semi-refined extract tiers.
- EU REACH chemical standards:Solvent residue thresholds and processing disclosure requirements extend compliance timelines. Smaller processors face capital barriers.
Strategic Opportunities
- India BIS certification pathways:Standardized import protocols for hydrocolloids open formulation partnerships with domestic food manufacturers. Regulatory clarity reduces entry friction.
- Cell-culture propagation:Laboratory cultivation of Chondrus crispus biomass decouples supply from wild harvest constraints. Biotechnology convergence enables year-round output.
- Direct-to-manufacturer platforms:Digital procurement channels bypass traditional distributor markups for mid-volume buyers. Transparency on carrageenan grade and provenance commands premium positioning.
Industry Challenges
- Novel Food dossier compilation:EFSA safety studies and toxicology data requirements demand 18-24 month preparation cycles. Specialist regulatory consultants command scarce capacity.
- Alcohol precipitation capex:Food-grade ethanol recovery systems and solvent handling infrastructure require seven-figure investment. Financing access constrains processor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irish Moss Extract Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Extract, Powder, Gel, Capsules Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutritional Supplements Form: Liquid, Solid, Semi-Solid, Cream Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | CP Kelco, Cargill, DuPont de Nemours, Kerry Group, Ceamsa, Gelymar, Shemberg, Greenfresh, LONGRUN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irish Moss Extract Market Trends and Innovations
Formulation science and regulatory science are converging to reshape how Irish moss extract moves from coastal harvest to finished goods, with purity verification and supply traceability emerging as competitive differentiators.
Enzyme-assisted extraction is consolidating processing efficiency gains across the hydrocolloid sector. Food-grade cellulase and protease treatments reduce alkali demand and shorten refinement cycles. European contract manufacturers are retrofitting lines to accommodate enzymatic protocols. This shift is consolidating market share among processors with in-house biotechnology capabilities, squeezing traditional alkali-reliant operations.
EU REACH chemical safety standards are tightening disclosure requirements for solvent residues in food-grade extracts. Processors must document ethanol and isopropanol recovery rates across batch records. The semi-refined carrageenan segment faces the steepest compliance burden, with several Irish processors investing in closed-loop recovery systems to maintain European market access.
Ingredient provenance verification is displacing commodity purchasing in premium formulation channels. Clean-label food brands now demand GPS-tracked harvest coordinates and batch-level DNA authentication. This behavioral shift is most visible in German and Dutch organic food manufacturing, where supply chain transparency directly influences supplier selection and contract renewal decisions.
Irish Moss Extract Market Segmentation
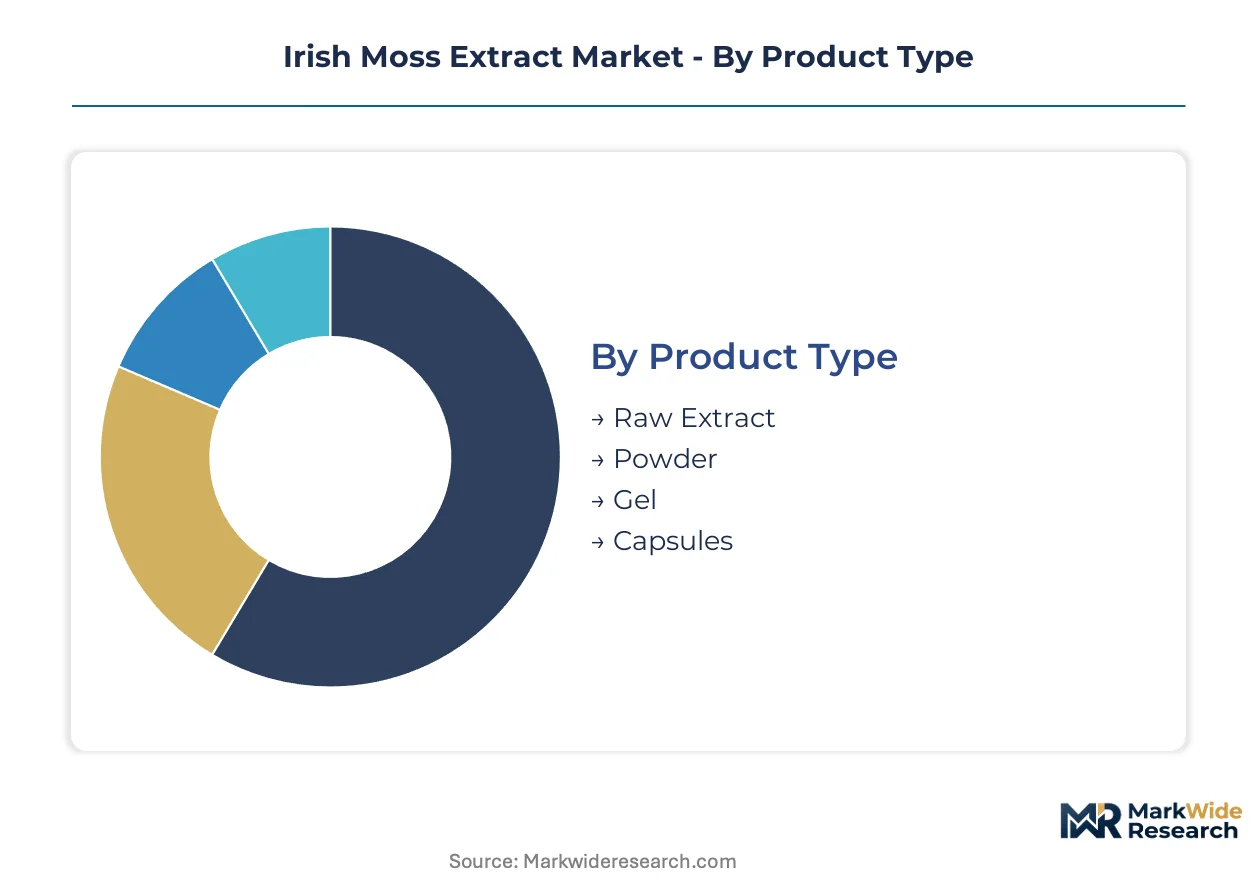
Segmentation in the Irish Moss Extract Market reveals how processing intensity and end-use specifications fragment commercial pathways. Carrageenan-grade requirements, shelf-stability demands, and formulation viscosity targets pull extractors toward specialized production configurations rather than commodity supply.
Product Type:
Formulation upgrade cycles drive purchasing patterns across product tiers, with manufacturers replacing legacy raw inputs with refined grades to meet clean-label and performance specifications.
- Raw Extract:Semi-processed biomass retaining 35-45% carrageenan content serves regional food processors and artisanal cosmetic formulators in Ireland and coastal Scotland. Demand concentrates among small-batch buyers prioritizing traceability over standardization; supply volatility from wild harvest fluctuations constrains contract reliability.
- Powder:Spray-dried or drum-dried particulate with 55-65% carrageenan purity dominates industrial procurement due to extended shelf stability and bulk handling efficiency. Volume concentrates in food manufacturing hubs across Germany and the Netherlands; powder specifications now require EFSA-compliant Novel Food dossiers for new supplier qualification.
- Gel:Hydrated colloidal suspensions with pre-activated gelling properties target ready-to-use cosmetic and pharmaceutical formulation channels. Specialized rheology profiles command premium positioning in dermal care applications.
- Capsules:Encapsulated dry extracts standardized for prebiotic fiber content serve direct-to-consumer wellness brands. Convenience positioning drives uptake in nutritional supplement retail channels.
Volume placements concentrate in Powder; the faster expansion belongs to Capsules.
Application:
Cost tier differentiation separates commodity food-grade supply from pharmaceutical-grade extraction, with certification requirements and purity thresholds determining margin capture.
- Food & Beverage:Hydrocolloid functionality for dairy alternatives, processed meats, and confectionery represents the established revenue base. Carrageenan gelling and thickening properties anchor formulation stability; EFSA food additive classifications govern purity thresholds for continental European access.
- Nutritional Supplements:Collagen-alternative positioning and gut-health prebiotic claims accelerate formulator uptake in functional wellness products. Clean-label demand from German and Dutch organic brands drives premium pricing for provenance-verified extracts.
- Cosmetics:Film-forming and moisture-retention properties support dermal care and hair conditioning formulations. Sustainability credentials increasingly influence supplier selection in French and British personal care manufacturing.
- Pharmaceuticals:Excipient-grade specifications for tablet binding and sustained-release matrices require USP or EP compliance. Regulatory dossier complexity limits viable supplier pools.
Revenue gravity sits with Food & Beverage; Nutritional Supplements is climbing the fastest.
Form:
Customer type segmentation separates industrial bulk buyers from specialized formulators, with handling infrastructure and batch scale determining format preference.
- Liquid:Aqueous suspensions or concentrated solutions enable direct pipeline injection in continuous food processing operations. Beverage manufacturers in Ireland and the United Kingdom favor liquid formats for simplified hydration protocols.
- Solid:Dried powders and granules support extended storage and flexible reconstitution across diverse manufacturing settings. Powder handling systems in continental European plants reinforce solid format dominance.
- Semi-Solid:Pastes and slurries with intermediate moisture content target intermediate processing stages where controlled hydration rates matter. Specialized cosmetic compounders utilize semi-solid intermediates.
- Cream:Emulsion-stabilized preparations serve topical pharmaceutical and premium cosmetic finished goods. Texture and spreadability specifications demand customized rheology profiles.
Procurement weight tilts toward Solid; Cream formats are gaining share fastest in premium channels.
Distribution Channel:
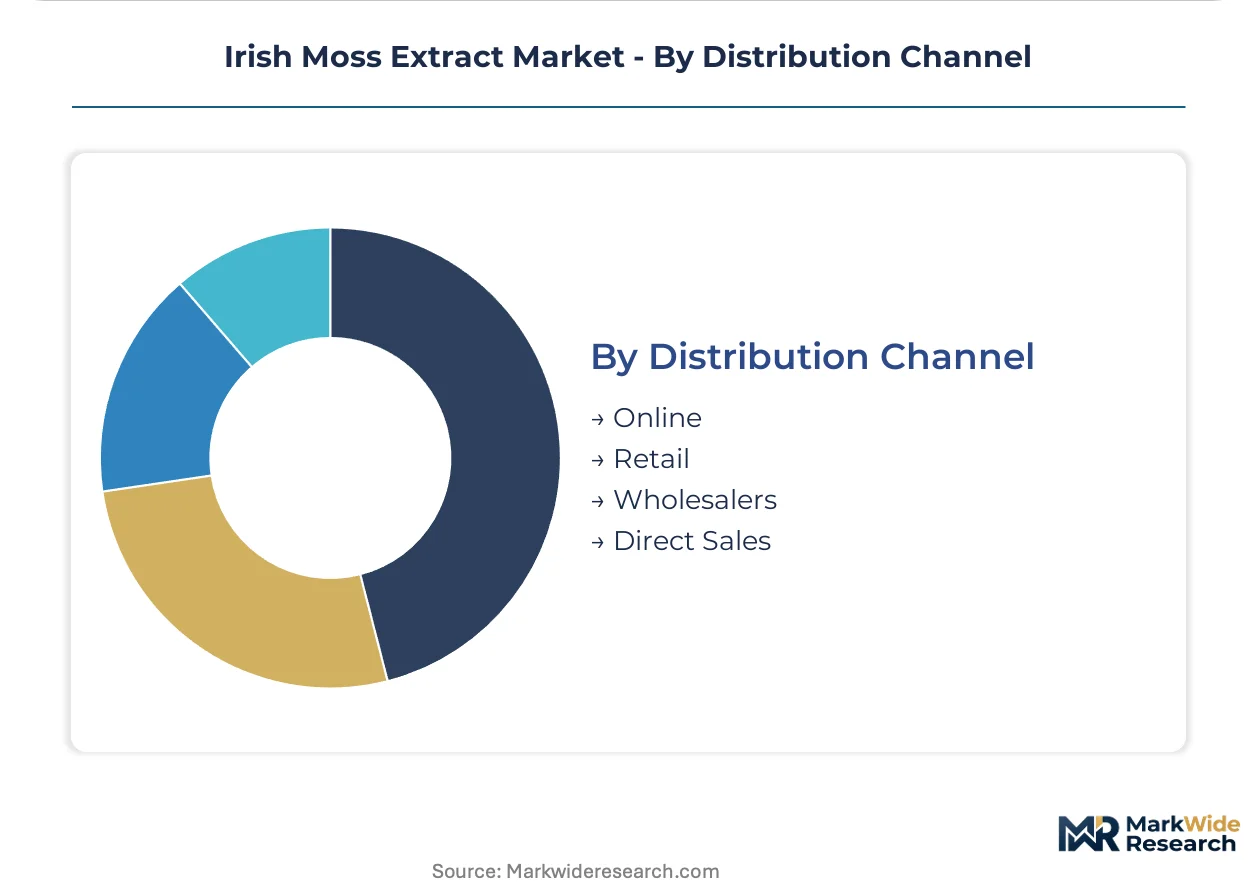
Supply concentration patterns favor direct relationships with coastal processors, though digital platforms are restructuring access for mid-volume buyers.
- Direct Sales:Long-term contracts between extract processors and major food manufacturers secure volume commitments and specification alignment. Cargill and CP Kelco anchor direct channel dominance through captive sourcing relationships.
- Wholesalers:Regional distributors aggregate smaller lot sizes for independent formulators and specialty manufacturers. Inventory carrying costs and quality verification burdens compress wholesaler margins.
- Online:B2B procurement platforms enable transparent grade comparison and provenance documentation for mid-tier buyers. Transparency on carrageenan specifications commands premium positioning.
- Retail:Consumer-facing channels for finished supplement and cosmetic products; minimal raw extract flow through retail.
Contract value concentrates in Direct Sales; Online channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shannon Free Zone tax incentives concentrate Irish moss extract processing in Ireland's west coast corridor, anchoring European supply chains for carrageenan-grade hydrocolloids.
Ireland
Traditional harvesting communities in County Kerry and County Cork sustain wild-stock access for Chondrus crispus biomass. EFSA Novel Food dossier requirements govern extract purity thresholds for continental European export. The Shannon Estuary processing cluster houses alkali-modification facilities serving German and Dutch food manufacturers.
United Kingdom
Scottish coastal harvesters in the Hebrides supply semi-refined grades to regional cosmetic compounders. UK Food Standards Agency classifications align with retained EU food additive regulations post-Brexit. The Grangemouth industrial zone hosts drum-drying operations for powder formulations targeting nutritional supplement brands.
Germany
Clean-label food manufacturers in Hamburg and Bremen drive demand for provenance-verified extracts with GPS-tracked harvest coordinates. REACH chemical safety standards mandate solvent residue documentation across batch records. The Cologne-Düsseldorf corridor anchors formulation partnerships between extract distributors and organic dairy alternatives producers.
Netherlands
Rotterdam port logistics enable bulk powder imports for redistribution across continental European food manufacturing hubs. Dutch organic certification bodies enforce supply chain transparency requirements exceeding baseline EU standards. The Eindhoven region hosts specialized rheology testing laboratories supporting cosmetic gel formulation development.
India
Domestic food manufacturers in Maharashtra and Gujarat seek BIS-certified hydrocolloid imports for processed dairy and confectionery applications. FSSAI food safety codes layer additional testing requirements on top of import protocols. The Mumbai-Pune industrial corridor houses contract manufacturers retrofitting lines for enzymatic extraction protocols.
Irish Moss Extract Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply configurations. The market structure consolidates around three to five integrated processors controlling captive Atlantic sourcing relationships, while mid-tier refiners compete on specialized grade differentiation. Strategic archetypes span backward-integrated harvester-processors, technology-licensing specialists, and regional trading houses. Capacity expansion in closed-loop solvent recovery and M&A targeting coastal harvesting quotas represent dominant competitive moves.
Within the integrated processor tier, CP Kelco and Cargill anchor positions through controlled sourcing relationships with Atlantic coastal communities. Gelymar occupies a specialized position focused on refined extracts for clean-label food applications. Chinese fabricators including Greenfresh and LONGRUN exemplify scale-driven competition on semi-refined powder grades for Asian manufacturing hubs.
| Leading Market Players |
|---|
| CP Kelco |
| Cargill |
| DuPont de Nemours |
| Kerry Group |
| Ceamsa |
| Gelymar |
| Shemberg |
| Greenfresh |
| LONGRUN |
| Others |
Pricing and Supply Chain Analysis
Traditional harvesters in County Kerry and County Cork anchor labor-cost differentials that widen pricing-tier spreads between artisanal raw extract and industrial powder grades. Seasonal labor pools tied to Atlantic tidal cycles compress wage flexibility, forcing processors to absorb cost volatility or push tier premiums.
Pricing Analysis
Short lead-time premiums command pricing power for spot powder deliveries to German dairy-alternative manufacturers, while contracted annual offtakes secure volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates EFSA Novel Food-certified extracts from semi-refined grades and unqualified raw biomass. Price differentiation hinges on carrageenan purity thresholds and REACH solvent-residue documentation. Pricing pressure stems from potassium hydroxide cost spikes tracking European energy markets. Nutritional supplement brands show least price sensitivity; regional food processors in Ireland exhibit highest elasticity.
Supply Chain Analysis
EFSA Novel Food dossier requirements and REACH chemical safety certifications gate European market access, filtering supplier pools to established processors. Geographic supply concentrates in Ireland, the United Kingdom, and coastal France, with wild Chondrus crispus biomass drawing from Atlantic tidal zones. Alkali modification inputs—potassium hydroxide, sodium carbonate—and food-grade ethanol for precipitation constitute critical dependencies. Single-source vulnerability runs through County Kerry harvesting cooperatives supplying CP Kelco and Cargill. Distribution runs through direct-processor relationships for volume buyers, with Rotterdam port logistics enabling continental redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in an enzyme-assisted extraction transition, with cellulase and protease protocols displacing legacy alkali-heavy processing. Biotechnology retrofit investments now separate viable processors from stranded capacity.
For Market Incumbents: Extend captive sourcing relationships with Atlantic coastal communities to lock harvest quotas before cell-culture propagation matures. Cell-culture biotechnology threatens wild-harvest dependency; backward integration into closed-loop solvent recovery preserves REACH-compliant European access. For New Entrants and Emerging Players: B2B procurement platforms offer route-to-market bypass for mid-volume buyers seeking provenance-verified extracts. White-space targets include Indian BIS-certified hydrocolloid partnerships and enzymatic-extraction contract manufacturing. Nutritional supplement capsules represent the most penetrable segment given collagen-alternative demand acceleration. For Investors and Strategic Acquirers: Re-rating potential sits with enzyme-capable mid-tier refiners given EFSA Novel Food approval velocity and clean-label brand pull. Five-to-ten year viability favors processors with dual wild-harvest and cell-culture technology pathways. Watch EFSA dossier approval timelines as inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Retrofit | Cellulase and protease protocols reduce alkali demand and accelerate EFSA compliance timelines. |
| Cell-Culture Propagation Investment | Laboratory cultivation of Chondrus crispus decouples supply from Atlantic climate volatility. |
| Closed-Loop Solvent Recovery | Food-grade ethanol recovery systems secure REACH chemical safety certification for European market retention. |
| Novel Food Dossier Submission | EFSA safety studies unlock formulation partnerships with German and Dutch clean-label manufacturers. |
| Direct-to-Manufacturer Platform Launch | Digital procurement transparency on carrageenan grade commands premium positioning among mid-volume buyers. |
Research Methodology
Document review covered EFSA Novel Food registers, REACH chemical safety filings, and BIS hydrocolloid import protocols, complemented by interviews with extraction plant managers, procurement leads at German dairy-alternative manufacturers, coastal harvesting cooperative coordinators, and regulatory affairs specialists at Irish processing facilities. Secondary validation drew from customs trade data, FSSAI food safety codes, and SEC filings of diversified ingredient conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Historical extraction capacity utilization cross-referenced against panel input from formulation scientists and contract manufacturers informed the analytical framework. Segmentation dimensions spanned product type, application end-use, form factor, and regional regulatory cluster. CAGRs derived from trend-line extrapolation of enzyme-adoption curves and Novel Food approval velocity. Forecast inputs incorporated coastal harvesting quota trajectories and cell-culture propagation technology maturation curves.
Inputs from EFSA dossier databases and Irish coastal cooperative harvest records were available through the study window; gaps in proprietary cell-culture yield data introduce uncertainty bands around biotechnology supply projections. Forecasts reflect documented assumptions regarding regulatory approval timelines and climate-driven biomass fluctuation patterns. A model refresh is warranted upon material change in EFSA Novel Food evaluation criteria or breakthrough cell-culture cost parity achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Frankincense Oil Market
Extracts
Palmarosa Oil Market
Extracts
Peppermint Leaf Powder Market
Extracts
Belladonna Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Helichrysum Oil Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Glycerol Extracts Market
Extracts
Clary Sage Oil Market
Extracts
Extracts and Distillates Market
Extracts
Global Ginseng Extracts Market
Extracts
Cornflower Extract Market
Extracts
Sage Extract Market
Extracts
Global Herbal Extract Market
Extracts
Citronella Oil Market
Extracts
Saffron Extract Market