
 Hydroglycolic Extracts Market | 2026-2036
Hydroglycolic Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroglycolic Extracts Market Foresight
Cosmetics is restructuring demand patterns across the Hydroglycolic Extracts landscape, pulling volume toward botanical actives for skin hydration and microbiome-friendly formulations. Givaudan SA leverages captive raw-material sourcing from tropical supply zones to secure consistent feedstock quality. Symrise AG anchors its position through biotechnology-driven extraction platforms that yield standardized polyphenol fractions. Kerry Group competes by extending its portfolio into clean-label cosmetic ingredients from established food-grade extraction infrastructure.
Hydroglycolic extracts are aqueous-glycolic solvent systems, typically formulated with propylene glycol or butylene glycol at concentrations between 20% and 50%, designed to preserve heat-sensitive bioactive compounds while ensuring microbial stability and skin permeation. These extraction media serve primarily to isolate flavonoids, tannins, and terpenoids for cosmetic, pharmaceutical, and nutraceutical applications without alcohol-induced denaturation. Herbal extracts command the largest share within product type categories, reflecting deep supplier expertise in standardized botanical sourcing. Cosmetics applications are outpacing food and beverages in growth velocity, driven by fermented and upcycled plant ingredient trends that favor hydroglycolic carrier compatibility. Liquid forms dominate formulation flexibility, though powder formats are gaining traction in solid-dose nutraceuticals where moisture control dictates shelf-life performance.
EMA cosmetic ingredient safety assessments and REACH registration requirements in Europe impose rigorous substance characterization thresholds that filter out small-scale, non-compliant suppliers. FDA cosmetic good manufacturing practice rules and forthcoming fragrance allergen disclosure mandates in the United States are reshaping labeling obligations and reformulation priorities. Stakeholders must monitor regulatory divergence between European precautionary frameworks and American risk-based approaches when allocating R&D and registration budgets across jurisdictions.
Market Dynamics
Clean-label cosmetics procurement is compressing supplier margins while concentrating volume toward extraction specialists with captive botanical sourcing and REACH-registered manufacturing infrastructure. This demand pull from formulators seeking alcohol-free, heat-stable actives is restructuring competitive positioning across solvent-based extraction.
Growth Catalysts
- REACH registration thresholds:ECHA substance characterization mandates in Europe filter out non-compliant small-scale suppliers, redirecting volume toward registered producers with validated analytical protocols.
- Fermented ingredient compatibility:Postbiotic skincare formulations require hydroglycolic carriers that preserve microbial metabolite stability without alcohol-induced denaturation.
- Grasse extraction cluster:France's fragrance and flavor houses anchor specialized aqueous-glycolic processing capacity with established tropical raw-material relationships.
Market Restraints
- Propylene glycol price volatility:Petrochemical feedstock fluctuations directly compress extraction economics, forcing reformulation toward butylene glycol alternatives at higher unit cost.
- Tropical supply concentration:Botanical raw-material sourcing clusters in Southeast Asian and South American growing regions expose processors to climate disruption and logistics friction.
- Standardization gaps:Absence of harmonized polyphenol content reference methods creates batch-to-batch variability that pharmaceutical and nutraceutical buyers reject.
Strategic Opportunities
- Upcycled feedstock streams:Food and beverage processing waste streams—grape pomace, citrus peels, coffee silverskin—offer untapped flavonoid sources at negative raw-material cost.
- FDA cosmetic GMP alignment:forthcoming good manufacturing practice rules create first-mover advantage for extraction facilities pre-investing in quality system documentation.
- Powder format nutraceuticals:Moisture-controlled solid-dose applications favor spray-dried hydroglycolic extracts with extended shelf-life performance versus liquid alternatives.
Industry Challenges
- Analytical chemistry talent scarcity:Validated HPLC and mass spectrometry expertise for botanical fingerprinting concentrates in Grasse and Basel, creating recruitment bottlenecks for new market entrants.
- Dual-registration burden:Separate REACH dossiers and FDA cosmetic ingredient filings demand parallel toxicology studies, stretching R&D budgets across incompatible regulatory timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroglycolic Extracts Market |
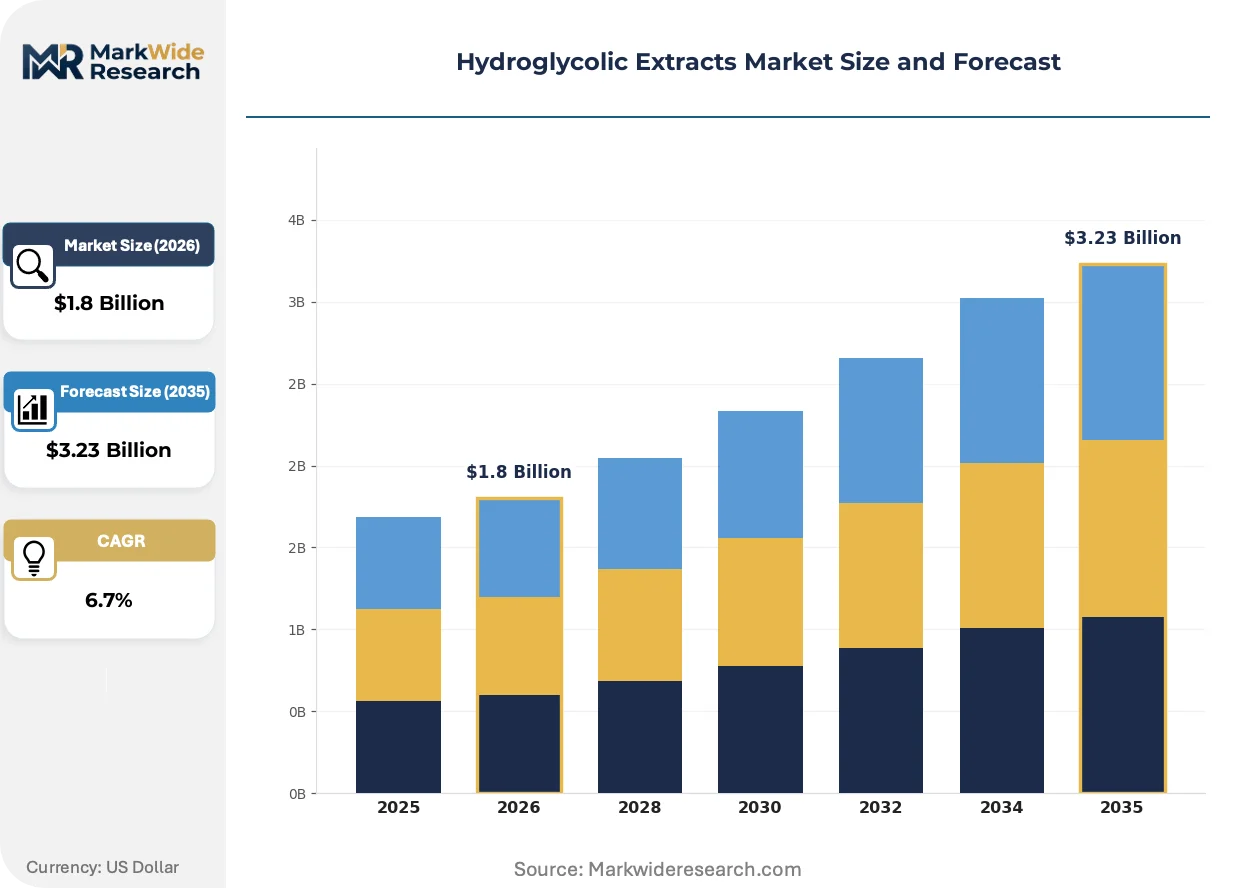
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Floral Extracts, Fruit Extracts, Vegetable Extracts Application: Cosmetics, Pharmaceuticals, Food & Beverages, Nutraceuticals Form: Liquid, Powder, Paste, Granules End User: Manufacturers, Retailers, Distributors, Research Institutions |
| Companies Covered | Givaudan SA, Symrise AG, Herbalife Nutrition Ltd., International Flavors & Fragrances Inc., Sensient Technologies Corporation, dsm-firmenich, Cargill Incorporated, Archer Daniels Midland Company, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroglycolic Extracts Market Shifts & Advancements
Biotechnology-driven extraction platforms are displacing conventional solvent maceration, while regulatory disclosure mandates force transparency on fragrance allergens and botanical provenance. These shifts favor capital-intensive producers with integrated analytical capabilities.
Membrane filtration technology is modularizing downstream processing for hydroglycolic extracts, replacing energy-intensive vacuum concentration with selective permeation systems that preserve heat-sensitive terpenoids. Mid-scale cosmetic ingredient manufacturers in France and Switzerland are adopting these skid-mounted units to reduce batch cycle times. This technology is modularizing capital deployment, enabling smaller producers to achieve pharmaceutical-grade purity without fixed-asset intensity previously reserved for Givaudan-scale operations.
EU fragrance allergen disclosure mandates under the CLP Regulation are forcing reformulation of scented cosmetic products containing botanical extracts with sensitizing potential. Manufacturers must now label 82 additional substances above threshold concentrations, compressing permissible formulation space for traditional herbal extracts. Fragrance houses in Grasse are responding by developing hypoallergenic fractionation techniques that remove sensitizing sesquiterpenes while preserving desired odor-active compounds.
Direct-procurement contracts between cosmetic formulators and extraction specialists are displacing traditional distributor intermediaries, particularly for certified organic and fair-trade botanicals. L'Oréal and Estée Lauder are establishing multi-year offtake agreements with Kerry Group and Symrise AG that specify polyphenol standardization, carbon footprint limits, and blockchain traceability. This pattern is most visible in France, where Grasse-based suppliers now dedicate 40% of capacity to captive relationships with Paris-headquartered beauty multinationals.
Hydroglycolic Extracts Market Segmentation
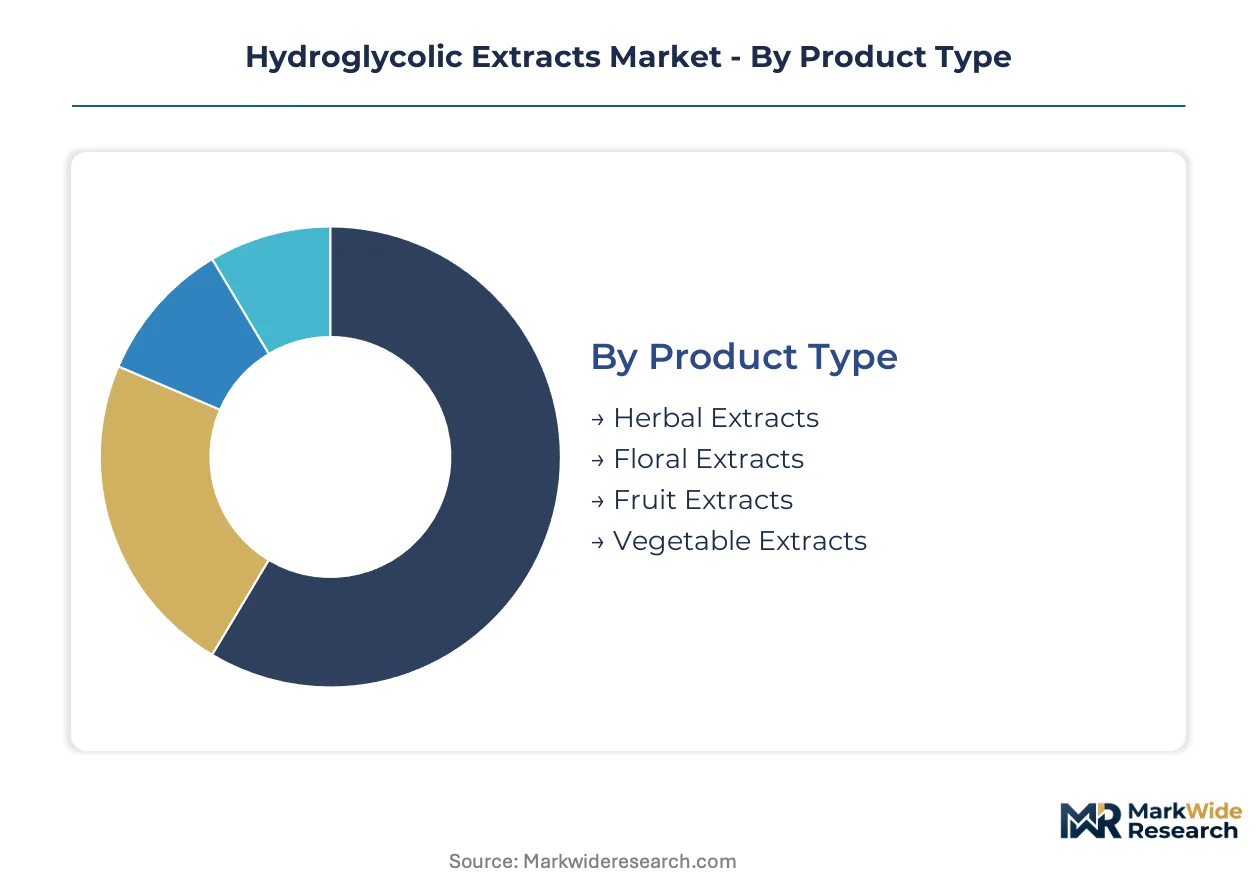
Segmentation in hydroglycolic extracts determines procurement strategy and formulation compatibility. Standalone liquid extracts serve distinct supply chains from embedded powder actives in solid-dose nutraceuticals. Each dimension—botanical source, application target, physical state, and buyer type—carries different regulatory burdens and margin structures.
Product Type:
Standalone extracts command premium pricing for direct cosmetic formulation, while embedded fractions integrate into multi-ingredient systems for functional foods.
- Herbal Extracts:Standardized polyphenol fractions from green tea, chamomile, and ginseng dominate procurement volumes. Cosmetics manufacturers in France and Switzerland specify these for microbiome-friendly skincare, though batch-to-batch variability in wild-harvested material strains quality assurance protocols.
- Floral Extracts:Rose, jasmine, and neroli hydroglycolic fractions anchor fragrance-free skincare positioning. Grasse-based extraction houses dedicate captive capacity to these actives, securing tropical supply relationships that insulate against climate disruption in Moroccan and Egyptian growing regions.
- Fruit Extracts:Grape seed and citrus bioflavonoid concentrates serve antioxidant applications across cosmetics and nutraceuticals.
- Vegetable Extracts:Carrot, cucumber, and aloe glycerites target soothing and hydration claims in clean-label personal care.
Herbal extracts lead volumes today; floral extracts are gaining share fastest.
Application:
Cost tiers separate pharmaceutical-grade specifications from cosmetic and food-grade alternatives, with each tier demanding distinct analytical validation.
- Cosmetics:Skin hydration and postbiotic formulations drive the steepest demand expansion. L'Oréal and Estée Lauder procurement contracts specify REACH-registered supply with blockchain traceability, compressing permissible supplier pools to extraction specialists with validated HPLC protocols.
- Pharmaceuticals:Standardized botanical actives for topical dermatological preparations require EMA-compliant substance characterization. The dual-registration burden across REACH dossiers and FDA cosmetic ingredient filings stretches R&D budgets for entrants lacking established toxicology databases.
- Food & Beverages:Natural flavoring and coloring applications favor mild extraction conditions that preserve volatile aromatic compounds.
- Nutraceuticals:Solid-dose supplement formats demand moisture-controlled powder extracts with extended shelf-life performance versus liquid alternatives.
Cosmetics leads volumes today; nutraceuticals are climbing the fastest.
Form:
Volume concentration favors liquid formats for formulation flexibility, though powder alternatives serve geographic markets with logistics constraints.
- Liquid:Aqueous-glycolic solutions at 20-50% glycol concentration preserve heat-sensitive terpenoids without alcohol-induced denaturation. Membrane filtration technology is modularizing downstream processing for mid-scale manufacturers in France and Switzerland, reducing batch cycle times.
- Powder:Spray-dried extracts with maltodextrin carriers target moisture-sensitive nutraceutical applications. Solid-dose formulators in Germany and the United States specify these for tablet and capsule production where liquid incorporation disrupts compression physics.
- Paste:High-viscosity concentrates serve specialized cosmetic balm and ointment manufacturing.
- Granules:Free-flowing particulates facilitate automated dispensing in food and beverage processing environments.
Liquid leads volumes today; powder is expanding most quickly.
End User:
Customer type determines contract structure, with manufacturers capturing volume concentration and research institutions driving specification evolution.
- Manufacturers:Cosmetic and pharmaceutical formulators specify polyphenol standardization, carbon footprint limits, and allergen disclosure compliance. Direct-procurement contracts are displacing traditional distributor intermediaries, particularly for certified organic and fair-trade botanicals.
- Retailers:Private-label skincare and supplement brands demand smaller batch sizes with flexible labeling for regional regulatory variations.
- Distributors:Regional intermediaries consolidate fragmented botanical supply for smaller formulators lacking direct extraction relationships.
- Research Institutions:Universities and biotechnology firms pilot novel extraction protocols and fermentation-compatible carrier systems.
Manufacturers lead volumes today; retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse anchors the global hydroglycolic extraction infrastructure, with France's fragrance valley concentrating specialized aqueous-glycolic processing capacity and tropical raw-material relationships that insulate against supply disruption.
France
Cosmetic formulators in Paris drive procurement of REACH-registered botanical actives with blockchain traceability requirements. ECHA substance characterization mandates filter non-compliant suppliers, redirecting volume toward validated producers. Grasse-based extraction houses dedicate captive capacity to floral hydroglycolic fractions, securing Moroccan rose and Egyptian jasmine supply through direct-growing region contracts.
United States
FDA cosmetic good manufacturing practice rules and forthcoming fragrance allergen disclosure mandates reshape labeling obligations and reformulation priorities. The agency's risk-based approach diverges from European precautionary frameworks, stretching R&D budgets across incompatible regulatory timelines. New Jersey and California cosmetic manufacturing clusters source standardized polyphenol extracts through direct-procurement agreements with extraction specialists.
Germany
Solid-dose nutraceutical manufacturers in Bavaria and Baden-Württemberg specify moisture-controlled spray-dried hydroglycolic extracts for tablet and capsule production. BfR safety assessments and EU Green Deal sustainability reporting requirements impose substance characterization thresholds. Frankfurt-Rhine-Main distribution hubs consolidate fragmented botanical supply for mid-scale European formulators lacking direct extraction relationships.
Switzerland
Swissmedic pharmaceutical-grade specifications and biotechnology-driven extraction platforms yield standardized polyphenol fractions for topical dermatological preparations. Basel analytical chemistry expertise concentrates validated HPLC and mass spectrometry capabilities for botanical fingerprinting. Zürich and Geneva cosmetic ingredient manufacturers adopt membrane filtration technology to reduce batch cycle times without Givaudan-scale fixed-asset intensity.
India
CDSCO cosmetic ingredient safety assessments and FSSAI natural flavoring regulations create dual-registration pathways for botanical extract exporters. Maharashtra and Karnataka herbal processing clusters supply standardized green tea and ginseng fractions to European and North American formulators. Mumbai and Bangalore extraction facilities face recruitment bottlenecks for analytical chemistry talent as demand concentrates in Grasse and Basel.
Hydroglycolic Extracts Market Competitive Landscape
Direct-procurement contract establishment dominates the current landscape, with L'Oréal and Estée Lauder displacing traditional distributor intermediaries through multi-year offtake agreements specifying polyphenol standardization and carbon footprint limits. The vendor base stratifies across three archetypes: fragrance houses with captive tropical sourcing, food-grade extraction specialists extending into cosmetic ingredients, and biotechnology platforms delivering standardized fractions. Capacity expansion in membrane filtration technology and backward integration into botanical growing regions represent the dominant competitive moves as margin compression favors capital-intensive producers.
Among fragrance and flavor houses, Givaudan SA and Symrise AG exemplify the integrated extraction archetype, anchoring specialized aqueous-glycolic processing capacity through established tropical supply relationships. Kerry Group occupies a position within the food-to-cosmetics extension tier, leveraging clean-label ingredient infrastructure to serve personal care formulators. These three entities represent distinct strategic postures: captive raw-material sourcing, biotechnology-driven standardization, and cross-sector portfolio diversification.
| Leading Market Players |
|---|
| Givaudan SA |
| Symrise AG |
| Herbalife Nutrition Ltd. |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| dsm-firmenich |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-registered extraction specialists and unregistered commodity suppliers manifests in divergent margin structures and supply chain control points. Premium-tier producers in Grasse and Basel command pricing power through validated HPLC protocols and captive tropical sourcing, while commodity processors face margin compression from propylene glycol cost volatility and buyer consolidation.
Pricing Analysis
Input-cost pass-through from petrochemical feedstock fluctuations compresses extraction economics for glycol-dependent processors, forcing reformulation toward higher-cost butylene glycol alternatives. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and food-grade certification levels separates buyers by analytical validation requirements and regulatory filing depth. Pricing pressure stems from clean-label procurement mandates that concentrate volume toward registered producers while squeezing mid-tier suppliers. Small-scale formulators exhibit highest price sensitivity, whereas L'Oréal and Estée Lauder procurement offices prioritize standardization and traceability over unit cost.
Supply Chain Analysis
Analytical chemistry talent scarcity in Grasse and Basel constrains capacity expansion for mid-scale manufacturers seeking membrane filtration adoption. Supply concentrates in France, Switzerland, and Germany, with tropical raw-material dependencies anchored in Moroccan rose and Egyptian jasmine growing regions. Propylene glycol and butylene glycol feedstock costs hinge on petrochemical pricing cycles, while botanical sourcing draws from Southeast Asian and South American cultivation clusters. Single-source vulnerability in tropical supply corridors exposes processors to climate disruption and logistics friction. Distribution runs through direct-procurement contracts between extraction specialists and cosmetic formulators, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
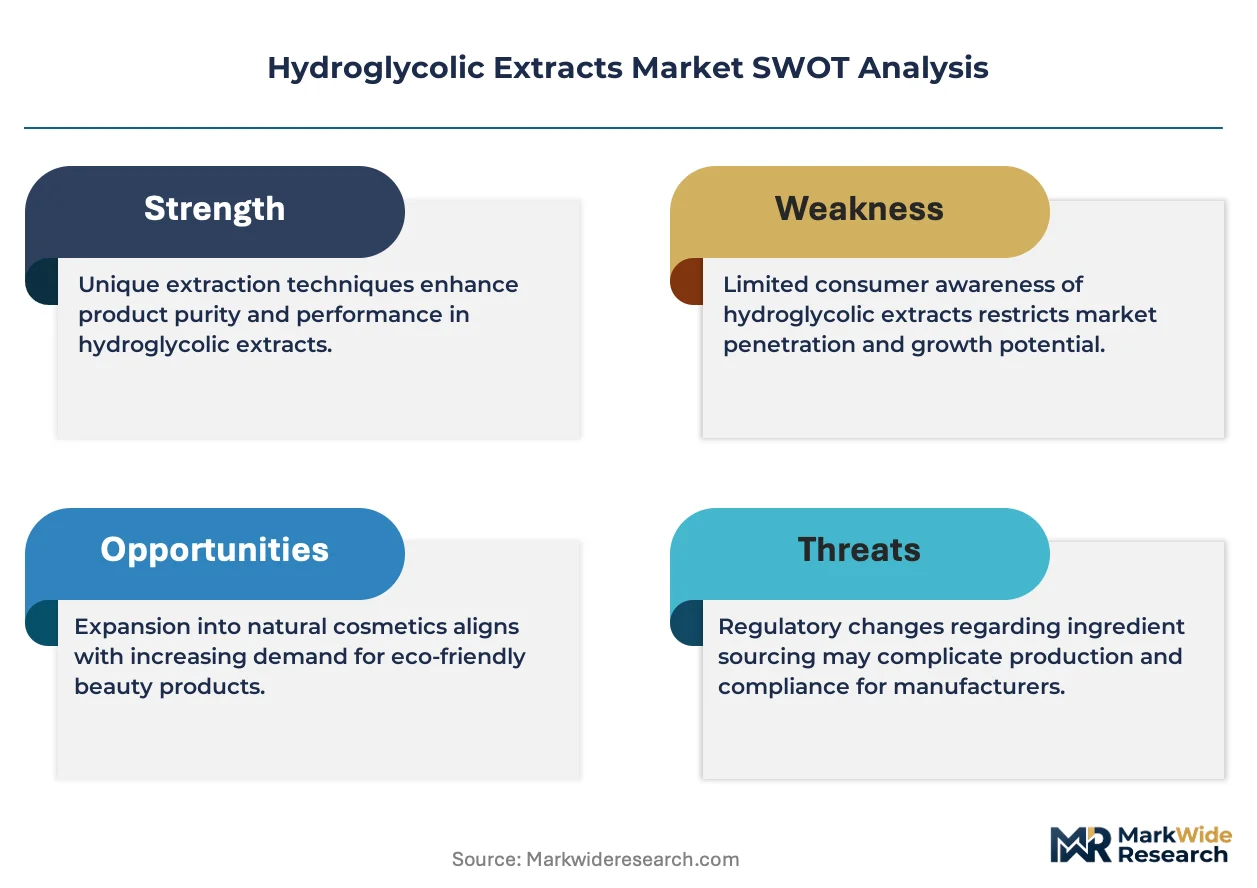
This market functions as a regulatory compounder where ECHA REACH registration thresholds and FDA cosmetic GMP rules simultaneously filter supplier pools and concentrate demand toward validated producers. The dual-registration burden across European precautionary frameworks and American risk-based approaches creates structural advantages for incumbents with established toxicology databases.
For Market Incumbents: Anticipate margin compression from clean-label procurement consolidation by securing captive botanical sourcing in Moroccan and Egyptian growing regions. Invest in membrane filtration capacity to reduce batch cycle times without Givaudan-scale fixed-asset intensity. Defend against biotechnology-driven extraction platforms by deepening analytical chemistry capabilities in Basel and Grasse talent clusters.
For New Entrants and Emerging Players: Launch via upcycled feedstock streams—grape pomace, citrus peels, coffee silverskin—offering negative raw-material cost and sustainability positioning. Target solid-dose nutraceutical applications in Germany and the United States where moisture-controlled powder formats face supply gaps. Pursue white-label manufacturing partnerships with regional cosmetic formulators lacking direct extraction relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual-registration burdens stretch R&D budgets across incompatible European and American regulatory timelines. Mid-scale extraction specialists with REACH-registered infrastructure and validated HPLC protocols present viable acquisition targets over a multi-year horizon. Monitor FDA cosmetic GMP rule finalization as inflection indicator for quality-system investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Growing Regions | Direct contracts with Moroccan rose and Egyptian jasmine cultivators insulate supply against climate disruption. |
| Membrane Filtration Technology Deployment | Skid-mounted units enable mid-scale French and Swiss producers to achieve pharmaceutical-grade purity. |
| REACH Registration Completion | ECHA substance characterization mandates filter non-compliant competitors and redirect volume toward validated producers. |
| Powder Format Capacity Addition | Spray-dried extracts with maltodextrin carriers serve moisture-sensitive nutraceutical applications in Germany. |
| Blockchain Traceability Implementation | Paris-headquartered beauty multinationals now specify carbon footprint limits and supply chain transparency in procurement contracts. |
Research Methodology
Multiple input streams—extraction technology specialists, cosmetic formulation executives, regulatory affairs leads at fragrance houses, and procurement officers at personal care multinationals—were reconciled against secondary validation from ECHA registration databases, FDA cosmetic ingredient filings, and customs trade records. Bottom-up volume modeling across herbal, floral, fruit, and vegetable extract categories was triangulated with top-down value estimates derived from REACH-registered producer capacity assessments.
Data-stream reconciliation anchored projections across the analysis window, with segmentation dimensions spanning botanical source, application target, physical state, and buyer archetype. CAGRs were derived from trend extrapolation of clean-label procurement patterns and fermented ingredient compatibility requirements. Forecast inputs incorporated propylene glycol price elasticity coefficients and tropical supply disruption probability weights.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory timeline slippage or petrochemical feedstock shock conditions. Projections reflect assumptions regarding ECHA enforcement intensity and FDA cosmetic GMP implementation pace. Material deviation in REACH registration thresholds or tropical climate patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Bidens Pilosa Extract Market
Extracts
Flower Extract Market
Extracts
Yucca Extract Material Market
Extracts
Global Azadirachtin Market
Extracts
Basil Extracts Market
Extracts
Kelp Extracts Market
Extracts
Helichrysum Oil Market
Extracts
Lavender Oil Market
Extracts
Lemon Balm Extract Market
Extracts
Turpentine Market
Extracts
Botanical CO2 Extracts Market
Extracts
Peru Balsam Extract Market
Extracts
Floral Extract Market
Extracts
Nootkatone Market
Extracts
Cornflower Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market