
 Copaiba Essential Oil Market | 2026-2036
Copaiba Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Copaiba Essential Oil Market Intelligence
Wellness centers are redrawing demand patterns for Copaiba essential oil, displacing traditional homecare users as the fastest-expanding buyer archetype. doTERRA International leverages direct-to-practitioner channels to capture this institutional shift. Young Living Essential Oils anchors its position through farm-to-bottle traceability programs in Latin American sourcing zones. Berjé Inc competes on pharmaceutical-grade certification, supplying compounding pharmacies with standardized oleoresin batches.
Copaiba essential oil comprises sesquiterpenes, primarily beta-caryophyllene, extracted from Copaifera tree oleoresin through steam distillation or CO2 supercritical methods, yielding a pale yellow liquid with woody-balsamic notes used for anti-inflammatory, antimicrobial, and fragrance applications. Steam distilled product dominates volume due to lower capital requirements and established equipment networks across Amazonian processing cooperatives. CO2 extracted variants command premium positioning in pharmaceutical and high-end cosmetics applications where residual solvent thresholds approach zero. Amber bottles lead packaging type selection, driven by UV-protection requirements that preserve terpene stability during the extended distribution cycles typical of natural ingredient supply chains.
Brazil's ANVISA oversees pharmaceutical registration pathways for Copaiba-derived products, while the USDA Organic and ISO 9235 standards govern cosmetic and aromatherapy claims in North American and European export markets. REACH compliance in Europe restricts volatile organic compound thresholds, forcing processors to document complete terpene profiles for cosmetics-bound shipments. Stakeholders must monitor evolving bioprospecting consent frameworks under the Nagoya Protocol, as digital traceability requirements for Amazonian botanicals tighten sourcing documentation obligations.
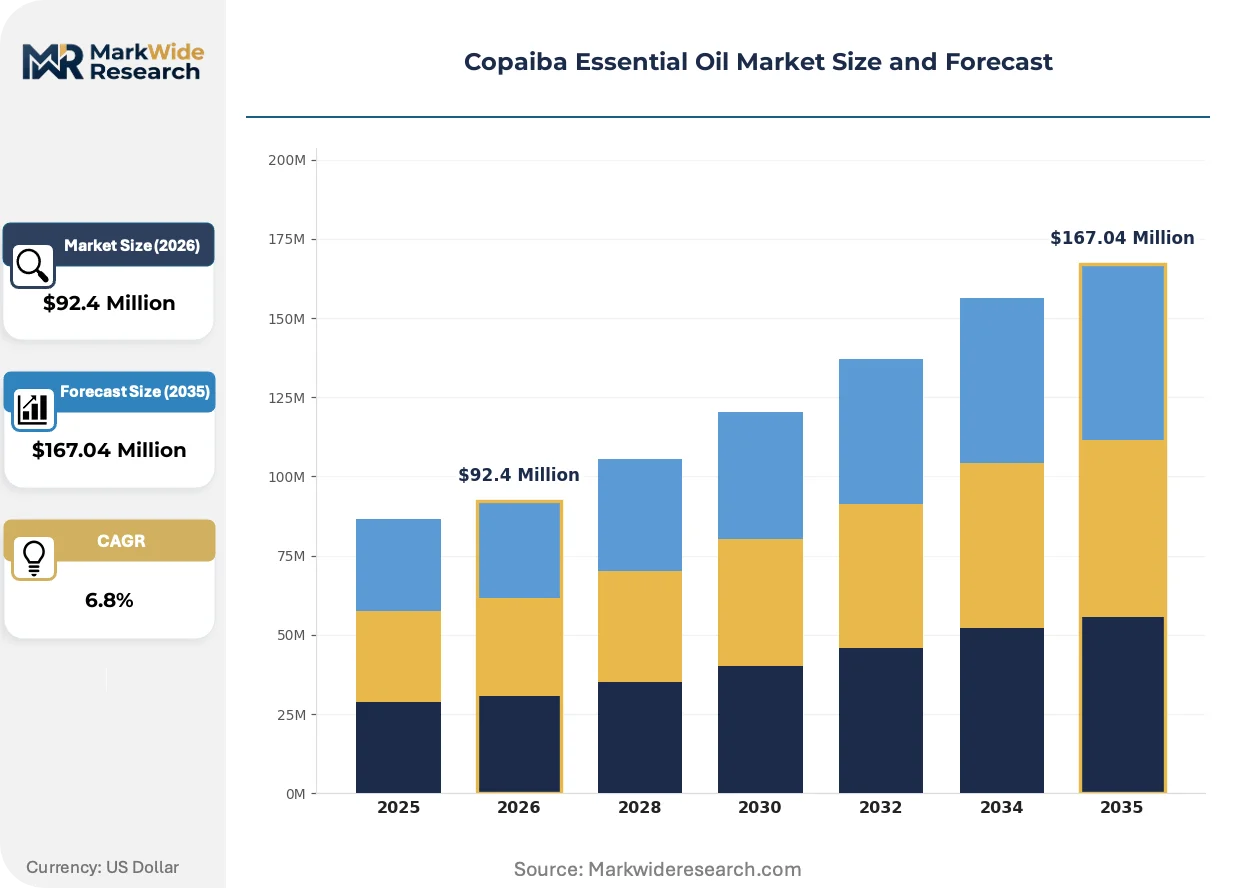
Market Dynamics
Pharmaceutical procurement of Copaiba oleoresin is compressing traditional aromatherapy demand patterns, as institutional buyers impose batch-level terpene certification requirements that homecare channels cannot satisfy.
Growth Catalysts
- REACH terpene disclosure mandates:ECHA documentation requirements for volatile organic compound profiles are filtering out unstandardized processors, concentrating volume among certified Amazonian cooperatives.
- Beta-caryophyllene isolation demand:Pharmaceutical formulators are expanding purchases of high-purity sesquiterpene fractions for topical anti-inflammatory development pipelines.
- Steam distillation infrastructure:Established equipment networks across Pará and Amazonas states are lowering capital barriers for new processor entrants.
Market Restraints
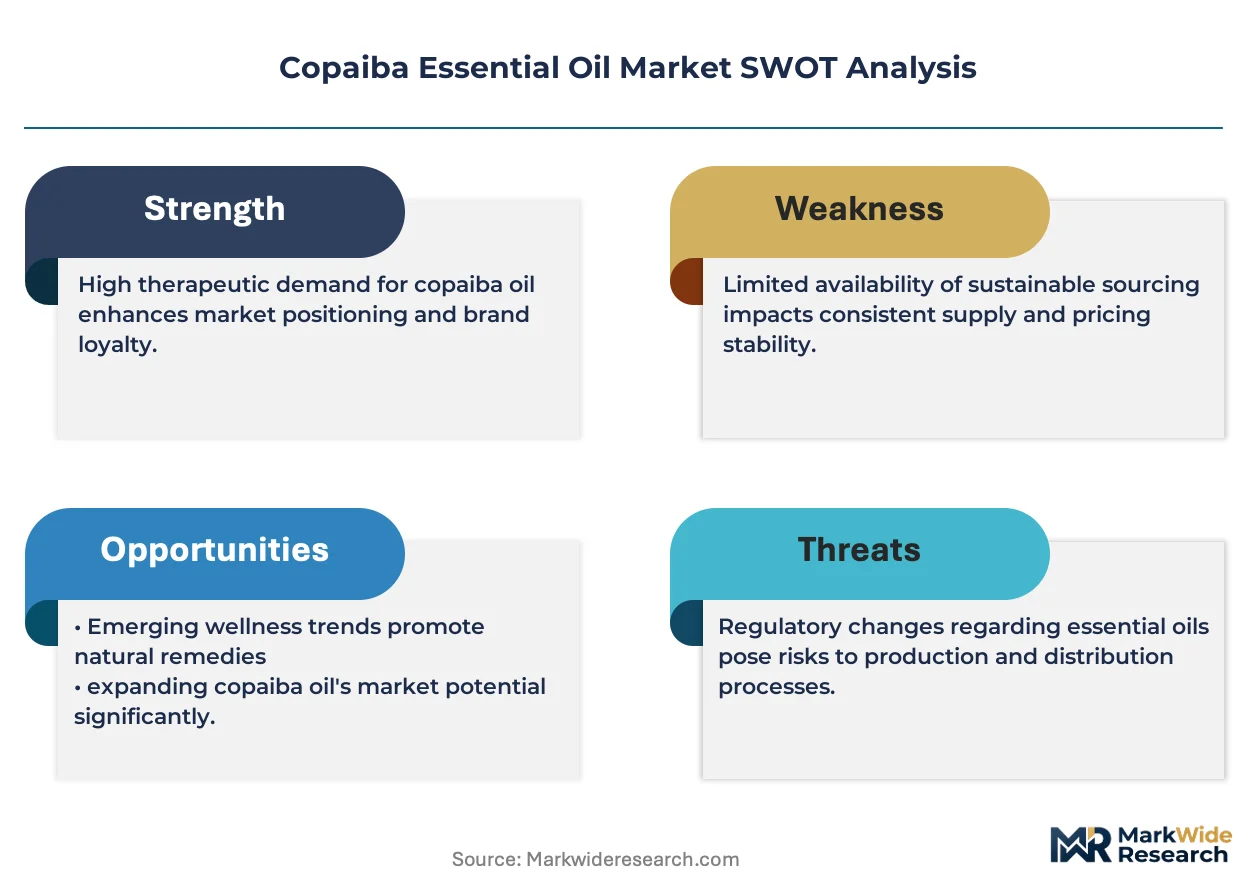
- Copaifera oleoresin yield volatility:Tapping frequency and seasonal rainfall patterns create 15-40% annual volume swings from individual trees.
- Brazilian sourcing concentration:Over 90% of commercial oleoresin originates from Amazonian extractive reserves, exposing buyers to localized climate and logistics disruptions.
- CO2 supercritical capex thresholds:Pharmaceutical-grade extraction requires capital outlays that cooperative processors cannot access without external financing.
Strategic Opportunities
- Nagoya Protocol bioprospecting frameworks:Digital traceability requirements for Amazonian botanicals are creating first-mover advantages for processors with documented prior informed consent systems.
- USDA Organic certification expansion:North American cosmetic brands are paying premiums for certified-organic Copaiba oil, opening price tiers above conventional steam-distilled grades.
- Direct-to-practitioner channels:Wellness centers are consolidating purchasing power away from retail aromatherapy distributors, enabling volume contracts with guaranteed purity specifications.
Industry Challenges
- ISO 9235 analytical chemistry capacity:Few Amazonian laboratories can perform the gas chromatography-mass spectrometry testing required for European cosmetics-bound shipments.
- ANVISA pharmaceutical registration timelines:Brazilian regulatory pathways for Copaiba-derived anti-inflammatory products extend 24-36 months, delaying revenue recognition for formulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copaiba Essential Oil Market |
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $167.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Distilled, CO2 Extracted, Solvent Extracted, Cold Pressed Application: Aromatherapy, Cosmetics, Personal Care, Natural Remedies, Pharmaceuticals End User: Wellness Centers, Beauty Salons, Pharmaceutical Companies, Homecare Users Packaging Type: Glass Bottles, Plastic Bottles, Dropper Bottles, Amber Bottles |
| Companies Covered | doTERRA International, Young Living Essential Oils, Berjé Inc, Plant Therapy Essential Oils, Rocky Mountain Oils, Edens Garden, Mountain Rose Herbs, Aura Cacia, Beraca Ingredients Naturais, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copaiba Essential Oil Market Strategic Shifts & Innovations
Extraction technology and compliance documentation are diverging into parallel tracks serving pharmaceutical and wellness end-uses with incompatible purity standards and capital requirements.
CO2 supercritical extraction is bifurcating the Copaiba oil supply base into pharmaceutical-grade and wellness-grade tiers. Compounding pharmacies and topical formulation developers are adopting CO2 methods for residual-solvent-free beta-caryophyllene concentrates. This technology compression is marginalizing steam-distilled product in high-value applications while expanding volume in basic aromatherapy channels.
REACH volatile organic compound thresholds are forcing processors to submit complete sesquiterpene profiles for every cosmetics-bound batch. ECHA documentation requirements have eliminated small-scale processors from European supply chains. Brazilian exporters are responding by consolidating testing contracts with São Paulo analytical laboratories capable of ISO 17025-compliant chromatography.
Practitioner-directed purchasing is displacing retail aromatherapy distribution in wellness applications. Spa chains and integrative medicine clinics are negotiating direct supply agreements with Amazonian cooperatives, bypassing traditional essential oil importers. This channel rotation is most visible in North American urban markets where wellness center density supports consolidated procurement volumes.
Copaiba Essential Oil Market Segmentation
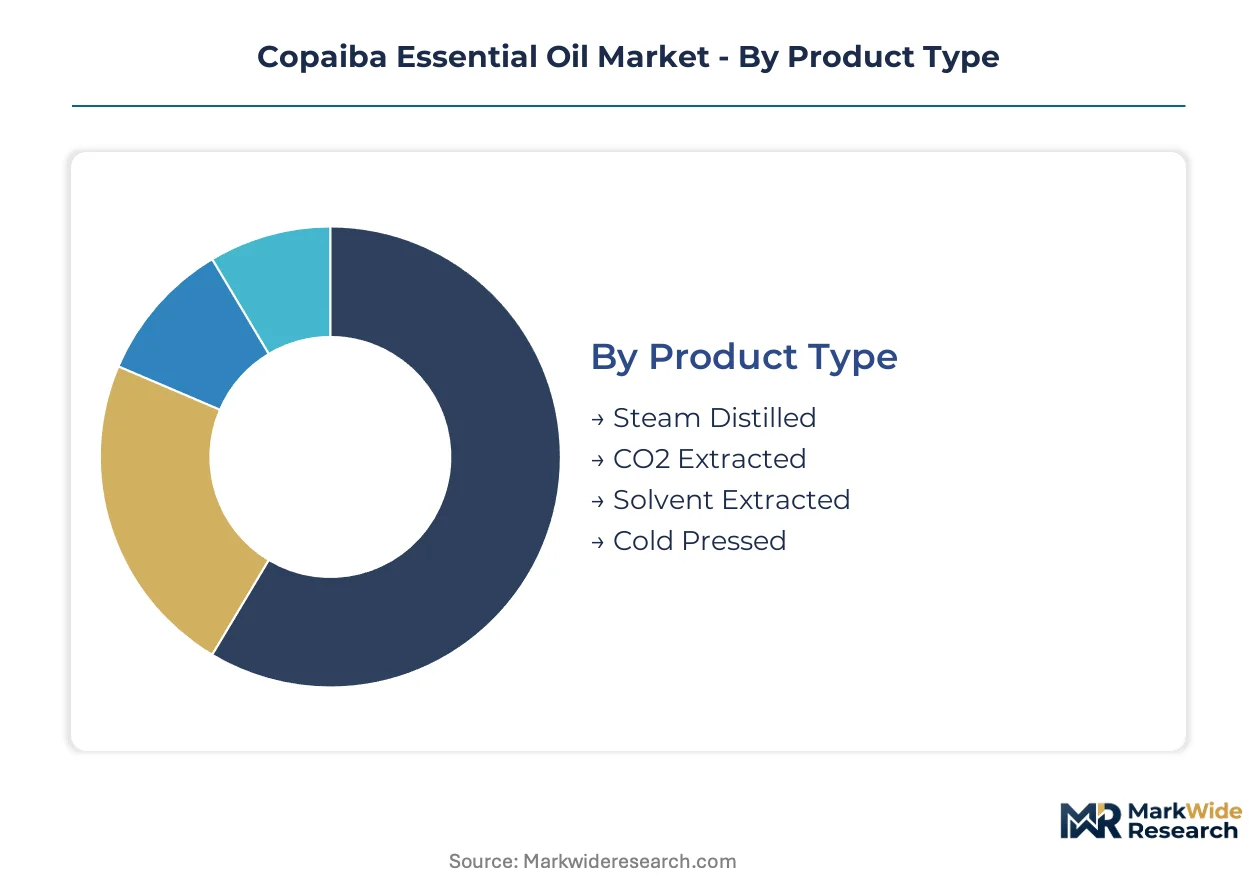
Channel economics in the Copaiba essential oil market diverge sharply across extraction methods and purity grades. Pharmaceutical procurement channels demand batch-certified CO2 extracts, while wellness retail channels absorb lower-cost steam-distilled volumes.
Product Type:
Steam-distilled Copaiba oil moves through established aromatherapy distributors and Amazonian cooperative networks, while CO2 extracts flow through pharmaceutical-grade certification channels with mandatory residual solvent testing.
- Steam Distilled:Dominates volume through lower capital requirements and established equipment networks across Pará and Amazonas processing cooperatives. Wellness centers and homecare users in São Paulo and Belém absorb the majority of output, constrained by batch-to-batch terpene variability that limits pharmaceutical uptake.
- CO2 Extracted:Yields pharmaceutical-grade oleoresin with near-zero residual solvents, commanding premium positioning in topical anti-inflammatory development pipelines. Compounding pharmacies in Germany and France specify CO2 methods for beta-caryophyllene isolation, though Brazilian cooperatives face capital access barriers for supercritical equipment.
- Solvent Extracted:Marginal share confined to industrial fragrance applications with less stringent purity thresholds.
- Cold Pressed:Minimal commercial presence due to low oleoresin yield and inconsistent sesquiterpene profiles.
Steam-distilled product dominates installed base. CO2 extracted variants are where expansion concentrates.
Application:
Margin structures vary threefold across application tiers, with pharmaceutical formulators paying certification premiums that cosmetics brands cannot justify.
- Aromatherapy:Traditional diffuser and topical use segments absorb standardized steam-distilled grades through retail and direct-to-practitioner channels.
- Cosmetics:REACH-compliant terpene disclosure mandates have concentrated European-bound volume among São Paulo-certified processors capable of ISO 17025 chromatography documentation.
- Personal Care:Mid-tier pricing segment serving North American natural product brands with USDA Organic certification requirements.
- Natural Remedies:Traditional medicine channels in Brazil's North region maintain steady demand for unstandardized oleoresin with documented community sourcing consent.
- Pharmaceuticals:Anti-inflammatory formulation pipelines are expanding purchases of high-purity beta-caryophyllene fractions, with ANVISA registration timelines extending revenue recognition cycles.
Cosmetics applications anchor current volume. Pharmaceutical development pipelines are climbing the fastest.
End User:
Procurement consolidation is shifting volume toward institutional buyers with analytical chemistry capabilities and long-term contracting power.
- Wellness Centers:Spa chains and integrative medicine clinics in North American urban markets are negotiating direct supply agreements with Amazonian cooperatives, bypassing traditional importers through consolidated procurement volumes.
- Beauty Salons:Mid-scale service providers source through regional distributors with limited batch certification requirements.
- Pharmaceutical Companies:Institutional buyers impose batch-level terpene certification that homecare channels cannot satisfy, compressing traditional aromatherapy demand patterns.
- Homecare Users:Retail-dependent segment facing displacement as wellness centers consolidate purchasing power.
Homecare users retain the broadest installed base. Wellness centers are gaining share fastest.
Packaging Type:
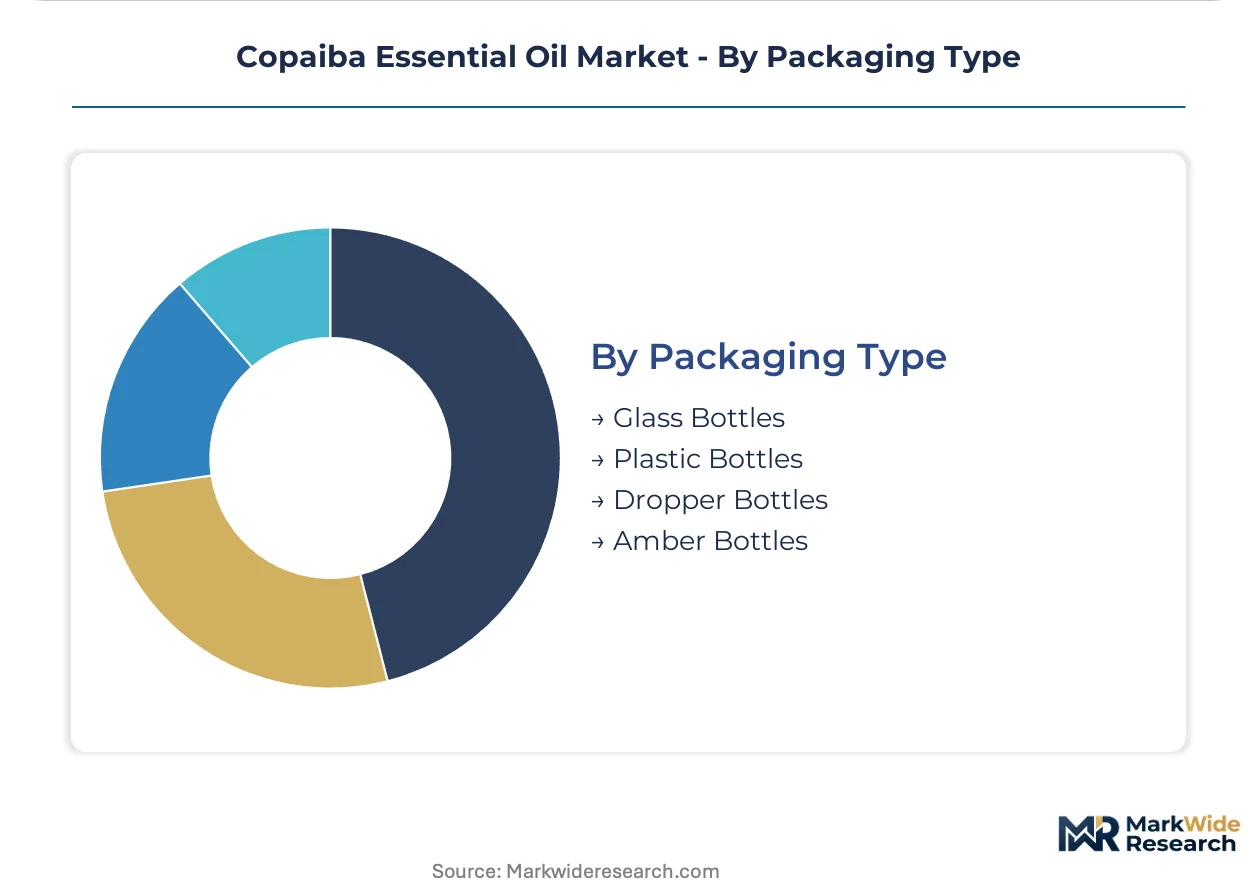
UV protection requirements and distribution cycle length determine packaging selection across premium and commodity tiers.
- Glass Bottles:Standard pharmaceutical and cosmetics packaging with inert material properties preserving terpene stability.
- Plastic Bottles:Cost-driven selection for high-volume aromatherapy channels with shorter distribution cycles.
- Dropper Bottles:Precision-dosing format preferred by practitioner-directed wellness applications.
- Amber Bottles:Lead selection for UV-sensitive sesquiterpene preservation during extended natural ingredient supply chains.
Amber bottles dominate premium channels. Dropper formats are expanding most quickly in practitioner-directed procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness centers in São Paulo and North American metropolitan markets are consolidating procurement power, displacing traditional retail aromatherapy channels as the dominant buyer archetype across sourcing geographies.
Brazil
Pará and Amazonas states host the densest concentration of Copaifera oleoresin tapping cooperatives, supplying over 90% of commercial volume. ANVISA pharmaceutical registration pathways extend 24-36 months for anti-inflammatory formulations, delaying revenue cycles for domestic processors. São Paulo analytical laboratories now handle ISO 17025-compliant chromatography for export-bound batches.
United States
Integrative medicine clinics in urban wellness corridors negotiate direct supply agreements with Amazonian cooperatives, bypassing traditional importers. USDA Organic certification governs cosmetic and aromatherapy claims for North American brands. Greater Los Angeles and New York Metro wellness center density supports consolidated procurement volumes exceeding regional distributor capacity.
Germany
Compounding pharmacies specify CO2-extracted beta-caryophyllene concentrates for topical anti-inflammatory development. REACH terpene disclosure mandates through ECHA filter unstandardized processors from cosmetics supply chains. Frankfurt and Hamburg serve as consolidation points for pharmaceutical-grade oleoresin distribution across European formulation labs.
France
High-end cosmetics manufacturers demand batch-level sesquiterpene certification that steam-distilled grades cannot satisfy. EU Cosmetics Regulation compliance elevates extraction and purity standards for Amazonian-sourced material. Paris-based fragrance houses maintain steady demand for woody-balsamic notes in premium perfume formulations.
Canada
Health Canada and PMRA oversee natural health product registration for Copaiba-derived anti-inflammatory claims. Toronto and Vancouver wellness markets import certified-organic grades at premiums above conventional steam-distilled tiers. British Columbia integrative health practitioners drive practitioner-directed purchasing patterns matching US urban corridors.
Copaiba Essential Oil Market Key Industry Players
Player mix skews toward vertically integrated wellness brands and pharmaceutical-grade ingredient suppliers. Market structure concentrates around three operational tiers: direct-to-practitioner wellness networks, farm-to-bottle traceability specialists, and compounding pharmacy certification providers. Dominant competitive moves include backward integration into Amazonian sourcing zones and portfolio diversification across steam-distilled and CO2 extraction grades.
Within the direct-to-practitioner tier, doTERRA International and Young Living Essential Oils exemplify wellness-brand archetypes with established Amazonian supply relationships. Berjé Inc occupies a position among pharmaceutical-grade certification specialists supplying standardized oleoresin batches to compounding pharmacies. These three entities represent distinct strategic positions: practitioner-channel capture, traceability program anchoring, and regulatory-grade batch certification.
| Leading Market Players |
|---|
| doTERRA International |
| Young Living Essential Oils |
| Berjé Inc |
| Plant Therapy Essential Oils |
| Rocky Mountain Oils |
| Edens Garden |
| Mountain Rose Herbs |
| Aura Cacia |
| Beraca Ingredients Naturais |
| Others |
Cost & Logistics Intelligence
Steam distillation capacity utilization across Pará and Amazonas cooperatives sets price floors for commodity-grade oleoresin while concentrating supply power among processors with ISO 17025 testing access. REACH compliance costs in Europe and ANVISA registration timelines in Brazil create divergent margin structures that reward certified exporters with pricing power over unstandardized competitors.
Pricing Analysis
Cost-plus contracts with beta-caryophyllene content indexation dominate pharmaceutical procurement, linking batch premiums to sesquiterpene assay results from São Paulo laboratories. Three-tier pricing structure across pharmaceutical-grade CO2 extracts, certified-organic steam-distilled grades, and conventional aromatherapy tiers reflects certification investment and residual solvent thresholds. Pricing pressure stems from wellness center consolidation demanding volume discounts that compress distributor margins. Homecare users exhibit highest price sensitivity, while compounding pharmacies in Germany and France absorb certification premiums without volume elasticity.
Supply Chain Analysis
Brazil produces over ninety percent of commercial Copaiba oleoresin through extractive reserve cooperatives in Pará and Amazonas states. Raw material flows draw from Copaifera tree tapping networks, amber bottle packaging from domestic glass manufacturers, and chromatography certification from São Paulo analytical laboratories. Single-source geographic concentration exposes buyers to Amazonian climate disruptions and logistics bottlenecks at Belém export terminals. Distribution runs through direct-to-practitioner channels for wellness centers, pharmaceutical-grade importers for European compounding pharmacies, and aromatherapy distributors for retail homecare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copaiba essential oil sits in early-cycle expansion as practitioner-directed procurement displaces retail aromatherapy channels and pharmaceutical formulators build anti-inflammatory development pipelines.
For Market Incumbents: Consolidate testing capacity partnerships with ISO 17025-certified São Paulo laboratories to defend batch certification margins against emerging cooperative processors. Deepen upstream control over Copaifera tapping rights in Pará extractive reserves to secure oleoresin supply ahead of Nagoya Protocol traceability requirements tightening consent documentation standards. For New Entrants and Emerging Players: USDA Organic certification fast-track offers entry path into North American cosmetic brand supply chains paying premiums above conventional grades. Target integrative medicine clinics in Greater Los Angeles and New York Metro corridors with direct supply agreements bypassing established aromatherapy importers. Lead with practitioner education programs demonstrating beta-caryophyllene anti-inflammatory mechanisms to build clinical credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with hybrid extraction capabilities spanning steam distillation and CO2 supercritical methods to serve divergent pharmaceutical and wellness demand tiers. Long-term viability rests on documented prior informed consent systems under Nagoya Protocol frameworks. Watch ANVISA registration approvals for topical anti-inflammatory formulations as inflection signal for pharmaceutical demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Testing Partnership | ECHA documentation requirements eliminate unstandardized processors from REACH-compliant supply chains. |
| Direct-to-Practitioner Channel Buildout | Wellness center consolidation in North American urban markets enables volume contracts with guaranteed purity specifications. |
| CO2 Supercritical Capacity Addition | Pharmaceutical-grade extraction captures premium positioning in topical anti-inflammatory development pipelines. |
| Nagoya Protocol Consent Documentation | Digital traceability requirements for Amazonian botanicals create first-mover advantages in bioprospecting frameworks. |
| USDA Organic Certification Expansion | North American cosmetic brands pay premiums for certified-organic grades above conventional steam-distilled tiers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of ANVISA registration filings, ECHA substance dossiers, and Brazilian customs export data to triangulate supply volumes and pricing structures. Primary interviews engaged cooperative processing managers in Pará and Amazonas, procurement leads at North American wellness center chains, regulatory affairs specialists at São Paulo analytical laboratories, and formulary directors at German compounding pharmacies. Secondary validation drew from USDA Organic certification databases, ISO 9235 standard documentation, and Nagoya Protocol national focal point records. Bottom-up cooperative capacity estimates and top-down pharmaceutical demand modeling were cross-checked for consistency.
Segmentation dimensions modeled include extraction method tier, application category, end-user archetype, and packaging format across the projection horizon. CAGRs were derived from volume trajectory analysis incorporating installed distillation capacity, pharmaceutical pipeline advancement rates, and wellness center expansion patterns. Industry-specific forecast inputs encompassed Copaifera oleoresin yield variability ranges and ANVISA registration timeline distributions.
Decision-makers should treat outputs as directional under sustained pharmaceutical interest in beta-caryophyllene isolation and stable Amazonian cooperative production capacity; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in regulatory approval timelines and bioprospecting consent framework enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Kelp Extracts Market
Extracts
Industrial Extractor Market
Extracts
Wild Yam Powder Market
Extracts
Bidens Pilosa Extract Market
Extracts
Yucca Extract Material Market
Extracts
Cochineal Extract Market
Extracts
Clary Sage Oil Market
Extracts
Belladonna Market
Extracts
Global Pine-Derived Chemicals Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Cassia Seed Extract Market
Extracts
Medicinal Plant Extracts Market
Extracts
Global Herbal Extract Market
Extracts
Marigold Essential Oil Market
Extracts
Global Ginseng Extracts Market
Extracts
Gum Turpentine Oil Market