
 Chlorophyll Extract Market | 2026-2036
Chlorophyll Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorophyll Extract Market Outlook
Supercritical CO2 extraction is narrowing the quality gap between artisanal and industrial chlorophyll production, compressing batch-to-batch variance in pigment concentration. BASF SE leverages its integrated agrochemical-to-specialty-chemical pipeline to secure alfalfa supply chains. DDW The Color House Inc. anchors North American natural colorant distribution through direct relationships with beverage formulators. British Chlorophyll Ltd. specializes in solvent-free extraction protocols for premium cosmetic-grade output.
Chlorophyll extract comprises magnesium-centered porphyrin complexes derived from photosynthetic plant tissue, typically standardized to copper chlorophyllin for enhanced stability in acidic food matrices. Industrial applications center on replacing synthetic dyes like FD&C Green No. 3 with plant-derived alternatives in beverage, confectionery, and oral care formulations. Powder extract commands the largest volume share due to extended shelf life and lower freight costs versus liquid variants. Dietary supplements represent the fastest-expanding application channel as copper chlorophyllin gains traction in internal deodorant and detoxification positioning. Alfalfa-sourced material dominates current supply, though spirulina-derived variants capture premium positioning in organic formulation segments.
EMA guidelines on novel food ingredients and EFSA purity specifications for chlorophyllin copper complex govern market access across European jurisdictions. FDA color additive regulations under 21 CFR 73.125 and USDA organic certification requirements shape product qualification pathways in United States commerce. Stakeholders must monitor evolving ECHA REACH dossier updates for copper chlorophyllin toxicity endpoints and adapt formulation strategies accordingly.
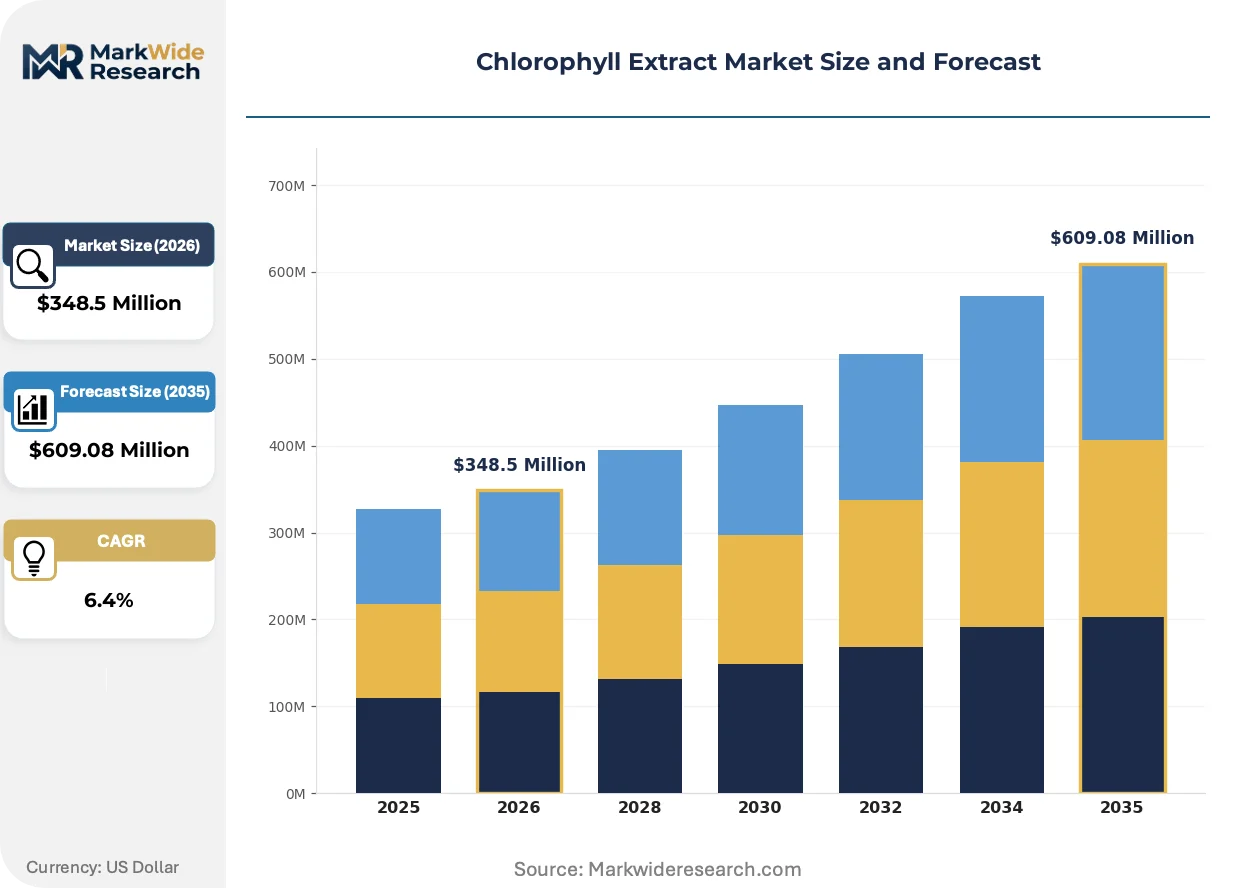
Market Dynamics
Clean-label mandates from EFSA and FDA are compressing synthetic colorant shelf space while supercritical CO2 extraction narrows quality variance between artisanal and industrial chlorophyll production. This regulatory-technological squeeze is redrawing competitive boundaries across food, cosmetic, and nutraceutical supply chains.
Growth Catalysts
- EFSA purity specifications:Tightened limits on copper chlorophyllin contaminants are disqualifying low-grade imports and opening premium shelf space for certified European suppliers.
- Spirulina cultivation:Organic-certified spirulina farms in France and Italy are capturing price premiums from cosmetic formulators seeking non-alfalfa provenance claims.
- Beverage reformulation:Major soft drink bottlers are replacing FD&C Green No. 3 with plant-derived alternatives in response to retailer clean-label mandates.
Market Restraints
- Alfalfa supply concentration:Overreliance on North American alfalfa crops exposes processors to drought-induced raw material volatility and pesticide residue spikes.
- Copper chlorophyllin stability ceiling:Acidic beverage matrices below pH 3.0 degrade pigment integrity, limiting application in citrus and functional drink segments.
- REACH dossier uncertainty:Pending ECHA toxicity endpoint updates for copper chlorophyllin are freezing capital commitments from risk-averse formulators.
Strategic Opportunities
- India nutraceutical channel:FSSAI's streamlined novel food ingredient pathway is opening dietary supplement applications previously blocked by import complexity.
- Cosmetic water-phase stability:Microencapsulation convergence with liposomal delivery systems is enabling colorant performance in aqueous skincare formulations.
- Direct-to-beverage-maker distribution:Bypassing traditional ingredient distributors through technical sales teams is capturing margin and formulation influence.
Industry Challenges
- Supercritical CO2 technician scarcity:Operational expertise for high-pressure extraction systems concentrates in German and Swiss equipment hubs, constraining capacity expansion.
- Organic certification timeline:USDA and EU organic equivalency negotiations are delaying cross-Atlantic product launches by 18-24 months for dual-certified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorophyll Extract Market |
| Market Size in 2026 | $348.5 Million |
| Market Size in 2035 | $609.08 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Capsule, Tablet Application: Food & Beverage, Dietary Supplements, Cosmetics, Pharmaceuticals Source: Alfalfa, Spirulina, Barley Grass, Wheatgrass Formulation Type: Organic, Conventional, Fermented, Freeze-Dried |
| Companies Covered | BASF SE, DDW The Color House Inc., British Chlorophyll Ltd., Global Essence Inc., Sensient Colors LLC, Merck Group, Chr. Hansen, Fengming Chlorophyll Co. Ltd, Kancor Ingredients Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorophyll Extract Market Strategic Shifts
Extraction technology maturation and regulatory stringency are compressing the viable supplier base while opening premium tiers for certified, stable, and traceable chlorophyll derivatives across food and personal care applications.
Supercritical CO2 extraction systems with integrated online spectrophotometric monitoring are rendering obsolete batch-based solvent extraction for high-purity cosmetic-grade chlorophyll. German equipment manufacturers are shipping these units to French and Italian natural colorant houses. The technology is compressing batch-to-batch variance from 15% to under 3% pigment concentration deviation.
EFSA's 2023 updated guidance on copper chlorophyllin specifications tightened heavy metal limits and mandated expanded stability testing for acidic food applications. European beverage formulators are reformulating portfolios to preempt compliance gaps. The regulation is accelerating substitution of non-compliant Asian imports with EU-sourced certified material.
Beverage procurement teams are consolidating supplier rosters and demanding integrated color-stability-technical service packages rather than commodity pigment transactions. This bundling is squeezing standalone distributors and favoring extraction houses with in-house application laboratories. The shift is most visible in German and Benelux carbonated soft drink supply chains.
Chlorophyll Extract Market Segmentation
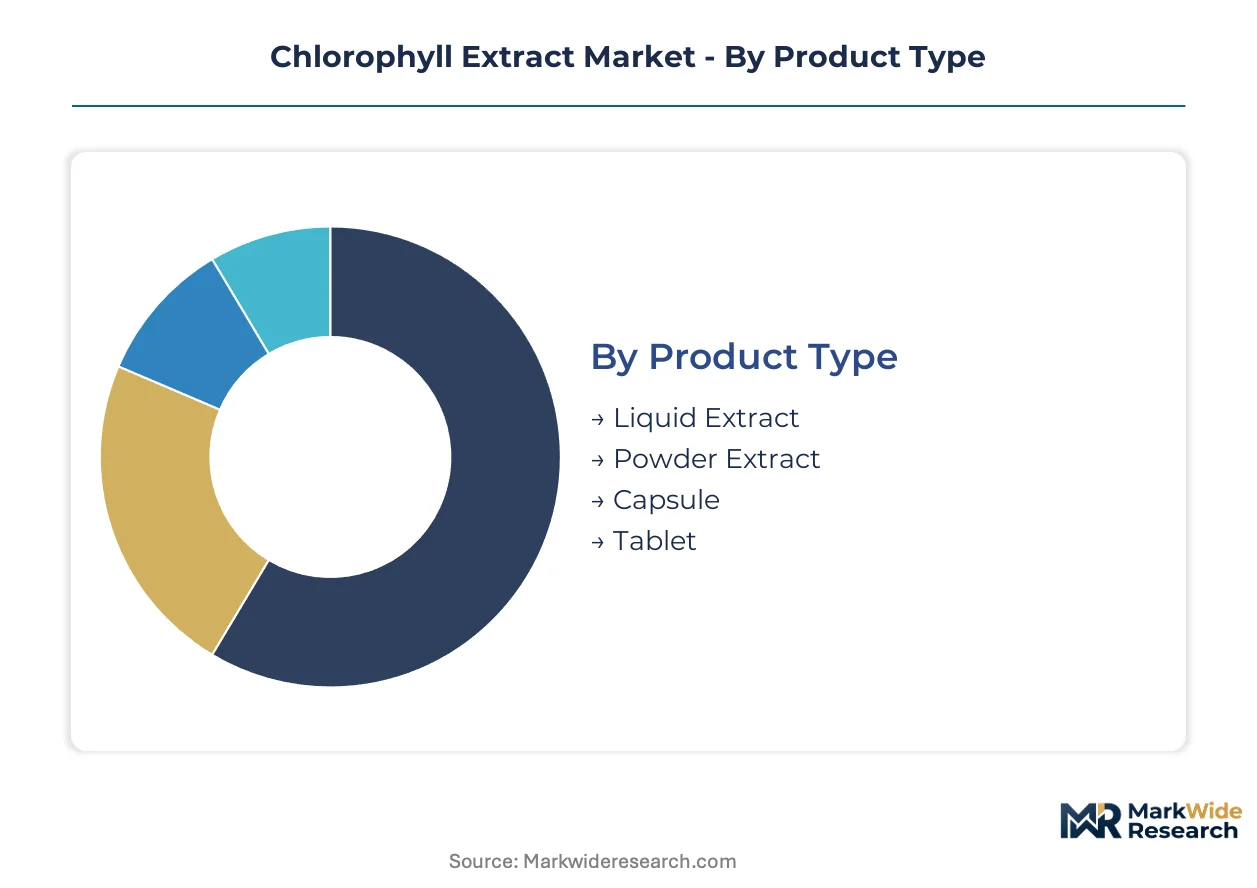
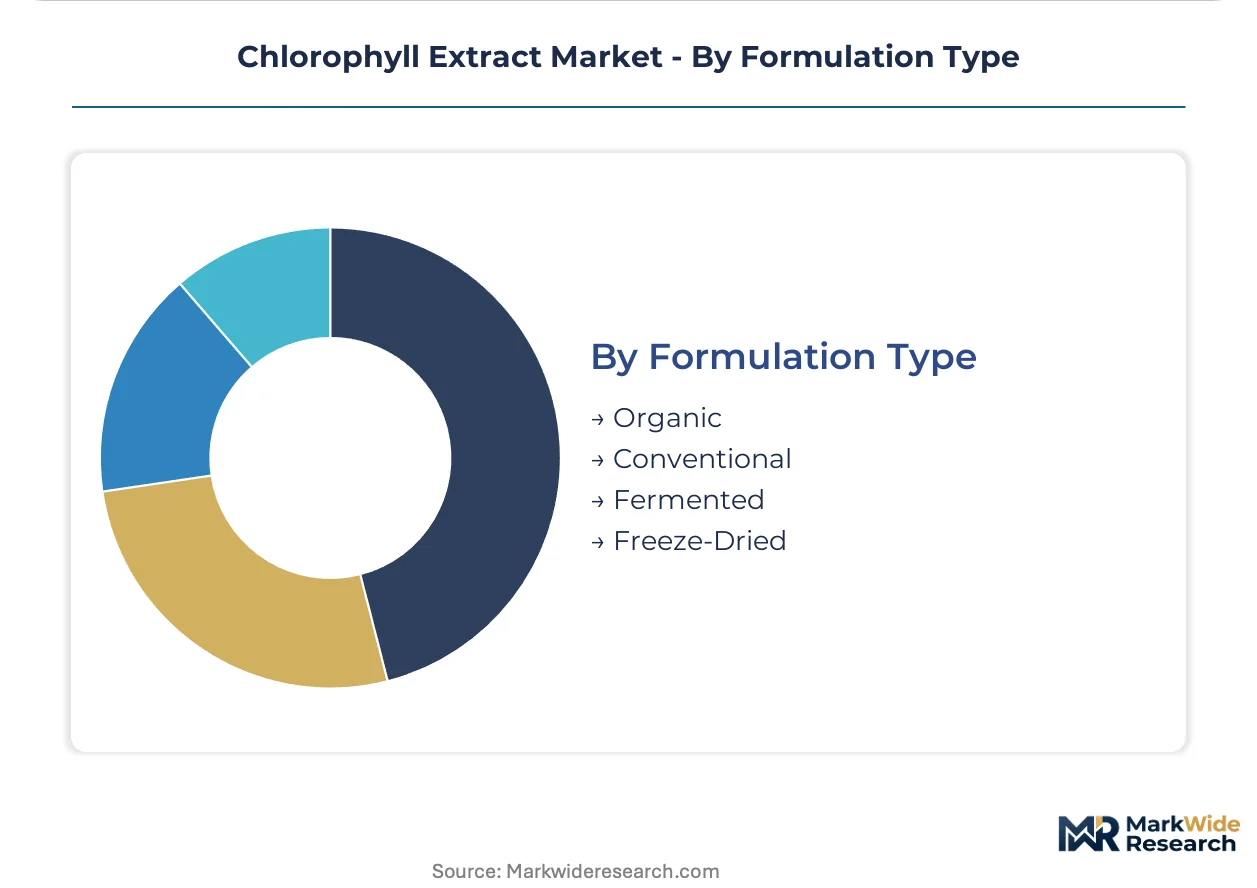
Chlorophyll extract segmentation reflects divergent technical requirements across food safety, cosmetic stability, and nutraceutical bioavailability standards. Formulators select product types and sources based on matrix compatibility, regulatory pathway, and provenance marketing claims.
Product Type:
Powder extract turns inventory fastest due to extended shelf life and lower freight costs, while liquid variants face accelerated spoilage curves and refrigerated logistics constraints.
- Liquid Extract:Aqueous suspensions of chlorophyllin copper complex deliver immediate solubility for beverage applications. German soft drink bottlers specify liquid formats for direct dosing into carbonated matrices, though pH stability below 3.0 remains unresolved.
- Powder Extract:Spray-dried or freeze-dried concentrates standardized to specific pigment content dominate industrial procurement. Extended ambient stability and reduced shipping weight make this format the default for multinational food manufacturers operating across EFSA jurisdictions.
- Capsule:Encapsulated copper chlorophyllin targets dietary supplement channels with precise unit dosing. FSSAI's novel food ingredient pathway in India is unlocking capsule uptake previously blocked by import complexity.
- Tablet:Compressed formulations with excipient matrices for controlled release. Tablet production concentrates with contract manufacturers serving direct-to-consumer nutraceutical brands.
Powder extract anchors the volume base while liquid extract gains share at the steepest rate among beverage reformulators.
Application:
Cost tiers stratify sharply: food and beverage procurement optimizes per-kilogram pigment cost, while cosmetic formulators absorb 3-5x premiums for solvent-free extraction certificates.
- Food & Beverage:Natural colorant replacement for FD&C Green No. 3 in confectionery, dairy, and beverage matrices. EFSA's tightened heavy metal limits are disqualifying non-compliant Asian imports and opening shelf space for certified European suppliers.
- Dietary Supplements:Copper chlorophyllin positioned for internal deodorant and detoxification claims. This channel is expanding most quickly as spirulina-sourced variants capture organic formulation premiums in France and Italy.
- Cosmetics:Water-phase colorant applications in skincare and oral care. Microencapsulation convergence with liposomal delivery systems is enabling stability in aqueous formulations previously inaccessible to chlorophyll derivatives.
- Pharmaceuticals:Wound healing and odor control applications with drug-device classification requirements. Regulatory pathway complexity limits participation to extraction houses with dedicated pharmaceutical quality systems.
Food and beverage commands the procurement volume while dietary supplements demonstrate the steepest expansion trajectory.
Source:
Supply geography dictates certification timelines: North American alfalfa integrates fastest into conventional supply chains, while French and Italian spirulina farms carry 18-24 month organic equivalency delays.
- Alfalfa:Medicago sativa-derived chlorophyll dominates current industrial supply through established dehydration and extraction infrastructure. Drought-induced volatility in North American crop yields exposes processors to raw material price spikes and pesticide residue compliance risks.
- Spirulina:Arthrospira platensis cultivation in controlled photobioreactor systems delivers organic-certified material with non-allergen provenance claims. French and Italian farms command price premiums from cosmetic formulators seeking alfalfa-free positioning.
- Barley Grass:Hordeum vulgare young leaf extracts positioned for premium nutraceutical applications. Japanese and Australian suppliers specialize in juice powder formats for functional beverage integration.
- Wheatgrass:Triticum aestivum shoot extracts competing in the same premium channel as barley grass. Smaller cultivation footprint limits scale relative to alfalfa and spirulina alternatives.
Alfalfa anchors the volume base while spirulina gains share at the steepest rate among organic-certified suppliers.
Formulation Type:
Customer procurement patterns bifurcate: multinational food manufacturers default to conventional formats for cost optimization, while indie cosmetic brands and premium supplement lines specify organic or fermented variants for narrative differentiation.
- Organic:USDA and EU organic certified material requiring segregated supply chains from cultivation through extraction. Dual-certification delays of 18-24 months constrain cross-Atlantic product launches for suppliers seeking both designations.
- Conventional:Standard agricultural input protocols with conventional pesticide and fertilizer allowances. This format dominates commodity pigment transactions where provenance claims carry minimal pricing power.
- Fermented:Bioprocessed variants with enhanced bioavailability positioning for nutraceutical applications. Korean and Japanese suppliers lead fermentation technology integration for chlorophyll derivative modification.
- Freeze-Dried:Low-temperature dehydration preserving heat-sensitive pigment structures. Premium cosmetic and pharmaceutical applications specify freeze-dried material for maximum chlorophyll integrity.
Conventional formulation anchors the volume base while organic gains share at the steepest rate among clean-label mandated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extraction houses export copper chlorophyllin to North American beverage formulators, while French and Italian spirulina farms supply organic-certified material to premium cosmetic laboratories across the Atlantic.
United States
Soft drink bottlers in Atlanta and Chicago drive reformulation from synthetic FD&C dyes to plant-derived alternatives. FDA color additive regulations under 21 CFR 73.125 govern qualification pathways. California-based natural colorant distributors maintain direct technical service relationships with beverage procurement teams.
Germany
Carbonated beverage manufacturers and cosmetic formulators cluster in the Rhine-Ruhr and Bavarian industrial corridors. EFSA purity specifications for copper chlorophyllin heavy metal limits shape supplier selection. Supercritical CO2 equipment manufacturers in Baden-Württemberg ship extraction systems to French and Italian natural colorant houses.
France
Organic-certified spirulina cultivation in Provence-Alpes-Côte d'Azur commands price premiums from cosmetic brands seeking non-alfalfa provenance. ANSM guidelines on cosmetic colorant safety intersect with EU REACH dossier requirements. Lyon-based extraction specialists supply solvent-free chlorophyll derivatives to Paris-region skincare laboratories.
Italy
Natural ingredients processors in Emilia-Romagna serve domestic confectionery and regional beverage markets. EMA guidelines on novel food ingredients govern cross-border trade into German and Benelux supply chains. Bologna-area natural colorant houses specialize in organic-certified spirulina derivatives for export to French cosmetic formulators.
India
Dietary supplement contract manufacturers in Maharashtra and Gujarat expand copper chlorophyllin capsule production for domestic and export markets. FSSAI's streamlined novel food ingredient pathway unlocks applications previously blocked by import complexity. Mumbai-based nutraceutical distributors build technical sales capabilities to bypass traditional ingredient intermediaries.
Chlorophyll Extract Market Competitive Environment
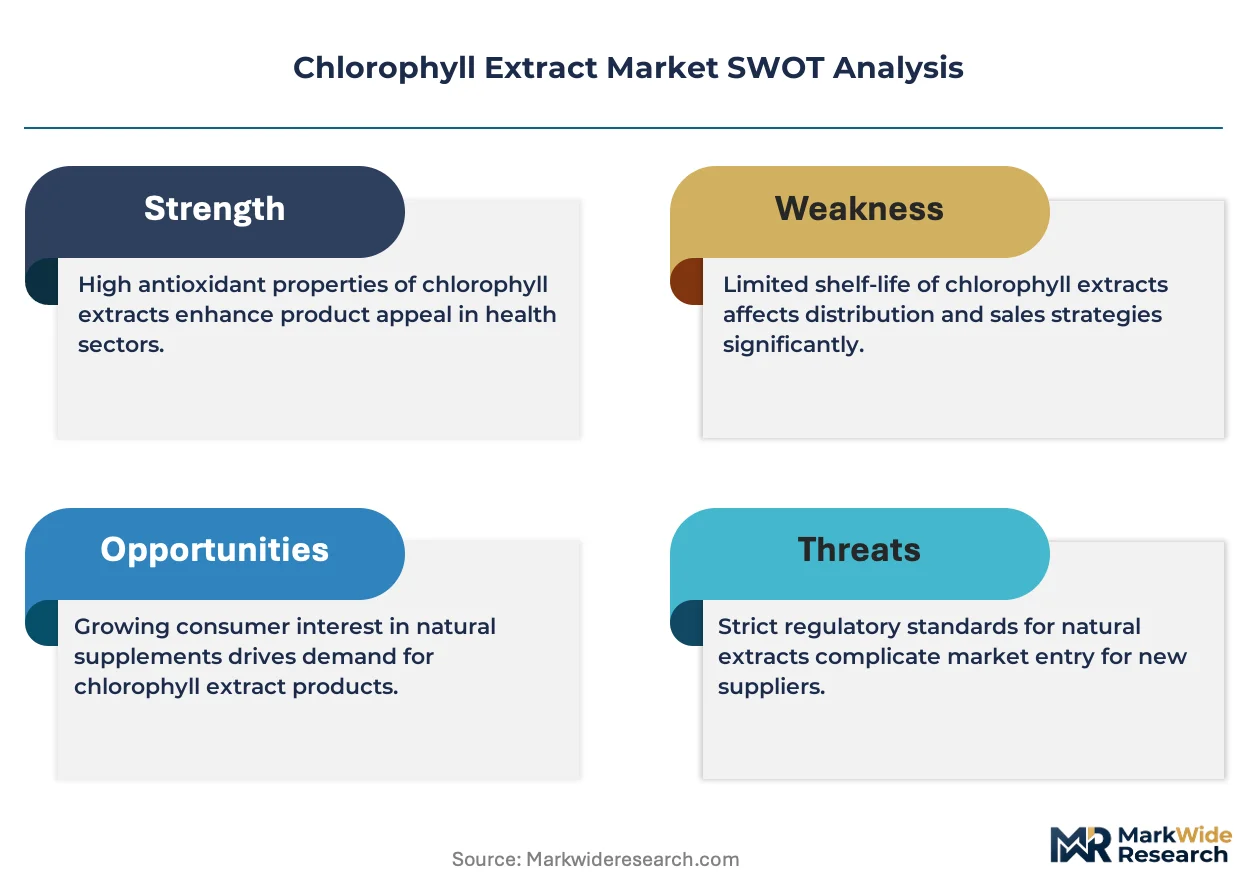
On the supply side, the industry is consolidating around extraction houses with integrated application laboratories and certified supply chains. Tiered competitive positioning separates multinational chemical conglomerates with captive agrochemical pipelines from specialized natural colorant houses and regional spirulina cultivators. Dominant competitive moves include backward integration into alfalfa cultivation and direct-to-beverage-maker distribution bypassing traditional ingredient wholesalers.
Within the multinational chemical tier, BASF SE anchors integrated agrochemical-to-specialty-chemical positioning through its German corporate structure. Among specialized natural colorant distributors, DDW The Color House Inc. represents North American beverage channel focus, while British Chlorophyll Ltd. exemplifies solvent-free extraction specialization for premium cosmetic applications. These three entities occupy distinct competitive positions based on supply chain depth, geographic orientation, and end-market certification requirements.
| Leading Market Players |
|---|
| BASF SE |
| DDW The Color House Inc. |
| British Chlorophyll Ltd. |
| Global Essence Inc. |
| Sensient Colors LLC |
| Merck Group |
| Chr. Hansen |
| Fengming Chlorophyll Co. Ltd |
| Kancor Ingredients Ltd. |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's supercritical CO2 equipment manufacturing cluster dictates extraction capacity deployment across European natural colorant houses, with German system availability constraining French and Italian processors' ability to capture EFSA-mandated premium pricing tiers. This geographic concentration of high-pressure extraction expertise creates asymmetric pricing power between equipment-limited artisanal suppliers and integrated multinational processors.
Pricing Analysis
Supercritical CO2 extraction technology commands a 40-60% premium over solvent-based legacy systems, compressing margins for non-upgraded processors while enabling certified houses to capture EFSA-tier price premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and stability performance, with organic-certified spirulina-derived material absorbing the highest premiums from cosmetic formulators. Cost compression in conventional alfalfa-sourced powder extract is intensifying because drought-induced raw material volatility exposes non-integrated processors to margin erosion. Food and beverage procurement teams demonstrate the highest price sensitivity, while cosmetic laboratories absorb substantial premiums for solvent-free extraction certificates and batch-to-batch consistency guarantees.
Supply Chain Analysis
Alfalfa feedstock draws from North American cultivation regions, spirulina biomass from French and Italian photobioreactor farms, and supercritical CO2 equipment from German precision engineering centers. Raw material dependencies center on alfalfa crop yields, spirulina cultivation density, and high-pressure pump systems with specialized sealing technology. Single-source vulnerability concentrates in North American alfalfa supply exposed to drought-induced yield volatility and pesticide residue compliance failures. Distribution runs through direct technical sales relationships between extraction houses and beverage formulators, bypassing traditional ingredient distributors in German and Benelux supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling expands faster than commodity pigment transactions, with beverage procurement teams consolidating supplier rosters around integrated color-stability-application support packages rather than standalone ingredient purchases.
For Market Incumbents: Harden EFSA certification moats by investing in expanded stability testing infrastructure for acidic beverage applications, preempting disqualification of non-compliant Asian imports. Deepen upstream control over alfalfa cultivation through contract farming arrangements in drought-resilient North American regions, reducing exposure to raw material price spikes and pesticide residue compliance failures. Capture formulation influence by embedding technical sales teams directly with Atlanta and Chicago soft drink bottlers, bypassing distributor margin extraction. For New Entrants and Emerging Players: Pursue India's dietary supplement capsule channel where FSSAI's streamlined novel food ingredient pathway unlocks applications previously blocked by import complexity. Target organic-certified spirulina cultivation in Provence-Alpes-Côte d'Azur and Emilia-Romagna, capturing price premiums from cosmetic formulators seeking non-alfalfa provenance claims unavailable from established North American suppliers. Differentiate through microencapsulation convergence with liposomal delivery systems for aqueous skincare formulations. For Investors and Strategic Acquirers: Carve-out targets emerge from agrochemical conglomerates seeking to divest non-core specialty chemical divisions with captive alfalfa supply chains and EFSA-certified extraction infrastructure. Long-term viability hinges on regulatory compliance automation and direct-to-beverage-maker distribution capabilities rather than commodity pigment scale. Watch ECHA REACH dossier updates for copper chlorophyllin toxicity endpoints as the signal indicating capital commitment resumption from risk-averse formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alfalfa Cultivation | Captive supply from North American contract farms reduces drought exposure and pesticide residue compliance risks. |
| Supercritical CO2 Capacity Expansion | German equipment deployment enables EFSA-tier certification and compresses batch-to-batch variance below 3%. |
| Direct-to-Beverage-Maker Distribution | Technical sales teams embedded with Atlanta and Chicago bottlers capture margin and formulation influence. |
| Organic Spirulina Cultivation Scale-Up | French and Italian photobioreactor farms command cosmetic premiums for non-alfalfa provenance claims. |
| Microencapsulation Technology Partnership | Liposomal delivery convergence enables aqueous skincare applications previously inaccessible to chlorophyll derivatives. |
Study Parameters
A standing panel of extraction plant managers, beverage procurement leads at multinational soft drink bottlers, natural colorant distribution channel partners, and cosmetic formulation R&D directors provided ongoing calibration against operational realities. Primary interviews with these stakeholders combined with secondary validation from EFSA guidance documents, FDA color additive regulations under 21 CFR 73.125, ECHA REACH dossier updates, and customs trade data on alfalfa and spirulina biomass imports. Bottom-up volume modeling across product types, applications, sources, and formulation types triangulated against top-down market sizing from identified supplier capacities.
Scenario-bracketing framed demand trajectories across the analysis window, with segmentation dimensions modeling product format preferences, application channel growth rates, source material certification tiers, and geographic regulatory clusters. CAGRs derived from fitted growth curves applied to base-year estimates, adjusted for EFSA purity specification enforcement timelines and FSSAI pathway implementation in India. Industry-specific forecast inputs included supercritical CO2 equipment installation rates and organic equivalency negotiation progress between USDA and EU authorities.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, drought frequency in North American alfalfa regions, or euro-dollar exchange rates affecting German equipment exports would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Cross-checking against EFSA import inspection data and beverage manufacturer reformulation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Global Rose Oils Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Nicotinic Acid Market
Extracts
Floral Extract Market
Extracts
Nigella Sativa Extract Market
Extracts
Asia-Pacific Botanical Extract Market
Extracts
Medicinal Plant Extracts Market
Extracts
Tagetes Oil Market
Extracts
Nootkatone Market
Extracts
Organic Herbal Extracts Market
Extracts
Sandalwood Oil Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Plum Extract Market
Extracts
Wild Yam Powder Market
Extracts
Hydroglycolic Extracts Market
Extracts
Peppermint Oil Market