
 Valerian Root Powder Market | 2026-2036
Valerian Root Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Valerian Root Powder Market Analytics
Skilled botanical extract technicians are unwinding supply constraints as European and North American facilities expand valerian processing capacity. Stanford Advanced Materials leverages its materials science expertise to secure high-purity raw botanical inputs. Pharmanager Ingredients anchors its position through specialized extraction protocols for European pharmaceutical clients. Lonier Herb Bio-Technology dominates cultivation networks across several Asian sourcing regions.
Valerian root powder comprises dried, milled rhizome and stolon material from Valeriana officinalis, typically standardized to valerenic acid concentrations between 0.3% and 0.8% for commercial applications. The powder serves primarily as a sedative and anxiolytic ingredient in dietary supplements, functional foods, and traditional herbal preparations. Organic valerian root powder commands premium positioning as clean-label formulations displace conventional extracts in Western European and North American health stores. Sleep aid applications lead volume consumption, while anxiety relief formulations represent the fastest-growing application segment as clinical validation accumulates. Online retail channels are capturing margin pools previously held by brick-and-mortar pharmacies, particularly among fitness enthusiasts and individual consumers seeking subscription-based replenishment.
The FDA's Current Good Manufacturing Practice framework for dietary supplements shapes quality thresholds for US-bound valerian products, while EFSA and national European regulators enforce botanical-specific safety assessments under the EU Food Supplements Directive. REACH compliance adds chemical safety documentation burdens for extract solvents and processing aids used in European manufacturing. Stakeholders must monitor evolving pharmacovigilance requirements for herbal sedatives as regulators weigh benefit-risk profiles against synthetic alternatives.
Market Dynamics
The valerian root powder market is experiencing acute supply chain recalibration as European and North American formulators decouple from concentrated Asian sourcing clusters. Regulatory divergence between FDA dietary supplement guidance and EU Novel Food requirements is forcing dual-track compliance investments that reshape competitive economics.
Growth Catalysts
- EU Novel Food standardization:The regulation's extract purity mandates are accelerating consolidation among certified European processors capable of pharmaceutical-grade documentation.
- Sleep aid formulations:Nutraceutical manufacturers are expanding valerian procurement as clinical validation accumulates for non-habit-forming sedative alternatives.
- German pharmacy networks:Traditional herbal medicine distribution channels maintain robust consumer access points that sustain premium positioning for certified organic grades.
Market Restraints
- Valerenic acid volatility:Raw botanical valerenic acid concentrations fluctuate seasonally, compressing margin predictability for standardized extract producers.
- Asian cultivation concentration:Sourcing gravity in Chinese and Indian growing regions exposes supply continuity to climate and trade policy disruptions.
- Synthetic melatonin substitution:Laboratory-produced sleep aids at lower unit economics threaten valerian's cost-positioning in mass-market supplement aisles.
Strategic Opportunities
- Subscription wellness platforms:Direct-to-consumer replenishment models are capturing margin pools previously held by brick-and-mortar pharmacy intermediaries.
- Anxiety relief applications:Emerging clinical trials for generalized anxiety disorder indications open formulation expansion beyond sleep-centric positioning.
- Clean-label displacement:Organic certification and solvent-free extraction protocols command pricing premiums as consumers reject conventional hexane-processed alternatives.
Industry Challenges
- Botanical authentication expertise:Shortages of trained phytochemists capable of valerenic acid quantification and adulterant detection constrain quality assurance scaling.
- REACH documentation burdens:European chemical safety filing requirements for extraction solvents extend product launch timelines and elevate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valerian Root Powder Market |
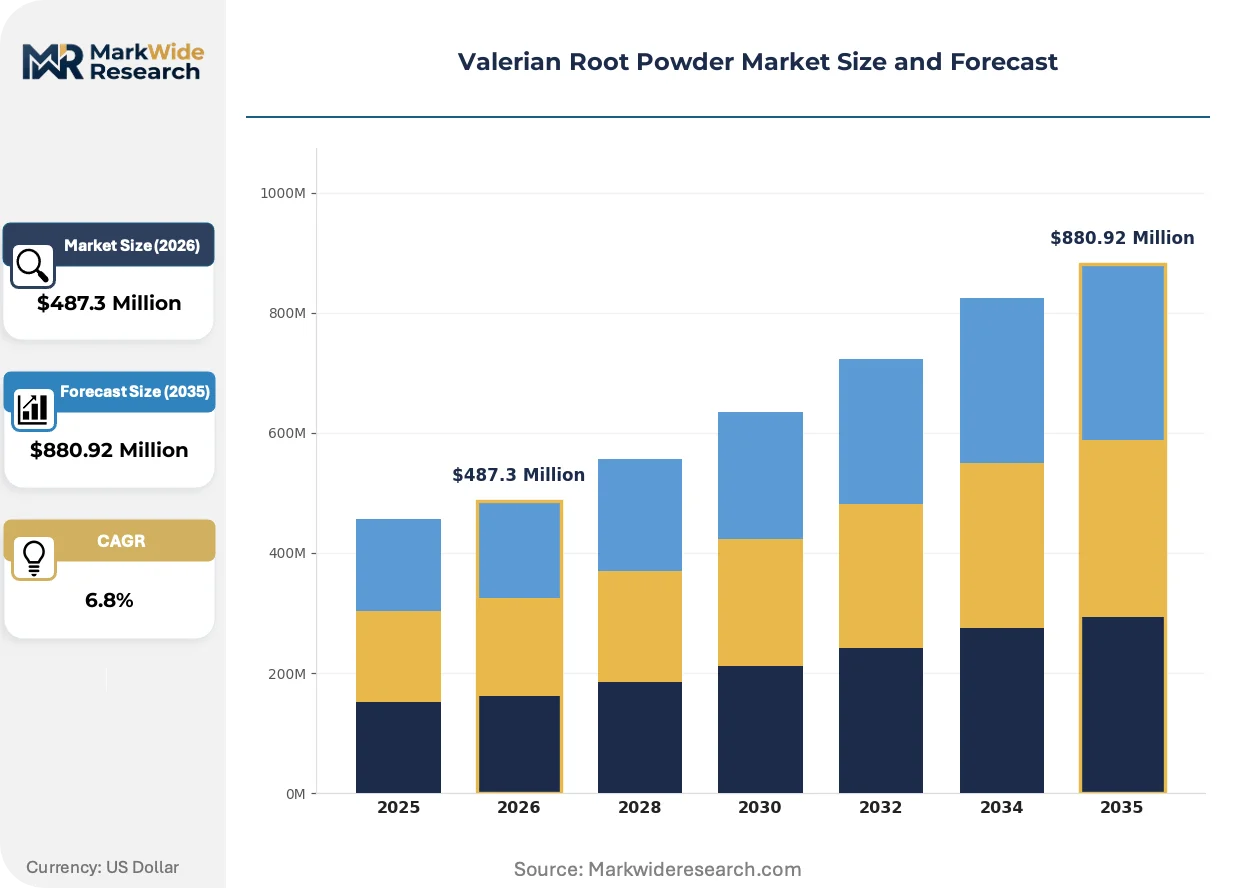
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Extract, Powder Application: Sleep Aid, Anxiety Relief, Dietary Supplements, Herbal Remedies Distribution Channel: Online Retail, Health Stores, Pharmacies, Specialty Stores End User: Individual Consumers, Health Practitioners, Nutraceutical Companies, Fitness Enthusiasts |
| Companies Covered | Stanford Advanced Materials, Pharmanager Ingredients, Artemis Nutraceuticals, Lonier Herb Bio-Technology, Jeeva Organic, Herbal Apothecary, Paninkret, Medikonda Nutrients, EUROMED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valerian Root Powder Market Evolving Landscape
Supercritical CO2 extraction protocols are redefining quality benchmarks across the valerian processing landscape. These advances compress production timelines while elevating active compound retention, forcing legacy solvent-based operations into defensive capital deployment.
Supercritical fluid extraction systems deploy pressurized carbon dioxide to isolate valerenic acids without thermal degradation or residual solvents. Premium organic brands and pharmaceutical contract manufacturers are adopting these systems at accelerated cadences. This technology is displacing conventional ethanol and hexane extraction infrastructure, devaluing existing capital bases among conventional processors.
REACH compliance deadlines for botanical processing aids are tightening chemical safety documentation requirements across European manufacturing. ECHA registration obligations now extend to ethanol suppliers and solvent recovery systems used in valerian extraction. German and Swiss extract houses are absorbing these costs fastest, while smaller Italian and Spanish operators face facility consolidation pressures.
Clean-label certification is redirecting procurement priorities among Western European and North American formulators. Subscription-based wellness platforms and fitness-oriented direct-to-consumer brands now specify organic, solvent-free valerian grades as table-stake requirements. This preference shift is most visible in German pharmacy chains and US specialty health retailers, where certified organic skus command shelf space advantages over conventional alternatives.
Valerian Root Powder Market Segmentation
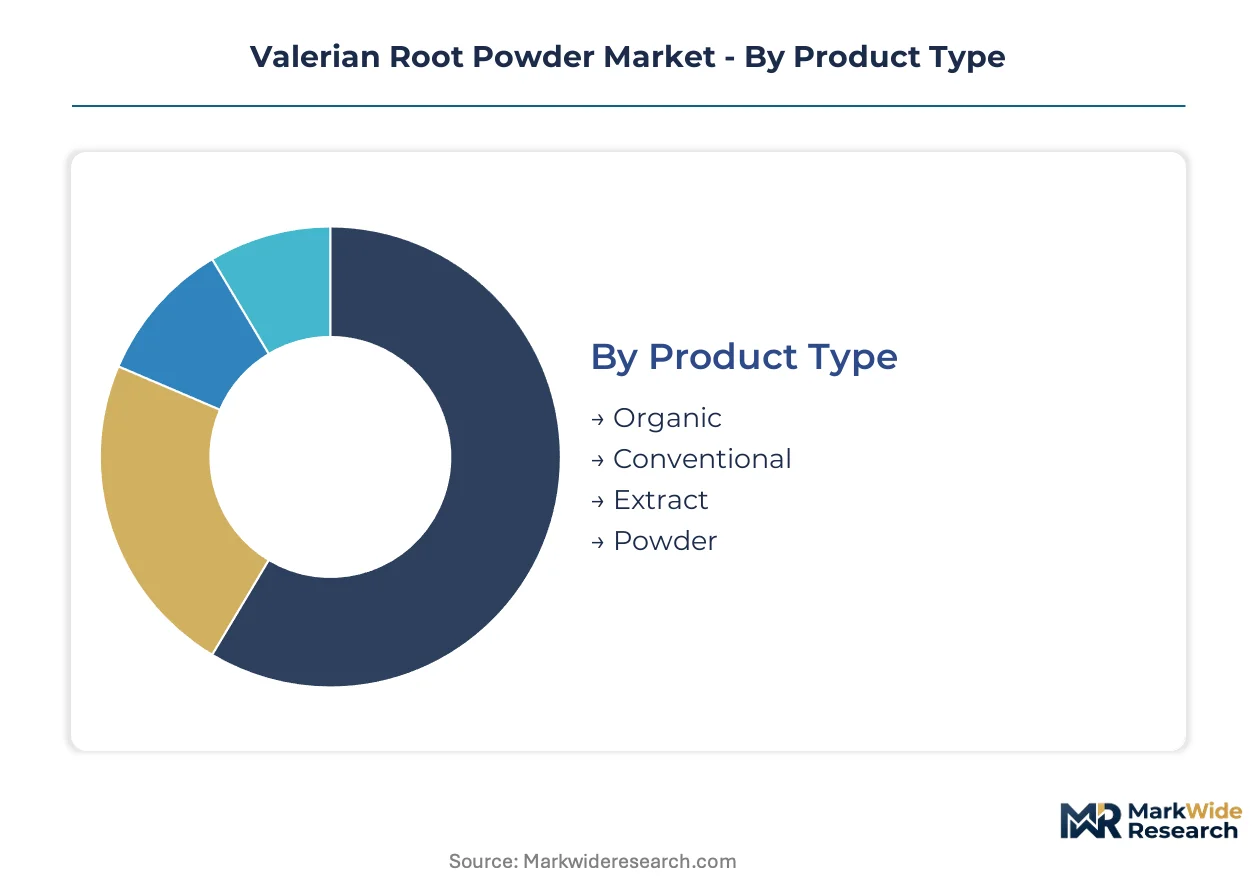
Segmentation in the valerian root powder market reveals how certification tiers, application positioning, and channel economics split margin capture across the value chain. Understanding these fault lines exposes where procurement power concentrates and which customer types sustain premium pricing.
Product Type:
Margin pools concentrate heavily in certified organic grades where clean-label premiums offset higher cultivation and processing costs.
- Organic:Cultivated without synthetic pesticides and processed through solvent-free extraction protocols, commanding shelf space advantages in German pharmacy chains and US specialty health retailers. Demand clusters among subscription wellness platforms and fitness-oriented direct-to-consumer brands that specify organic certification as table-stake requirements.
- Conventional:Standard cultivation with conventional pest management and hexane or ethanol extraction, serving mass-market supplement aisles where unit economics face pressure from synthetic melatonin alternatives. Volume concentrates in price-sensitive North American retail channels.
- Extract:Concentrated valerenic acid preparations standardized between 0.3% and 0.8% for pharmaceutical and nutraceutical formulation inputs.
- Powder:Dried, milled rhizome and stolon material in bulk form for traditional herbal preparations and functional food integration.
The dominant share belongs to Conventional, while Organic is closing the gap fastest as clean-label formulations displace hexane-processed alternatives.
Application:
Volume splits sharply between mature sleep-centric positioning and emerging anxiety relief formulations that attract clinical investment.
- Sleep Aid:The largest consumption category by volume, comprising sedative formulations in capsules, tablets, and teas. Demand concentrates in German pharmacy networks where traditional herbal medicine maintains robust consumer access, sustained by accumulation of clinical validation for non-habit-forming alternatives to synthetic sedatives.
- Anxiety Relief:Generalized anxiety disorder formulations represent the steepest expansion trajectory as emerging clinical trials open positioning beyond sleep-centric applications. Nutraceutical manufacturers are expanding procurement specifically for this indication.
- Dietary Supplements:Multi-ingredient formulations combining valerian with complementary botanicals for wellness positioning.
- Herbal Remedies:Traditional preparations in loose powder and tea bag formats serving heritage herbal medicine practitioners.
Sleep Aid retains volume leadership, yet Anxiety Relief is expanding most quickly as formulation R&D pivots toward mood disorder indications.
Distribution Channel:
Channel economics are restructuring as direct-to-consumer platforms capture margin pools previously held by brick-and-mortar intermediaries.
- Online Retail:Subscription-based replenishment models and fitness-oriented direct-to-consumer brands are capturing margin pools previously held by pharmacy intermediaries, particularly among individual consumers seeking automated replenishment.
- Health Stores:Specialty retailers in Western Europe and North America where certified organic SKUs command shelf space advantages through clean-label certification requirements.
- Pharmacies:German pharmacy networks anchor traditional herbal medicine distribution with robust consumer access points.
- Specialty Stores:Niche botanical and wellness-focused retail formats serving dedicated herbal medicine consumers.
Pharmacies hold established share in European markets, though Online Retail is gaining share fastest through subscription platform expansion.
End User:
Procurement scale and specification sophistication vary dramatically across individual purchasers versus institutional formulators.
- Individual Consumers:Fitness enthusiasts and wellness-focused purchasers driving subscription platform growth, typically specifying organic certification and solvent-free extraction as baseline requirements.
- Nutraceutical Companies:Institutional formulators expanding valerian procurement for sleep aid and anxiety relief product lines, requiring pharmaceutical-grade documentation and standardized valerenic acid concentrations.
- Health Practitioners:Licensed herbalists and integrative medicine providers sourcing for patient-specific preparations.
- Fitness Enthusiasts:Performance-oriented consumers seeking natural recovery and sleep optimization solutions.
Nutraceutical Companies dominate procurement volume, while Individual Consumers are climbing the fastest through direct-to-channel purchasing shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor pharmacy-distributed herbal sedatives while North American purchasers gravitate toward direct-to-consumer subscription platforms, revealing sharply divergent channel preferences across major consumption zones.
Germany
Traditional herbal medicine acceptance drives concentrated pharmacy demand for certified organic valerian grades. The Federal Institute for Drugs and Medical Devices enforces pharmaceutical-grade documentation under the Medicinal Products Act. Bavaria anchors processing infrastructure where specialized extract houses serve European pharmaceutical clients.
United States
Fitness enthusiasts and wellness-focused consumers propel subscription platform growth for clean-label sleep aids. FDA Current Good Manufacturing Practice frameworks shape quality thresholds for dietary supplement-bound valerian products. Pacific Northwest cultivation clusters are expanding organic acreage to serve domestic formulators.
China
Raw botanical supply concentration exposes European and North American processors to climate and trade policy disruptions. The National Medical Products Administration oversees botanical ingredient safety assessments for export-bound materials. Sichuan and Yunnan provinces host dominant cultivation networks supplying international extract manufacturers.
India
Ayurvedic medicine practitioners sustain heritage demand for whole-root preparations alongside growing nutraceutical export volumes. The Food Safety and Standards Authority of India regulates botanical ingredient standards for domestic and international trade. Madhya Pradesh and Uttar Pradesh cultivation belts are scaling organic certification capacity.
Switzerland
Pharmaceutical contract manufacturers demand supercritical CO2-extracted valerenic acid concentrates for premium formulation inputs. Swissmedic enforces stringent botanical authentication requirements exceeding baseline EU standards. Basel-region processing facilities specialize in high-purity extraction for European pharmaceutical clients.
Valerian Root Powder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling captive cultivation and extraction infrastructure while mid-scale players compete on certification specialization. The middle band fragments across regional processing houses and ingredient traders lacking vertical control. Three archetypes dominate: integrated cultivator-processors with Asian sourcing networks, European pharmaceutical-grade specialists with supercritical extraction capabilities, and North American clean-label formulators with direct-to-consumer distribution. Consolidation momentum concentrates in extraction technology licensing and backward integration into certified organic cultivation.
Among Asia-based cultivator-processors, Lonier Herb Bio-Technology occupies a position exemplifying integrated sourcing network control. Stanford Advanced Materials and Pharmanager Ingredients represent the European specialist tier, with the former exemplifying materials science crossover into botanical inputs and the latter anchoring pharmaceutical-grade documentation capabilities for continental clients. These three entities illustrate the geographic and functional segmentation pressuring mid-scale competitors without distinct certification or technology positioning.
| Leading Market Players |
|---|
| Stanford Advanced Materials |
| Pharmanager Ingredients |
| Artemis Nutraceuticals |
| Lonier Herb Bio-Technology |
| Jeeva Organic |
| Herbal Apothecary |
| Paninkret |
| Medikonda Nutrients |
| EUROMED |
| Others |
Value Network & Pricing Analysis
EU Novel Food standardization gates both supplier qualification and price tiering simultaneously, forcing processors to absorb pharmaceutical-grade documentation costs that separate certified organic grades from conventional hexane-extracted alternatives. This regulatory filter compresses margins for uncertified operators while amplifying premium capture for Bavarian and Swiss extract houses with supercritical CO2 infrastructure.
Pricing Analysis
Long-term offtake contracts dominate procurement between nutraceutical formulators and certified European processors, insulating premium organic grades from spot-market volatility while conventional powder trades on shorter purchasing cycles vulnerable to valerenic acid concentration fluctuations. Price differentiation hinges on organic certification tier and supercritical extraction capability, with German pharmacy networks showing lowest sensitivity due to reimbursement positioning. Cost compression in conventional grades is intensifying as synthetic melatonin alternatives undercut unit economics in mass-market supplement aisles. Individual consumers through subscription platforms exhibit highest price sensitivity, demanding solvent-free extraction at conventional price points.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for processors dependent on Chinese and Indian raw botanical inputs. Sourcing gravity centers on Sichuan and Yunnan provinces in China alongside Madhya Pradesh and Uttar Pradesh cultivation belts in India, with European and North American processors drawing from these clusters for dried rhizome material. Supply chain risk concentrates in single-source vulnerability to climate disruption across Asian growing regions. Distribution runs through German pharmacy networks for premium grades and direct-to-consumer subscription platforms for fitness-oriented segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services represent a faster-expanding recurring-revenue layer than bulk powder sales, creating attach opportunities for extraction technology licensing and certification consulting.
For Market Incumbents: Consolidate through backward integration into certified organic cultivation in Bavaria and the Pacific Northwest, securing captive supply as climate volatility threatens Asian sourcing clusters. Acquire supercritical CO2 extraction specialists to defend against synthetic melatonin substitution in mass-market channels. Prioritize pharmaceutical-grade documentation capabilities under EU Novel Food requirements to maintain German pharmacy network positioning. For New Entrants and Emerging Players: Lead with anxiety relief formulations targeting generalized anxiety disorder indications, the most penetrable application segment as clinical validation accumulates faster than sleep-centric positioning saturation. Target direct-to-consumer wellness platforms with solvent-free organic grades, exploiting clean-label preference shifts among fitness enthusiasts. Establish go-to-market partnerships with subscription platforms seeking differentiated botanical credentials. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical extraction infrastructure as REACH compliance deadlines force facility upgrades. Long-term viability favors processors with integrated cultivation networks and pharmaceutical-grade certification capabilities. Target acquisition archetypes include mid-scale European extract houses with ECHA-registered solvent systems and organic certification pipelines. Watch for inflection in valerenic acid standardization contract pricing as clinical trial readouts expand anxiety relief addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Stanford Advanced Materials and Swiss processors deploy pressurized carbon dioxide systems to isolate valerenic acids without thermal degradation or residual solvents. |
| Organic Certification Pipeline Development | Bavarian and Pacific Northwest cultivation clusters expand certified acreage to serve clean-label displacement in German pharmacy and US specialty retail channels. |
| Pharmaceutical-Grade Documentation Investment | EU Novel Food and FDA Current Good Manufacturing Practice frameworks force consolidation among processors capable of batch-level valerenic acid quantification. |
| Subscription Platform Partnership | Direct-to-consumer wellness brands capture margin pools previously held by brick-and-mortar pharmacy intermediaries through automated replenishment models. |
| Anxiety Relief Clinical Trial Advancement | Emerging generalized anxiety disorder indications open formulation expansion beyond sleep-centric positioning for nutraceutical procurement teams. |
Research Methodology
The analysis maps organic certification tiers, supercritical extraction capabilities, and application-specific formulation requirements, each validated through extraction technology providers, nutraceutical procurement directors, and German pharmacy network managers. Primary interviews with botanical authentication specialists, ECHA compliance consultants, and subscription platform supply chain heads combined with secondary validation from FDA dietary supplement guidance documents, EU Novel Food regulation filings, EFSA botanical safety assessments, and REACH registration databases. Bottom-up volume modeling across cultivation clusters triangulates against top-down value estimates from pharmaceutical contract manufacturer disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning certification grade, extraction technology, application indication, and distribution channel. CAGRs were derived from modeled annual growth trajectories incorporating valerenic acid standardization contract trends and clinical trial pipeline maturation. Forecast inputs include supercritical CO2 equipment deployment schedules, organic certification conversion rates in Asian cultivation belts, and regulatory filing timelines for novel food approvals.
The analysis sits within stated boundaries; outcomes outside continued EU Novel Food enforcement, stable Asia-Europe trade lane capacity, and sustained clinical validation for anxiety relief indications would require recalibration. Forecasts reflect documented assumptions regarding valerenic acid concentration stability, REACH compliance cost absorption rates, and synthetic melatonin substitution elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Lotus Extract Market
Extracts
Hesperidin Market
Extracts
Essential Oil Isolates Market
Extracts
Ovalbumin Powder Market
Extracts
Irish Moss Market
Extracts
Chamomile Oil Market
Extracts
Turpentine Market
Extracts
China Cedar Wood Oil Market
Extracts
Botanical CO2 Extracts Market
Extracts
Clary Sage Oil Market
Extracts
Pectinase Market
Extracts
Herb and Spice Extracts Market
Extracts
Organic Extracts Market
Extracts
Orange Oil Market
Extracts
Floral Extract Market
Extracts
Bidens Pilosa Extract Market