
 Palmarosa Oil Market | 2026-2036
Palmarosa Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Palmarosa Oil Market Outlook
Cosmetics is realigning as the dominant demand vertical for palmarosa oil, displacing traditional aromatherapy volumes as personal care brands reformulate around natural preservatives. IOI Corporation Berhad leverages its Malaysian plantation base to secure consistent geraniol-rich feedstock. AOS Products specializes in small-batch steam-distilled grades for European cosmetic houses. Sime Darby Plantation anchors Southeast Asian supply through integrated cultivation and distillation infrastructure.
Palmarosa oil is an essential oil extracted from Cymbopogon martinii grass, typically yielding 75-95% geraniol content through steam distillation, and serves primarily as a natural fragrance compound and antimicrobial agent in cosmetic and therapeutic applications. Steam distillation dominates extraction method share due to its cost efficiency and geraniol retention profile, while CO2 extraction captures premium pricing in high-purity pharmaceutical segments. Essential oil leads product type demand by volume, though hydrosol gains traction among mid-tier personal care brands seeking diluted, cost-effective formulations.
India's BIS and the EU REACH regulation impose geraniol purity thresholds and allergen labeling mandates that filter out unstandardized suppliers. The USDA organic certification and ISO 9001 quality frameworks further segment market access between premium cosmetic-grade and commodity fragrance-grade channels. Stakeholders must monitor extraction technology shifts and evolving purity standards across target export jurisdictions to sustain procurement competitiveness.
Market Dynamics
Steam distillation's dominance in palmarosa oil extraction is tightening supply-side control among integrated plantation operators, compressing margins for independent distillers while concentrating geraniol-rich feedstock access.
Growth Catalysts
- EU REACH allergen mandates:Cosmetic formulators are substituting synthetic preservatives with palmarosa oil's natural antimicrobial properties to meet labeling requirements.
- Clean-label skincare:Personal care brands are reformulating around plant-derived fragrance compounds, displacing petrochemical alternatives in premium product lines.
- Indonesian plantation belt:Integrated cultivation-distillation infrastructure anchors consistent upstream supply for export-grade essential oil.
Market Restraints
- Feedstock concentration:Cymbopogon martinii grass cultivation clusters in Southeast Asian tropical zones, exposing supply to monsoon volatility.
- India BIS compliance costs:Small-batch distillers face capital barriers meeting purity thresholds for export certification.
- Synthetic geraniol substitution:Laboratory-produced fragrance compounds undercut natural oil pricing in mass-market applications.
Strategic Opportunities
- Brazil ANVISA cosmetic approvals:Regulatory pathway opening for natural preservatives in South American personal care markets.
- Hydrosol dilution formats:Mid-tier brands are adopting cost-effective hydrosol variants for mass-market skincare lines.
- CO2 extraction convergence:Supercritical fluid technology is capturing pharmaceutical-grade demand for high-purity geraniol isolates.
Industry Challenges
- Steam distillation expertise gap:Master distillers with geraniol retention optimization skills are retiring faster than training pipelines replace them.
- Multi-jurisdiction certification timelines:Simultaneous USDA organic, ISO 9001, and EU REACH compliance creates 18-24 month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palmarosa Oil Market |
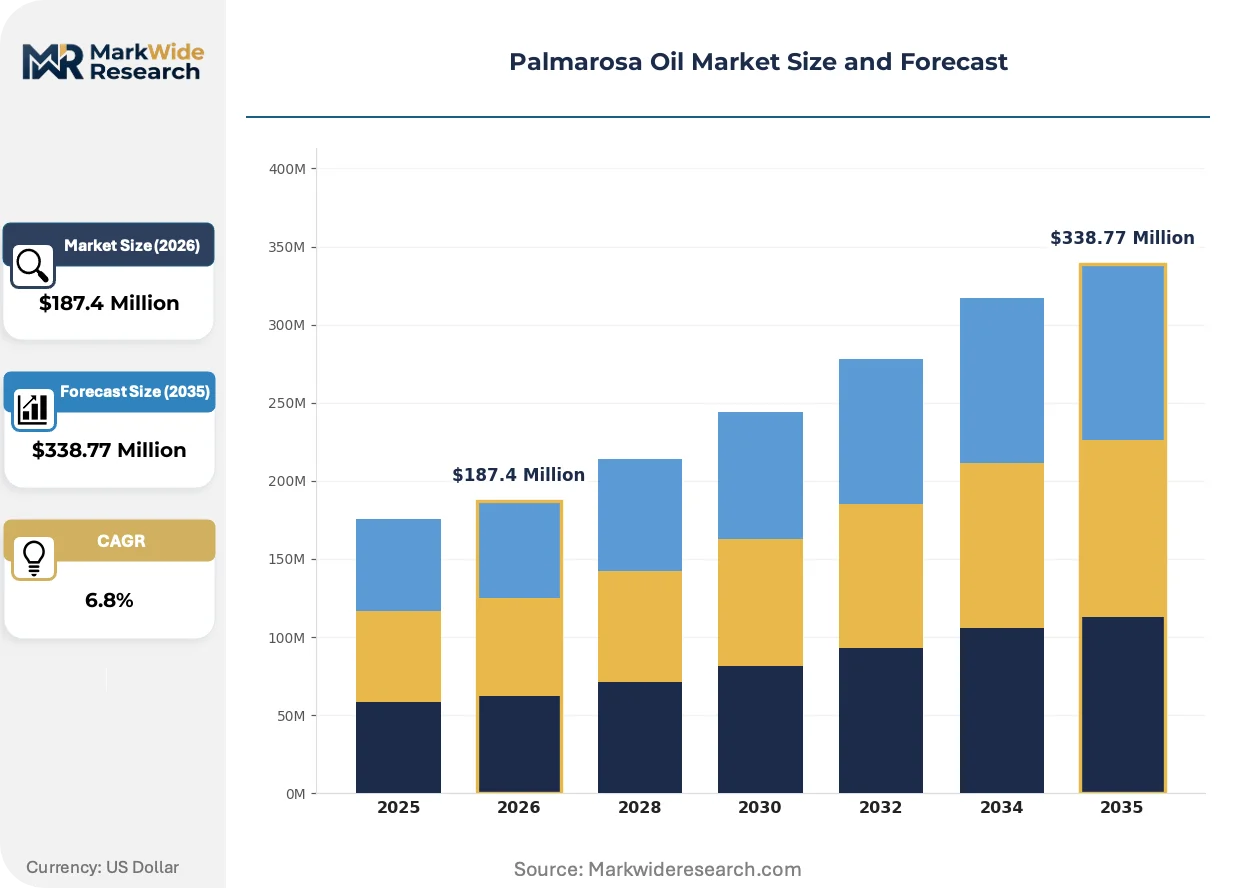
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Hydrosol, Aroma Oil, Fragrance Oil Extraction Method: Steam Distillation, Cold Pressing, Solvent Extraction, CO2 Extraction Application: Cosmetics, Aromatherapy, Food Flavoring, Household Products End User: Personal Care Brands, Food and Beverage Industry, Pharmaceutical Companies, Wellness Centers |
| Companies Covered | IOI Corporation Berhad, Musim Mas Group, Sinar Mas Group, Wilmar International, Sime Darby Plantation, Mewah Group, Kuala Lumpur Kepong Berhad, AOS Products, Asian Agri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palmarosa Oil Market Strategic Shifts
Extraction technology diversification and regulatory purity escalation are fragmenting competitive advantage across plantation-integrated and specialist-distiller business models.
Supercritical CO2 extraction is decentralizing pharmaceutical-grade supply chains by enabling smaller-scale, high-purity production outside traditional plantation belts. European API manufacturers are adopting this technology to reduce dependency on Southeast Asian feedstock. The method is decentralizing geographic concentration of premium geraniol supply.
India's BIS essential oil standards are tightening geraniol purity benchmarks and mandating traceable cultivation documentation. Domestic distillers must retrofit analytical laboratories to maintain export eligibility. Cosmetic-grade channels are most affected, with unstandardized suppliers exiting formal trade.
Direct plantation-to-brand contracting is compressing traditional broker channels in personal care procurement. Indonesian integrated operators are establishing captive supply agreements with European cosmetic houses. This pattern is most visible in German and French fragrance compound markets.
Palmarosa Oil Market Segmentation
Palmarosa oil procurement decisions hinge on purity grade, extraction technology, and end-use certification requirements. Each segment tier carries distinct capital barriers and margin profiles that reshape supplier competitiveness across cosmetic, pharmaceutical, and food channels.
Product Type:
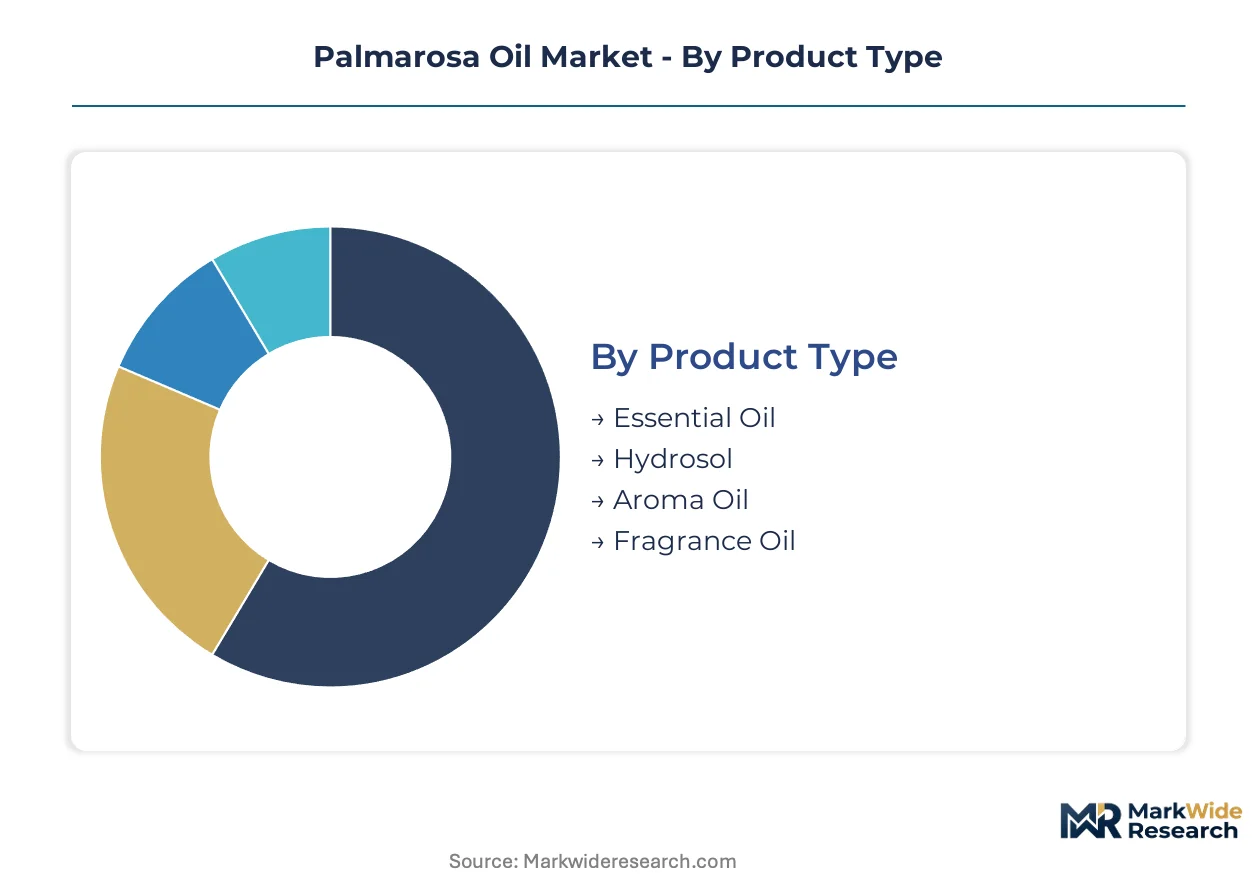
Capital intensity varies sharply across product formats, with steam-distilled essential oil requiring integrated distillation infrastructure while hydrosol production leverages lower-cost fractionation.
- Essential Oil:Steam-distilled Cymbopogon martinii extract yielding 75-95% geraniol content serves as the baseline reference standard for cosmetic and therapeutic formulations. Demand concentrates in European personal care brands reformulating around EU REACH allergen mandates, with procurement shifting toward certified organic grades that command premium positioning in clean-label skincare lines.
- Hydrosol:Aqueous byproduct of steam distillation containing diluted geraniol and water-soluble plant compounds offers cost-accessible entry points for mid-tier personal care brands. Indonesian plantation operators are expanding hydrosol fractionation capacity to capture mass-market skincare demand in Southeast Asian domestic markets.
- Aroma Oil:Blended formulations combining palmarosa essential oil with carrier oils for direct consumer application.
- Fragrance Oil:Synthetic-nature hybrid compounds incorporating palmarosa-derived geraniol for mass-market perfumery applications.
Most installed capacity flows through Essential Oil. Expansion is steepest in Hydrosol.
Extraction Method:
Technology selection determines geraniol retention rates, batch scalability, and regulatory compliance pathways for target export markets.
- Steam Distillation:Dominant industrial method employing heated water vapor to volatilize and condense essential oil fractions preserves geraniol integrity at scale. Integrated plantation operators in Indonesia's Musim Mas and Sime Darby networks anchor supply through captive distillation infrastructure, while independent Indian distillers face BIS certification barriers.
- CO2 Extraction:Supercritical fluid technology using pressurized carbon dioxide as solvent yields pharmaceutical-grade geraniol isolates with residual solvent-free certification. European API manufacturers are adopting this method to reduce dependency on Southeast Asian feedstock concentration and meet EMA purity specifications.
- Cold Pressing:Mechanical expression method limited to citrus and seed oils with minimal application for grass-derived palmarosa extraction.
- Solvent Extraction:Chemical solvent-based methods for absolute and concrete production with restricted cosmetic-grade acceptance due to residual solvent concerns.
Steam Distillation retains the dominant installed base. CO2 Extraction is climbing the fastest as pharmaceutical-grade demand escalates.
Application:
End-use diversification creates divergent purity requirements and pricing power across cosmetic, therapeutic, and food channels.
- Cosmetics:Natural preservative and fragrance compound in skincare, haircare, and color cosmetic formulations. German and French cosmetic houses are establishing direct plantation contracts to secure geraniol-rich supply chains for clean-label product lines.
- Aromatherapy:Therapeutic-grade essential oil for diffusers, massage blends, and wellness applications. Demand is fragmenting as cosmetic procurement displaces traditional aromatherapy volumes in supplier priority rankings.
- Food Flavoring:GRAS-status flavor compound for confectionery and beverage applications with FSSAI and FDA compliance requirements.
- Household Products:Natural antimicrobial for surface cleaners, air fresheners, and laundry formulations targeting petrochemical substitution.
Cosmetics captures the largest value share. Aromatherapy is expanding most quickly in premium wellness positioning.
End User:
Customer type segmentation reflects procurement scale, certification sophistication, and formulation technical requirements.
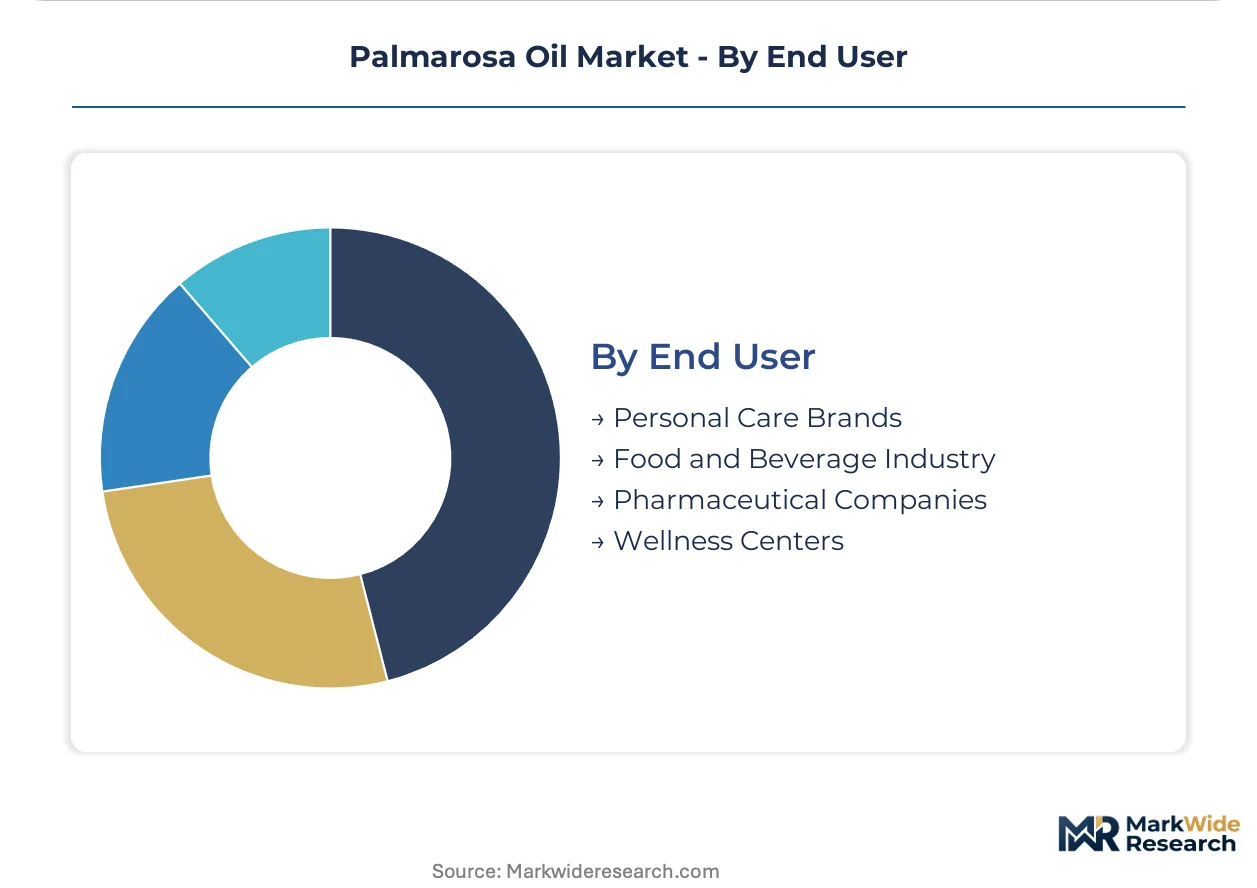
- Personal Care Brands:Multinational and indie cosmetic formulators driving specification-grade demand for geraniol purity and traceable cultivation documentation. EU REACH and BIS compliance timelines create 18-24 month qualification cycles that favor established plantation-integrated suppliers.
- Pharmaceutical Companies:API manufacturers and natural product developers requiring CO2-extracted, pharmaceutical-grade geraniol isolates for antimicrobial and therapeutic applications. EMA and FDA DMF pathways demand analytical laboratory infrastructure that filters out commodity distillers.
- Food and Beverage Industry:Flavor houses and natural product developers incorporating palmarosa-derived compounds for clean-label flavor systems.
- Wellness Centers:Spa chains and holistic health practitioners sourcing bulk essential oil for in-house treatment formulations.
Personal Care Brands absorb the majority of volume. Pharmaceutical Companies are gaining share fastest on purity premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's plantation belt anchors upstream supply for palmarosa oil extraction, with integrated cultivation-distillation infrastructure concentrating geraniol-rich feedstock access among major operators.
Indonesia
Cosmetic-grade essential oil demand from European personal care brands drives procurement volumes through Musim Mas Group and Sime Darby Plantation networks. The country's national standards body enforces traceable cultivation documentation for export eligibility. North Sumatra and Riau provinces host the densest concentration of Cymbopogon martinii cultivation and captive steam distillation facilities.
India
Domestic distillers serve both pharmaceutical and fragrance compound channels with small-batch steam-distilled grades. BIS essential oil standards impose geraniol purity thresholds that filter out unstandardized suppliers. Uttar Pradesh and Madhya Pradesh clusters are retrofitting analytical laboratories to maintain export certification timelines.
Malaysia
IOI Corporation Berhad leverages plantation infrastructure to secure consistent feedstock for geraniol-rich output. The country's national pharmaceutical regulator aligns cosmetic ingredient approvals with ASEAN harmonized standards. Peninsular Malaysia's integrated palm and aromatic grass cultivation zones support backward integration into essential oil production.
Germany
EMA purity specifications drive demand for CO2-extracted pharmaceutical-grade geraniol isolates among API manufacturers. EU REACH allergen labeling mandates push cosmetic formulators toward natural preservative substitution. Cologne and Hamburg fragrance compound houses are establishing direct plantation contracts with Southeast Asian suppliers.
Brazil
ANVISA cosmetic approvals are opening regulatory pathways for natural preservatives in South American personal care markets. The country's national health surveillance agency is streamlining botanical ingredient registration for clean-label skincare lines. São Paulo and Minas Gerais formulators are piloting palmarosa-derived antimicrobial compounds in mass-market product development.
Palmarosa Oil Market Competitive Environment
Capacity expansion dominates the current landscape as plantation-integrated operators retrofit distillation infrastructure to capture cosmetic-grade demand. The market structure concentrates around Southeast Asian upstream controllers, mid-tier Indian specialist distillers, and European pharmaceutical-grade extractors. Three archetypes define positioning: integrated plantation operators with captive supply, specialist distillers serving certified organic channels, and technology-led extractors pursuing CO2 pharmaceutical grades. Competitive moves center on backward integration into cultivation and direct contracting with cosmetic houses.
Among plantation-integrated operators, IOI Corporation Berhad, Musim Mas Group, and Sime Darby Plantation exemplify the upstream control archetype. These Malaysia and Indonesia-based entities occupy positions that anchor Southeast Asian supply through combined cultivation and distillation infrastructure. Their scale-driven model represents the dominant competitive formation in export-grade essential oil channels.
| Leading Market Players |
|---|
| IOI Corporation Berhad |
| Musim Mas Group |
| Sinar Mas Group |
| Wilmar International |
| Sime Darby Plantation |
| Mewah Group |
| Kuala Lumpur Kepong Berhad |
| AOS Products |
| Asian Agri |
| Others |
Value Chain & Pricing Dynamics
Master distillers with geraniol retention optimization skills in Uttar Pradesh and Madhya Pradesh command wage premiums that widen spreads between certified organic cosmetic-grade and commodity fragrance-grade palmarosa oil tiers.
Pricing Analysis
Input-cost pass-through from Cymbopogon martinii grass cultivation and steam distillation energy inputs anchors contract-based long-term offtake agreements between Indonesian plantation operators and European cosmetic houses. Price differentiation separates EU REACH-compliant certified organic grades from standard fragrance-grade output, with volume scale and after-sales analytical documentation driving tier placement. Cost compression in mid-tier hydrosol channels is intensifying because Indonesian operators are expanding fractionation capacity for mass-market skincare. Personal care brands with direct plantation contracts exhibit lowest price sensitivity, while independent aromatherapy distributors face highest margin pressure.
Supply Chain Analysis
Cymbopogon martinii grass supply rests on Indonesian, Indian, and Malaysian tropical cultivation belts, with geraniol-rich biomass, steam distillation equipment, and analytical laboratory infrastructure forming critical input dependencies. Single-source vulnerability concentrates in Indonesian integrated operators controlling captive distillation infrastructure. Distribution runs through direct plantation-to-brand contracting that compresses traditional broker channels, with European fragrance compound houses establishing captive supply agreements for clean-label skincare formulations.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU REACH allergen mandates lock in structural demand for natural preservative substitution across European personal care formulations.
For Market Incumbents: To counter synthetic geraniol substitution in mass-market applications, deepen backward integration into certified organic cultivation in North Sumatra and Riau provinces while retrofitting analytical laboratories to compress BIS and EU REACH compliance timelines from 24 months toward 18 months. For New Entrants and Emerging Players: Launch via CO2 extraction technology partnerships with European API manufacturers seeking pharmaceutical-grade geraniol isolates outside Southeast Asian feedstock concentration. Target Brazilian ANVISA cosmetic approval pathways for natural preservatives in São Paulo and Minas Gerais formulator networks. For Investors and Strategic Acquirers: European cosmetic houses are the most active acquirer in this space, seeking upstream control over traceable cultivation documentation. Five-to-ten-year viability hinges on plantation-integrated operators with captive distillation infrastructure. Watch for EMA purity specification escalations that would filter out commodity distillers lacking CO2 extraction capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Cultivation | Musim Mas Group and Sime Darby Plantation networks secure EU REACH-compliant feedstock access for European cosmetic houses. |
| CO2 Extraction Technology Adoption | European API manufacturers reduce dependency on Indonesian plantation belts while meeting EMA pharmaceutical-grade specifications. |
| Direct Plantation-to-Brand Contracting | German and French fragrance compound houses compress traditional broker margins through captive supply agreements. |
| Hydrosol Fractionation Capacity Expansion | Indonesian operators capture mass-market skincare demand in Southeast Asian domestic markets with cost-accessible formulations. |
| Analytical Laboratory Retrofitting | Indian distillers in Uttar Pradesh and Madhya Pradesh maintain BIS export certification eligibility against tightening purity thresholds. |
Study Parameters
Multiple input streams — structured interviews with plantation operations managers, cosmetic procurement leads at European personal care brands, and essential oil distillation technical directors — were reconciled against customs and trade data, BIS certification registries, and EU REACH substance registration databases. Bottom-up volume estimates from cultivation acreage and distillation capacity were triangulated against top-down demand assessments from personal care brand formulation disclosures.
Historical extraction technology adoption patterns were cross-referenced against panel input from regulatory affairs specialists and pharmaceutical API manufacturers to inform projections across the analysis window. Segmentation modeling incorporated extraction method, product type, application channel, and end-user certification sophistication. CAGRs were derived from demand elasticity parameters tied to EU REACH compliance cost pass-through and clean-label skincare reformulation intensity.
Several conditions sit outside the modeled scope, including monsoon volatility impacts on Cymbopogon martinii grass yields and abrupt shifts in synthetic geraniol production economics. Forecasts reflect assumptions about regulatory timeline stability and plantation operator capacity expansion execution. A small set of named triggers warrants ongoing watch: EMA purity specification escalations, Brazil ANVISA approval acceleration, and master distiller workforce attrition rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Global Pine-Derived Chemicals Market
Extracts
Organic Herbal Extracts Market
Extracts
Valerian Root Powder Market
Extracts
Belladonna Market
Extracts
Phytochemicals Market
Extracts
Citronella Oil Market
Extracts
Functional Extract Market
Extracts
Cochineal Extract Market
Extracts
Agmatine Market
Extracts
Frankincense Oil Market
Extracts
Yucca Extract Material Market
Extracts
Sage Extract Market
Extracts
Peppermint Leaf Powder Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Global Herbal Extract Market
Extracts
Asia-Pacific Mineral Turpentine Market