
 Anise Extract Market | 2026-2036
Anise Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Anise Extract Market Outlook
Artisanal distillers and clean-label food developers is redrawing procurement priorities across the anise extract value chain. McCormick & Company leverages its spice-sourcing infrastructure to secure consistent Illicium verum supplies from Vietnamese growing regions. Symrise AG anchors European demand through its flavor-compounding expertise in Holzminden. Changsha Staherb Natural Ingredients competes on concentrated trans-anethole specifications for pharmaceutical-grade contracts.
Anise extract is a hydroalcoholic or supercritical CO2-derived concentrate of Pimpinella anisum or Illicium verum, typically standardized to 80-90% trans-anethole content for commercial use in flavoring, fragrance, and therapeutic applications. The substance serves as a carminative agent in digestive preparations and a top-note aromatic in licorice-type flavor profiles. Organic Extract commands premium positioning among European buyers subject to EU organic regulation thresholds, while Liquid formulations dominate food-service channels due to dosing precision and solubility advantages. Functional Extract is gaining fastest in pharmaceutical applications where standardization supports regulatory dossier submissions.
FDA food additive regulations and EFSA flavoring substance evaluations govern market access for anise extract in the United States and European Union respectively, with purity thresholds directly determining qualification for pharmaceutical-grade versus food-grade classifications. India's FSSAI and China's NMPA maintain parallel but non-harmonized standards for imported botanical extracts, fragmenting compliance requirements for multinational suppliers. Stakeholders must monitor evolving novel food classifications and organic equivalency agreements to preserve cross-border shipment eligibility.
Market Dynamics
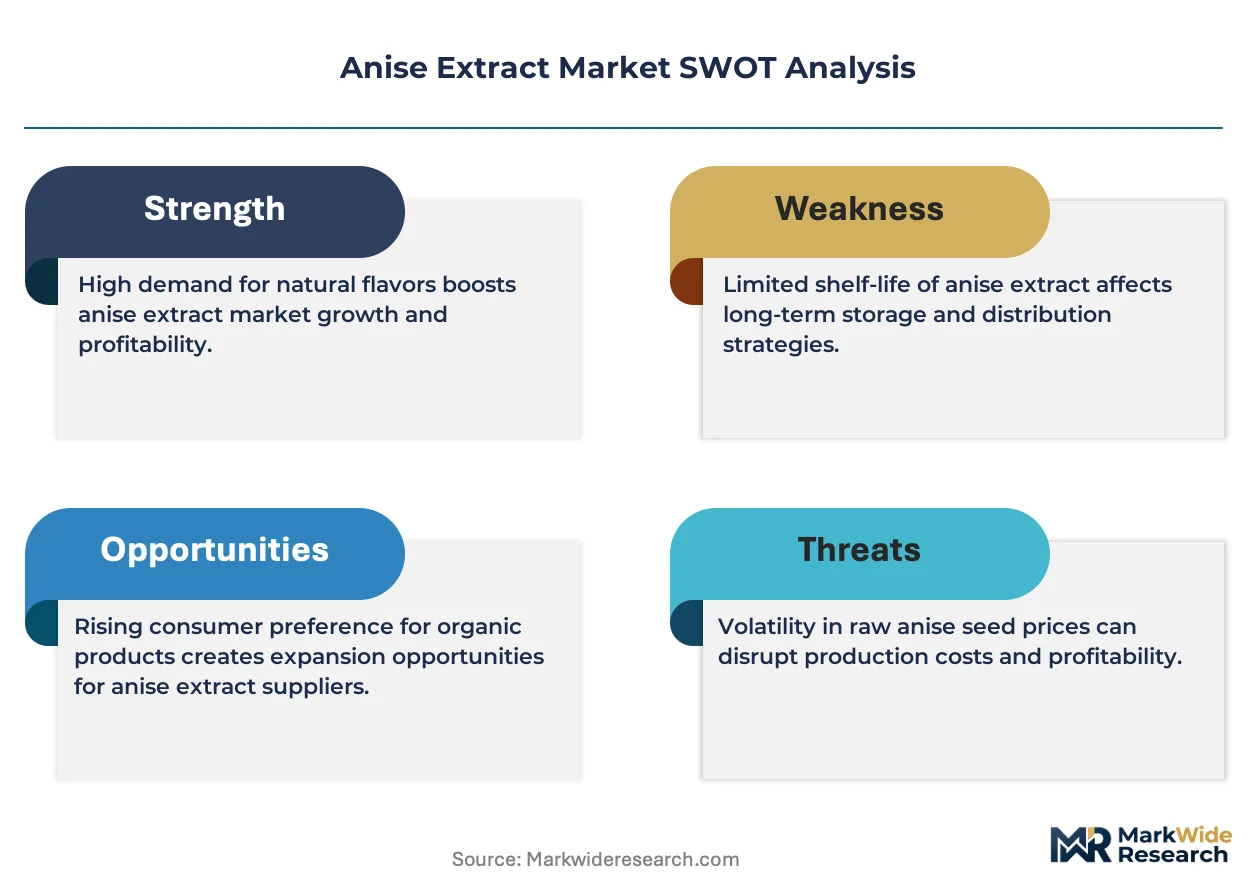
Clean-label formulation mandates from European retailers are forcing flavor houses to source trans-anethole from certified organic distillation clusters rather than conventional solvent extraction facilities.
Growth Catalysts
- EU Novel Food Regulation:Standardized safety dossier requirements accelerate pharmaceutical-grade extract qualification, opening therapeutic applications in digestive wellness.
- Functional food manufacturers:Deepening procurement of anise extract for gut-health positioning in fortified beverages and probiotic adjuncts.
- Supercritical CO2 extraction:Replacing hydroalcoholic methods in Spanish Castile-La Mancha facilities to meet residual solvent limits for premium flavor contracts.
Market Restraints
- Illicium verum supply concentration:Vietnamese growing regions dominate raw star anise supply, exposing processors to climate-driven harvest volatility.
- Organic certification cost structure:EU organic regulation compliance adds 15-25% to extraction facility operating costs versus conventional processing.
- Natural flavor substitution:Fennel-derived anethole and synthetic alternatives compete on price in mass-market confectionery applications.
Strategic Opportunities
- India's FSSAI import pathway:Underpenetrated ayurvedic pharmaceutical segment offers expansion for standardized extract suppliers meeting botanical drug monograph requirements.
- Direct-to-manufacturer e-procurement platforms:Emerging B2B channels in food-service distribution bypass traditional flavor house intermediaries for liquid extract volumes.
- Carbon-negative distillation incentives:EU Green Deal funding for biomass-powered extraction facilities in Portugal and Greece creates cost-advantaged supply nodes.
Industry Challenges
- Phytochemical standardization expertise:Scarce analytical chemists capable of validating trans-anethole content consistency across harvest batches delay contract approvals.
- Cross-border organic equivalency:Non-harmonized certification between EU and India's NPOP creates shipment holds and relabeling costs at ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anise Extract Market |
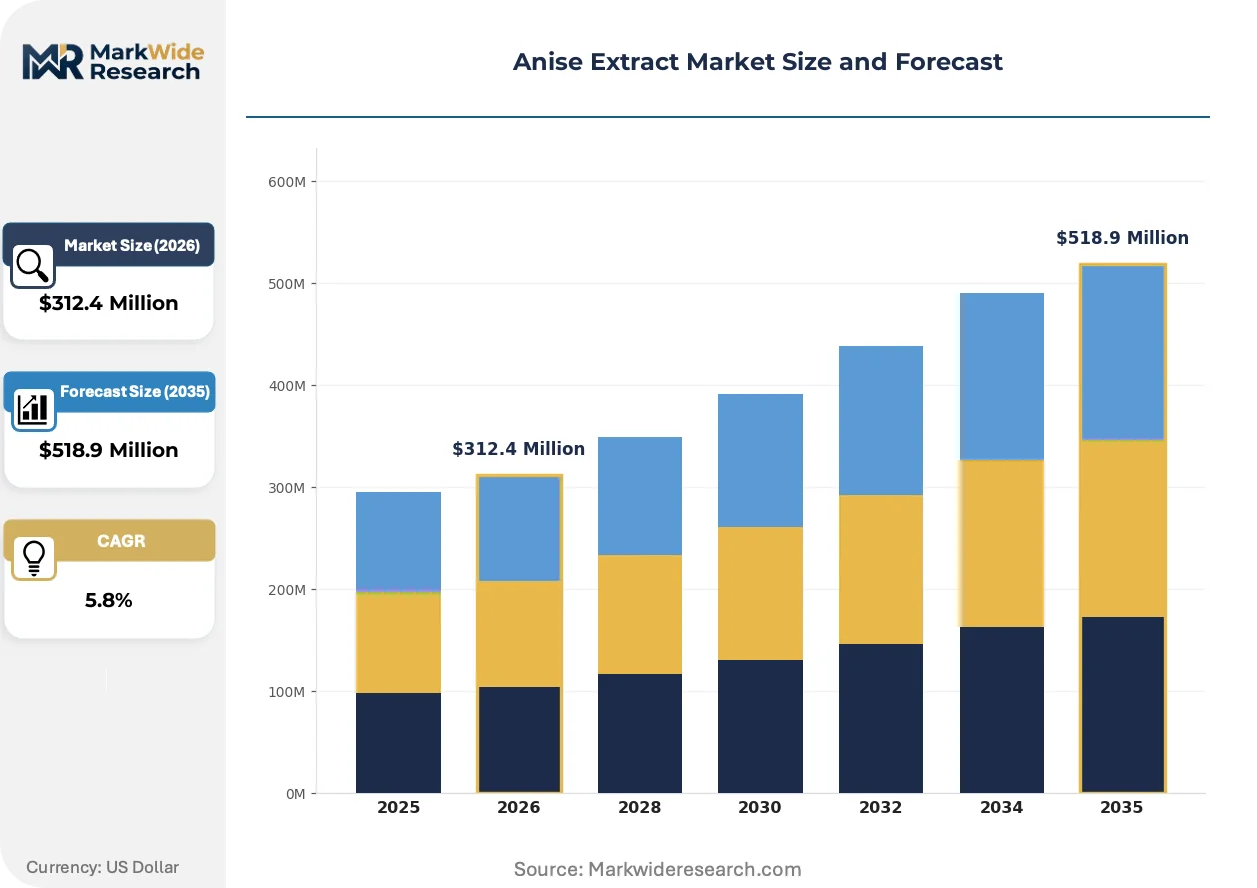
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Extract, Conventional Extract, Flavored Extract, Functional Extract Form: Liquid, Powder, Granules, Capsules Application: Food & Beverage, Pharmaceuticals, Cosmetics, Aromatherapy Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | McCormick & Company, Inc., Nielsen-Massey Vanillas, Inc., Döhler Group, Symrise AG, Givaudan SA, Changsha Staherb Natural Ingredients, Herb Pharm, Frontier Natural Products Co-op, Martin Bauer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anise Extract Market Strategic Shifts
Extraction technology advancement and procurement digitization are compressing traditional supply chain tiers while regulatory purity benchmarks reshape competitive qualification requirements.
Supercritical CO2 extraction systems are displacing conventional steam distillation in European flavor house supply chains. Pharmaceutical manufacturers in Germany and Switzerland now specify CO2-derived extracts for regulatory dossier submissions. This displacement is compressing margins for solvent-based processors unable to fund capital upgrades.
EFSA's updated flavoring substance evaluation protocols now require extended toxicity data for hydroalcoholic extracts above 0.01% residual ethanol. Food-grade suppliers in France and Spain face reformulation costs or classification downgrades. Premium organic extract segments absorb compliance investments fastest, widening specification gaps from conventional grades.
Buyers in bakery and confectionery verticals now contract directly with Vietnamese star anise cooperatives, bypassing traditional spice traders. Digital traceability platforms verify organic chain-of-c custody from harvest to extraction. This disintermediation concentrates most visibly in Dutch and German procurement offices seeking cost transparency for clean-label product lines.
Anise Extract Market Segmentation
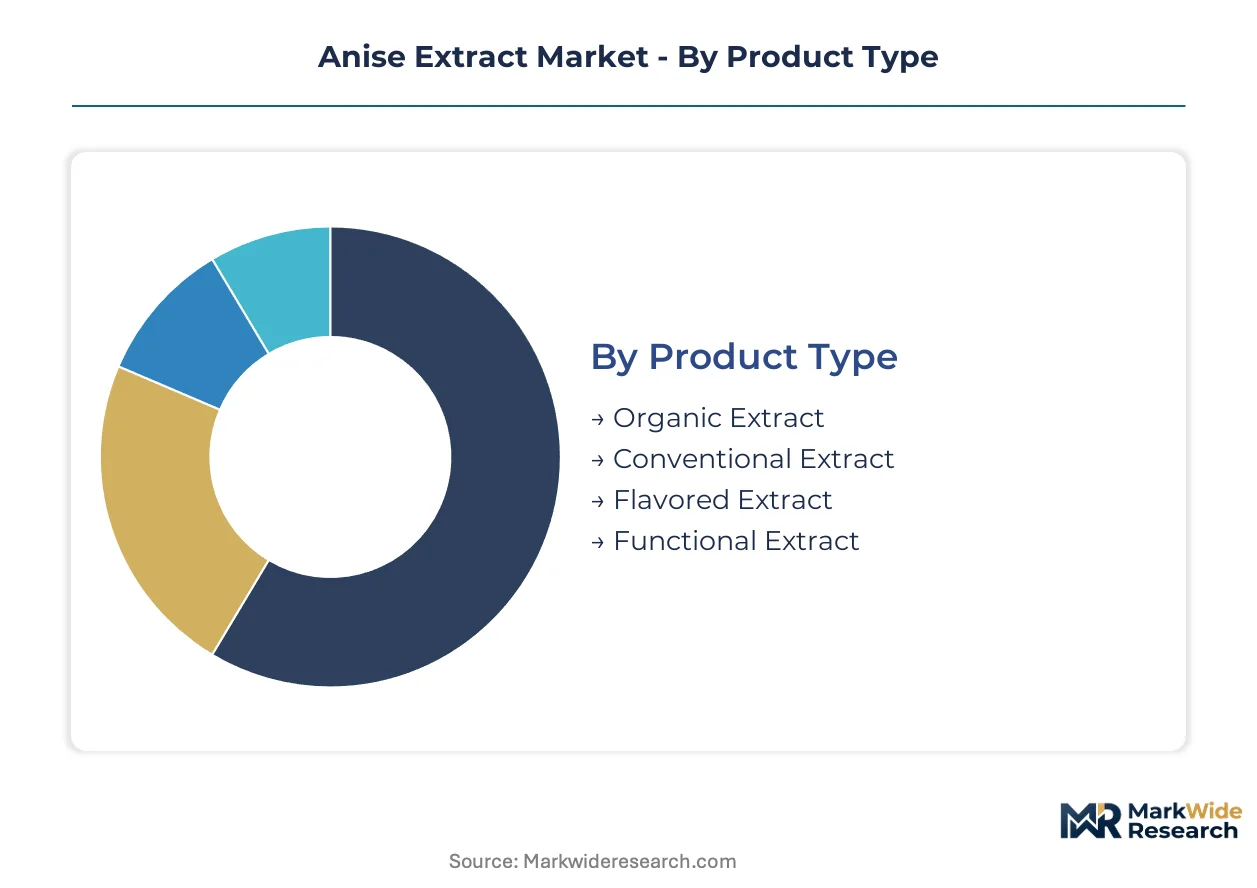
Segmentation in the anise extract market reveals distinct procurement patterns between export-oriented premium grades and domestically consumed commodity volumes. Extractors align certification tiers and form factors with end-use regulatory requirements across food, pharmaceutical, and cosmetic channels.
Product Type:
Organic and functional extracts flow predominantly to export markets in Germany and France, while conventional grades serve price-sensitive domestic food processors in Spain and Italy.
- Organic Extract:Certified to EU organic regulation thresholds with full traceability from Castile-La Mancha distillation clusters. German flavor houses and Swiss pharmaceutical manufacturers absorb the majority of output, paying premiums for residue-free CO2-derived material that satisfies EFSA dossier requirements.
- Functional Extract:Standardized to precise trans-anethole concentrations for therapeutic applications, particularly digestive wellness formulations. Demand concentrates among German and Austrian contract manufacturers supplying regulated botanical drug markets where batch consistency underpins regulatory approvals.
- Conventional Extract:Hydroalcoholic derivatives serving mass-market confectionery and bakery applications across Southern Europe.
- Flavored Extract:Value-added blends targeting beverage manufacturers seeking licorice-type top notes without full botanical certification costs.
Organic extract commands the established base. The steepest expansion runs through functional extract.
Form:
Form selection tracks dosing precision requirements and solubility constraints across customer types, with liquid formats dominating food-service B2B procurement.
- Liquid:Hydroalcoholic or CO2-derived solutions offering precise volumetric dosing for industrial flavor compounding. French and Italian beverage manufacturers specify liquid formats for seamless integration into syrup concentrates and alcoholic spirit formulations.
- Powder:Spray-dried or encapsulated extracts targeting dry mix applications. German bakery ingredient suppliers favor powder for shelf-stable seasoning blends where moisture control determines product integrity.
- Granules:Intermediate form for tea and infusion manufacturers seeking controlled release characteristics.
- Capsules:Pre-measured unit doses for ayurvedic and phytopharmaceutical distributors in India meeting FSSAI botanical drug monograph specifications.
Liquid formats anchor current procurement volumes. Powder is gaining share fastest among dry-mix ingredient suppliers.
Application:
Application segmentation reflects divergent purity benchmarks, with pharmaceutical and cosmetic channels imposing stricter residual solvent limits than food-grade specifications.
- Food & Beverage:Flavoring applications spanning confectionery, bakery, and alcoholic spirits. Spanish anise liqueur producers in Madrid and Barcelona represent concentrated demand for traditional hydroalcoholic extracts with protected geographical indication status.
- Pharmaceuticals:Carminative and digestive therapeutic preparations requiring standardized active content. German and Swiss manufacturers specify pharmaceutical-grade material for EU market authorization dossiers submitted to national regulators.
- Cosmetics:Fragrance and personal care applications where trans-anethole contributes licorice-type top notes.
- Aromatherapy:Inhalation-grade extracts for wellness product formulators in France and the United Kingdom.
Food and beverage holds the volume base. Pharmaceuticals is climbing the fastest on regulatory qualification investments.
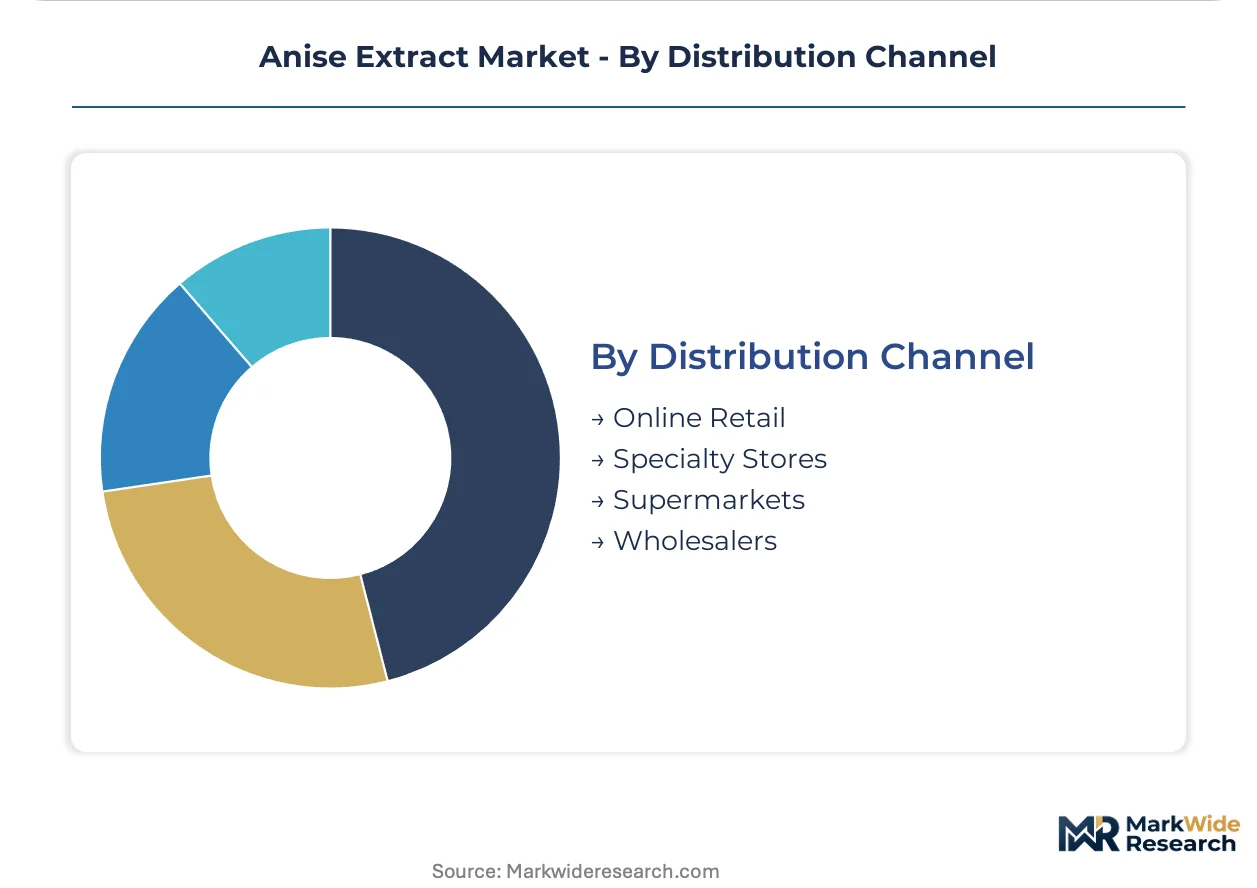
Distribution Channel:
Channel structure varies by customer scale and certification complexity, with direct procurement displacing traditional intermediaries in premium segments.
- Online Retail:B2B platforms enabling direct contracting between Vietnamese star anise cooperatives and European clean-label manufacturers. Dutch and German procurement offices leverage digital traceability for organic chain-of-custody verification.
- Specialty Stores:Regional distributors serving artisanal distillers and small-batch flavor houses in Portugal and Greece.
- Supermarkets:Mass-market retail for consumer-facing anise oil and extract products.
- Wholesalers:Traditional spice traders handling volume commodity grades for conventional food processors.
Wholesalers retain the established base. Online retail is expanding most quickly through procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese growing regions supply the dominant share of Illicium verum feedstock, while European extraction clusters in Spain and Germany command premium-grade processing. Regulatory divergence between EU organic standards and Asian import protocols fragments cross-border shipment eligibility.
Germany
Flavor compounding expertise in Holzminden anchors European demand for pharmaceutical-grade extracts. EFSA flavoring substance evaluations govern market access, with residual ethanol thresholds tightening for hydroalcoholic derivatives. Bavarian contract manufacturers supply standardized botanical drugs to national regulators.
Spain
Traditional distillation clusters in Castile-La Mancha supply premium grades to European flavor houses. Supercritical CO2 extraction systems displace conventional steam distillation to meet residual solvent limits. Madrid and Barcelona anise liqueur producers maintain protected geographical indication status for hydroalcoholic extracts.
Vietnam
Star anise cooperatives in northern growing regions dominate raw material supply for global processors. Climate-driven harvest volatility exposes extractors to price swings. Digital traceability platforms now verify organic chain-of-custody for direct contracting with Dutch and German buyers.
France
Aromatherapy wellness formulators in Provence and the Paris basin drive demand for inhalation-grade extracts. ANSM and CNIL oversight intersect with EU organic regulation compliance. Reformulation costs mount for food-grade suppliers facing EFSA extended toxicity data requirements.
India
Ayurvedic pharmaceutical distributors in Maharashtra and Gujarat seek standardized extracts meeting FSSAI botanical drug monograph specifications. Non-harmonized organic certification between EU and India's NPOP creates port delays. The underpenetrated therapeutic segment offers expansion for qualified suppliers.
Anise Extract Market Competitive Environment
Concentration sits with diversified flavor houses and specialized botanical extractors. Tiered competitive dynamics separate premium organic certifiers from conventional solvent processors. Strategic archetypes include integrated spice-sourcing conglomerates, CO2 extraction technology specialists, and cooperative-backed regional suppliers. Capacity upgrades and direct-to-manufacturer e-procurement partnerships represent the dominant competitive moves reshaping channel structures.
Among integrated flavor houses, McCormick & Company, Inc. and Symrise AG occupy positions spanning procurement infrastructure and compounding expertise. Changsha Staherb Natural Ingredients exemplifies the technology-specialist archetype competing on concentrated specifications. Nielsen-Massey Vanillas, Inc. and Frontier Natural Products Co-op represent quality-focused operators serving clean-label and cooperative market segments respectively. These named entities anchor broader industry patterns without constituting an exhaustive competitive map.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Nielsen-Massey Vanillas, Inc. |
| Döhler Group |
| Symrise AG |
| Givaudan SA |
| Changsha Staherb Natural Ingredients |
| Herb Pharm |
| Frontier Natural Products Co-op |
| Martin Bauer Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Vietnamese star anise cooperatives and German flavor houses lock in supply access and price visibility across harvest cycles, insulating premium organic extractors from spot-market volatility while exposing conventional processors to climate-driven raw material swings.
Pricing Analysis
EU organic regulation dictates the pricing tier structure across the anise extract value chain. Three-tier pricing structure across premium, standard, and economy levels separates CO2-derived organic certified material from hydroalcoholic conventional grades and synthetic anethole alternatives. Price differentiation rests on certification grade and residual solvent thresholds. Cost compression in conventional hydroalcoholic tiers is intensifying because EFSA extended toxicity data requirements force reformulation investments. Mass-market confectionery buyers exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers absorb premiums for dossier-compliant material.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg disrupts container availability for Vietnamese star anise shipments arriving through the Asia-Europe trade lane. Geographic supply concentration centers on Vietnam for Illicium verum feedstock, Spain for Castile-La Mancha distillation clusters, and Germany for pharmaceutical-grade compounding. Raw material dependencies include star anise fruit, supercritical CO2 processing equipment, and organic certification audit services. Single-source vulnerability in Vietnamese growing regions exposes processors to climate-driven harvest volatility. Distribution runs through direct-to-manufacturer e-procurement platforms for premium organic grades and traditional spice traders for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-manufacturer e-procurement platforms are reconfiguring the anise extract market into a platform-economics inflection, where digital traceability interoperability between Vietnamese cooperatives and European buyers disintermediates traditional flavor house intermediaries.
For Market Incumbents: Secure backward integration into Vietnamese star anise growing regions through cooperative equity stakes or long-term offtake agreements. Invest in supercritical CO2 extraction capacity upgrades at Castile-La Mancha facilities to defend against synthetic anethole substitution threats. Channel control through direct e-procurement platform ownership represents the critical lever for margin preservation. For New Entrants and Emerging Players: EU organic regulation fast-track certification offers entry into underpenetrated ayurvedic pharmaceutical segments in Maharashtra and Gujarat. Target India's FSSAI botanical drug monograph pathway where standardized extract demand outpaces qualified supply. Direct contracting with German contract manufacturers seeking alternative CO2-derived sources provides the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward CO2 extraction technology specialists with existing EU organic certification and validated pharmaceutical dossier submissions. Long-term viability over a multi-year horizon hinges on regulatory qualification depth rather than commodity volume scale. The signal to watch is EFSA flavoring substance evaluation protocol amendments affecting hydroalcoholic extract classifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Equity stakes in Vietnamese star anise cooperatives secure climate-resilient supply access for premium extractors. |
| Supercritical CO2 Capacity Expansion | Spanish facilities meeting EFSA residual solvent limits qualify for pharmaceutical-grade dossier submissions. |
| EU Organic Certification Investment | Compliance with EU organic regulation thresholds unlocks German and Swiss flavor house premium contracts. |
| Direct E-Procurement Platform Launch | Digital traceability interoperability bypasses traditional spice traders for Dutch and German clean-label buyers. |
| India FSSAI Regulatory Pathway | Botanical drug monograph qualification opens Maharashtra and Gujarat ayurvedic pharmaceutical distribution. |
Study Parameters
A standing panel of extraction facility technical directors, flavor house procurement managers, organic certification auditors, and pharmaceutical regulatory affairs specialists provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against EFSA flavoring substance evaluations, EU organic regulation compliance databases, FSSAI botanical drug monographs, and Vietnamese agricultural export statistics. Bottom-up volume modeling across product type, form, application, and distribution channel segments triangulated against top-down trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including certification tier, extraction technology, end-use regulatory channel, and geographic production cluster. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking capacity expansion announcements. Industry-specific forecast inputs included EFSA evaluation protocol amendments and EU Green Deal biomass-powered extraction incentives.
Underlying assumptions cover stable EU organic regulation thresholds and functional food manufacturer procurement deepening, with deviation risk concentrated in climate-driven Vietnamese harvest volatility and cross-border organic equivalency disputes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Global Magnolia Bark Extract Market
Extracts
Gum Turpentine Oil Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Floral Extract Market
Extracts
Irish Moss Market
Extracts
Yucca Extract Material Market
Extracts
Patchouli Oil Market
Extracts
Europe Mineral Turpentine Market
Extracts
Aloe Vera Extract Market
Extracts
CO2 Extract Market
Extracts
Amla Extract Market
Extracts
Global Marigold Flower Extract Market
Extracts
Marigold Essential Oil Market
Extracts
Peppermint Oil Market
Extracts
Turpentine Market
Extracts
Natural Rosemarine Extract Market