
 Potassium Hydrogen Tartrate Market | 2026-2036
Potassium Hydrogen Tartrate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Hydrogen Tartrate Market Insights
Fragmentation across specialty food manufacturers and craft beverage producers is expanding the buyer base beyond traditional industrial purchasers. Changmao Biochemical leverages its integrated fermentation capacity to serve regional Asian markets with consistent food-grade supply. Tártaros Gonzalo Castelló anchors European demand through its established wine-derivative extraction operations in Spain. Bioking Biochemical competes on pharmaceutical-grade certification, targeting formulation houses with USP-compliant material.
Potassium hydrogen tartrate, a potassium salt of tartaric acid with molecular formula KC₄H₅O₆, crystallizes as odorless white granules with solubility of 6.2 g per 100 mL water at 25°C and functions primarily as an acidulant, stabilizer, and pH buffer across food, pharmaceutical, and chemical applications. Food Grade material dominates volume due to its widespread use in baking powder formulations and wine stabilization, while Pharmaceutical Grade commands premium positioning as oral formulation excipients face tightening pharmacopeial standards. Laboratory Grade represents a concentrated margin pool serving analytical reagent demand, though volume remains constrained by niche academic and R&D consumption patterns.
FDA food additive regulations under 21 CFR 184.1077 govern purity thresholds for US-market material, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for industrial chemical placement. China's GB standards and NMPA pharmaceutical excipient rules create a multi-jurisdictional compliance landscape that favors suppliers with cross-certified manufacturing infrastructure. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergence in heavy metal limits and microbial specifications directly determines which producers can access high-margin pharmaceutical channels without reformulation costs.
Market Dynamics
Pharmaceutical-grade certification requirements are bifurcating supplier capabilities as USP, EP, and ChP standards diverge on heavy metal and microbial specifications, forcing capital allocation toward cross-certified manufacturing infrastructure.
Growth Catalysts
- REACH registration mandates:ECHA dossier requirements for industrial chemical placement are consolidating compliant supplier pools in Europe, advantaging producers with existing toxicological documentation.
- Bakery sector acidulant demand:Baking powder formulation expansion in processed food manufacturing is pulling food-grade volume through specialized ingredient distributors.
- Wine stabilization protocols:Tartrate precipitation management in cold stabilization processes sustains consistent offtake from enological chemical suppliers.
Market Restraints
- Tartaric acid feedstock concentration:Derivative production gravity in China creates single-source dependency risk for non-integrated compounders.
- GB standard compliance costs:NMPA pharmaceutical excipient rules impose reformulation burdens on exporters targeting China's formulation houses.
- Citric acid substitution pressure:Alternative acidulants with broader pH buffering ranges encroach on food-grade applications where cost sensitivity dominates.
Strategic Opportunities
- Clean-label bakery positioning:Natural acidulant claims in artisanal and craft baking segments open premium pricing tiers beyond commodity industrial supply.
- CSRD-aligned carbon accounting:EU corporate sustainability reporting requirements favor suppliers with fermentation-derived, biobased carbon footprints.
- Laboratory reagent channel expansion:Analytical-grade material demand from academic R&D clusters in Germany and Switzerland offers concentrated margin pools.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent heavy metal limits across USP, EP, and ChP specifications force batch-specific certification workflows that extend order fulfillment cycles.
- Cross-contamination control capex:Dedicated food-grade and pharmaceutical-grade production lines require segregated facility investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Hydrogen Tartrate Market |
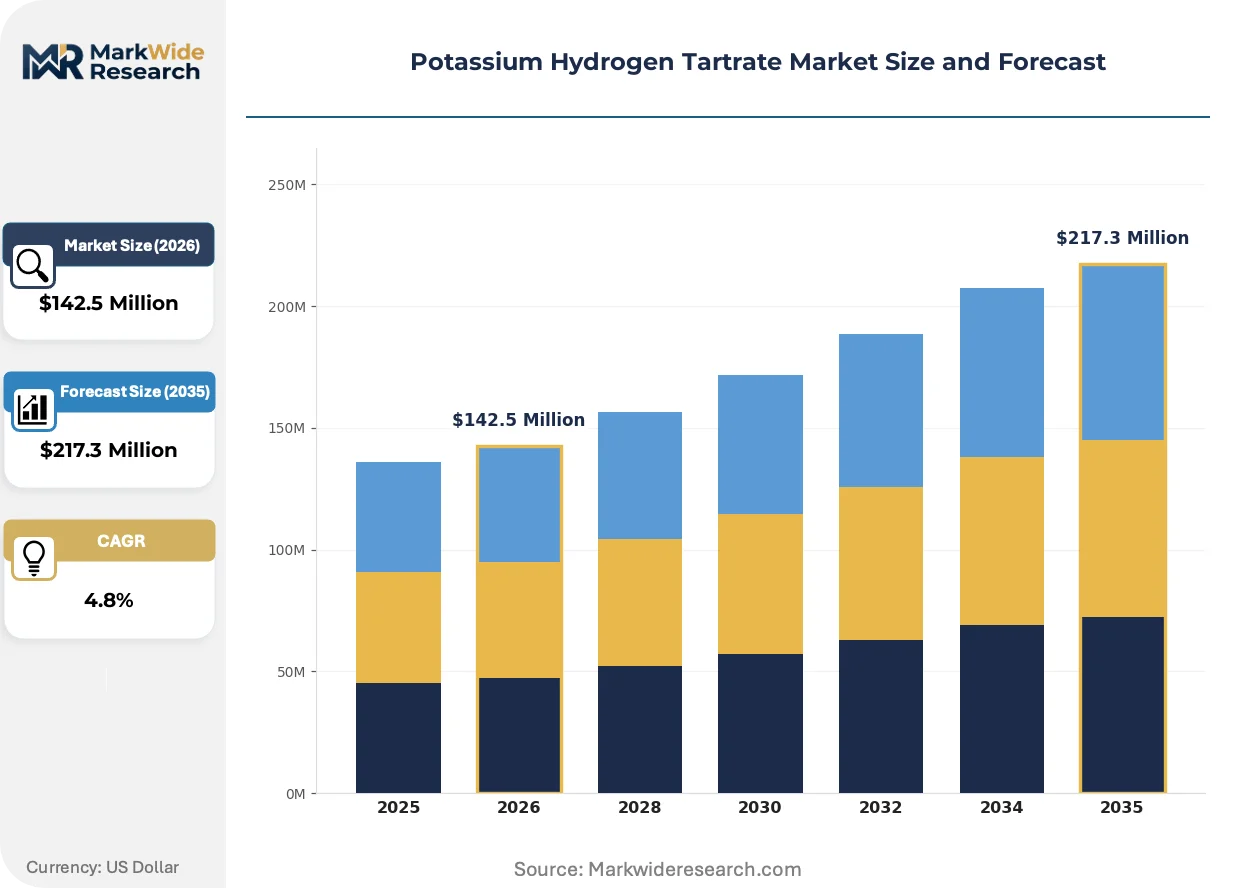
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Laboratory Grade End User: Food Industry, Pharmaceutical Companies, Research Laboratories, Chemical Manufacturers Application: Food Additive, Buffering Agent, Pharmaceutical Formulation, Electrolyte Distribution Channel: Online Retail, Wholesale Distribution, Direct Sales, Third-Party Retailers |
| Companies Covered | Bioking Biochemical, Changmao Biochemical, Anhui Aibo, Anhui Hailan, Greatwall Biochem, Industrias Vinicas, Pahi, Randi Group, Tártaros Gonzalo Castelló, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Hydrogen Tartrate Market Trends and Innovations
Continuous crystallization control systems and inline spectroscopic monitoring are compressing batch-to-batch variability, enabling real-time grade certification that accelerates customer qualification timelines.
Membrane filtration integration with traditional solvent crystallization is rewriting purity-versus-yield tradeoffs in tartaric acid derivative processing. Pharmaceutical excipient manufacturers in Switzerland and Germany are adopting these hybrid systems to reduce solvent recovery costs while hitting tightening USP microbial specifications. The technology is compressing the cost gap between food-grade and pharmaceutical-grade production, forcing legacy batch crystallizers into commodity-only positioning.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration system retrofits at wine stabilization facilities, altering seasonal demand patterns for tartrate precipitation chemicals. Spanish and Italian wineries are shifting cold stabilization timing to align with lower-GWP cooling infrastructure deployment. The regulation is compressing traditional Q4 demand concentration into extended shoulder seasons.
Direct procurement relationships between craft beverage producers and certified chemical suppliers are displacing layered distributor networks in specialty food channels. Small-batch wineries and artisanal bakeries in France and California are establishing approved vendor lists with documentation requirements previously reserved for industrial accounts. This channel fragmentation is visible most acutely in Burgundy and Napa Valley clusters where traceability demands exceed standard distributor capabilities.
Potassium Hydrogen Tartrate Market Segmentation
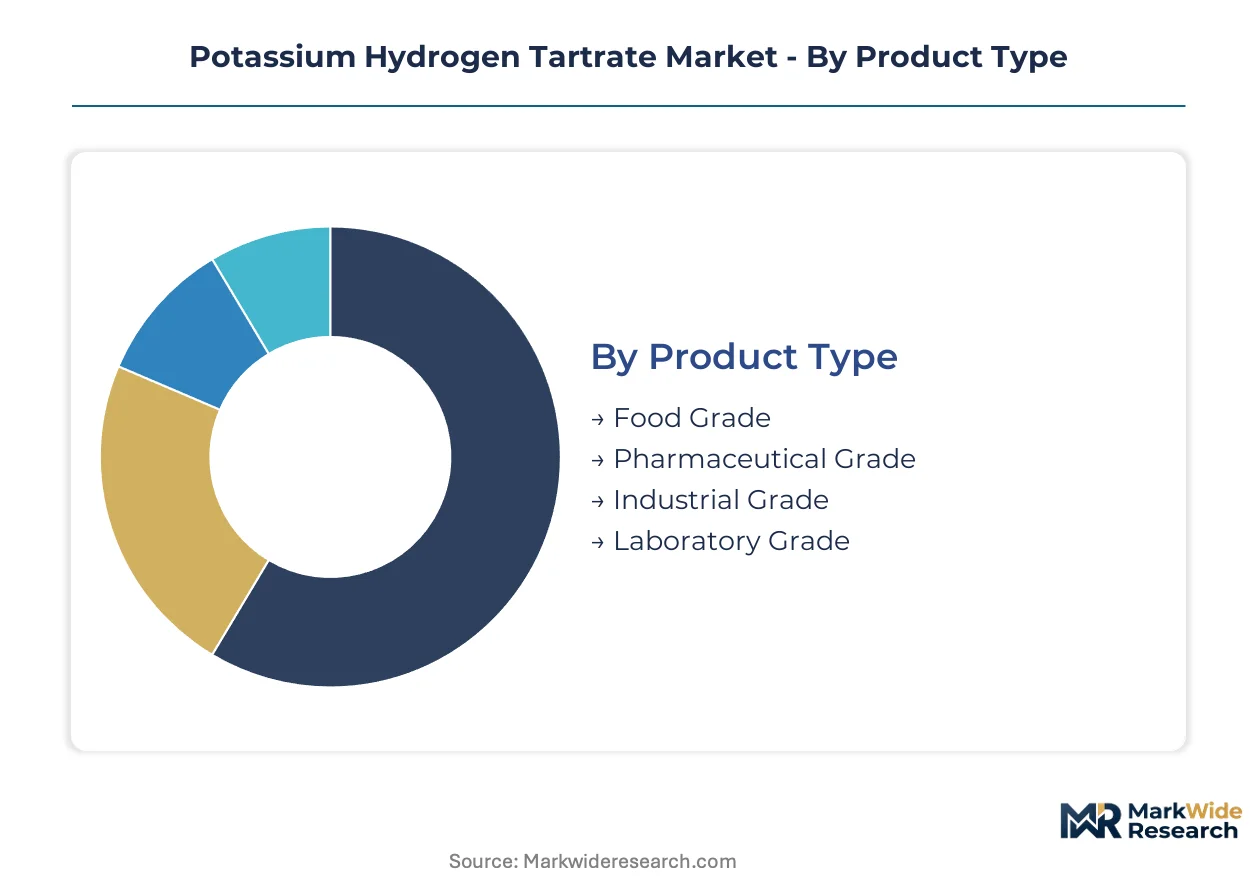
Grade-specific certification requirements fragment supplier capabilities across the potassium hydrogen tartrate value chain. Each tier demands distinct manufacturing infrastructure, from fermentation-derived food material to USP-compliant pharmaceutical excipients.
Product Type:
Upgrade cycles in tartaric acid derivative processing favor producers with cross-certified infrastructure capable of serving multiple purity tiers from shared feedstock.
- Food Grade:Odorless white crystalline material meeting FCC and GB standards for acidulant and stabilizer applications. Bakery sector demand in China and Spain pulls volume through specialized ingredient distributors serving industrial baking powder manufacturers. FDA 21 CFR 184.1077 compliance remains the baseline threshold for US-market placement.
- Pharmaceutical Grade:USP, EP, and ChP-certified material with tightened heavy metal and microbial specifications for oral formulation use. Swiss and German excipient manufacturers deploy membrane filtration hybrid systems to compress cost gaps against food-grade production while meeting pharmacopeial harmonization gaps.
- Industrial Grade:Technical specification material for chemical processing applications with lower purity thresholds than food or pharmaceutical tiers.
- Laboratory Grade:Analytical reagent specification serving academic R&D clusters in Germany and Switzerland with concentrated margin pools despite constrained volume.
Food Grade sits at the top of the volume ranking, with Pharmaceutical Grade climbing the fastest.
End User:
Customer-type concentration shapes procurement patterns, with formulation houses demanding documentation depth that commodity chemical buyers rarely require.
- Food Industry:Processed food manufacturers and craft beverage producers across France, California, and China's coastal provinces. Direct procurement relationships are displacing layered distributor networks in specialty channels where traceability demands exceed standard capabilities.
- Pharmaceutical Companies:Oral dosage form manufacturers requiring excipient certification dossiers for NMPA, FDA, and EMA submissions. Cross-contamination control capex for dedicated production lines strains mid-cap balance sheets.
- Research Laboratories:Academic and industrial R&D facilities in German and Swiss clusters.
- Chemical Manufacturers:Downstream compounders integrating tartrate derivatives into broader chemical portfolios.
Food Industry commands the dominant share, while Pharmaceutical Companies are gaining share fastest.
Application:
Functional use cases determine regulatory pathway complexity, with food-contact and pharmaceutical excipient routes diverging sharply on documentation burden.
- Food Additive:Acidulant, stabilizer, and pH buffer roles in baking powder and wine stabilization. Clean-label positioning in artisanal baking segments opens premium pricing tiers beyond commodity supply.
- Buffering Agent:pH control applications across food and chemical processing with formulation flexibility advantages over citric acid alternatives.
- Pharmaceutical Formulation:Oral solid dosage excipient use facing tightening pharmacopeial standards and harmonization gaps between USP, EP, and ChP heavy metal limits.
- Electrolyte:Specialized chemical and laboratory applications with niche volume concentration.
Food Additive leads by volume, with Pharmaceutical Formulation showing the steepest expansion trajectory.
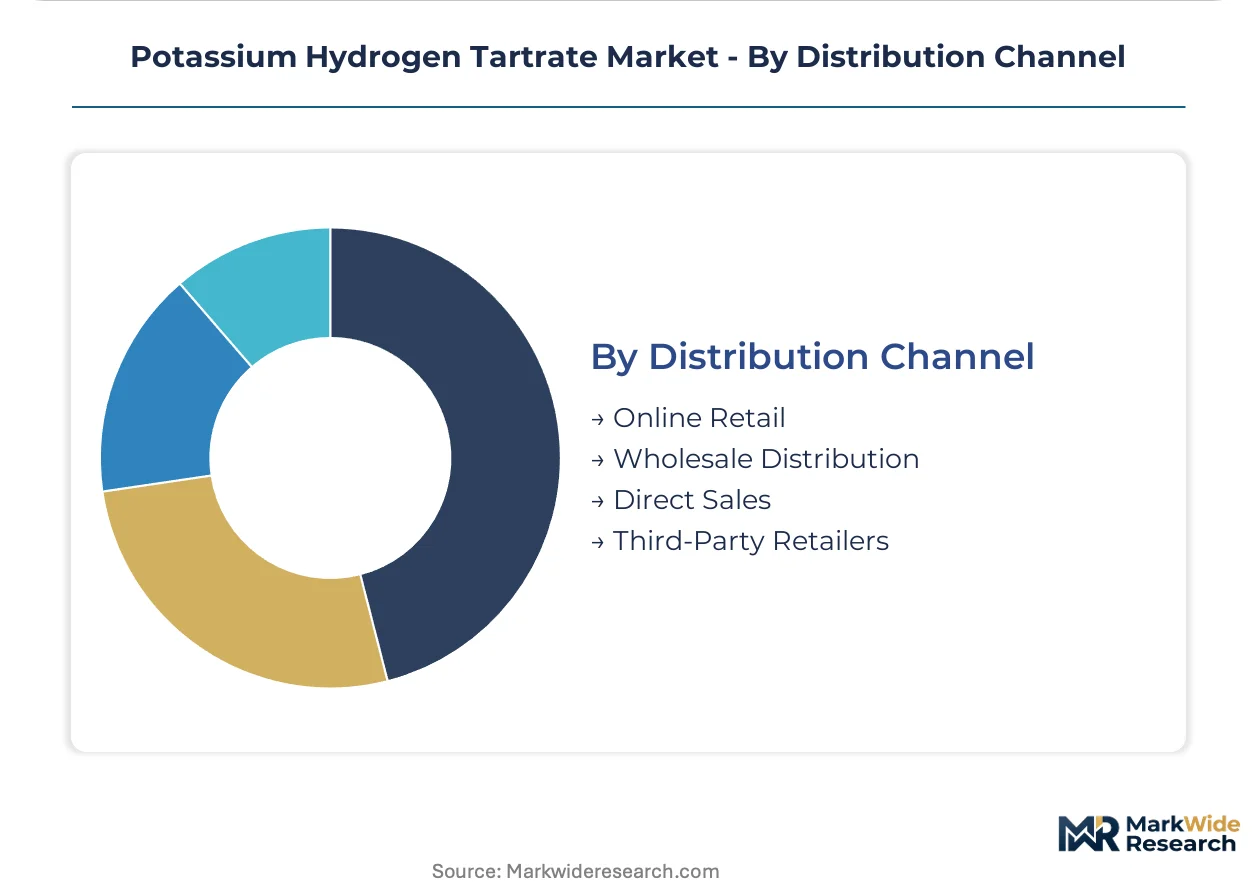
Distribution Channel:
Channel structure reflects customer scale fragmentation, with small-batch producers forcing documentation requirements upstream through approved vendor lists.
- Wholesale Distribution:Traditional layered networks serving industrial-scale food and chemical manufacturers with established logistics infrastructure.
- Direct Sales:Approved vendor relationships between certified suppliers and craft wineries in Burgundy and Napa Valley, plus artisanal bakeries demanding traceability documentation.
- Online Retail:Laboratory-grade material procurement by academic and small-scale R&D facilities.
- Third-Party Retailers:Specialty ingredient resellers serving fragmented craft producer segments.
Wholesale Distribution maintains volume leadership, with Direct Sales expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands derivative production scale while Switzerland and Germany anchor pharmaceutical-grade demand, creating divergent regulatory compliance burdens across supplier networks.
China
Fermentation-derived tartaric acid feedstock and coastal food processing clusters drive volume concentration. NMPA pharmaceutical excipient rules impose documentation requirements on exporters targeting formulation houses. Yangtze River Delta manufacturers serve both domestic bakery sector demand and international pharmaceutical certification channels.
Switzerland
Pharmaceutical excipient manufacturers deploy membrane filtration hybrid systems to meet tightening USP microbial specifications. Swissmedic certification requirements favor suppliers with cross-certified infrastructure. Basel and Zurich clusters concentrate analytical-grade demand from academic R&D facilities.
Germany
Laboratory reagent procurement from German academic clusters sustains concentrated margin pools for analytical-grade material. ECHA REACH registration mandates consolidate compliant supplier pools for industrial chemical placement. Bavarian wine stabilization facilities alter seasonal demand patterns under EU F-Gas Regulation retrofits.
Spain
Wine-derivative extraction operations sustain established enological chemical supply relationships. Spanish wineries shift cold stabilization timing to align with lower-GWP cooling infrastructure deployment. Catalonian and Rioja sub-regions concentrate tartrate precipitation chemical offtake.
United States
Craft beverage producers in California's Napa Valley establish approved vendor lists with documentation requirements previously reserved for industrial accounts. FDA 21 CFR 184.1077 compliance remains the baseline threshold for food additive market placement. Direct procurement relationships displace layered distributor networks in specialty channels.
Potassium Hydrogen Tartrate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across grade-specific certification tiers. Market structure fragments along purity thresholds, with food-grade volume concentrating among fermentation-integrated producers and pharmaceutical-grade margin pools attracting excipient specialists. Three archetypes dominate: integrated fermentation operators, wine-derivative extraction specialists, and pharmaceutical-grade certification holders. Capacity expansion in cross-certified manufacturing infrastructure and backward integration into tartaric acid feedstock represent the dominant competitive vectors.
Within the pharmaceutical-grade certification tier, Bioking Biochemical exemplifies the specialist archetype through USP-compliant positioning. Changmao Biochemical represents the integrated fermentation model serving regional Asian markets. Tártaros Gonzalo Castelló anchors the wine-derivative extraction segment through Spanish-based operations.
| Leading Market Players |
|---|
| Bioking Biochemical |
| Changmao Biochemical |
| Anhui Aibo |
| Anhui Hailan |
| Greatwall Biochem |
| Industrias Vinicas |
| Pahi |
| Randi Group |
| Tártaros Gonzalo Castelló |
| Others |
Pricing and Supply Chain Analysis
Membrane filtration integration with solvent crystallization is compressing cost economics for pharmaceutical-grade production while concentrating supply leverage among hybrid-system adopters in Switzerland and Germany. This technology shift simultaneously erodes legacy batch-crystallizer margins and rewards cross-certified manufacturers with pricing power across food and pharmaceutical tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for food-grade material as fermentation-integrated producers exploit captive tartaric acid supply. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates USP-certified excipients from FCC-compliant acidulants and technical-specification chemical feedstock. Cost compression in food-grade tiers is intensifying because citric acid substitution pressure limits pass-through elasticity. Industrial bakeries in China's coastal provinces exhibit highest price sensitivity, while Swiss pharmaceutical formulators accept premium positioning for microbial-compliant material.
Supply Chain Analysis
Specialized fermentation technicians and crystallization engineers concentrate in China's Jiangsu and Zhejiang provinces, constraining capacity expansion speed for non-integrated entrants. Supply draws from Chinese fermentation-derived tartaric acid, Spanish wine-derivative extraction operations, and Swiss membrane-filtration equipment manufacturers. Single-source vulnerability from tartaric acid feedstock concentration in China exposes compounders to export license disruptions. Distribution runs through specialized ingredient distributors serving industrial food manufacturers, with direct procurement relationships displacing layered networks in craft beverage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium hydrogen tartrate functions as a late-cycle quality story where pharmaceutical-grade certification premiums widen as USP, EP, and ChP harmonization gaps force reformulation costs onto non-compliant suppliers. Demand is shifting toward premium specifications as clean-label bakery positioning and oral formulation excipient standards tighten simultaneously.
For Market Incumbents: Extend cross-certified manufacturing infrastructure to capture pharmaceutical-grade margin expansion as harmonization gaps persist between USP and ChP microbial specifications. Deepen backward integration into tartaric acid feedstock to defend against Chinese supply concentration risk. Prioritize dedicated production line segregation to meet FDA 21 CFR 184.1077 and REACH registration mandates without batch-specific certification delays. For New Entrants and Emerging Players: Launch via direct sales relationships with craft wineries in Burgundy and Napa Valley where approved vendor list requirements exceed standard distributor documentation capabilities. Target laboratory-grade analytical reagent channels in German and Swiss academic clusters where concentrated margin pools offset constrained volume. Exploit membrane filtration technology licensing to compress cost gaps against established pharmaceutical-grade producers. For Investors and Strategic Acquirers: Valuations sit cheapest among wine-derivative extraction specialists with established enological chemical relationships but limited pharmaceutical certification infrastructure. Five-to-ten year viability hinges on pharmacopeial harmonization trajectory and fermentation-versus-extraction cost convergence. Watch EMA and FDA guidance alignment on heavy metal limits as the inflection signal for cross-certified infrastructure ROI.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Certified Capacity Expansion | Enables simultaneous USP, EP, and ChP compliance from shared fermentation feedstock. |
| Backward Integration into Tartaric Acid | Captures margin from Chinese feedstock concentration and reduces single-source exposure. |
| Membrane Filtration Technology Adoption | Compresses pharmaceutical-grade cost gaps while tightening USP microbial specifications. |
| Direct Sales Channel Development | Displaces distributor networks in Burgundy and Napa Valley craft beverage segments. |
| CSRD-Aligned Carbon Accounting | Positions fermentation-derived material for EU corporate sustainability reporting preference. |
Research Methodology
Coverage spans China, Switzerland, Germany, Spain, and the United States, with primary inputs from each region's manufacturing clusters and regulatory environments. The approach combines interviews with fermentation plant managers, pharmaceutical excipient procurement leads, enological chemical distributors, and laboratory reagent channel partners with secondary validation from customs and trade data, ECHA REACH registration dossiers, FDA 21 CFR filings, and SEC 10-K disclosures for diversified chemical producers. Bottom-up volume estimates from grade-specific production capacity triangulate against top-down demand segmentation across food, pharmaceutical, and laboratory end uses.
Granularity extends to grade tier, end-use industry, and regional production hub dimensions across the modeling period. CAGRs derive from segmented volume and value modeling with cross-validation against trade flow analysis and capacity expansion announcements. Forecast inputs incorporate REACH registration compliance timelines, EU F-Gas Regulation retrofit schedules, and NMPA pharmaceutical excipient rule evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt pharmacopeial specification divergence or Chinese export license restrictions. Projections reflect documented assumptions on fermentation yield improvements, membrane filtration adoption curves, and craft beverage direct procurement penetration rates. Material deviation in tartaric acid feedstock availability or EMA-FDA harmonization acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Medicinal Plant Extracts Market
Extracts
Agmatine Market
Extracts
Organic Herbal Extracts Market
Extracts
Thymoquinone Market
Extracts
Belladonna Market
Extracts
Global Azadirachtin Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Global Rose Oils Market
Extracts
Herb and Spice Extracts Market
Extracts
Irish Moss Extract Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Pectinase Market
Extracts
Valerian Root Powder Market
Extracts
Gelatin Hydrolysates Market
Extracts
Corn Steep Powder Market