
 Citrus Powder Market | 2026-2036
Citrus Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Powder Market Analysis
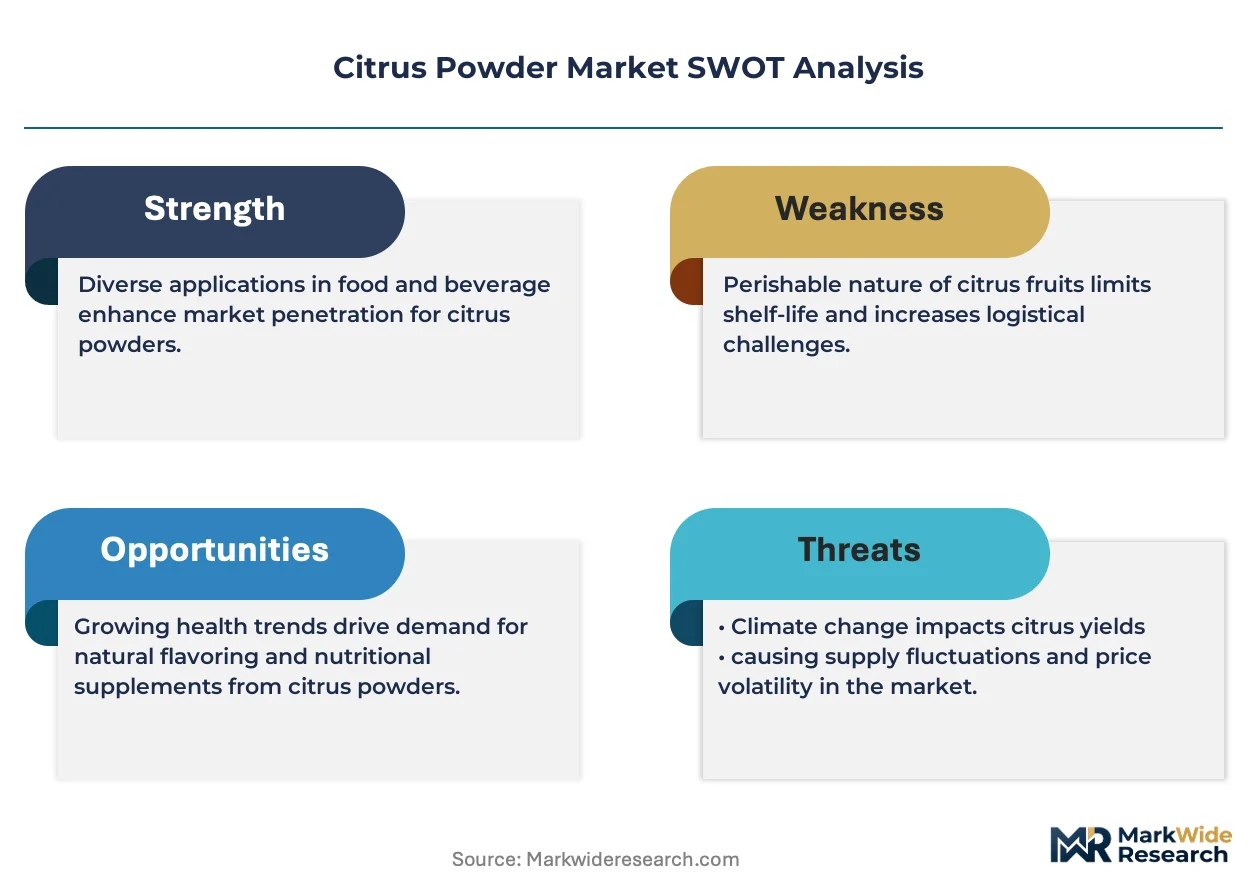
The capital-intensity divergence between spray-drying specialists and commodity traders is rotating competitive advantage toward integrated processors. Givaudan SA leverages captive flavor formulation expertise to command premium positioning in beverage applications. LemonConcentrate S.L. anchors its operations around Mediterranean citrus varietals, sustaining geographic specificity that commodity blenders cannot replicate. Van Drunen Farms differentiates through direct farm partnerships, controlling raw material provenance from orchard to powder.
Citrus powder consists of dehydrated citrus fruit tissue, typically produced via spray-drying or freeze-drying to achieve moisture content below 5% and preserve volatile terpene profiles for flavor retention. The material functions primarily as a natural flavoring agent, acidulant, and vitamin C carrier across formulated consumer products. Orange powder leads volume given its mild sweetness and broad compatibility with baking and beverage matrices, while grapefruit powder occupies narrower premium positioning in nutraceutical capsules where bioflavonoid content commands formulation premiums. The dry powder form dominates commercial logistics for its stability and shelf life, though liquid extracts capture share in ready-to-drink applications where reconstitution speed outweighs transport cost.
The FDA's GRAS self-affirmation pathway shapes US market entry timelines for novel citrus cultivar powders, while the EMA and EFSA jointly govern health claim substantiation for EU nutraceutical positioning. India's FSSAI enforces additive labeling thresholds that determine whether citrus powder qualifies as a natural ingredient or requires additive disclosure on packaged foods. Stakeholders must monitor evolving maximum residue limits for pesticide metabolites across these jurisdictions, as tightening standards threaten sourcing flexibility from conventional orchard regions.
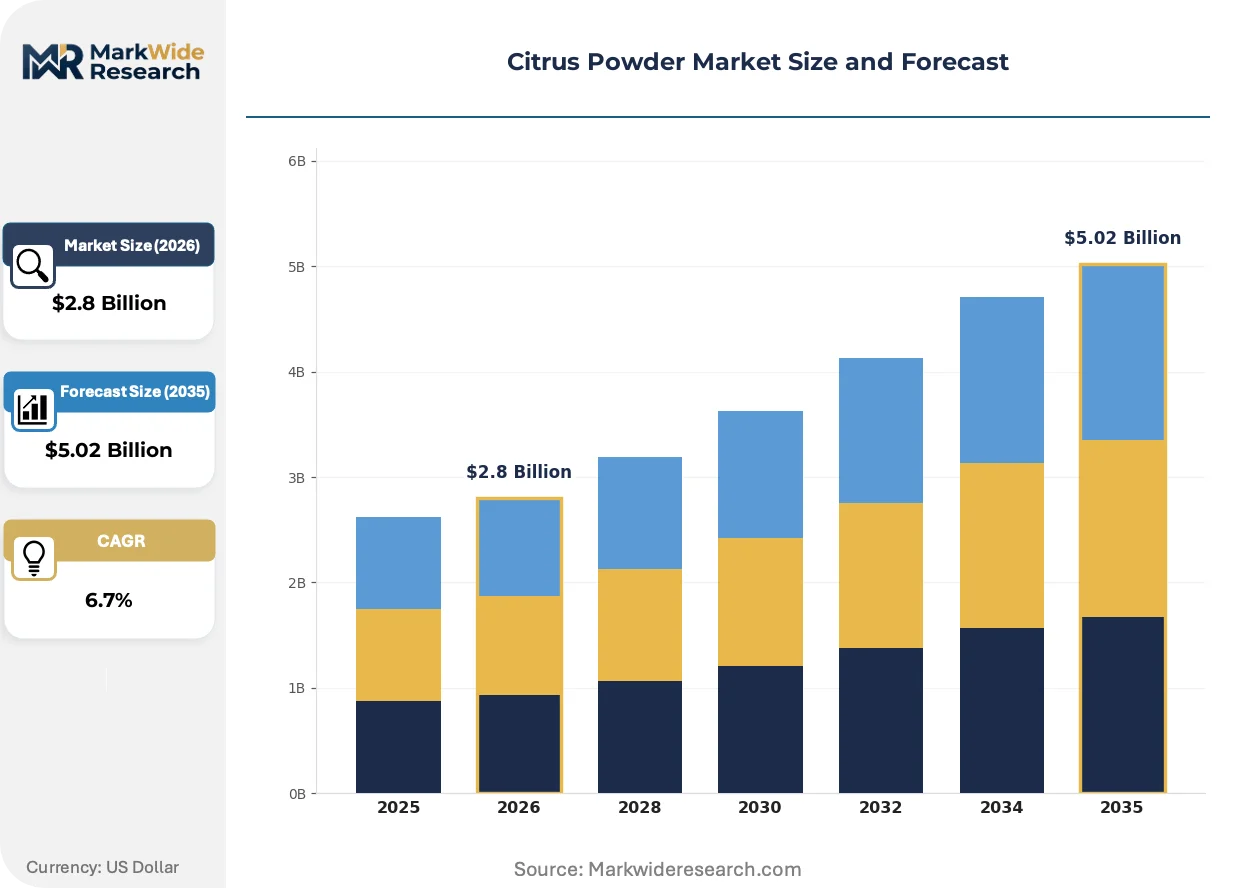
Market Dynamics
Clean-label vitamin C fortification is compressing synthetic ascorbic acid demand across beverage and nutraceutical formulations, redirecting procurement toward citrus-derived alternatives with traceable orchard provenance.
Growth Catalysts
- Novel Food Regulation (EU):The EU's streamlined approval pathways for citrus-derived bioactive extracts are accelerating new ingredient commercialization timelines for nutraceutical formulators seeking differentiated positioning.
- Spray-drying efficiency gains:Advanced atomization technologies are reducing energy intensity per kilogram of powder output, improving unit economics for processors serving price-sensitive bakery applications.
- Brazilian orange processing clusters:Concentrated raw material supply in São Paulo state is securing feedstock cost advantages for integrated processors with captive orchard partnerships.
Market Restraints
- Freeze-drying capital intensity:Equipment outlays for low-temperature dehydration exceed spray-drying by three to four times, restricting premium powder production to well-capitalized specialists.
- Seasonal supply volatility:Mediterranean citrus harvest fluctuations concentrate procurement risk for processors dependent on Spanish and Italian varietals without Southern Hemisphere sourcing diversification.
- Synthetic vitamin C substitution:Fermentation-derived ascorbic acid from Chinese producers maintains cost advantages in mass-market fortification applications where label claims permit non-botanical sources.
Strategic Opportunities
- Indian FSSAI threshold navigation:Processors achieving natural ingredient classification under India's additive disclosure rules can access packaged food channels where synthetic alternatives face mandatory labeling.
- Bioflavonoid extraction convergence:Combining citrus powder production with hesperidin and naringin recovery is creating dual-revenue streams from identical feedstock for nutraceutical ingredient suppliers.
- Direct-to-bakery distribution:Bypassing traditional ingredient distributors to supply artisanal and industrial bakeries through specialized e-procurement platforms is capturing margin previously absorbed by intermediaries.
Industry Challenges
- Terpenes preservation expertise gap:Formulators with volatile compound retention capabilities command premium compensation, constraining expansion for processors lacking specialized flavor chemistry talent.
- Maximum residue limit compliance:Tightening pesticide metabolite standards across the EU, US, and Japan are forcing supply chain requalification and testing protocol investments that strain mid-tier processor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Powder Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange Powder, Lemon Powder, Lime Powder, Grapefruit Powder End User: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Dry Powder, Liquid Extract, Granules, Crystals Application: Baking, Beverages, Seasoning, Flavoring |
| Companies Covered | Givaudan SA, Allen Flavors Inc., LemonConcentrate S.L., Van Drunen Farms, Paradiesfrucht GmbH, Cham Foods, Nutra Green Biotechnology Co., Ltd., Mountain Rose Herbs Inc., Nanjing NutriHerb BioTech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Powder Market Emerging Trajectories
Dehydration technology maturation and regulatory pathway evolution are simultaneously expanding application scope and compressing commercialization timelines for citrus-derived ingredients across formulated products.
Low-temperature vacuum microwave drying is displacing conventional freeze-drying for heat-sensitive citrus bioactives, with nutraceutical capsule manufacturers adopting the technology to preserve flavonoid integrity at 40% lower capital cost. The process enables smaller processors to enter premium positioning previously reserved for established freeze-drying specialists with legacy equipment bases.
REACH registration requirements for novel extraction solvents are forcing reformulation of citrus oil recovery processes across European processing facilities. The regulation's industrial consequence is accelerated investment in supercritical CO2 systems that eliminate solvent residue concerns entirely. Beverage flavor houses sourcing EU-processed citrus powders are now requiring documented REACH-compliant extraction methods in supplier qualification protocols.
Clean-label procurement mandates from retail grocery chains are compressing synthetic additive tolerance across private-label product development. Bakery and beverage category managers are specifying citrus powder fortification in vitamin C claims to satisfy consumer preference surveys indicating botanical source preference. This specification shift is most visible in German and French retail channels where discounter competition has amplified differentiation through ingredient transparency.
Citrus Powder Market Segmentation
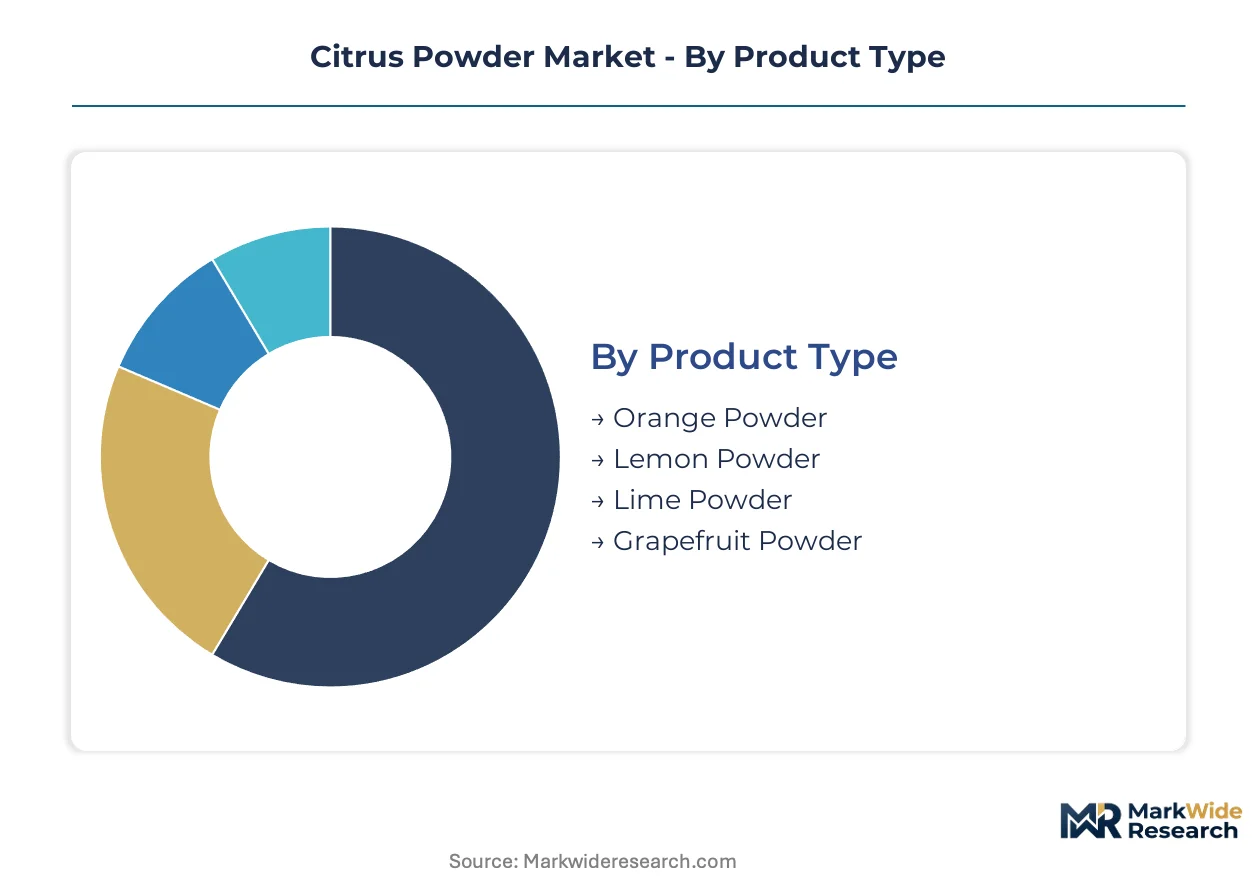
Citrus powder segmentation reveals distinct procurement patterns across product origins and processing tiers. Geographic concentration in raw material supply creates divergent cost structures that reshape competitive positioning by segment.
Product Type:
Orange powder dominates export-oriented supply chains anchored to Brazilian processing clusters, while Mediterranean-sourced lemon and lime powders serve premium domestic channels in European markets.
- Orange Powder:Mild sweetness and broad matrix compatibility position this segment as the workhorse for industrial bakery and beverage fortification. Brazilian São Paulo state processors leverage captive orchard partnerships to secure feedstock cost advantages for volume export contracts.
- Lemon Powder:Higher citric acid concentration and pronounced aromatic profile command formulation premiums in clean-label preservative applications. Spanish and Italian varietals sustain geographic specificity that commodity blenders cannot replicate, though harvest volatility concentrates procurement risk without Southern Hemisphere diversification.
- Lime Powder:Distinct terpene signature supports niche positioning in Latin American and Southeast Asian flavor formulations.
- Grapefruit Powder:Narrower premium positioning in nutraceutical capsules where bioflavonoid content drives ingredient selection.
Orange powder commands the established base. The steepest expansion runs through grapefruit powder as bioflavonoid extraction convergence creates dual-revenue streams.
End User:
Customer type determines specification stringency, with pharmaceutical and nutraceutical buyers imposing certificate-of-analysis requirements that exclude commodity-grade suppliers.
- Food & Beverage:Clean-label vitamin C fortification mandates from retail grocery chains redirect procurement toward traceable orchard provenance. Bakery and beverage category managers specify botanical-source claims to satisfy consumer preference surveys in German and French channels.
- Pharmaceuticals:Excipient-grade specifications require documented REACH-compliant extraction methods and pesticide residue testing protocols that strain mid-tier processor margins.
- Cosmetics:Antioxidant positioning in topical formulations leverages citrus bioflavonoid marketing claims subject to EMA and EFSA health claim substantiation requirements.
- Nutraceuticals:The fastest-growing end-use application as consumers shift toward clean-label vitamin C fortification, compressing synthetic ascorbic acid demand.
Food and beverage absorbs the volume base. Nutraceuticals is climbing the fastest as regulatory pathway streamlining accelerates new ingredient commercialization.
Form:
Moisture content and reconstitution speed trade off against transport economics and shelf stability across the four physical presentations.
- Dry Powder:Moisture content below 5% achieves stability for commercial logistics, though volatile terpene retention demands specialized atomization expertise.
- Liquid Extract:Captures share in ready-to-drink applications where reconstitution speed outweighs transport cost, particularly in US beverage manufacturing.
- Granules:Intermediate dissolution characteristics serve seasoning applications requiring controlled release.
- Crystals:Highest purity presentation commands pharmaceutical and premium nutraceutical positioning.
Dry powder holds the volume anchor. Liquid extracts are gaining share fastest in convenience-oriented beverage channels.
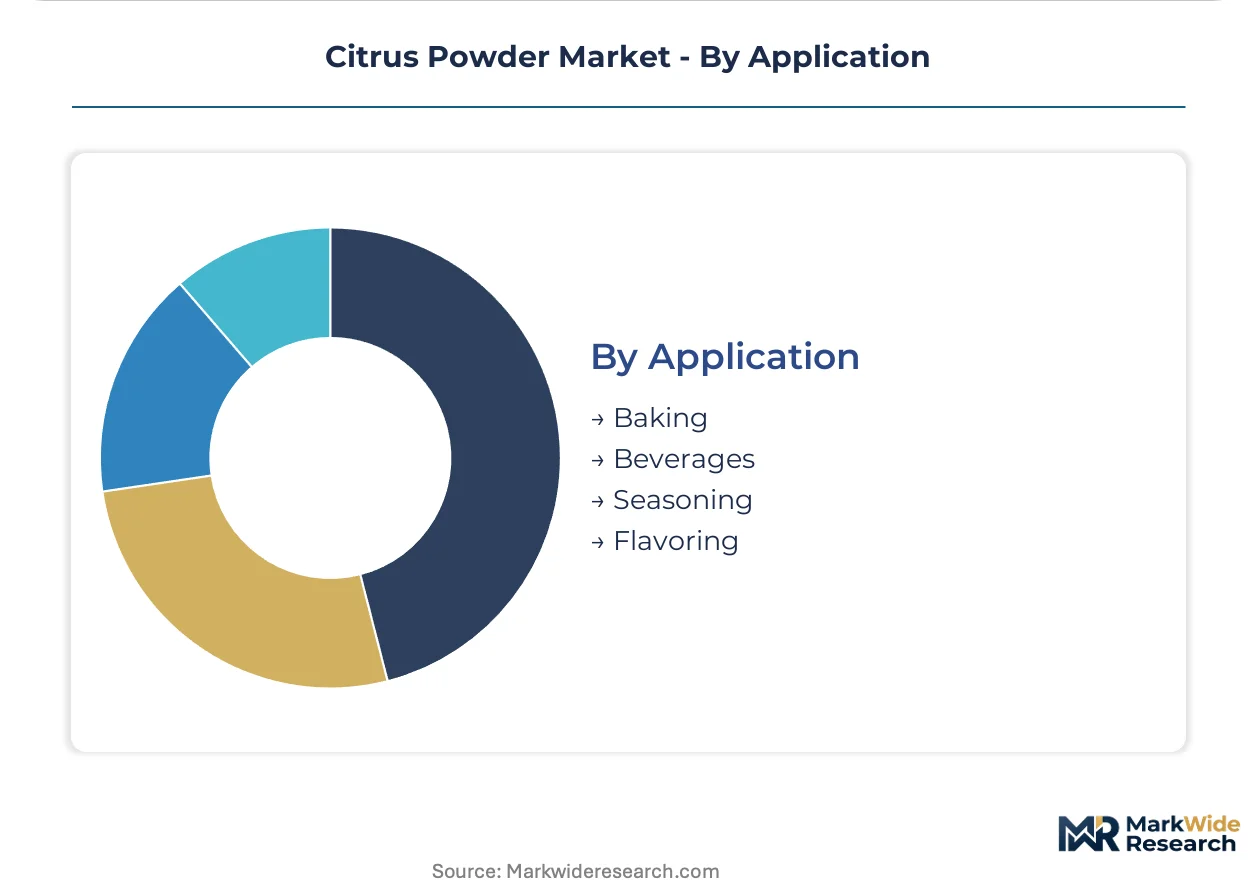
Application:
Heat exposure during processing determines terpene preservation requirements, with baking applications demanding the most robust flavor encapsulation.
- Baking:Heat-stable orange powder variants withstand oven temperatures without volatile loss, sustaining flavor impact in finished goods.
- Beverages:Rapid-dissolution specifications favor spray-dried powders with optimized particle size distribution for cold-mix applications.
- Seasoning:Granule form factors support controlled dispensing in savory blends.
- Flavoring:Premium positioning requires documented terpene retention capabilities that command specialized compensation.
Beverages anchor current demand. Flavoring applications show the steepest trajectory as beverage flavor houses enforce REACH-compliant extraction documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian processors command feedstock pricing leverage against European formulators, while Mediterranean suppliers extract premiums through geographic specificity that commodity blenders cannot replicate.
United States
FDA GRAS self-affirmation pathways accelerate novel citrus cultivar commercialization timelines for beverage and nutraceutical formulators. The agency's pesticide residue monitoring through Pesticide Residue Monitoring Program enforcement shapes sourcing decisions from Latin American suppliers. California's Central Valley citrus processing infrastructure anchors domestic spray-drying capacity for clean-label vitamin C fortification applications.
Brazil
São Paulo state orange processing clusters secure captive feedstock cost advantages for integrated processors serving export-oriented volume contracts. ANVISA's maximum residue limit enforcement for pesticide metabolites concentrates compliance investment among mid-tier exporters. The Triângulo Mineiro region's expanding citrus belt is attracting dehydration facility investment from international ingredient houses seeking Southern Hemisphere supply security.
Germany
REACH registration requirements for novel extraction solvents force reformulation of citrus oil recovery processes across flavor house supply chains. ECHA's industrial chemical authorization timelines determine capital deployment cycles for supercritical CO2 system adoption. The Hamburg-Bremen port complex serves as the primary entry node for Brazilian orange powder shipments into European bakery and beverage manufacturing channels.
India
FSSAI additive labeling thresholds determine whether citrus powder qualifies as natural ingredient or requires mandatory disclosure on packaged foods, redirecting procurement toward traceable orchard provenance. The regulator's evolving maximum residue limit harmonization with Codex Alimentarius standards strains conventional sourcing from untreated orchard regions. Maharashtra's Nagpur orange belt and Andhra Pradesh's citrus corridors are developing dehydration infrastructure to serve domestic nutraceutical capsule manufacturers.
Spain
EFSA health claim substantiation requirements govern nutraceutical positioning for Mediterranean lemon and lime varietals in premium export channels. The EU's Novel Food Regulation streamlined approval pathways accelerate bioflavonoid extract commercialization for Spanish processors. The Murcia and Valencia citrus belts sustain geographic specificity through controlled-origin denomination protections that commodity blenders cannot replicate.
Citrus Powder Market Vendor Landscape
Concentration sits with integrated processors possessing captive orchard partnerships and flavor chemistry expertise. The vendor base stratifies across three tiers: multinational flavor houses with beverage formulation integration, regional Mediterranean specialists leveraging geographic specificity, and commodity traders serving price-sensitive industrial applications. Competitive moves center on backward integration into orchard assets and technology licensing for volatile terpene retention capabilities.
Among Swiss-headquartered flavor houses, Givaudan SA exemplifies the integrated multinational archetype through captive formulation expertise. LemonConcentrate S.L. occupies a position within the Mediterranean geographic specificity tier. Van Drunen Farms represents the direct farm partnership model controlling raw material provenance from orchard to powder.
| Leading Market Players |
|---|
| Givaudan SA |
| Allen Flavors Inc. |
| LemonConcentrate S.L. |
| Van Drunen Farms |
| Paradiesfrucht GmbH |
| Cham Foods |
| Nutra Green Biotechnology Co., Ltd. |
| Mountain Rose Herbs Inc. |
| Nanjing NutriHerb BioTech Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Synthetic ascorbic acid displacement by citrus-derived vitamin C is redrawing procurement geography toward Brazilian orchard clusters while compressing margin structures for processors lacking captive feedstock. This substitution dynamic simultaneously elevates traceability premiums in European nutraceutical channels and intensifies cost competition in mass-market bakery applications.
Pricing Analysis
The customization-premium spread between configured-to-order grapefruit bioflavonoid extracts and standard orange powder runs wide. Three-tier pricing structure across premium, standard, and economy levels reflects terpene retention certification, organic orchard designation, and volume scale. Price differentiation hinges on REACH-compliant extraction documentation and direct farm partnership verification. Pricing pressure stems from Chinese fermentation-derived ascorbic acid undercutting botanical-source claims in cost-sensitive fortification applications. Industrial bakery buyers exhibit highest price sensitivity; pharmaceutical excipient purchasers tolerate substantial premiums for pesticide residue compliance.
Supply Chain Analysis
Inventory lead times stretch longest for Mediterranean lemon and lime varietals subject to harvest volatility without Southern Hemisphere diversification. Feedstock draws from Brazilian São Paulo orange clusters, Spanish Murcia-Valencia citrus belts, and emerging Indian Maharashtra-Andhra Pradesh corridors. Key inputs encompass fresh citrus fruit, spray-drying energy, and supercritical CO2 extraction solvents. Single-source vulnerability concentrates in São Paulo state processors commanding export contract leverage. Distribution runs through Hamburg-Bremen port entry for European manufacturing, with direct-to-bakery e-procurement platforms capturing intermediary margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail grocery chains specifying clean-label procurement mandates, fragmenting processor pricing leverage across fragmented supplier bases.
For Market Incumbents: Compound captive orchard partnerships through backward integration into Brazilian Triângulo Mineiro expansion zones and Mediterranean denomination-protected belts. Deepen terpene preservation expertise to defend premium positioning against low-temperature vacuum microwave drying entrants. Prioritize REACH registration completion for novel extraction solvents before ECHA authorization timelines tighten. For New Entrants and Emerging Players: Anchor in Indian domestic nutraceutical capsule manufacturing, where FSSAI natural ingredient classification creates protected channel access against synthetic additive disclosure requirements. Target direct-to-bakery e-procurement white space bypassing traditional ingredient distributors. Pursue bioflavonoid extraction convergence as dual-revenue stream differentiation from identical feedstock. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Mediterranean geographic specialists lacking Southern Hemisphere sourcing diversification. Five-to-ten year viability favors processors with integrated spray-drying infrastructure and documented farm-to-powder traceability systems. Monitor ANVISA maximum residue limit enforcement intensity as inflection indicator for Brazilian export cost structure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Orchard Partnership Expansion | Brazilian Triângulo Mineiro facility investment secures Southern Hemisphere supply security for export contracts. |
| Low-Temperature Vacuum Microwave Drying Adoption | 40% capital cost reduction versus freeze-drying enables premium segment entry for mid-tier processors. |
| REACH-Compliant Supercritical CO2 System Deployment | ECHA solvent authorization timelines force extraction process reformulation across European flavor houses. |
| Bioflavonoid Extraction Convergence | Hesperidin and naringin recovery creates dual-revenue streams from identical citrus feedstock. |
| Direct-to-Bakery E-Procurement Platform Launch | Bypassing traditional distributors captures margin previously absorbed by intermediary channel layers. |
Methodological Framework
Cross-validation between processor production data and retail procurement specifications anchors the qualitative findings in this study. Primary interviews with spray-drying facility managers, nutraceutical formulators, bakery category buyers, and flavor house technical directors combined with secondary validation from FDA GRAS notifications, EFSA health claim submissions, ANVISA residue monitoring reports, and FSSAI additive classification rulings. Bottom-up capacity modeling and top-down demand triangulation reconcile volume estimates across the analysis window.
Sensitivity analysis around Brazilian harvest yield variance and EU Novel Food approval velocity shapes the analytical framework. Segmentation dimensions span citrus varietal, processing technology tier, end-use application, and geographic regulatory cluster. CAGRs derive from fitted trend extrapolation against historical volume trajectories, incorporating spray-drying energy intensity improvements and clean-label procurement mandate diffusion rates as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained Brazilian orchard productivity and stable REACH enforcement intensity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Marine Algae Polysaccharides Market
Extracts
Orange Oil Market
Extracts
Pectin Powder Market
Extracts
Industrial Extractor Market
Extracts
Natural Rosemarine Extract Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Bee Venom Extract Market
Extracts
Thymoquinone Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Essential Oil Isolates Market
Extracts
Plum Extract Market
Extracts
Algae Extracts Market
Extracts
Corn Steep Powder Market
Extracts
Jalapeno Extract Market
Extracts
Pectinase Market
Extracts
Potassium Hydrogen Tartrate Market