
 Bidens Pilosa Extract Market | 2026-2036
Bidens Pilosa Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Bidens Pilosa Extract Market Outlook
Modular capsule-and-powder bundling is consolidating as the dominant product-configuration pattern, letting buyers toggle between bulk manufacturing inputs and finished consumer formats. DSM leverages its integrated nutraceutical infrastructure to anchor European pharmaceutical-grade supply. BASF competes through cosmetic-active specialization, while Hunan Nutramax dominates Chinese extraction capacity for powder intermediates.
Bidens pilosa extract comprises flavonoids, polyacetylenes, and caffeic acid derivatives obtained through solvent extraction or supercritical CO2 processing, primarily serving cosmetic anti-inflammatory and pharmaceutical anti-diabetic applications. Powder formats lead manufacturing throughput due to stability in bulk compounding, though liquid extracts capture faster growth in clean-label cosmetic serums where solubility simplifies formulation. Cosmetics and dietary supplements concentrate margin pools, while herbal remedies remain fragmented across traditional medicine channels.
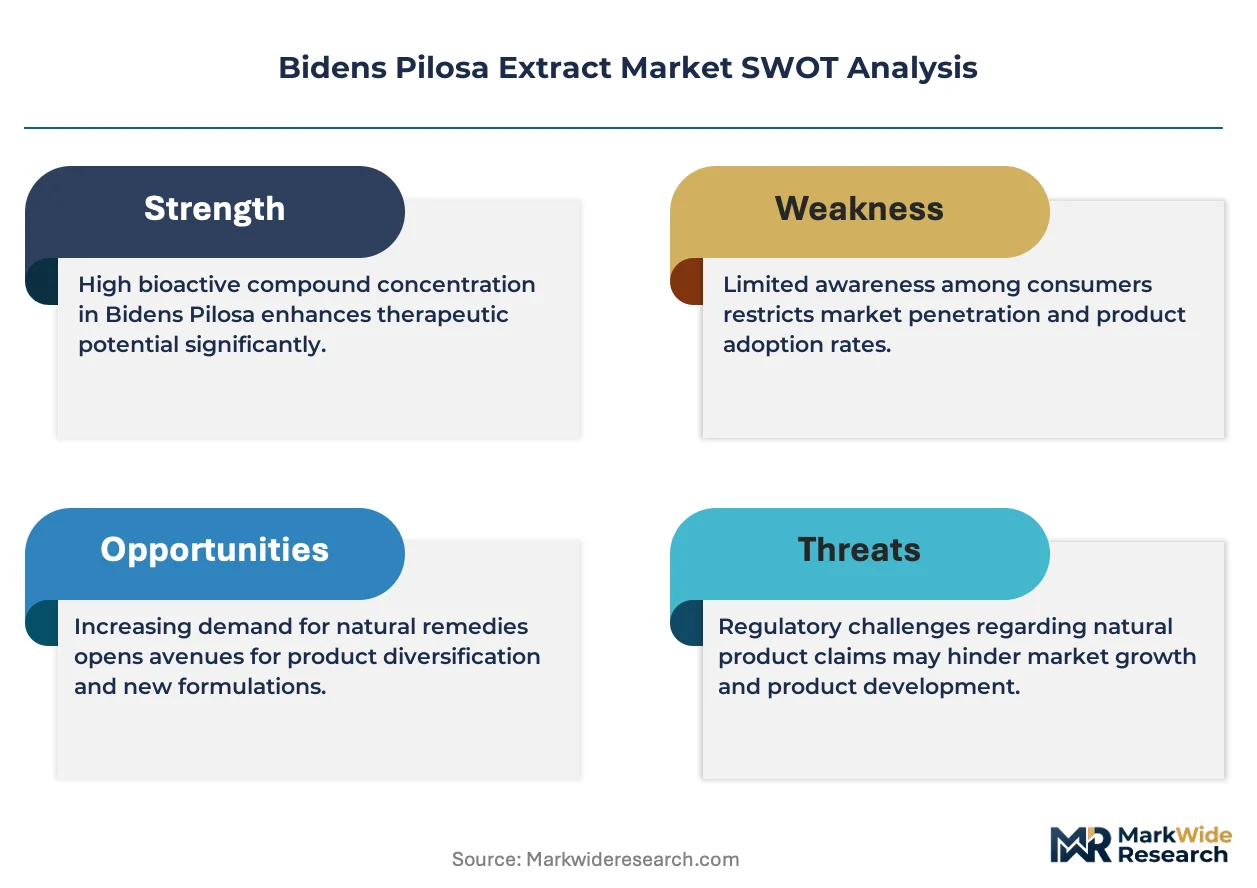
EMA cosmetic ingredient guidelines, REACH substance registration, and China's NMPA botanical drug standards collectively elevate analytical and traceability burdens on suppliers. FDA GRAS self-affirmation pathways for dietary supplement use create dual-track compliance complexity for cross-border marketers. Stakeholders must monitor evolving pharmacovigilance requirements for botanical actives as regulatory convergence between cosmetic and pharmaceutical classifications accelerates.
Market Dynamics
Clean-label certification mandates across cosmetics and nutraceuticals are compressing supplier qualification timelines while fragmenting raw material sourcing networks. REACH substance registration and China's NMPA botanical drug standards now require batch-level phytochemical traceability that many mid-tier extractors cannot operationalize.
Growth Catalysts
- Anti-aging cosmetic actives:Formulators at European and North American personal care brands are expanding Bidens pilosa extract inclusion in skin-brightening serums, driven by consumer preference for plant-derived alternatives to synthetic retinoids.
- REACH compliance infrastructure:Early investment in full substance dossier preparation by specialized European suppliers has created preferential access to pharmaceutical-grade procurement channels.
- Traditional medicine heritage in China:Domestic NMPA recognition of Bidens pilosa as a botanical drug raw material accelerates ingredient acceptance across dietary supplement and herbal remedy distribution networks.
Market Restraints
- Wild-harvest supply concentration:Primary raw material sourcing clusters in subtropical Chinese provinces create weather-dependent yield volatility and quality inconsistency.
- Supercritical CO2 equipment capex:Pharmaceutical-grade extraction capacity expansion requires specialized high-pressure processing infrastructure that locks in 7-10 year depreciation cycles.
- Synthetic anti-inflammatory substitutes:Cost-competitive corticosteroid analogs in topical dermatology formulations limit extract penetration in price-sensitive mass-market segments.
Strategic Opportunities
- Clean-label certification convergence:USDA Organic and EU Organic dual-certification pathways enable premium positioning in cross-border nutraceutical distribution.
- India Ayurvedic channel expansion:Underpenetrated traditional medicine networks in Kerala and Karnataka offer first-mover positioning for standardized extract formats.
- Supercritical-fluid and microwave-assisted extraction convergence:Hybrid processing technologies reduce solvent residue while preserving heat-sensitive polyacetylene compounds for high-potency cosmetic actives.
Industry Challenges
- Phytochemical standardization expertise:Scarcity of analytical chemists proficient in flavonoid and polyacetylene quantification methods delays batch release timelines.
- Dual-track compliance complexity:Simultaneous FDA GRAS self-affirmation and EMA cosmetic ingredient dossier preparation strains regulatory affairs bandwidth at mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bidens Pilosa Extract Market |
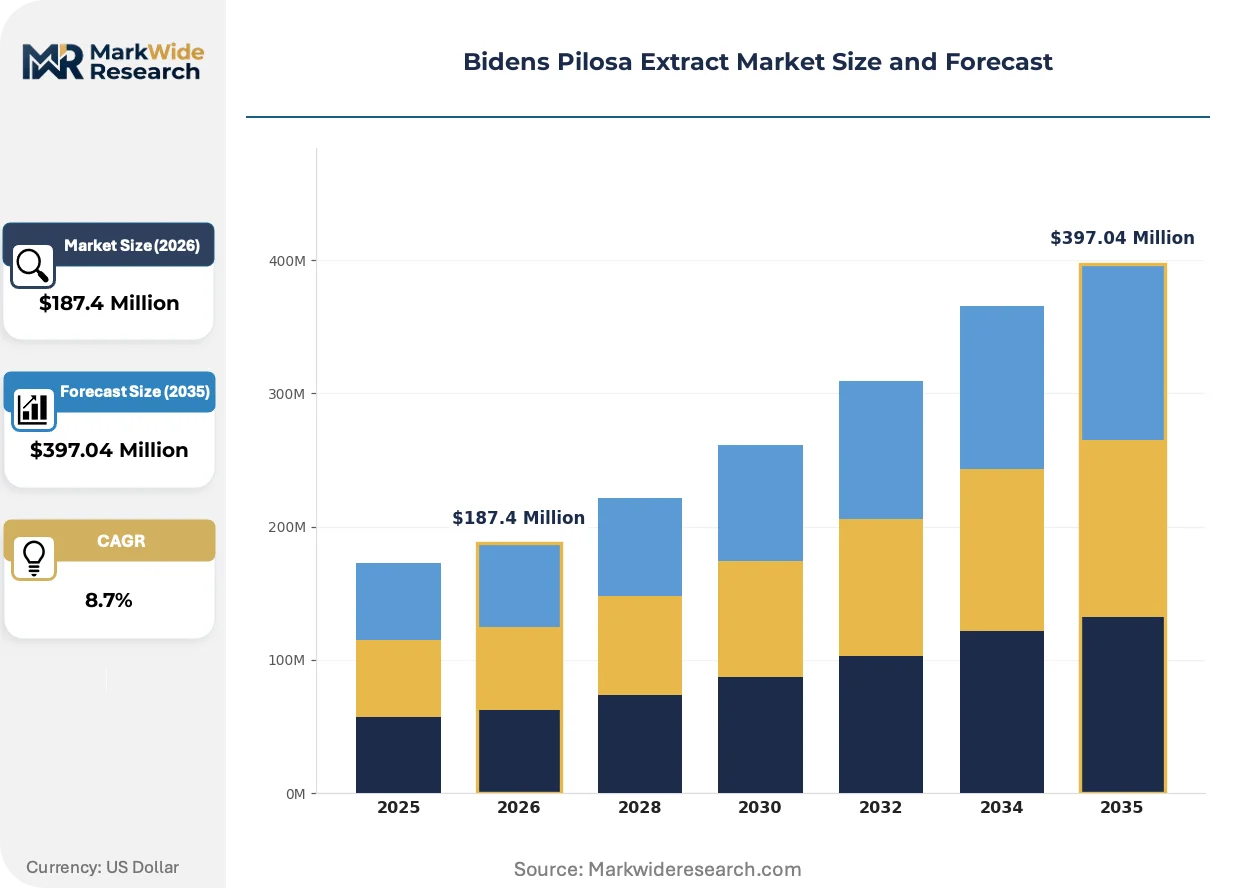
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tincture, Capsule Application: Cosmetics, Pharmaceuticals, Dietary Supplements, Herbal Remedies Distribution Channel: Online Stores, Retail Outlets, Health Shops, Direct Sales End User: Consumers, Healthcare Providers, Manufacturers, Researchers |
| Companies Covered | Chemyunion, Koei Kogyo, Bath Spa Skincare, Hunan Nutramax, Xi'an DN Biology, Xi'an Teng Yun Biotech, Yangling Ciyuan Biotech, DSM, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bidens Pilosa Extract Market Strategic Shifts
Processing technology convergence and regulatory classification shifts are compressing the gap between cosmetic and pharmaceutical-grade supply tiers. These developments are redrawing competitive boundaries around analytical capabilities rather than extraction scale alone.
Supercritical CO2 extraction with inline chromatographic fractionation is electrifying the separation of caffeic acid derivatives from less active co-extractives. Specialty cosmetic laboratories in France and Germany are adopting these systems at replacement cycle pace. The technology is electrifying premium serum formulation economics by reducing downstream purification steps.
EMA's 2023 update to cosmetic ingredient safety assessment guidelines is mandating expanded dermal sensitization data for botanical actives above 0.1% concentration. European formulators now face reformulation costs or supplier switching to dossier-complete sources. Fragrance-free anti-aging segments are most affected, with brands accelerating supplier audits to preempt registration gaps.
Ingredient sourcing decisions now hinge on certification depth rather than unit cost alone. Cosmetic brand procurement teams are consolidating supplier relationships around dual-certified organic and FairWild sources, displacing spot-market purchasing. This concentration is most visible in German and Swiss premium skincare markets, where retailer sustainability scorecards determine shelf access.
Bidens Pilosa Extract Market Segmentation
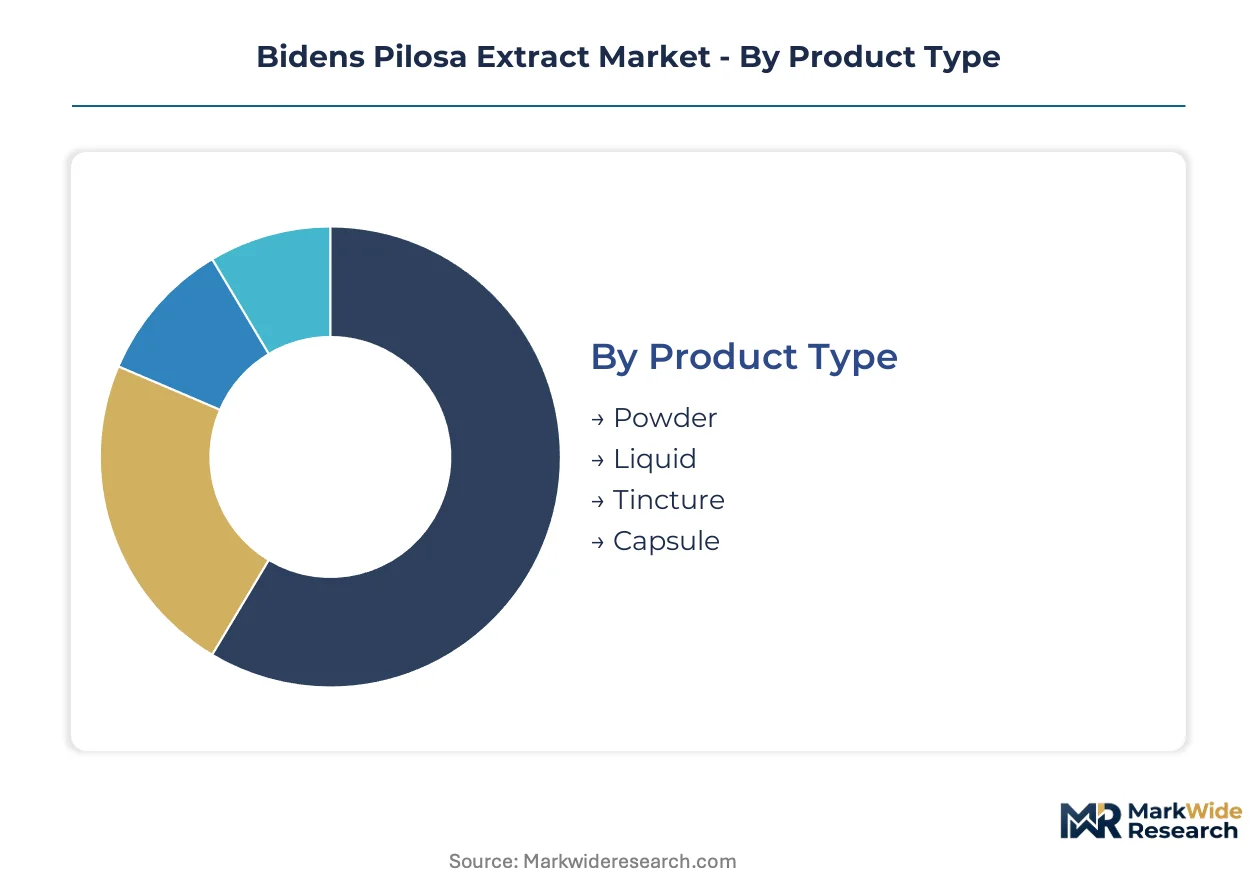
Segmentation in Bidens pilosa extract markets reveals how regulatory thresholds fragment supply tiers. Certification requirements for REACH dossiers, FDA GRAS self-affirmation, and NMPA botanical drug standards create divergent qualification pathways that reshape competitive boundaries across each category.
Product Type:
Powder formats require REACH substance registration for European pharmaceutical procurement, while liquid extracts face EMA cosmetic ingredient safety assessments above threshold concentrations. Tinctures and capsules navigate FDA dietary supplement labeling rules with varying analytical burdens.
- Powder:Dried extract standardized to flavonoid and polyacetylene content serves bulk cosmetic compounding and pharmaceutical intermediate manufacturing. Stability in ambient storage drives procurement from Hunan and Guangxi extraction facilities serving DSM and BASF supply contracts. REACH-registered powder commands premium positioning in German and Swiss pharmaceutical-grade channels.
- Liquid:Hydroalcoholic or glycerin-based solutions with enhanced solubility accelerate clean-label serum formulation timelines. French and German cosmetic laboratories source liquid formats for dermal delivery systems, though EMA's expanded sensitization data requirements above 0.1% concentration compress supplier qualification pools.
- Tincture:Traditional alcohol-based preparations retain heritage positioning in Chinese herbal remedy distribution and North American naturopathic channels.
- Capsule:Pre-dosed softgel and hard-shell formats streamline finished nutraceutical manufacturing for direct-to-consumer brands.
Leading the category by volume: Powder. Growing fastest: Liquid.
Application:
Margin structures diverge sharply across end-use segments, with cosmetics and dietary supplements capturing premium pools while herbal remedies fragment across traditional medicine networks.
- Cosmetics:Anti-aging and skin-brightening serums incorporate standardized caffeic acid derivatives as plant-derived retinoid alternatives. European formulators at L'Oréal and Beiersdorf suppliers face reformulation costs from EMA's 2023 dermal sensitization guideline updates, accelerating audits of dossier-complete extract sources.
- Pharmaceuticals:Anti-diabetic and anti-inflammatory drug development pipelines require NMPA-recognized botanical drug raw material status. China's domestic suppliers leverage traditional medicine heritage to anchor extraction capacity for pharmaceutical-grade procurement.
- Dietary Supplements:Capsule and tablet formats navigate FDA GRAS self-affirmation pathways with dual-track complexity for cross-border marketers.
- Herbal Remedies:Traditional medicine channels in Kerala and Karnataka present underpenetrated expansion opportunities for standardized extract formats.
Cosmetics commands the highest unit margins. Pharmaceuticals shows the steepest expansion trajectory from clinical pipeline activity.
Distribution Channel:
Channel selection determines certification depth requirements, with direct sales to manufacturers demanding batch-level phytochemical traceability that spot-market intermediaries cannot operationalize.
- Online Stores:Direct-to-consumer platforms consolidate USDA Organic and EU Organic dual-certified SKUs, displacing conventional extract sales. German and Swiss premium skincare markets use retailer sustainability scorecards to filter shelf access.
- Retail Outlets:Mass-market pharmacy and supermarket chains in France and Italy drive volume for standardized capsule formats with established GRAS status.
- Health Shops:Specialized nutrition and wellness retailers in North America curate clean-label tincture and liquid extract assortments.
- Direct Sales:B2B supply contracts to cosmetic laboratories and pharmaceutical manufacturers require REACH dossier completeness and NMPA botanical drug recognition.
Direct Sales dominates procurement value. Online Stores is gaining share fastest from sustainability-scorecard retail consolidation.
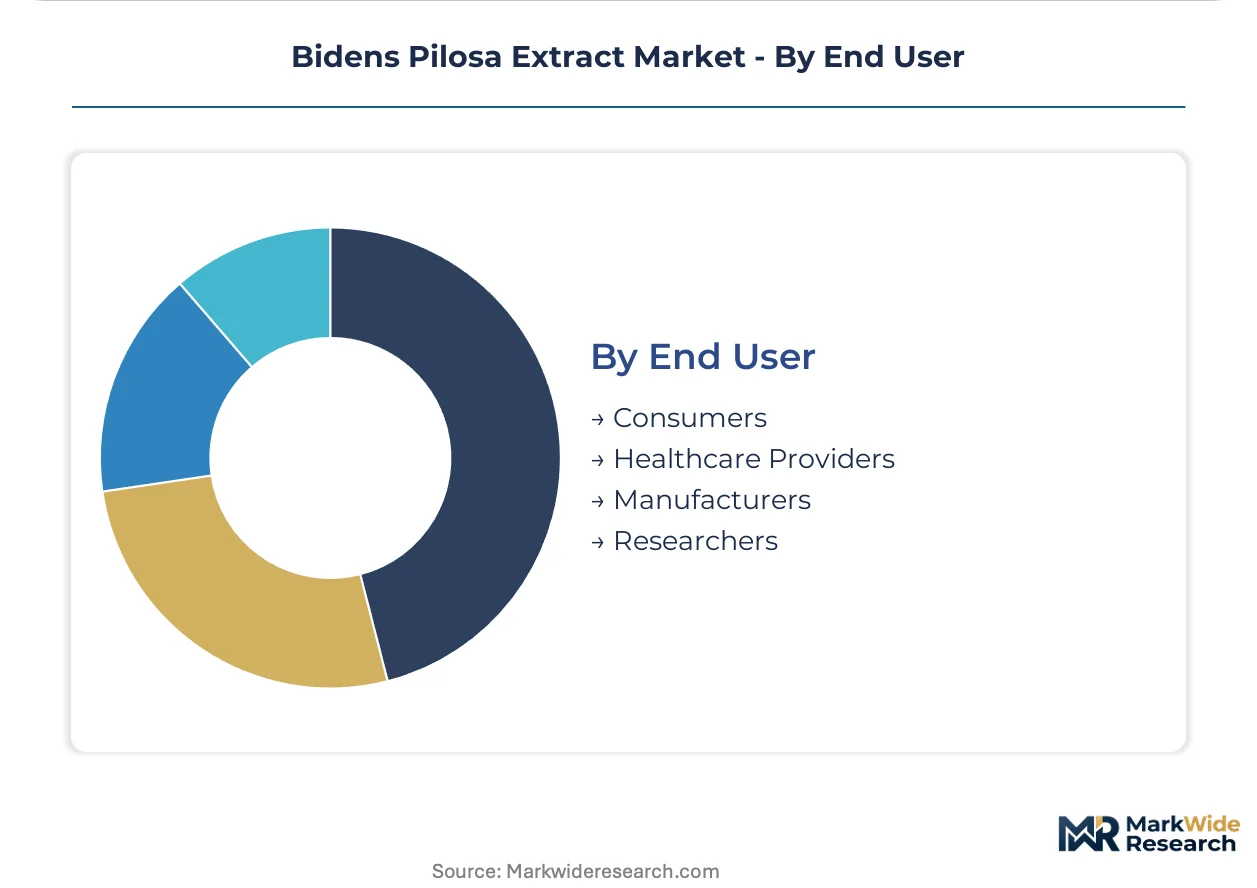
End User:
User type dictates specification granularity, with manufacturers and researchers requiring certificate-of-analysis depth that consumer-facing channels rarely demand.
- Consumers:Individual purchasers prioritize certified organic and FairWild sourcing badges over unit cost in German and Swiss premium markets.
- Healthcare Providers:Naturopathic and integrative medicine practitioners in North America specify tincture formats with documented phytochemical standardization.
- Manufacturers:Cosmetic and pharmaceutical formulators consolidate supplier relationships around dual-certified sources with REACH and NMPA compliance infrastructure.
- Researchers:Academic and clinical trial investigators require batch-level quantification of flavonoid and polyacetylene fractions with validated analytical methods.
Manufacturers represent the largest procurement volume. Researchers is expanding most quickly from pharmacological study activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands extraction capacity while European and North American markets absorb finished formulations. This production-consumption divide shapes regulatory arbitrage and supply chain configuration across the value chain.
China
Hunan and Guangxi provinces anchor wild-harvest collection and solvent extraction infrastructure for powder intermediates. NMPA botanical drug standards require batch-level phytochemical documentation that domestic suppliers leverage for pharmaceutical-grade procurement. Yangling Biotech clusters in Shaanxi are deploying supercritical CO2 systems to capture premium cosmetic-active contracts from European formulators.
Germany
EMA cosmetic ingredient guidelines and REACH substance registration create preferential access for dossier-complete suppliers in skin-brightening serum formulations. Baden-Württemberg specialty chemical clusters integrate inline chromatographic fractionation to reduce downstream purification steps. Frankfurt procurement offices at Beiersdorf and L'Oréal suppliers are consolidating supplier relationships around dual-certified organic sources.
United States
FDA GRAS self-affirmation pathways for dietary supplement use attract capsule-format manufacturers seeking cross-border distribution flexibility. California clean-label cosmetic brands drive liquid extract demand for solubility-optimized serums. Pacific Northwest naturopathic distribution networks specify tincture formats with documented standardization for integrative medicine practitioners.
France
ANSM enforcement of EMA's 2023 dermal sensitization data requirements above 0.1% concentration compresses supplier qualification pools for fragrance-free anti-aging segments. Provence-Alpes-Côte d'Azur cosmetic laboratories adopt hybrid microwave-assisted extraction to preserve heat-sensitive polyacetylenes. Paris-based premium skincare brands use retailer sustainability scorecards to filter shelf access for FairWild-certified inputs.
India
Ayurvedic channel expansion in Kerala and Karnataka presents underpenetrated positioning for standardized extract formats. CDSCO botanical drug regulations and FSSAI dietary supplement standards create dual-track compliance complexity for cross-border marketers. Maharashtra pharmaceutical formulation clusters are evaluating NMPA-recognized Chinese suppliers for anti-diabetic drug development pipelines.
Bidens Pilosa Extract Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers. The vendor base stratifies between REACH-registered pharmaceutical-grade suppliers, EMA-compliant cosmetic-active specialists, and traditional medicine channel intermediaries. Three archetypes dominate: integrated nutraceutical infrastructure operators, extraction-technology pure-plays, and regional wild-harvest sourcing networks. Capacity expansion in supercritical CO2 equipment and strategic partnerships for dual-certification procurement represent the dominant competitive moves.
Among European diversified chemical groups, DSM and BASF occupy positions spanning pharmaceutical-grade and cosmetic-active supply tiers. Hunan Nutramax exemplifies the China-based extraction-capability archetype, anchoring powder intermediate production for multinational supply contracts. These three entities represent the competitive spectrum from integrated infrastructure to regional specialization.
| Leading Market Players |
|---|
| Chemyunion |
| Koei Kogyo |
| Bath Spa Skincare |
| Hunan Nutramax |
| Xi'an DN Biology |
| Xi'an Teng Yun Biotech |
| Yangling Ciyuan Biotech |
| DSM |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Analytical chemist scarcity in Hunan and Guangxi extraction clusters widens labor-cost differentials between REACH-registered pharmaceutical-grade suppliers and commodity powder intermediates, compressing margin spreads at the standard tier while premium pricing holds firm.
Pricing Analysis
Margin tightening in standard-grade powder reflects wild-harvest yield volatility and supercritical CO2 equipment depreciation burdens. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered pharmaceutical suppliers from EMA-compliant cosmetic specialists and unregistered commodity extractors. Price differentiation hinges on certification depth—dual-certified organic and FairWild sources command 40-60% premiums over conventional grades. Cost-down pressure on economy-tier powder accelerates because synthetic corticosteroid substitutes erode market share in price-sensitive mass-market dermatology. Pharmaceutical manufacturers show least price sensitivity; direct-to-consumer capsule brands face acute margin compression.
Supply Chain Analysis
Dual-sourcing mandates from European cosmetic formulators require simultaneous qualification of Hunan Nutramax and Yangling Ciyuan Biotech capacity to preempt weather-dependent yield disruptions. Geographic supply concentration centers on China for wild-harvest raw material and solvent extraction infrastructure, Germany for inline chromatographic fractionation systems, and France for dermal delivery formulation. Raw material dependencies draw from subtropical Bidens pilosa cultivation zones, high-pressure CO2 processing equipment, and phytochemical standardization reagents. Single-source vulnerability in Chinese wild-harvest clusters exposes buyers to quality inconsistency and regulatory audit failures. Distribution runs through direct B2B contracts to cosmetic laboratories and pharmaceutical manufacturers, bypassing spot-market intermediaries lacking batch-level traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance registration operates as a cost-of-compliance moat, elevating analytical and dossier-preparation barriers that mid-tier extractors cannot operationalize and thereby consolidating procurement access around early-investor European suppliers.
For Market Incumbents: Hedge wild-harvest supply volatility through captive cultivation partnerships in Guangxi and backward integration into supercritical CO2 equipment operation. Synthetic retinoid substitutes threaten plant-derived cosmetic actives; defend positioning by accelerating dual-certification procurement for premium serum contracts. Capacity addition in Shaanxi Yangling clusters anchors pharmaceutical-grade supply security.
For New Entrants and Emerging Players: NMPA botanical drug recognition in China opens a window for standardized extract formats in underpenetrated Kerala and Karnataka Ayurvedic channels. Target India's CDSCO regulatory pathway for anti-diabetic drug development pipelines. Go-to-market angle: hybrid microwave-assisted extraction technology preserving heat-sensitive polyacetylenes for cosmetic laboratories seeking EMA-compliant sensitization data.
For Investors and Strategic Acquirers: Re-rating potential sits with REACH-registered extraction-technology pure-plays given regulatory convergence between cosmetic and pharmaceutical classifications. Long-term viability over a 5-10 year horizon favors suppliers with integrated supercritical CO2 and inline chromatographic infrastructure. Watch for EMA cosmetic ingredient guideline updates as inflection signal for supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Captures pharmaceutical-grade procurement from NMPA-recognized Chinese suppliers. |
| Dual-Certification Procurement Partnership | Enables premium positioning in German and Swiss retailer sustainability scorecards. |
| Hybrid Extraction Technology Deployment | Preserves heat-sensitive polyacetylenes for EMA-compliant cosmetic serum formulations. |
| Backward Integration into Wild-Harvest Cultivation | Reduces weather-dependent yield volatility in subtropical Chinese sourcing clusters. |
| Regulatory Dossier Preparation Investment | Secures preferential access to REACH-registered European pharmaceutical supply channels. |
Study Parameters
Trade databases, EMA cosmetic ingredient submission records, and NMPA botanical drug registration filings formed the secondary backbone for this analysis. Primary interviews with extraction plant managers, cosmetic formulation R&D directors, regulatory affairs specialists at European suppliers, and procurement leads at German personal care brands validated supply chain configurations. Bottom-up triangulation against top-down trade flow estimates anchored volume and value assessments across the forecast period.
Historical trendline analysis of powder intermediate and liquid extract pricing informed the projection framework. Segmentation dimensions modeled include product format, application end-use, certification tier, and regional regulatory cluster. CAGRs derived from supply-side capacity expansion schedules and demand-side formulation adoption curves. Forecast inputs incorporated supercritical CO2 equipment deployment timelines and EMA guideline update implementation trajectories.
The model assumes a particular technology adoption path; alternative pathways for microwave-assisted extraction convergence would alter the outlook. Forecasts reflect assumptions around regulatory enforcement intensity and wild-harvest yield stability. A model refresh is warranted upon material change in REACH substance registration deadlines or NMPA botanical drug standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Myrrh Powder Market
Extracts
Organic Extracts Market
Extracts
Chamomile Oil Market
Extracts
Chlorophyll Extract Market
Extracts
Global Ginseng Extracts Market
Extracts
Aloe Vera Extract Market
Extracts
Citronella Oil Market
Extracts
Lavender Oil Market
Extracts
Irish Moss Market
Extracts
Botanicals Market
Extracts
White Willow Bark Extract Market
Extracts
Sage Extract Market
Extracts
Extracts and Distillates Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Citrus Powder Market
Extracts
Thymoquinone Market