
 Strength Training Equipment Market | 2026-2036
Strength Training Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Strength Training Equipment Market Analysis
Certified strength coaching labor is collapsing across commercial fitness chains, forcing operators to prioritize equipment that reduces hands-on instruction dependency. Technogym S.p.A leverages embedded biomechanical feedback screens to sustain premium positioning in European health clubs. Rogue Fitness anchors its dominance in North American collegiate and CrossFit affiliate channels through made-in-USA barbell and rig fabrication. Matrix Fitness competes on integrated console ecosystems that occupy the mid-market commercial segment with scalable software subscriptions.
Strength training equipment encompasses mechanically loaded resistance apparatus designed to induce muscular hypertrophy and neuromuscular adaptation through progressive overload, typically constructed from calibrated steel shafts, urethane-encased cast iron, or elastomeric tension elements rated to specific load tolerances. Its primary commercial purpose centers on enabling quantified, repeatable mechanical stress across fitness, athletic performance, and clinical rehabilitation environments. Smart Equipment with embedded force plates and velocity-based training sensors captures the fastest-growing margin pool as facilities monetize data-driven programming. Steel-framed traditional plate-loaded systems still dominate absolute unit volume across budget-conscious commercial gyms and municipal recreation centers. Home Users represent a structurally expanding end-user segment where space-efficient adjustable dumbbell systems and modular cable stations displace full rack installations.
ISO 20957-1 fixed strength training equipment safety standards and ASTM F2276 test methods govern structural integrity and biomechanical risk exposure across manufacturing and facility liability frameworks. The EU Machinery Directive and CE marking requirements shape European import compliance costs and product design cycles for non-domestic suppliers. China's GB 17498 national fitness equipment standards and NMPA oversight of rehabilitation-classified devices create dual certification pathways for brands serving clinical and consumer channels. Stakeholders must monitor how AI-enabled form correction features trigger medical-device classification debates in multiple jurisdictions.
Market Dynamics
Smart equipment integration is compressing traditional procurement cycles as commercial gym chains redirect capital toward connected strength systems with embedded force plates and velocity-based training sensors, fundamentally altering how facilities monetize member engagement.
Growth Catalysts
- ISO 20957-1 Safety Standards:Harmonized international testing protocols reduce certification friction for multi-market equipment suppliers, accelerating cross-border distribution.
- Home Gym Premiumization:Space-constrained residential buyers in the United States and Germany are driving demand for adjustable dumbbell systems and modular cable stations.
- Digital Coaching Convergence:Embedded biomechanical feedback screens reduce dependency on certified strength coaching labor, enabling 24/7 facility operation.
Market Restraints
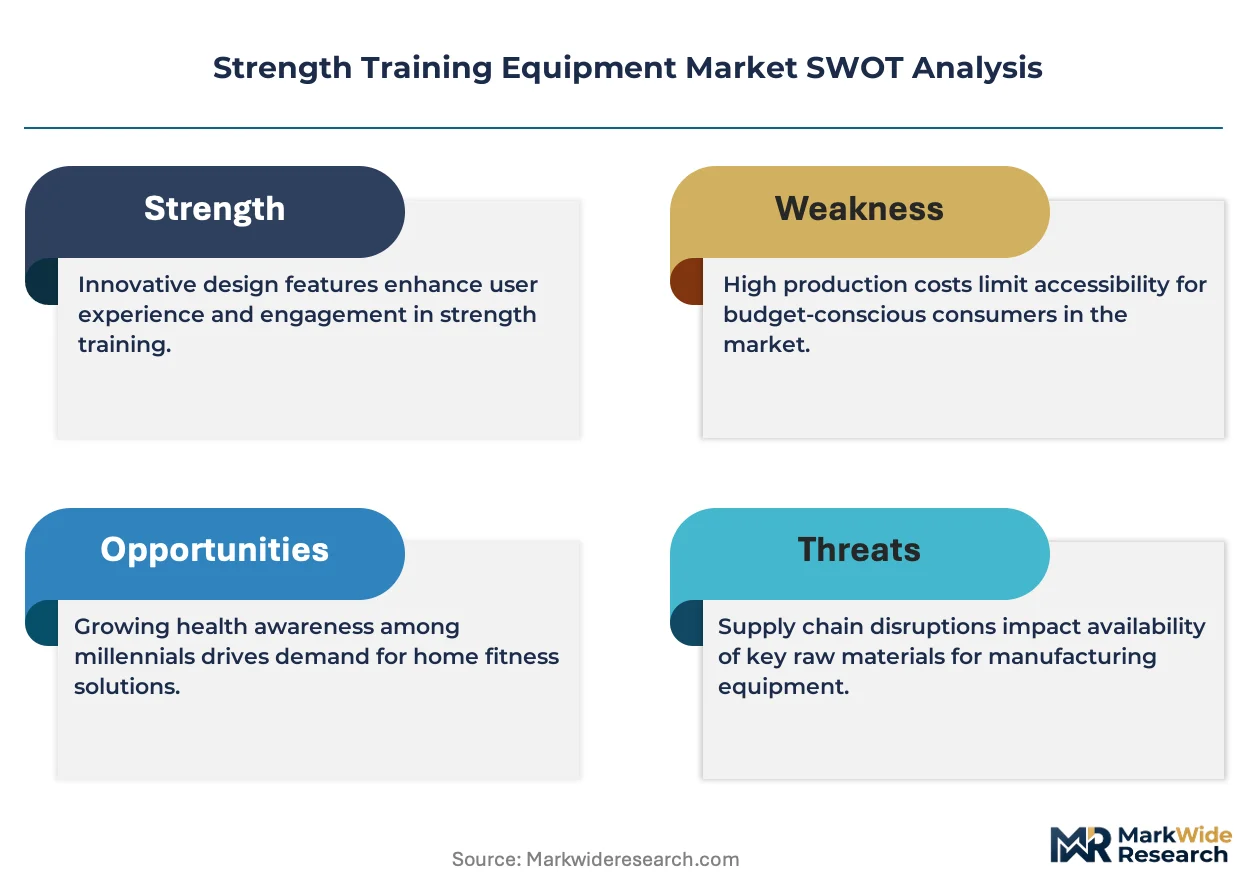
- Steel Input Volatility:Calibrated steel shaft fabrication costs fluctuate with raw material pricing, compressing margin pools for plate-loaded system manufacturers.
- EU Machinery Directive Compliance:CE marking requirements and import certification cycles create dual cost burdens for non-European suppliers serving health club chains.
- AI Medical Device Classification Risk:Form correction algorithms risk triggering NMPA and FDA medical-device oversight, extending product launch timelines.
Strategic Opportunities
- China Clinical Rehabilitation Channel:GB 17498 standards and NMPA oversight create a dual certification pathway for equipment serving hospital-based physiotherapy centers.
- Velocity-Based Training Sensor Integration:Convergence of force plate technology with elastomeric tension elements opens subscription-based programming revenue streams.
- Direct-to-Consumer Modular Systems:E-commerce channels bypass traditional fitness distributor markups for home users seeking rack-free installations.
Industry Challenges
- Certified Coaching Labor Scarcity:Commercial fitness chains face collapsing availability of qualified strength coaches, forcing equipment-dependent service models.
- Legacy Console Integration Friction:Mid-market facilities struggle to retrofit integrated software ecosystems onto existing steel-framed installations without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strength Training Equipment Market |
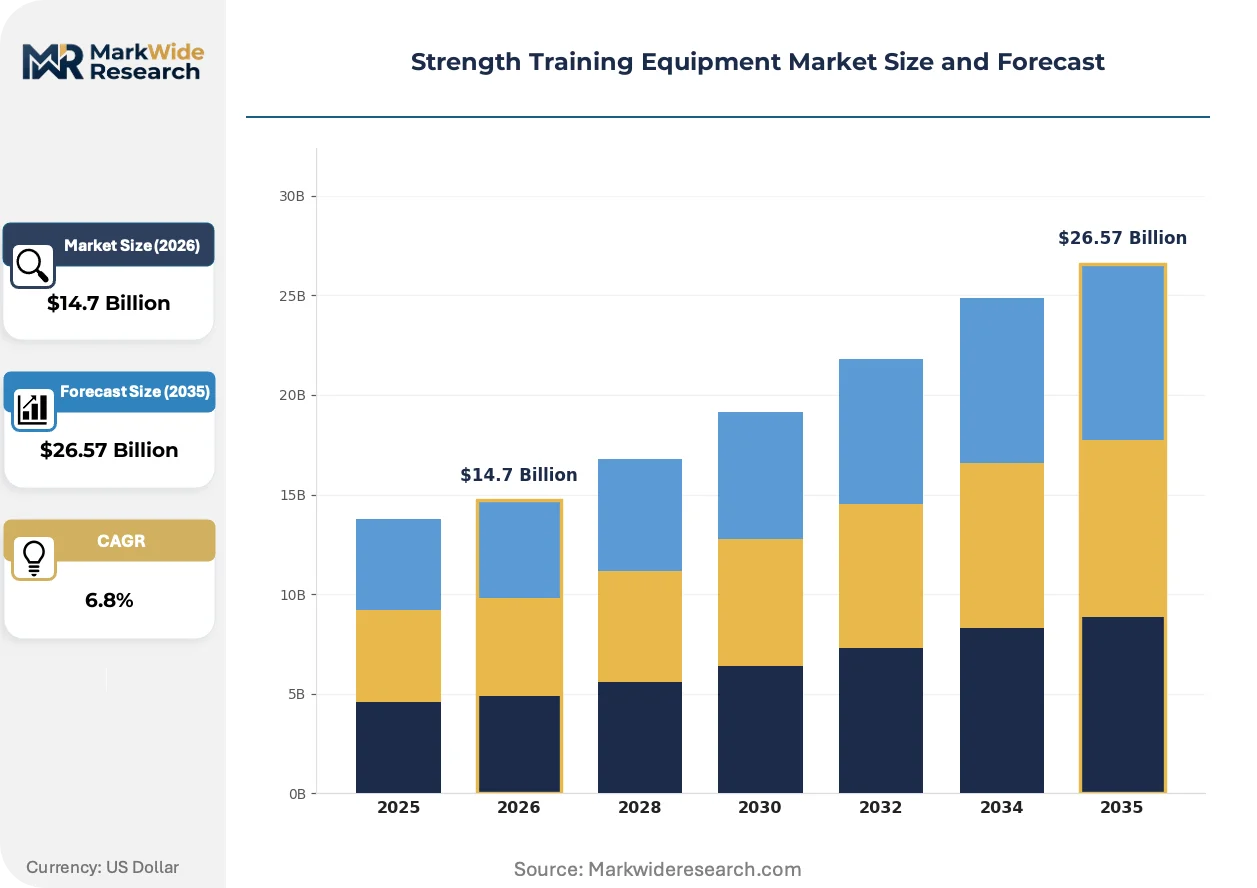
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dumbbells, Resistance Bands, Weight Plates, Barbells End User: Commercial Gyms, Home Users, Rehabilitation Centers, Sports Teams Material: Steel, Rubber, Plastic, Vinyl Technology: Smart Equipment, Adjustable Weights, Magnetic Resistance, Traditional |
| Companies Covered | Core Health & Fitness, Matrix Fitness, Life Fitness, Eleiko Sport AB, DHZ Fitness Equipment, Technogym S.p.A, Precor, gym80 International GmbH, Rogue Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strength Training Equipment Market Emerging Trajectories
Embedded sensor technology and AI-enabled feedback systems are actively displacing traditional instruction-dependent training models, while regulatory frameworks scramble to classify novel capabilities across multiple jurisdictions.
Velocity-based training sensors with integrated force plates are displacing manual load progression protocols in collegiate athletic facilities. Strength coaches at Division I programs now prescribe training blocks using real-time bar velocity data rather than percentage-based periodization. This capability compression is reducing the experiential premium previously commanded by tenured coaching staff.
China's NMPA is scrutinizing AI form correction features for potential medical-device classification under rehabilitation equipment standards. Manufacturers serving clinical channels must now navigate dual certification pathways alongside consumer-grade GB 17498 compliance. European suppliers face parallel uncertainty as the EU AI Act's risk categorization framework remains unresolved for biomechanical analysis software.
Facility procurement committees now unbundle after-sales service contracts from equipment purchases, demanding API-accessible data exports rather than locked console ecosystems. Commercial gym chains in Germany and the United States prioritize interoperable platforms that feed member performance data into third-party coaching applications. This behavioral shift erodes the recurring revenue defense of historically closed-system vendors.
Strength Training Equipment Market Segmentation
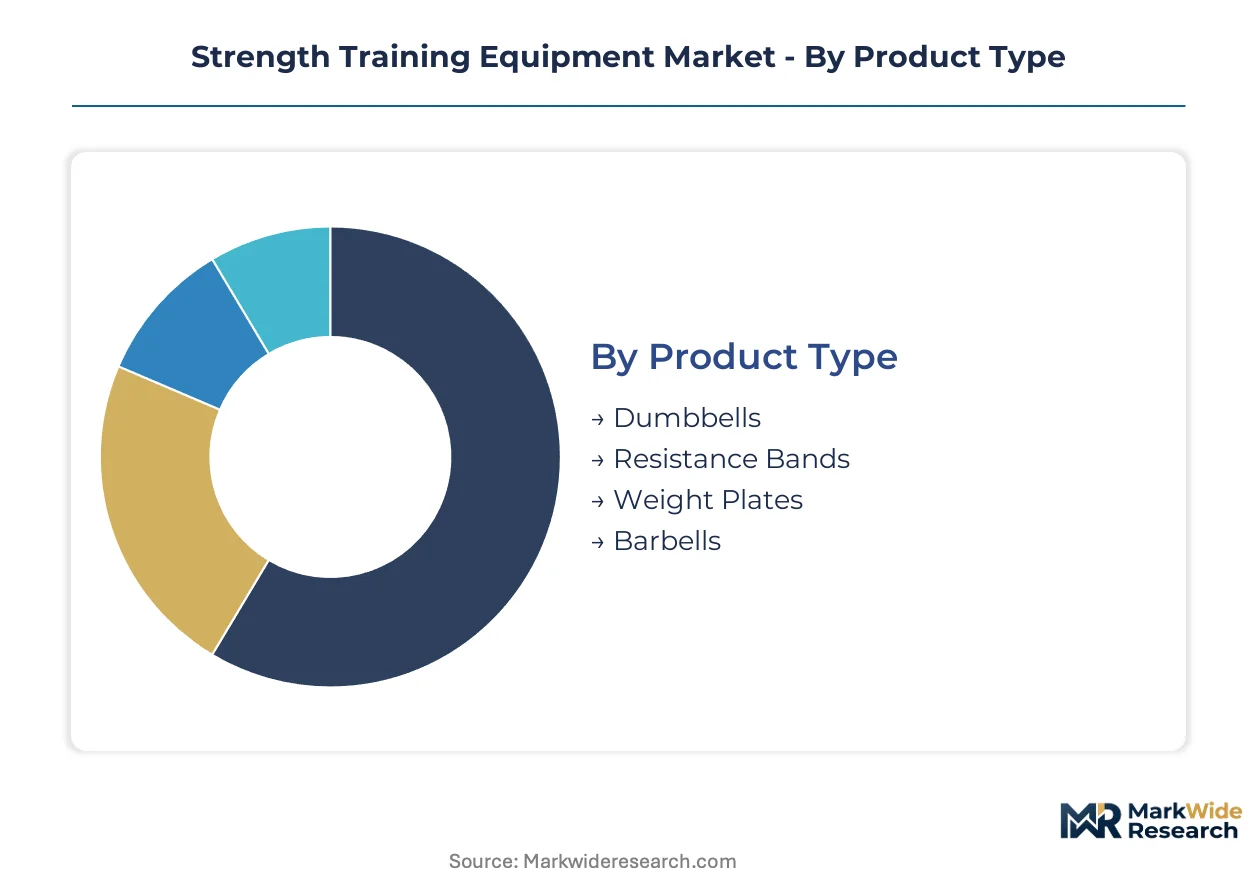
Equipment segmentation in strength training reveals divergent procurement logics across facility types and user environments. Material specifications and embedded technology layers determine margin structure and regulatory exposure more than absolute unit volume.
Product Type:
Domestic fabrication dominates steel-intensive categories, while elastomeric and composite products flow through export-led supply chains from East Asian manufacturing clusters.
- Barbells:Calibrated steel shafts with knurled grip surfaces and rotating sleeve bearings constitute the technical core of competitive weightlifting. Olympic barbell demand concentrates in United States collegiate athletic facilities and CrossFit affiliates where made-in-USA sourcing carries procurement weight. Load tolerance certification to IWF specifications separates premium competition bars from commercial-grade alternatives.
- Dumbbells:Urethane-encased cast iron heads mounted on hardened chrome handles offer the most space-efficient progressive overload solution for commercial floor plans. German health clubs and United States municipal recreation centers drive specification toward hexagonal anti-roll geometries and rack-compatible profiles that maximize storage density.
- Weight Plates:Calibrated bumper plates with Shore A durometer ratings above 90 absorb repeated drops in Olympic lifting environments.
- Resistance Bands:Layered latex or fabric-covered elastomeric loops provide variable tension curves for rehabilitation and travel applications.
Barbells command the established base in commercial procurement budgets. The steepest expansion runs through resistance bands as home users seek rack-free installation options.
End User:
Facility-based buyers prioritize durability certifications and service contracts, while residential purchasers trade structural longevity for space efficiency and aesthetic integration.
- Commercial Gyms:Multi-location chains in the United States and Germany refresh equipment on compressed cycles as member retention hinges on perceived novelty. ISO 20957-1 structural testing and ASTM F2276 biomechanical safety documentation are non-negotiable in procurement specifications. Capital allocation is shifting toward connected strength systems that reduce certified coaching labor dependency.
- Home Users:Space-constrained residential buyers in United States metropolitan markets and German urban centers favor adjustable dumbbell systems and modular cable stations over full rack installations. E-commerce direct-to-consumer channels bypass traditional fitness distributor markups, compressing price points while expanding addressable volume.
- Rehabilitation Centers:Hospital-based physiotherapy departments in China require dual GB 17498 and NMPA certification pathways for equipment serving clinical populations.
- Sports Teams:Collegiate and professional athletic programs demand velocity-based training sensor integration for load prescription automation.
Commercial gyms absorb the majority of steel-framed plate-loaded system volume. Home users are climbing the fastest as residential fitness normalization persists.
Material:
Raw material selection determines manufacturing geography, with steel fabrication concentrated in domestic foundries and polymer processing distributed across Asian contract manufacturers.
- Steel:Calibrated alloy shafts and cast iron load elements remain the structural foundation of plate-loaded resistance systems. Input cost volatility from scrap metal and iron ore pricing directly compresses margin pools for barbell and weight plate manufacturers serving budget-conscious commercial segments.
- Rubber:Urethane and virgin rubber encasement protects facility flooring and reduces acoustic transmission in multi-use spaces. Premium health clubs in Germany specify low-odor, phthalate-free formulations that meet REACH compliance thresholds for indoor air quality.
- Plastic:Glass-filled nylon and ABS components enable cost-competitive selectorized weight stack mechanisms for entry-level home gym systems.
- Vinyl:Dip-coated finishes on cast iron dumbbells provide corrosion resistance at price points accessible to municipal recreation centers.
Steel retains absolute volume leadership across commercial procurement. Rubber-encased alternatives are gaining share fastest in premium facility segments.
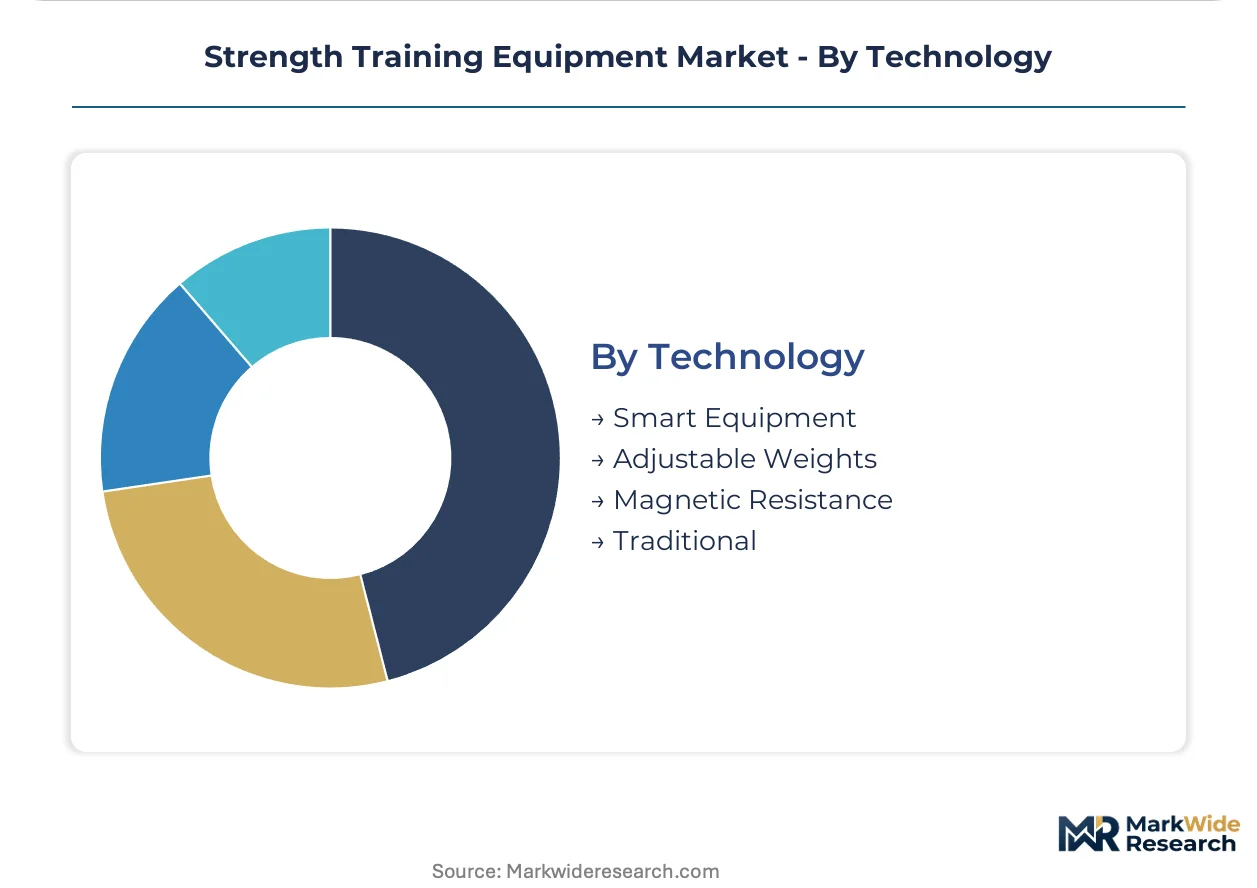
Technology:
Embedded sensor architecture is bifurcating the market between data-monetizable connected systems and price-optimized mechanical alternatives.
- Smart Equipment:Force plate integration, velocity-based training sensors, and AI-enabled form correction algorithms transform resistance apparatus into data capture platforms. United States collegiate athletic facilities and premium German health clubs prioritize API-accessible data exports over locked console ecosystems. Regulatory uncertainty from FDA and NMPA medical-device classification debates extends product launch timelines.
- Traditional:Mechanically loaded plate and pin systems without electronic components dominate municipal recreation centers and budget commercial chains where capital constraints override connectivity requirements. Simplified maintenance profiles and absence of firmware obsolescence risk sustain procurement preference in cost-sensitive segments.
- Adjustable Weights:Dial-select and pin-mechanism systems compress multiple load increments into single footprint solutions for space-constrained home users.
- Magnetic Resistance:Eddy current braking systems enable silent, friction-free load modulation in connected cable machines and rower hybrids.
Traditional systems anchor installed base across price-sensitive facility tiers. Smart equipment is expanding most quickly as procurement committees prioritize member engagement monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German health clubs and United States collegiate athletic facilities, while Chinese manufacturers compete on steel fabrication costs and dual certification agility. This asymmetry shapes procurement patterns across facility tiers.
United States
Collegiate athletic programs and CrossFit affiliates drive demand for IWF-certified competition barbells and velocity-based training sensor integration. NCAA Division I strength coaches now prescribe training blocks using real-time bar velocity data. Pittsburgh-based Rogue Fitness anchors domestic fabrication of made-in-USA barbell and rig systems for this channel.
Germany
Premium health clubs in Berlin and Munich prioritize REACH-compliant urethane formulations and API-accessible data exports over locked console ecosystems. The EU Machinery Directive and CE marking requirements shape import compliance costs for non-European suppliers. Baden-Württemberg manufacturing clusters produce precision steel components for selectorized weight stack mechanisms.
China
Hospital-based physiotherapy centers in Shanghai and Beijing require dual GB 17498 and NMPA certification pathways for rehabilitation-classified equipment. The NMPA scrutinizes AI form correction features for potential medical-device classification. Ningbo and Qingdao manufacturing hubs dominate elastomeric resistance band and adjustable dumbbell exports to North American and European home gym segments.
Japan
Commercial fitness chains in Tokyo and Osaka refresh equipment on compressed cycles amid post-pandemic fitness normalization. METI oversight and JIS standards govern structural integrity testing for imported plate-loaded systems. Osaka-based distributors increasingly source connected strength systems with embedded force plates from European suppliers.
United Kingdom
Boutique studio operators in London and Manchester prioritize space-efficient cable stations and modular rig systems for high-rent urban locations. The UKCA marking transition from CE compliance creates certification friction for continental European suppliers. Midlands manufacturing clusters produce steel framing components for budget commercial gym chains.
Strength Training Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with smart equipment specialists commanding premium positioning while steel fabricators compete on input cost management. The vendor base spans three tiers: embedded sensor platform developers, traditional mechanical system manufacturers, and direct-to-consumer modular specialists. Consolidation pressure runs highest in the mid-market commercial segment where software subscription attach rates determine profitability. Capacity expansion and strategic partnerships represent the dominant competitive moves as facilities unbundle after-sales service contracts from equipment purchases.
Within the premium smart equipment tier, Technogym S.p.A and Matrix Fitness occupy positions defined by integrated console ecosystems and biomechanical feedback capabilities. Rogue Fitness exemplifies the domestic fabrication archetype, anchoring made-in-USA sourcing preferences in North American collegiate and CrossFit channels. Eleiko Sport AB represents the precision competition equipment specialist, with Swedish-origin signaling IWF certification authority for Olympic lifting apparatus.
| Leading Market Players |
|---|
| Core Health & Fitness |
| Matrix Fitness |
| Life Fitness |
| Eleiko Sport AB |
| DHZ Fitness Equipment |
| Technogym S.p.A |
| Precor |
| gym80 International GmbH |
| Rogue Fitness |
| Others |
Supply Flow & Price Mechanics
Ninety-day steel shaft lead times from domestic foundries compress procurement flexibility for plate-loaded system manufacturers, concentrating pricing power with vertically integrated fabricators while forcing distributors to absorb inventory carrying costs. This temporal rigidity reinforces three-tier pricing stratification across premium IWF-certified competition bars, mid-market commercial-grade alternatives, and economy selectorized systems for municipal recreation centers.
Pricing Analysis
German health clubs pay 40-60% premiums over United States municipal buyers for REACH-compliant urethane formulations and API-accessible console ecosystems. Pricing stratifies across premium smart equipment with embedded force plates, standard steel-framed plate-loaded systems, and economy vinyl-dip dumbbells for budget chains. Cost compression in the economy tier intensifies because Chinese elastomeric exports bypass traditional distributor markups through direct-to-consumer channels. Municipal recreation centers exhibit highest price sensitivity; Division I collegiate athletic programs demonstrate lowest sensitivity due to performance-data requirements.
Supply Chain Analysis
Just-in-time steel procurement dominates North American barbell fabrication, while Asian contract manufacturers maintain strategic stockpiles of layered latex for resistance band production. Supply concentrates in United States domestic foundries for calibrated alloy shafts, China's Ningbo and Qingdao hubs for elastomeric components, and Germany's Baden-Württemberg cluster for precision selectorized mechanisms. Raw material dependencies include scrap metal and iron ore for cast iron load elements, virgin rubber for urethane encasement, and glass-filled nylon for selectorized weight stacks. Single-source vulnerability runs through IWF-certification testing laboratories for competition-grade equipment. Distribution runs through fitness equipment distributors for commercial gym chains, with e-commerce platforms capturing growing home-user volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected strength systems face substitution pressure from AI-enabled fitness applications that deliver comparable biomechanical feedback without capital equipment acquisition, forcing incumbents to defend installed-base relationships through data portability guarantees.
For Market Incumbents: Compound API-accessibility investments to preempt member churn toward interoperable third-party coaching platforms. Prioritize backward integration into force plate sensor manufacturing to protect margin pools from component supplier pricing power. Defend against direct-to-consumer modular specialists by embedding subscription-based programming revenue into commercial service contracts. For New Entrants and Emerging Players: Anchor in China's hospital-based physiotherapy channel where dual GB 17498 and NMPA certification requirements create incumbent friction for established consumer-grade suppliers. Target velocity-based training sensor integration for Division I athletic programs seeking load prescription automation. Pursue white-label manufacturing partnerships with Ningbo-based elastomeric producers to bypass capital-intensive steel fabrication. For Investors and Strategic Acquirers: Long-term, this sits as a data-monetization play because member performance analytics are displacing equipment hardware as the primary value capture mechanism. Acquisition targets should display software subscription attach rates above industry medians and API-forward console architectures. Watch for NMPA medical-device classification rulings on AI form correction as the signal for regulatory-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| API-Forward Console Development | Enables data export to third-party coaching applications, reducing member churn risk. |
| Backward Integration into Sensor Manufacturing | Captures margin pools from force plate and velocity sensor component suppliers. |
| Dual Certification Pathway Investment | Opens China's NMPA-regulated clinical rehabilitation channel alongside consumer markets. |
| Direct-to-Consumer Modular Launch | Bypasses fitness distributor markups in United States and German home-gym segments. |
| Subscription-Based Programming Rollout | Transforms one-time equipment sales into recurring revenue streams for commercial accounts. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with commercial gym procurement directors, collegiate strength coaches, hospital physiotherapy managers, and fitness equipment distributors; and secondary validation through ISO 20957-1 certification databases, ASTM F2276 test method documentation, NMPA registration filings, and customs trade records for steel and elastomeric imports. Bottom-up equipment shipment estimates triangulated against top-down facility investment surveys across the United States, Germany, and China.
Across the analysis window, the forecasting framework modeled demand across product type, end-user segment, material composition, and embedded technology tier. CAGRs derived from facility expansion pipelines, equipment refresh cycle compression rates, and residential fitness normalization trends. Industry-specific inputs included NCAA athletic program capital expenditure patterns and NMPA medical-device classification trajectory assumptions.
Decision-makers should treat outputs as directional under stable steel input pricing and unaltered AI regulatory classification; material deviation would warrant model refresh. Forecasts reflect assumptions regarding post-pandemic fitness normalization persistence and certified coaching labor scarcity continuation. Practitioners should keep alternative scenarios live as EU AI Act risk categorization and NMPA rehabilitation-equipment oversight evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Cardio Fitness Trampolines Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Elliptical Market