
 Motion Simulation Market | 2026-2036
Motion Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Simulation Market Outlook
Direct-to-enterprise sales channels is reconfiguring how motion simulation systems reach end users, bypassing traditional systems integrators for shorter procurement cycles. Moog Inc. leverages its heritage in precision servo control to dominate high-fidelity defense and aerospace platforms. CAE Inc. sustains broad geographic coverage through training center networks spanning multiple continents. Bosch Rexroth AG anchors its position via captive supply of linear motion components that underpin third-party simulator builds.
Motion simulation encompasses electromechanical, hydraulic, and pneumatic actuation systems that reproduce physical accelerations, vibrations, and positional changes with specified degrees of freedom, typically six-axis configurations for full-body immersion. These systems replicate real-world kinematic conditions for operator training, product validation, and human factors research without exposing personnel or prototypes to actual hazards. Hardware segments command the deepest margin pools due to actuator precision requirements and long replacement cycles, while software layers are expanding fastest as physics engines and scenario authoring tools decouple from proprietary platforms. Aerospace and military applications retain the largest revenue footprint, though automotive adoption is accelerating as virtual validation replaces physical prototype mileage targets.
The FAA mandates Level D full-flight simulator standards for pilot type certification, forcing manufacturers to meet exacting motion cueing fidelity thresholds. EASA's CS-FSTD rules and the EU AI Act's emerging requirements for autonomous system training data are tightening compliance scopes across European deployments. China's GB standards for aviation training equipment and NMPA oversight of medical simulation devices add further certification complexity for multinational suppliers. Stakeholders must monitor how regulatory divergence between FAA and EASA motion fidelity criteria affects platform development costs and geographic product variant strategies.
Market Dynamics
The European Union's F-Gas Regulation is forcing a wholesale migration from hydraulic to electromechanical motion platforms, compressing replacement cycles and rewiring supplier relationships across aerospace and automotive validation centers.
Growth Catalysts
- Defense procurement expansion:NATO member states are enlarging training budgets for flight and vehicle simulators, creating sustained demand for high-fidelity motion platforms in military aviation centers.
- Automotive virtual validation:Germany's OEM engineering corridors around Stuttgart and Munich are replacing physical prototype mileage with simulation-based homologation, accelerating platform deployment.
- EU regulatory hardware mandates:The F-Gas Regulation is compelling simulator operators to retire legacy hydraulic systems ahead of schedule, generating replacement demand for electric motion bases.
Market Restraints
- Precision actuator supply concentration:High-torque servo motor and linear drive production clusters heavily in German and Japanese industrial zones, creating geographic dependency risk for platform builders.
- Certification cost escalation:FAA Level D and EASA CS-FSTD motion fidelity standards require extensive validation testing, inflating development budgets and extending payback periods.
- Skilled integration labor scarcity:Mechatronics engineers capable of tuning six-axis cueing algorithms command premium compensation, constraining deployment velocity for simulator integrators.
Strategic Opportunities
- Medical simulation expansion:China's NMPA oversight of surgical training devices is formalizing quality standards, opening compliant motion platform suppliers to hospital procurement channels.
- Autonomous vehicle validation:Human-in-the-loop testing for self-driving systems requires motion platforms that replicate emergency maneuvers, creating new demand from automotive safety labs.
- Direct-to-enterprise channels:OEMs and defense agencies are bypassing systems integrators for shorter procurement cycles, rewarding manufacturers with captive sales and service capabilities.
Industry Challenges
- Cross-certification fragmentation:Divergent FAA and EASA motion cueing fidelity criteria force platform developers to maintain separate product variants, duplicating engineering and test overhead.
- Legacy system integration complexity:Electromechanical retrofits must interface with existing visual and computational subsystems, requiring custom mechanical adapters and control law recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Simulation Market |
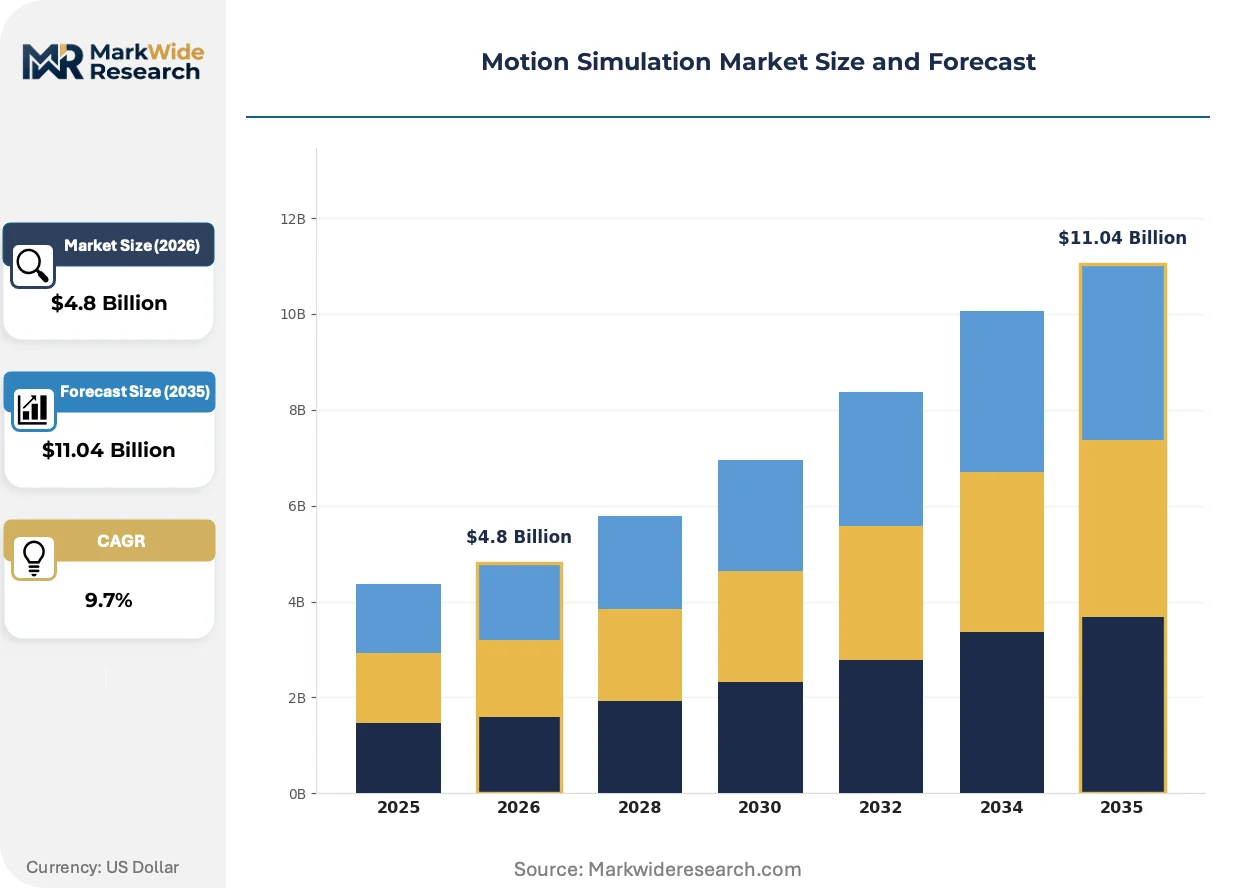
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Accessories Application: Aerospace, Automotive, Entertainment, Military Technology: Virtual Reality, Augmented Reality, 3D Simulation, Haptic Feedback End User: Academia, Enterprises, Government, Training Centers |
| Companies Covered | Moog Inc., CAE Inc., D-BOX Technologies Inc., Honeywell International Inc., Bosch Rexroth AG, VI-grade GmbH, Thales Group, L3Harris Technologies, Inc., FAAC Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Simulation Market Strategic Shifts
Electromechanical actuation architectures are supplanting hydraulic systems across high-fidelity applications, while regulatory mandates and procurement model evolution are compressing supplier margins and rewiring channel economics.
High-bandwidth electric linear actuators with integrated force feedback sensing are rendering obsolete legacy hydraulic motion bases in full-flight simulators. CAE and L3Harris training centers are completing platform swaps at accelerated pace. The technology shift is compressing maintenance revenue streams for hydraulic component suppliers while expanding long-term service contracts for electromechanical system providers.
China's GB standards for aviation training equipment are tightening electromagnetic compatibility and safety interlock requirements for imported simulators. Domestic certification complexity is lengthening approval timelines for multinational suppliers. European and North American manufacturers are responding by establishing localized integration partnerships and pre-certified subsystem architectures.
Outcome-based contracting is displacing capital purchase models in commercial aviation training centers. Airlines now prefer per-training-hour fees that bundle motion platform uptime guarantees with scenario content updates. The restructuring is most visible in Asia-Pacific markets where fleet expansion outpaces owned simulator infrastructure.
Motion Simulation Market Segmentation
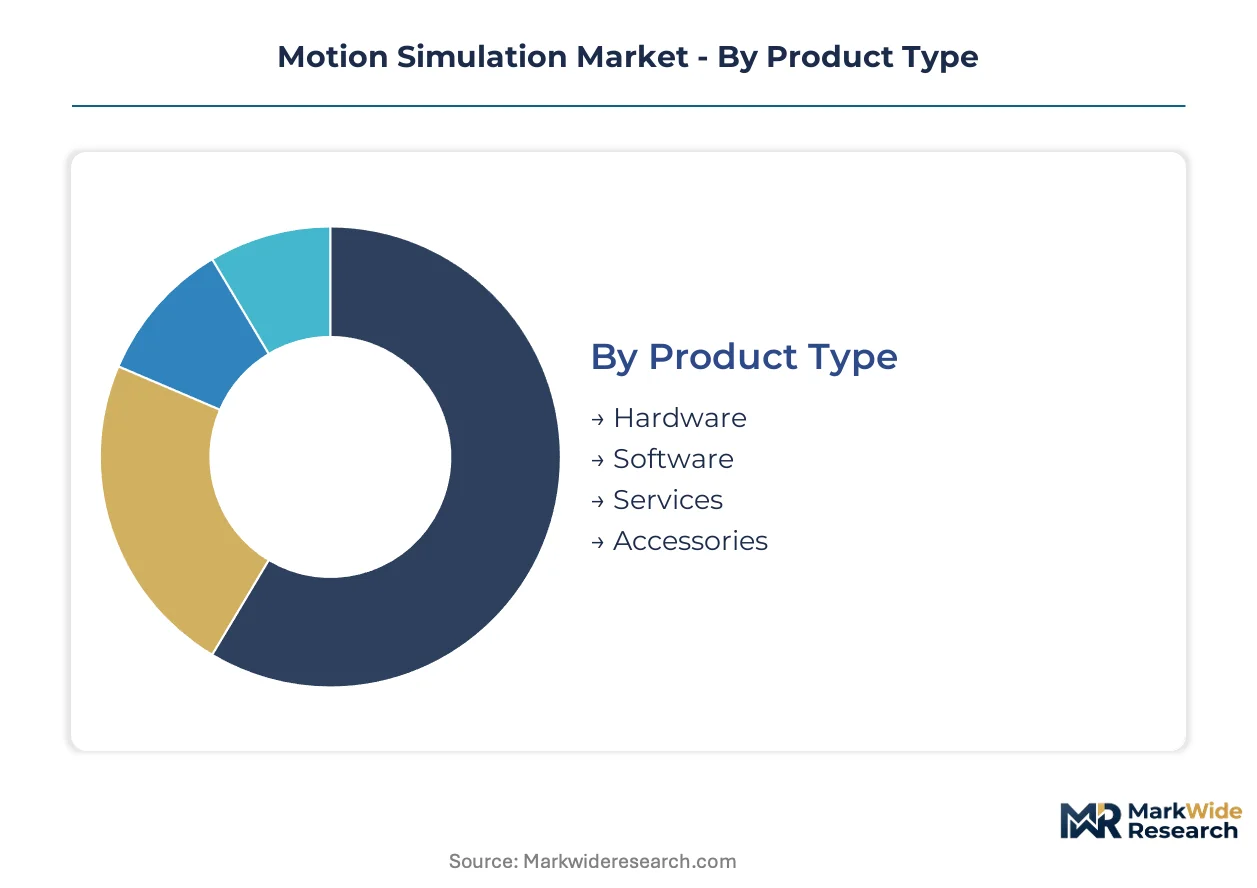
Segmentation in motion simulation reveals how distinct technical requirements and procurement patterns fragment the addressable market. Product architecture, application intensity, and end-user sophistication each create separate margin pools and competitive battlegrounds for platform suppliers.
Product Type:
Use-case spectrum spans from capital-intensive motion bases requiring precision engineering to recurring-revenue software layers that decouple from proprietary hardware.
- Hardware:Electromechanical actuators, hydraulic motion bases, and control cabinets constitute the physical reproduction layer. Stuttgart's automotive validation corridors and NATO flight training centers concentrate demand for six-axis platforms with sub-millimeter positional accuracy.
- Software:Physics engines, scenario authoring tools, and cueing algorithms enable motion command generation. The segment is expanding most quickly as open-architecture standards allow third-party content to run across multiple hardware vendors.
- Services:Installation, certification support, and maintenance contracts sustain platform lifecycle economics. FAA Level D and EASA CS-FSTD compliance validation creates sticky recurring relationships with simulator operators.
- Accessories:Cockpit shells, instrument panels, and environmental control modules complete immersive environments. Demand tracks retrofits of existing training devices rather than greenfield installations.
The dominant share belongs to Hardware, while Software is closing the gap fastest.
Application:
Application intensity correlates directly with safety-critical validation requirements and regulatory certification burden.
- Aerospace:Full-flight simulators replicate aircraft handling qualities for pilot type certification. FAA mandates Level D motion fidelity for zero-flight-time training approvals, forcing manufacturers to meet exacting acceleration bandwidth specifications.
- Military:Combat vehicle and rotary-wing trainers prioritize survivability rehearsal under hostile conditions. NATO procurement agencies in Germany, the United Kingdom, and the United States are enlarging dedicated simulation budgets for collective training exercises.
- Automotive:Virtual homologation replaces physical prototype mileage for durability and safety validation. Munich-based OEM engineering facilities are deploying motion platforms for human-in-the-loop testing of autonomous emergency maneuvers.
- Entertainment:Theme park attractions and location-based experiences emphasize throughput and reliability over precision. Lower certification barriers attract price-sensitive buyers with reduced technical specifications.
Aerospace commands the deepest revenue concentration, though Automotive demonstrates the steepest expansion trajectory as virtual validation displaces physical testing protocols.
Technology:
Technology maturity determines integration complexity and the pace at which legacy visual systems require replacement.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking reduce physical cockpit footprint requirements. Training centers in Japan and South Korea are adopting VR-native architectures for ab initio pilot instruction.
- 3D Simulation:Projected visual environments on dome screens remain the standard for high-end flight training. The technology anchors the largest installed base across CAE and L3Harris operational networks.
- Augmented Reality:Overlay graphics on physical cockpits support maintenance and procedural training. Adoption concentrates in military maintenance schools requiring hybrid physical-digital instruction.
- Haptic Feedback:Force-reflecting control loaders replicate aerodynamic loading on yokes and pedals. Integration with electromechanical motion bases is displacing standalone hydraulic force-feel systems.
3D Simulation retains the dominant installed position, while Virtual Reality is gaining share fastest among new training center constructions.
End User:
End-user procurement sophistication ranges from centralized defense acquisition with multi-year funding to fragmented academic purchasing with constrained capital cycles.
- Government:Defense procurement agencies operate structured acquisition programs with explicit motion fidelity requirements. The F-Gas Regulation is accelerating hardware refresh timelines for European military flight schools.
- Training Centers:Commercial aviation training providers balance utilization rates against per-hour contracting economics. Asia-Pacific fleet expansion is outpacing owned infrastructure, favoring outcome-based fee structures.
- Enterprises:Automotive OEMs and Tier-1 suppliers deploy platforms for R&D validation and dealer training. Direct-to-enterprise channels are compressing procurement cycles by bypassing traditional systems integrators.
- Academia:Universities and research institutes prioritize cost accessibility over peak performance. Grant-funded purchases concentrate in human factors and biomechanics research programs.
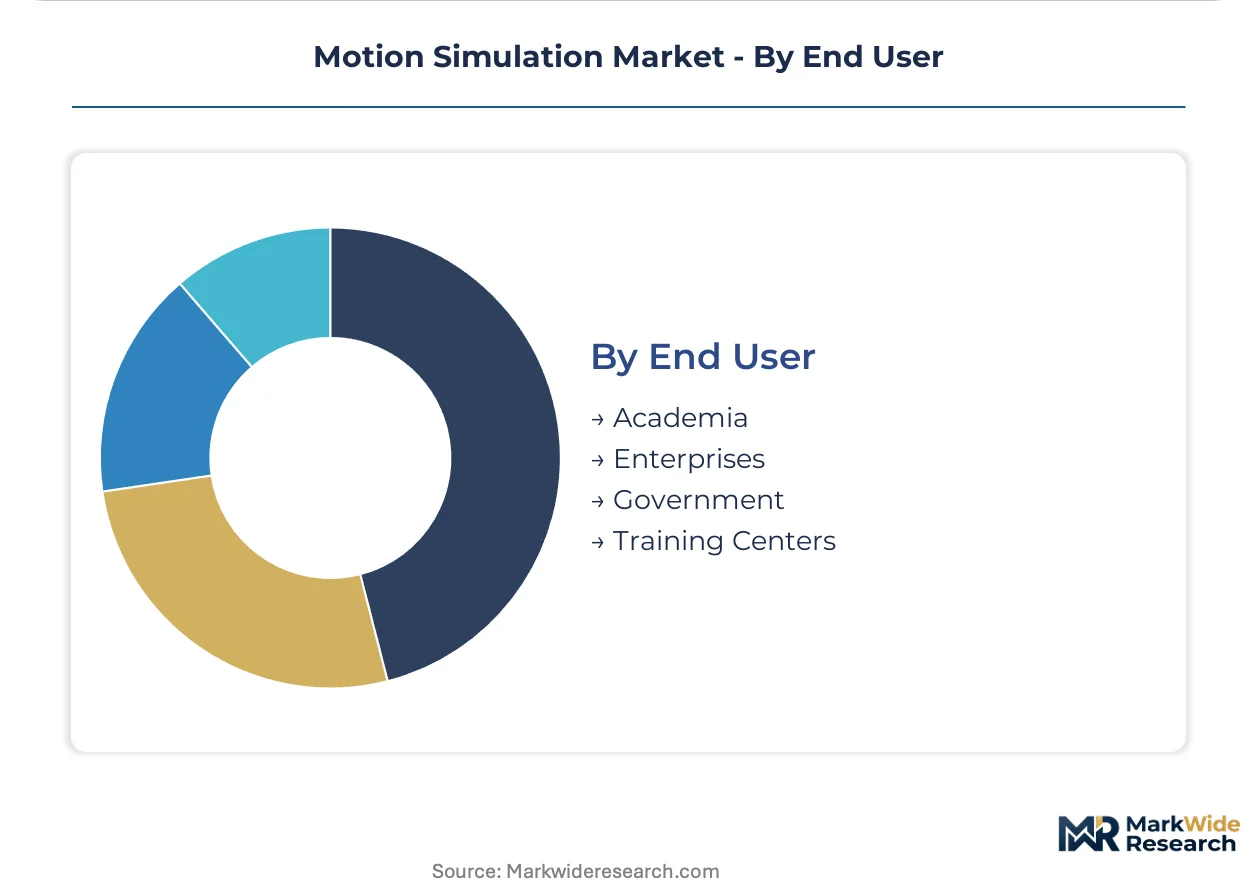
Government accounts for the dominant procurement volume, though Enterprises are expanding their platform footprint most aggressively as automotive virtual validation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motion platform manufacturers command pricing premiums against North American suppliers due to precision actuator clustering around Stuttgart. Asian buyers absorb cost differentials to access EU-certified electromechanical systems. Procurement patterns diverge sharply between defense-heavy NATO markets and automotive-driven validation corridors.
United States
The Pentagon's training modernization programs sustain demand for high-fidelity flight simulators at military aviation centers. FAA Level D certification mandates force domestic operators toward exacting motion cueing standards. Orlando's simulation corridor concentrates training device manufacturing and integration expertise.
Germany
Baden-Württemberg's automotive OEM engineering facilities drive virtual homologation platform deployment. The F-Gas Regulation accelerates hydraulic-to-electric retrofits at Stuttgart-area validation centers. Munich-based Tier-1 suppliers operate extensive human-in-the-loop testing infrastructure.
China
NMPA oversight of surgical training devices formalizes quality standards for medical motion platforms. GB standards for aviation training equipment tighten electromagnetic compatibility requirements for imported simulators. Shanghai's aerospace district hosts localized integration partnerships for multinational suppliers.
United Kingdom
Royal Air Force procurement expansion targets collective training exercises with networked motion platforms. EASA CS-FSTD rules align UK certification with continental motion fidelity criteria. BAE Systems' Lancashire facilities anchor domestic simulator integration capacity.
Japan
METI-supported autonomous vehicle testing programs generate demand for emergency maneuver replication platforms. JIS standards govern industrial motion system safety interlocks for manufacturing applications. Nagoya's automotive engineering belt deploys simulation-based durability validation.
Motion Simulation Market Competitive Environment
Precision-control specialists and full-system integrators split the market between component supply and turnkey platform delivery. The vendor base organizes around three strategic archetypes: captive actuator manufacturers, training center operators with in-house platform development, and pure-play motion base engineering houses. Consolidation pressures concentrate among mid-tier integrators lacking proprietary servo technology. Dominant competitive moves include backward integration into linear drive production and geographic expansion through localized certification partnerships.
Among precision-control specialists, Moog Inc. and Bosch Rexroth AG exemplify the captive-component archetype, anchoring positions through in-house production of servo valves and linear motion systems. CAE Inc. occupies a distinct tier as a training center operator with integrated platform development capabilities, representing the vertical-scope model that bundles motion hardware with scenario content and certification services. These three entities illustrate how competitive positioning stratifies between component-level engineering depth and end-to-end training ecosystem control.
| Leading Market Players |
|---|
| Moog Inc. |
| CAE Inc. |
| D-BOX Technologies Inc. |
| Honeywell International Inc. |
| Bosch Rexroth AG |
| VI-grade GmbH |
| Thales Group |
| L3Harris Technologies, Inc. |
| FAAC Incorporated |
| Others |
Value Chain & Pricing Dynamics
Rhine-Alpine corridor freight rates from Stuttgart to Rotterdam shape cost absorption patterns for German precision actuator suppliers, compressing margins for mid-tier platform builders while amplifying price differentiation between certified and uncertified motion systems.
Pricing Analysis
The customization-premium spread spans three-to-five-fold between standard electromechanical motion bases and FAA Level D-configured platforms with integrated cueing algorithms. Pricing stratifies across certification tiers, with EASA CS-FSTD compliance adding substantial engineering validation costs. Cost compression in the mid-market segment is intensifying because automotive OEMs are consolidating vendor panels for virtual validation contracts. Training centers exhibit the highest price sensitivity due to outcome-based contracting pressures, while defense procurement agencies absorb premiums for mission-critical fidelity specifications.
Supply Chain Analysis
Upstream feedstock for high-torque servo motors and precision ball screws draws heavily from German, Japanese, and South Korean industrial zones. Rare-earth magnet supply for permanent-motor assemblies rests on Chinese processing capacity. Single-source vulnerability concentrates in linear encoder production, where Heidenhain and Renishaw dominate sub-micron measurement tiers. Distribution runs through captive direct-sales teams for defense and aerospace accounts, with systems integrators retaining residual channel share in academic and entertainment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motion simulation sits in early-cycle expansion as automotive virtual validation displaces physical prototype programs and EU F-Gas Regulation forces hardware refresh timelines.
For Market Incumbents: Harden supply chain control over precision actuator sourcing through backward integration into linear drive production or exclusive partnerships with Stuttgart-area component specialists. Defend against emerging pure-play electromechanical engineering houses by embedding scenario authoring tools into proprietary hardware architectures, creating switching costs that resist unbundling. For New Entrants and Emerging Players: Build out white-space positions in medical simulation platforms compliant with China's NMPA surgical training standards, where incumbent presence remains thin. Target academic research institutes with grant-funded human factors programs as the most penetrable end-user segment, offering modular three-degree-of-freedom systems at accessible price points with open-architecture software compatibility. For Investors and Strategic Acquirers: Component-captive mid-tier integrators with established EASA certification track records represent the most attractive acquisition archetype for platform consolidation plays. Monitor FAA-EASA motion cueing fidelity criteria convergence as the critical inflection signal; regulatory harmonization would eliminate variant duplication costs and expand addressable margins for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Drive Production | Captive supply of precision actuators insulates margin pools from Stuttgart supplier concentration. |
| EASA CS-FSTD Pre-Certification Investment | Pre-validated subsystem architectures compress approval timelines for China GB standard compliance. |
| Direct-to-Enterprise Channel Buildout | Bypassing systems integrators captures procurement cycle compression in automotive OEM validation programs. |
| Outcome-Based Service Contract Expansion | Per-training-hour bundling aligns revenue with Asia-Pacific airline fleet expansion patterns. |
| Medical Simulation Regulatory Compliance | NMPA-aligned quality standards open hospital procurement channels previously blocked to industrial suppliers. |
Study Parameters
A spread of perspectives from flight training center operators, defense procurement officers, automotive platform validation engineers, and electromechanical systems integrators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA certification databases, EASA CS-FSTD technical standards, EU F-Gas Regulation implementation reports, and customs trade data for precision actuator flows. Bottom-up demand modeling from individual simulator installations triangulated against top-down market sizing from training center network expansions.
Demand-supply-balance framing anchored the forecast framework, with installation rates across aerospace, military, automotive, and medical applications balanced against production capacity constraints in German and Japanese actuator manufacturing hubs. Segmentation dimensions modeled include product architecture, application intensity, technology maturity, and end-user procurement sophistication. CAGRs were derived from fitted growth curves against historical replacement cycle data and regulatory mandate acceleration effects. Industry-specific inputs incorporated F-Gas Regulation compliance deadlines and FAA Level D certification queue lengths.
Stress conditions across raw material cost volatility, cross-certification timeline extensions, and defense budget reallocation scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against CAE and L3Harris disclosed training center deployment schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
Process Analyzer Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Global Weather Forecasting Systems Market