
 Europe Computational Fluid Dynamics Market | 2026-2036
Europe Computational Fluid Dynamics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Computational Fluid Dynamics Market Intelligence
Multi-source licensing is realigning how European engineering teams procure simulation tools. Siemens leverages its hardware-software integration to dominate industrial automation CFD workflows. Ansys Inc. sustains deep partnerships with aerospace primes across France and Germany. Dassault Systemes anchors its position through tight coupling with CATIA CAD installations in automotive OEMs.
Computational Fluid Dynamics encompasses numerical methods and algorithms that solve the Navier-Stokes equations to analyze fluid flow, heat transfer, and related phenomena, typically requiring mesh resolutions from thousands to billions of cells depending on turbulence modeling fidelity. Its primary industrial purpose centers on reducing physical prototyping costs and accelerating design iteration cycles in product development. Software solutions occupy the largest revenue pool given perpetual license models and maintenance streams, while cloud-based solutions represent the fastest-expanding deployment mode as HPC elasticity appeals to mid-sized consultancies. Aerospace end users command premium pricing due to certification-grade accuracy requirements, whereas energy sector adoption is maturing around standardized turbine and heat exchanger simulation templates.
REACH and the EU Green Deal shape material compliance and emissions benchmarking requirements that CFD must validate across product lifecycles. CE marking under the EU Machinery Directive mandates thermal and aerodynamic safety documentation that simulation outputs increasingly satisfy. EASA airworthiness standards for European aerospace OEMs require traceable computational validation protocols. Stakeholders must decide whether to build captive HPC infrastructure or accept cloud dependency as solver workloads scale with electrification and hydrogen system complexity.
Market Dynamics
EU Green Deal mandates and F-Gas Regulation compliance deadlines are forcing automotive and aerospace OEMs to replace physical thermal testing with high-fidelity simulation, compressing solver licensing cycles and concentrating procurement among vendors with integrated hardware-software stacks.
Growth Catalysts
- Electrification mandates:The EU Green Deal requires OEMs to validate battery thermal runaway containment through simulation rather than destructive testing, pulling high-performance solver demand from German and French automotive clusters.
- REACH material compliance:Chemical substitution protocols for coolants and refrigerants must be validated computationally before physical prototyping, embedding CFD into European product development workflows.
- Aerospace certification pressure:EASA airworthiness standards for hydrogen propulsion systems mandate traceable computational fluid validation, locking Toulouse and Munich primes into multi-year software partnerships.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in HPC accelerators creates vendor lock-in risk for European engineering teams scaling electrification workloads.
- Specialist talent scarcity:The pool of engineers combining turbulence modeling expertise with HPC architecture knowledge concentrates in German and Swiss academic corridors, inflating compensation costs.
- Perpetual license friction:CE marking documentation requirements under the EU Machinery Directive favor incumbent vendors with established validation libraries, raising switching costs for mid-tier consultancies.
Strategic Opportunities
- Polish manufacturing upgrade:EU cohesion funds are financing simulation capability buildouts in emerging automotive supplier parks near Wrocław and Poznań, creating greenfield licensing opportunities.
- Hydrogen infrastructure simulation:The EU Hydrogen Strategy mandates pipeline and storage validation standards that lack established physical test protocols, opening computational-first certification pathways.
- Cloud-HPC convergence:Mid-sized French engineering consultancies are adopting elastic solver access to bid on German OEM projects without captive supercomputing investment.
Industry Challenges
- Multiphysics integration complexity:Coupling thermal, electrical, and mechanical solvers for battery pack analysis requires rare cross-domain expertise that European universities produce insufficiently.
- Validation data scarcity:Hydrogen combustion and cryogenic storage phenomena lack comprehensive experimental datasets, forcing OEMs to fund proprietary test campaigns that delay simulation deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Computational Fluid Dynamics Market |
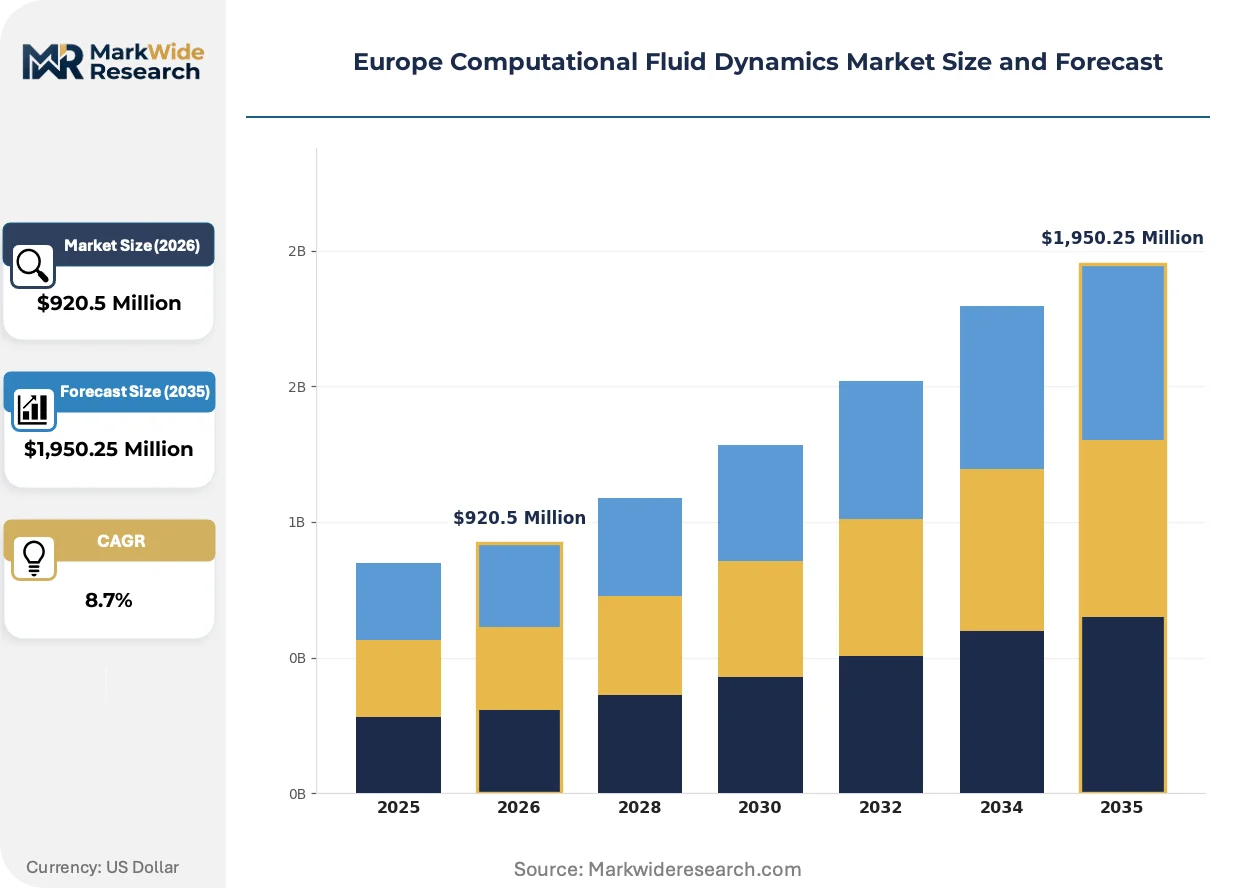
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,950.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Cloud-based Solutions, On-premise Solutions End User: Aerospace, Automotive, Energy, Healthcare Deployment: On-premises, Cloud, Hybrid, SaaS Solution: Simulation, Modeling, Analysis, Visualization |
| Companies Covered | Siemens, The MathWorks, Inc., Ansys Inc., PTC Inc., Hexagon AB, Dassault Systemes, Autodesk, Altair Engineering, COMSOL AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Computational Fluid Dynamics Market Strategic Shifts & Innovations
Digital thread architectures are collapsing the boundary between CAD geometry and solver mesh generation, enabling real-time design feedback loops that compress iteration cycles from weeks to hours in European automotive development centers.
Physics-informed neural networks are expanding into turbulence closure modeling, reducing mesh resolution requirements for external aerodynamics simulations. German OEMs are piloting these architectures for early-stage vehicle drag estimation, cutting preprocessing overhead by half. The technology is expanding into certification-grade workflows as EASA establishes validation protocols for machine-learning-augmented solvers.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is mandating computational validation of alternative thermal management fluids. French automotive suppliers must demonstrate heat exchanger performance using low-global-warming-potential coolants through simulation before physical prototyping approval. This regulatory pressure is accelerating solver procurement in Lyon and Paris engineering centers.
Subscription access models are displacing perpetual licenses among mid-sized consultancies bidding on fragmented EU project work. Italian engineering services firms now prefer monthly solver elasticity over capital-intensive HPC ownership, reshaping vendor revenue recognition patterns. This shift concentrates most visibly in Spain and Portugal, where aerospace subcontractor networks lack scale for captive infrastructure.
Europe Computational Fluid Dynamics Market Segmentation
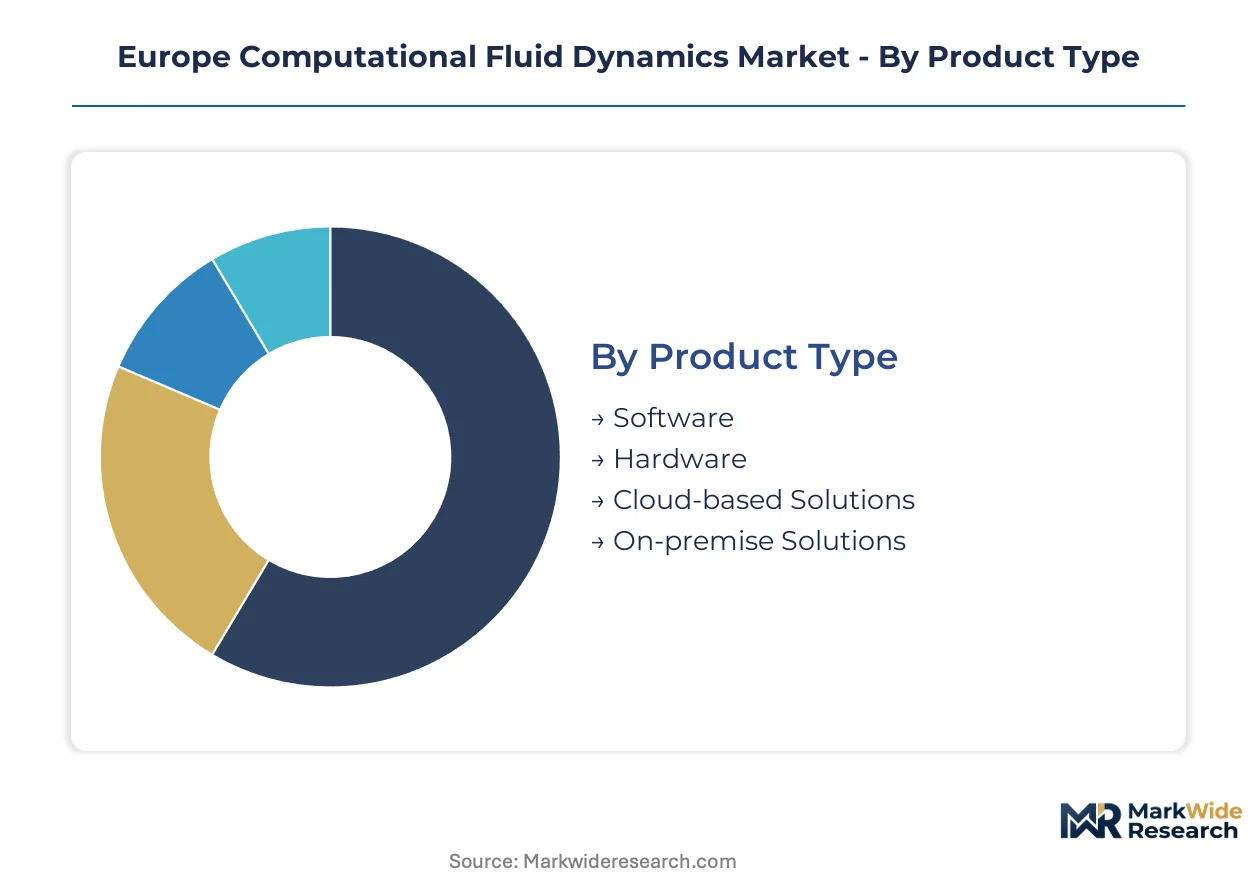
CFD market segmentation reveals how procurement patterns concentrate around solver licensing models and deployment architectures. European engineering teams select configurations based on project scale, certification requirements, and HPC infrastructure ownership.
Product Type:
Software licensing commands premium positioning where perpetual models anchor vendor revenue stability.
- Software:Perpetual licenses with annual maintenance streams dominate procurement from German automotive OEMs and French aerospace primes. EASA certification-grade accuracy requirements lock Toulouse and Munich engineering centers into multi-year solver partnerships with established validation libraries.
- Hardware:Captive HPC clusters concentrate in Swiss and German academic corridors where turbulence modeling expertise overlaps with accelerator architecture knowledge. NVIDIA GPU supply concentration creates vendor lock-in risk for teams scaling electrification workloads.
- Cloud-based Solutions:Elastic solver access appeals to mid-sized French consultancies bidding on fragmented EU project work.
- On-premise Solutions:CE marking documentation requirements favor incumbents with established thermal validation protocols.
Software absorbs the bulk of installed capacity; Cloud-based Solutions is expanding most quickly.
End User:
Application-driven segmentation shows how regulatory pressure reshapes solver demand across European industrial clusters.
- Aerospace:EASA airworthiness standards for hydrogen propulsion systems mandate traceable computational validation. Toulouse primes command premium pricing for certification-grade accuracy that physical testing cannot replicate.
- Automotive:EU Green Deal thermal runaway containment rules pull high-performance solver demand from German and French automotive clusters. Battery pack multiphysics integration requires rare cross-domain expertise.
- Energy:Standardized turbine and heat exchanger simulation templates mature around F-Gas Regulation compliance deadlines.
- Healthcare:Medical device thermal safety documentation under EU MDR embeds CFD into product development workflows.
Automotive commands the largest procurement volumes; Aerospace maintains the steepest pricing premiums.
Deployment:
Infrastructure ownership models segment European engineering teams by project predictability and capital availability.
- On-premises:German OEMs retain captive supercomputing for proprietary electrification programs where data sovereignty concerns block external solver access.
- Cloud:Italian and Spanish engineering services firms adopt monthly elasticity over capital-intensive HPC ownership.
- Hybrid:French automotive suppliers blend on-premise preprocessing with cloud burst capacity for peak certification campaigns.
- SaaS:Subscription access displaces perpetual licenses among mid-tier consultancies in Portugal and Poland.
On-premises retains the deepest solver customization; SaaS gains share fastest among emerging supplier networks.
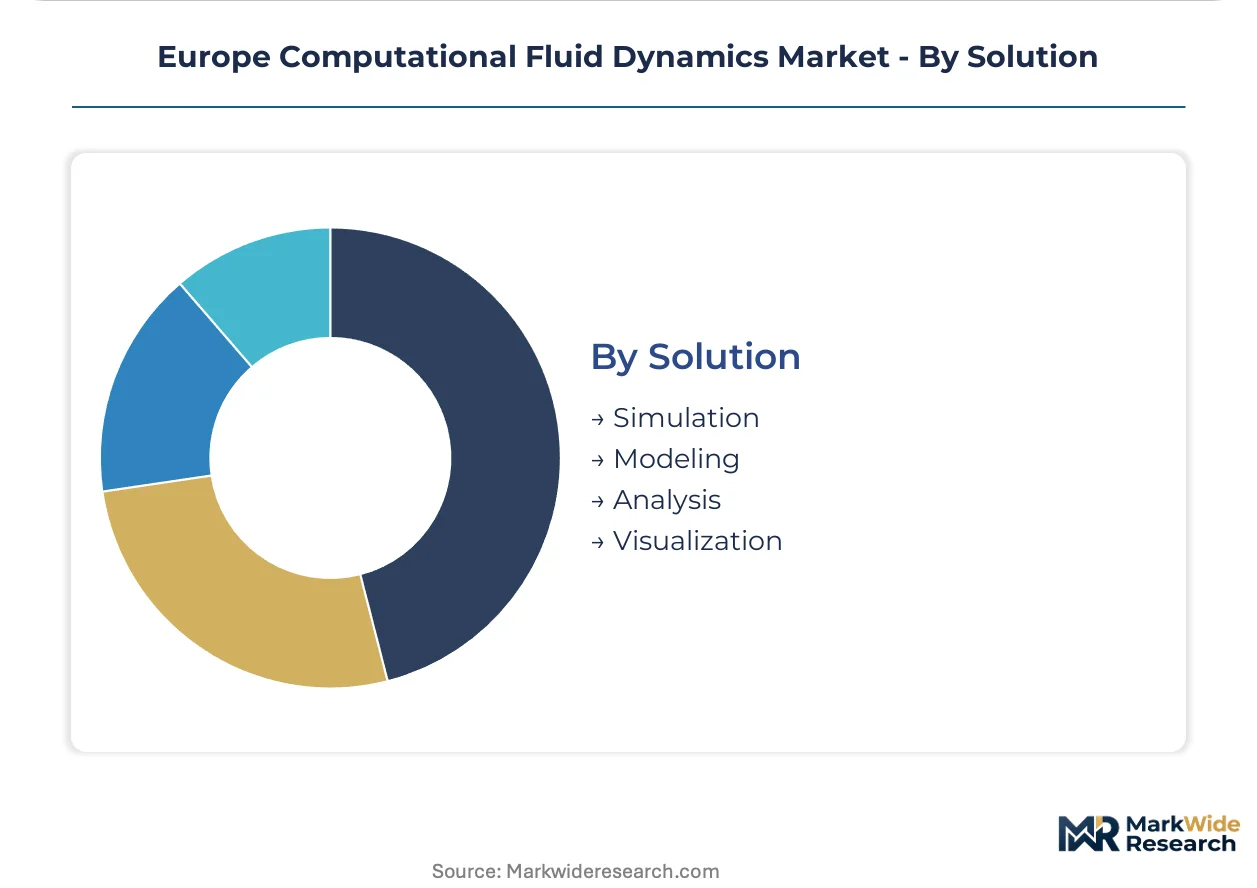
Solution:
Workflow stage segmentation tracks how digital thread architectures collapse traditional boundaries between geometry and analysis.
- Simulation:Navier-Stokes equation solvers with mesh resolutions from thousands to billions of cells anchor product development cost reduction.
- Modeling:Physics-informed neural networks expand into turbulence closure modeling at German OEM pilot programs.
- Analysis:REACH material compliance validation embeds chemical substitution protocols into European product lifecycles.
- Visualization:Real-time design feedback loops compress iteration cycles from weeks to hours in automotive development centers.
Simulation captures the core revenue base; Modeling climbs the fastest as machine-learning-augmented solvers mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CFD procurement concentrates in German and French industrial corridors where automotive electrification and aerospace certification demands overlap. Engineering teams in Munich, Stuttgart, and Toulouse anchor solver licensing volumes. Regulatory pressure from Brussels reshapes simulation requirements across the continent.
Germany
Battery thermal runaway containment and hydrogen propulsion validation pull high-performance solver demand from OEMs. The EU Green Deal mandates simulation-first approaches for electrification programs. Munich and Stuttgart engineering centers lock into multi-year partnerships with vendors offering EASA-grade validation libraries.
France
Aerospace primes in Toulouse command premium pricing for certification-grade accuracy requirements. REACH chemical substitution protocols embed CFD into coolant and refrigerant validation workflows. Lyon and Paris engineering centers accelerate solver procurement to meet F-Gas Regulation compliance deadlines.
United Kingdom
Automotive battery pack multiphysics integration drives solver demand from Midlands manufacturing clusters. CE marking documentation under the EU Machinery Directive favors incumbent vendors with established thermal validation protocols. Oxford and Cambridge academic corridors supply turbulence modeling expertise to engineering consultancies.
Italy
Mid-sized engineering services firms adopt subscription solver access for fragmented EU project work. The EU Hydrogen Strategy mandates pipeline validation standards that lack established physical test protocols. Turin and Milan automotive supplier networks leverage cloud elasticity to bid on German OEM contracts.
Poland
EU cohesion funds finance simulation capability buildouts in emerging automotive supplier parks near Wrocław and Poznań. REACH material compliance requirements embed chemical substitution validation into product development workflows. Greenfield licensing opportunities attract vendors targeting Central European manufacturing upgrades.
Europe Computational Fluid Dynamics Market Key Industry Players
Hardware-software integration dominates the current landscape as vendors bundle solvers with HPC infrastructure. The market structures around three tiers: industrial automation specialists with captive hardware stacks, pure-play simulation software houses with deep aerospace partnerships, and cloud-native entrants targeting mid-sized consultancies. Strategic archetypes include integrated platform providers, best-of-breed solver specialists, and elastic HPC service operators. M&A activity and technology licensing agreements represent the dominant competitive moves.
Among Germany-based industrial conglomerates, Siemens anchors the integrated platform tier through hardware-software bundling. Ansys Inc. and Dassault Systemes exemplify the best-of-breed archetype with established validation libraries. These three occupy positions that reflect distinct approaches to solver deployment: captive infrastructure, perpetual licensing, and CAD-integrated workflows.
| Leading Market Players |
|---|
| Siemens |
| The MathWorks, Inc. |
| Ansys Inc. |
| PTC Inc. |
| Hexagon AB |
| Dassault Systemes |
| Autodesk |
| Altair Engineering |
| COMSOL AB |
| Others |
Cost & Logistics Intelligence
Certification-grade solver accuracy separates premium perpetual licenses from commodity subscription tiers, with EASA validation libraries commanding threefold price multiples over standard cloud elasticity. This bifurcation concentrates procurement power among German and French aerospace primes while mid-sized consultancies in Italy and Spain absorb pricing pressure through SaaS displacement.
Pricing Analysis
High-volume automotive procurement compresses margins on standard solver licenses, while aerospace certification-grade accuracy sustains premium pricing. Three-tier pricing structure across premium, standard, and economy levels tracks EASA validation depth, GPU acceleration capability, and maintenance bundling. Pricing pressure stems from NVIDIA GPU supply concentration forcing hardware-software bundling concessions. Mid-sized engineering services firms exhibit highest price sensitivity, whereas Toulouse and Munich primes prioritize traceability over cost.
Supply Chain Analysis
Reverse-logistics flows for HPC accelerator refurbishment concentrate in German and Swiss academic corridors where GPU lifecycle extension reduces electrification workload costs. NVIDIA's Taiwan and USA fabrication network anchors accelerator supply, while European assembly and validation centers in Germany and the Netherlands manage regional distribution. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and liquid cooling components. Single-source vulnerability at the foundry level exposes European engineering teams to allocation risk. Distribution runs through direct vendor relationships with automotive OEMs and aerospace primes, supplemented by channel partners serving mid-tier consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist turbulence modeling expertise scarcity props pricing power for vendors with captive HPC infrastructure, constraining supply expansion despite electrification demand acceleration.
For Market Incumbents: Anticipate cloud-native entrants eroding mid-market share through elastic solver access, and respond by deepening hardware-software integration around Siemens' industrial automation bundling model. Prioritize certification library expansion for EASA hydrogen propulsion protocols to lock Toulouse and Munich primes into renewal cycles. Defensive consolidation through targeted turbulence modeling talent acquisition in German and Swiss academic corridors protects margin structure. For New Entrants and Emerging Players: Begin with Polish automotive supplier parks near Wrocław and Poznań where EU cohesion funds finance greenfield simulation capability without incumbent saturation. Target cloud-HPC convergence for mid-sized French engineering consultancies bidding on fragmented German OEM project work. Go-to-market angle: subscription elasticity with pre-configured battery thermal runaway templates aligned to EU Green Deal validation requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial automation conglomerates seeking solver technology for electrification verticals. Long-term viability favors vendors with established EASA validation protocols and captive GPU supply relationships over pure-play SaaS operators. Acquisition target archetype: mid-sized consultancies with embedded turbulence modeling expertise and German automotive OEM relationships. Signal to watch: EASA publication of machine-learning-augmented solver validation standards enabling physics-informed neural network certification.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Software Bundling | Siemens' integrated platform locks German automotive OEMs into captive infrastructure for battery thermal management. |
| Cloud-HPC Convergence | Elastic solver access enables Italian consultancies to bid on German electrification projects without supercomputing investment. |
| Certification Library Expansion | EASA-grade validation protocols for hydrogen propulsion secure multi-year partnerships with Toulouse aerospace primes. |
| Turbulence Modeling Talent Acquisition | German and Swiss academic corridor expertise scarcity makes specialist teams strategic defensive assets. |
| Physics-Informed Neural Network Development | Machine-learning-augmented solvers cut preprocessing overhead for early-stage vehicle drag estimation at pilot German OEMs. |
Research Approach
Trade publications, EASA regulatory filings, and hyperscaler capex disclosures formed the secondary backbone, cross-referenced against primary interviews with CFD software product managers, HPC infrastructure procurement leads at German automotive OEMs, aerospace certification engineers in Toulouse, and engineering consultancy principals in France and Italy. Bottom-up and top-down triangulation validated segment sizing across deployment models and end-user industries.
Bottom-up modeling tracked solver licensing volumes by deployment architecture, while top-down analysis calibrated against EU industrial software spending patterns across the analysis window. Segmentation dimensions included product type, end-user industry, deployment model, and solution workflow stage. CAGRs derived from regression analysis of historical electrification program simulation intensity and projected EU Green Deal compliance deadlines. Industry-specific inputs encompassed EASA airworthiness standard evolution and F-Gas Regulation phasedown timelines.
Underlying measurement precision varies by segment; aerospace certification-grade software carries tighter precision than emerging cloud-native solutions. Forecasts reflect documented assumptions regarding GPU supply availability, regulatory validation protocol adoption rates, and hydrogen infrastructure simulation standard development. Practitioners should monitor EASA machine-learning solver guidance, NVIDIA allocation policy shifts, and EU cohesion fund disbursement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Emission Monitoring Software Market