
 Computational Fluid Dynamics (CFD) Market | 2026-2036
Computational Fluid Dynamics (CFD) Market Size, Share, and Industry Trends Forecast 2026-2036
Computational Fluid Dynamics (CFD) Market Outlook
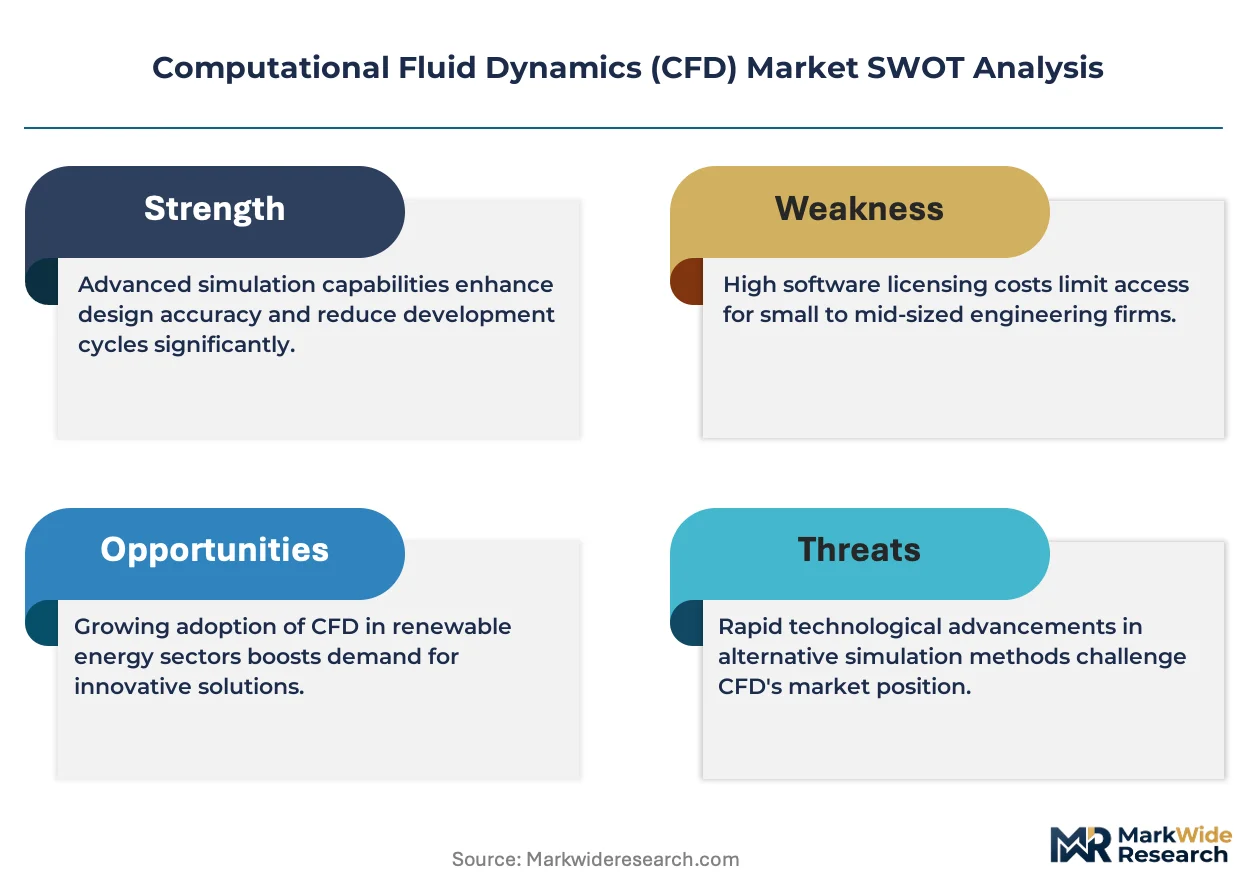
The CFD software market is decoupling into two distinct tiers: perpetual-license platforms with deep solver customization versus subscription cloud tools with templated workflows. ANSYS, Inc. dominates high-fidelity aerospace and automotive applications through its Fluent and CFX solvers. Siemens AG leverages its Xcelerator portfolio to anchor digital twin integrations across industrial machinery. Autodesk, Inc. competes on accessibility with Fusion 360 CFD targeting mid-market designers and smaller consultancies.
Computational Fluid Dynamics encompasses numerical methods and algorithms that solve the Navier-Stokes equations to simulate fluid flow, heat transfer, and related phenomena, typically requiring mesh resolutions from thousands to billions of cells depending on Reynolds number and turbulence modeling needs. Its primary purpose is to replace or reduce physical prototyping in engineering design cycles. Cloud-Based deployment is capturing the fastest expansion as engineering teams distribute simulation workloads without capital-intensive HPC infrastructure. Aerospace Design remains the most mature application segment with established solver benchmarks and certification pathways, while Semiconductor Cooling represents an emerging margin pool driven by thermal management demands in advanced node chip architectures.
The U.S. FAA imposes stringent computational validation for aircraft icing and aerodynamic stability, pushing OEMs toward certified high-accuracy solvers. The EU EASA aligns with CS-25 airworthiness codes that require documented CFD correlation with flight test data for new type certifications. The EU AI Act introduces emerging compliance obligations for autonomous simulation pipelines and machine-learning-augmented turbulence models. Stakeholders must weigh solver certification requirements against cloud accessibility trade-offs when selecting platform strategies.
Market Dynamics
CFD software procurement is bifurcating as aerospace OEMs demand solver-certified platforms for FAA-EASA compliance while mid-market engineering teams migrate to templated cloud subscriptions for rapid design iteration cycles.
Growth Catalysts
- EU EASA CS-25 airworthiness mandates:New type certifications require documented CFD correlation with flight test data, compelling turbine blade manufacturers to expand simulation budgets for high-fidelity aerodynamic validation.
- Semiconductor thermal management:Advanced node chip architectures below 3nm generate heat flux densities exceeding traditional cooling limits, driving foundries to adopt conjugate heat transfer solvers for package-level thermal design.
- Germany's industrial engineering clusters:Automotive OEMs and Tier-1 suppliers in Stuttgart and Munich concentrate demand for multiphysics coupling between CFD and structural solvers for powertrain optimization.
Market Restraints
- GPU memory bandwidth constraints:High-Reynolds-number turbulence simulations with billion-cell meshes exhaust available HBM3 capacity, forcing time-step sacrifices or mesh coarsening that degrades accuracy.
- License cost concentration:Perpetual solver licenses with source-code access command six-figure annual fees, excluding smaller consultancies and university spinouts from certified high-fidelity tools.
- FAA solver certification timelines:Validation protocols for aircraft icing and stability simulations extend 18-24 months, compressing available design windows for new aircraft programs.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic EV manufacturers require thermal management simulation for battery pack cooling, creating entry points for cloud-native CFD platforms without legacy infrastructure dependencies.
- Digital twin convergence:Coupling real-time sensor feeds with reduced-order CFD models enables predictive maintenance for industrial gas turbines, opening subscription revenue streams beyond design-phase licensing.
- EU AI Act compliance services:Autonomous mesh generation and ML-augmented turbulence models face emerging audit requirements, creating consultative margins for verification and documentation workflows.
Industry Challenges
- PhD-level turbulence modeling expertise:Industrial LES and hybrid RANS-LES implementations require specialized training that outpaces university pipeline output, inflating compensation for experienced CFD engineers.
- Legacy CAD-CFD integration friction:Established automotive workflows built on parametric CAD kernels resist automated meshing pipelines, forcing manual geometry cleanup that consumes 40-60% of project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computational Fluid Dynamics (CFD) Market |
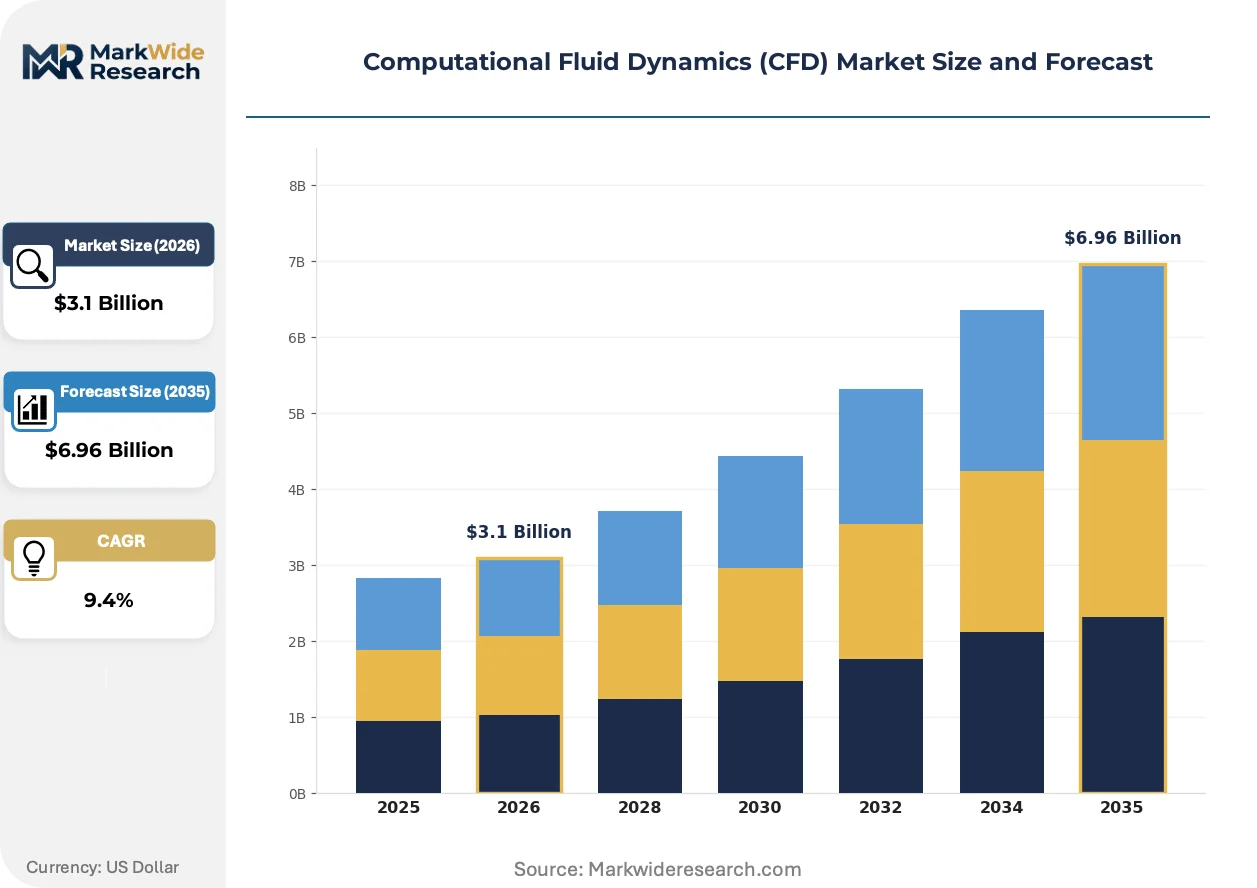
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.96 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: Software, Consulting Services, Simulation Tools, Training & Support Application: Aerospace Design, HVAC Systems, Marine Hydrodynamics, Semiconductor Cooling End User: OEMs, Research Institutes, Energy Producers, Defense Contractors |
| Companies Covered | Altair Engineering Inc., COMSOL AB, ANSYS, Inc., Flow Science, Inc., PTC Inc., Siemens AG, Autodesk, Inc., Hexagon AB, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computational Fluid Dynamics (CFD) Market Strategic Shifts
Physics-informed neural networks and reduced-order modeling techniques are compressing simulation turnaround times from weeks to hours, restructuring competitive advantage around solver speed rather than raw hardware scale.
GPU-native lattice Boltzmann methods are consolidating high-frequency aerodynamic and aeroacoustic simulations into unified workflows. Automotive wind noise teams at premium OEMs now execute overnight design sweeps that previously required week-long CPU cluster reservations. This acceleration is compressing the competitive window between physical prototype builds and virtual validation gates.
The EU AI Act's risk classification framework is mandating explainability documentation for machine-learning-augmented turbulence closures. Aerospace certification bodies now require traceable training data provenance and uncertainty quantification for AI-assisted simulations submitted in type certification packages. German and French OEMs are establishing internal audit functions to pre-validate solver outputs before regulatory submission.
Engineering procurement teams are unbundling perpetual licenses into consumption-based cloud credits for transient simulation bursts. Mid-market consultancies in Spain and Italy now access HPC-scale solvers through browser interfaces, bypassing capital-intensive on-premise infrastructure. This democratization is fragmenting the buyer base and compressing price realization for traditional seat-based licensing models.
Computational Fluid Dynamics (CFD) Market Segmentation
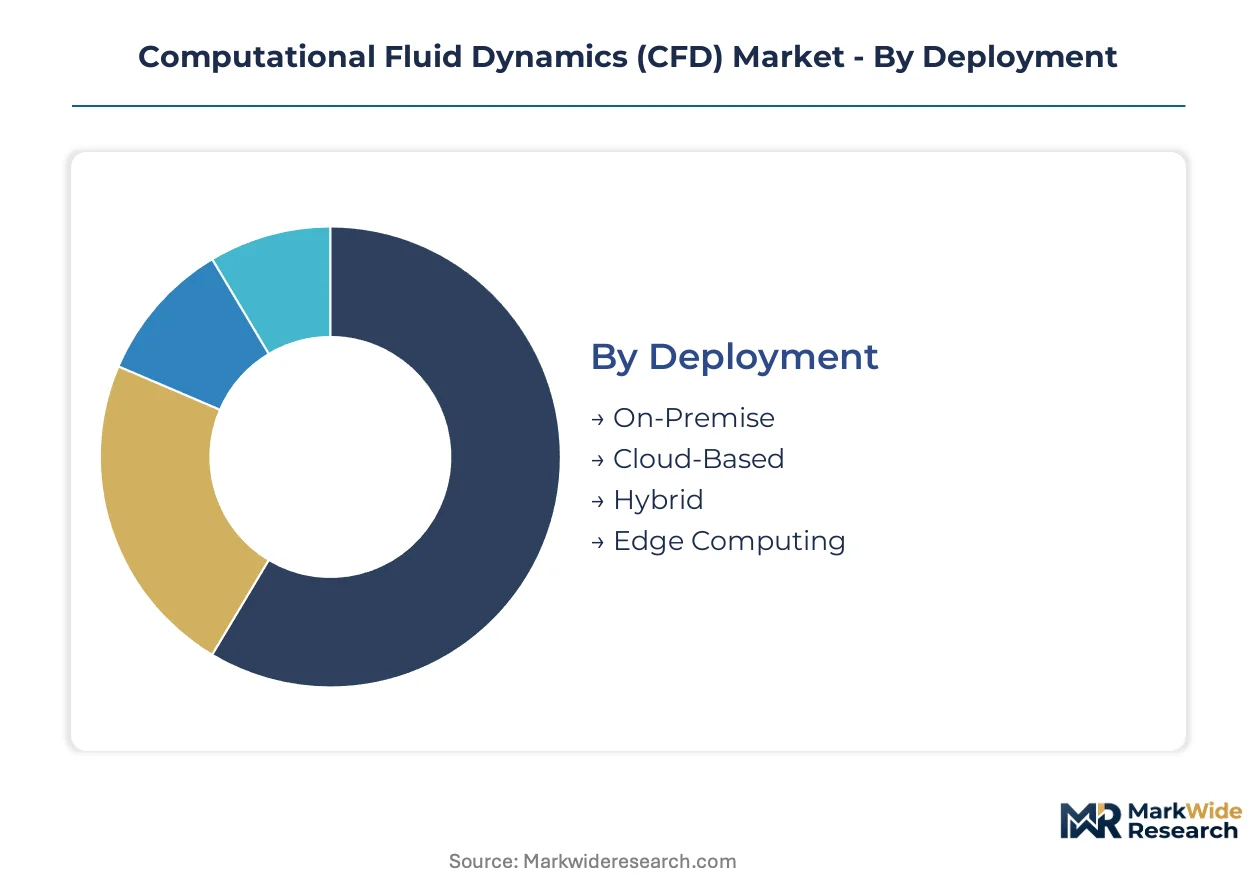
CFD procurement patterns diverge sharply across deployment architectures and buyer sophistication levels. Aerospace OEMs prioritize solver-certified perpetual licenses, while mid-market engineering teams favor consumption-based cloud access. Application-specific thermal and aerodynamic requirements further fragment vendor selection criteria.
Deployment:
Cost tier separates capital-intensive perpetual infrastructure from operational cloud expenditure models.
- On-Premise:Dedicated HPC clusters with GPU-accelerated nodes support billion-cell turbulence simulations. Demand concentrates at Boeing and Airbus facilities in Seattle and Toulouse, driven by FAA-EASA certification requirements for documented solver correlation.
- Cloud-Based:Browser-accessible solvers with consumption-based credits eliminate upfront hardware investment. Stuttgart automotive clusters and Spanish mid-market consultancies adopt these platforms for rapid design iteration without legacy infrastructure.
- Hybrid:Split workloads reserve on-premise capacity for steady-state validation while bursting transient simulations to cloud. Energy producers in Texas and Norway use this architecture for seasonal turbine maintenance scheduling.
- Edge Computing:Reduced-order models deployed directly on industrial equipment enable real-time thermal monitoring. Semiconductor foundries in Taiwan integrate these for wafer-level process control.
On-Premise deployments lead volumes today; Cloud-Based solutions are gaining share fastest.
Solution Type:
Application maturity determines whether buyers seek standalone solvers or integrated consultative support.
- Software:Perpetual licenses with source-code access command premium pricing for Navier-Stokes solver customization. German automotive OEMs in Munich specify these for multiphysics coupling with structural finite element packages.
- Consulting Services:PhD-level turbulence modeling expertise delivered through project-based engagements. Aerospace suppliers in Wichita and Bristol contract these for aircraft icing validation protocols.
- Simulation Tools:Pre-configured templates for specific physics domains accelerate non-expert adoption. HVAC contractors in Florida and Arizona deploy these for building energy code compliance.
- Training & Support:Certification programs and solver-specific education address talent pipeline gaps. Indian engineering institutes under the PLI scheme purchase these to develop domestic EV thermal management capabilities.
Software licenses dominate revenue today; Consulting Services show the steepest expansion trajectory.
Application:
Regulatory certification requirements create tiered entry barriers across industrial verticals.
- Aerospace Design:High-fidelity aerodynamic validation for turbine blades and airframe stability. FAA CS-25 mandates in the United States and EU EASA correlation requirements in France and Germany sustain concentrated simulation budgets at Airbus and Safran.
- Semiconductor Cooling:Conjugate heat transfer analysis for advanced node architectures below 3nm. Foundries in Taiwan and South Korea drive adoption as heat flux densities exceed traditional cooling limits.
- HVAC Systems:Building energy simulation for regulatory compliance and operational optimization. Contractors in California and New York specify these for state-level efficiency mandates.
- Marine Hydrodynamics:Hull resistance and propeller cavitation analysis for fuel efficiency. Shipbuilders in South Korea and Norway deploy these for IMO emissions compliance.
Aerospace Design anchors current spending; Semiconductor Cooling is climbing the fastest.
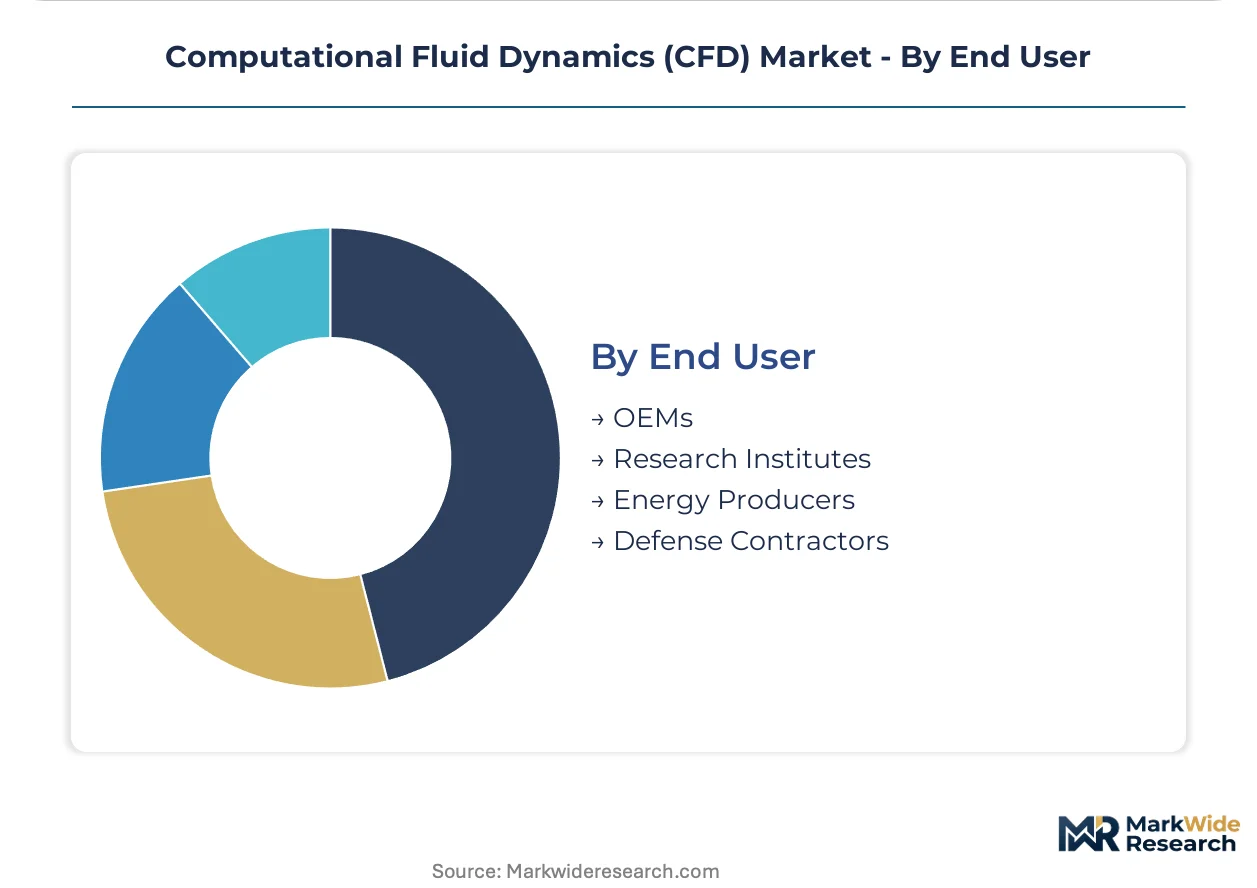
End User:
Internal R&D depth versus outsourced expertise determines procurement channel selection.
- OEMs:Captive simulation departments with multi-solver portfolios and dedicated HPC infrastructure. Automotive and aerospace manufacturers in Germany, Japan, and the United States maintain the largest internal CFD capabilities.
- Research Institutes:Academic and government laboratories advancing turbulence model fundamentals. National laboratories in the United States and Max Planck institutes in Germany publish benchmark validation studies.
- Energy Producers:Industrial gas turbine operators seeking predictive maintenance through digital twin integration. Utility operators in Texas, Saudi Arabia, and the United Kingdom contract reduced-order model deployments.
- Defense Contractors:Classified aerodynamic and thermal simulations for military platforms. Suppliers in the United States, United Kingdom, and France operate under restricted data handling protocols.
OEMs command the largest simulation budgets today; Energy Producers are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level turbulence modeling expertise concentrates in German automotive clusters, US aerospace hubs, and Taiwanese semiconductor foundries, creating geographic specialization in solver development and multiphysics applications.
United States
Boeing and Lockheed Martin sustain concentrated simulation budgets for FAA-certified aircraft icing validation. The FAA imposes stringent computational validation protocols for aerodynamic stability under CS-25 alignment. Seattle and Wichita host captive HPC facilities where billion-cell meshes support turbine blade optimization programs.
Germany
Automotive OEMs in Stuttgart and Munich drive demand for multiphysics coupling between CFD and structural solvers. EU EASA mandates documented correlation with flight test data for new type certifications. The Baden-Württemberg engineering cluster anchors Europe's deepest reservoir of LES implementation expertise for powertrain thermal management.
China
Domestic EV manufacturers under the national dual carbon goals require battery pack cooling simulation at scale. MIIT standards for new energy vehicle thermal safety push adoption of conjugate heat transfer solvers. The Yangtze River Delta foundries deploy package-level thermal design for advanced node architectures below 5nm.
South Korea
Samsung and SK Hynix generate demand for semiconductor cooling solutions as heat flux densities exceed traditional limits. The Korean Ministry of Trade, Industry and Energy funds domestic solver development through national R&D programs. The Seoul Capital Area concentrates foundry engineering teams integrating real-time thermal monitoring at wafer level.
India
Domestic EV manufacturers under the PLI scheme require thermal management simulation without legacy infrastructure dependencies. The Automotive Research Association of India establishes testing protocols that reference CFD validation for battery safety certification. Engineering institutes in Maharashtra and Karnataka purchase training programs to develop domestic solver capabilities.
Computational Fluid Dynamics (CFD) Market Competitive Environment
Top-tier vendors anchor perpetual-license platforms with deep solver customization, while mid-market specialists compete on cloud accessibility and templated workflows. The market structure consolidates around three to five dominant platforms serving certified aerospace applications, with fragmentation emerging at the cloud-native tier. Two strategic archetypes dominate: solver-certified incumbents pursuing FAA-EASA validation lock-in, and cloud-native challengers democratizing HPC access through consumption credits. Competitive moves center on digital twin integration partnerships and reduced-order model deployments for predictive maintenance revenue streams.
Within the solver-certified tier, ANSYS, Inc. and Siemens AG occupy positions exemplifying deep aerospace and automotive integration, while Autodesk, Inc. represents the accessibility-focused archetype targeting mid-market designers. These three anchors illustrate the bifurcation between high-fidelity certification requirements and rapid iteration demands across the buyer base.
| Leading Market Players |
|---|
| Altair Engineering Inc. |
| COMSOL AB |
| ANSYS, Inc. |
| Flow Science, Inc. |
| PTC Inc. |
| Siemens AG |
| Autodesk, Inc. |
| Hexagon AB |
| Dassault Systèmes |
| Others |
Value Chain & Pricing Dynamics
GPU-native lattice Boltzmann methods are compressing solver development timelines while concentrating production-grade HBM3 supply among Taiwanese foundries and Korean memory houses, simultaneously reshaping cost economics for high-fidelity simulation tiers and tightening vendor control over performance-differentiated pricing.
Pricing Analysis
Perpetual licenses with source-code access and SaaS consumption credits now split the buyer base. Price differentiation hinges on FAA-EASA certification tier and solver customization depth. Pricing pressure stems from cloud-native platforms democratizing HPC access through browser-based credits. Mid-market consultancies in Spain and Italy exhibit highest price sensitivity; aerospace OEMs in Seattle and Toulouse absorb premium tiers without elasticity.
Supply Chain Analysis
Dual-sourcing mandates from Boeing and Airbus compel solver vendors to qualify GPU clusters across both Taiwan and South Korea. The supply chain draws from NVIDIA H100 silicon, HBM3 memory stacks, and specialized cooling substrates. Single-source vulnerability concentrates in advanced node GPU allocation. Distribution runs through direct enterprise sales for perpetual licenses and hyperscaler marketplaces for cloud consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CFD procurement is a late-cycle quality story as FAA-EASA certification requirements harden demand for documented solver correlation with flight test data, elevating premium-tier pricing power.
For Market Incumbents: Extend certification investment into EU AI Act compliance documentation for ML-augmented turbulence models. Deepen vertical integration into reduced-order model deployment for industrial gas turbine predictive maintenance. Lock in aerospace OEM relationships through multi-year solver validation protocols that cloud-native challengers cannot replicate. For New Entrants and Emerging Players: Launch via hyperscaler marketplace distribution to bypass direct sales infrastructure costs. Target India's PLI-scheme EV manufacturers with battery pack cooling templates that require no legacy HPC investment. Emphasize consumption-based pricing to undercut perpetual-license sticker shock. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native CFD specialists with proven reduced-order model IP because aerospace digital twin convergence is fragmenting maintenance-phase revenue from design-phase incumbents. Monitor FAA solver certification queue lengths as inflection signal; compression indicates cloud-native pressure while extension validates incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Documentation | Creates audit-service margins for ML-augmented turbulence model verification at German and French OEMs. |
| Reduced-Order Model Deployment | Enables real-time thermal monitoring subscriptions for semiconductor foundries in Taiwan. |
| Hyperscaler Marketplace Distribution | Democratizes HPC access for Spanish and Italian mid-market engineering consultancies. |
| Multiphysics Solver Integration | Captures Stuttgart automotive demand for powertrain thermal-structural coupling. |
| PLI-Scheme Partnership in India | Develops domestic EV battery cooling capabilities without legacy infrastructure dependencies. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged CFD software product managers, aerospace certification engineers at FAA-EASA-aligned OEMs, HPC procurement officers, and thermal design leads at semiconductor foundries. Secondary validation drew from FAA CS-25 advisory circulars, EU EASA certification memoranda, SEC 10-K filings of publicly traded simulation vendors, and hyperscaler capex disclosure reports. Bottom-up deployment model sizing triangulated against top-down aerospace and automotive simulation budget aggregates.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. The analytical framework modeled deployment architecture, solution type, application vertical, and end-user sophistication tier. CAGRs derived from segment-level adoption curves weighted by regulatory mandate timing. Industry-specific inputs included GPU memory bandwidth progression timelines and FAA solver certification queue data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under AI Act enforcement intensity and foundry capital expenditure cycles. Deviation in FAA-EASA harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Digital Smell Technology Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Global Weather Forecasting Systems Market