
 AI-Powered Video Analytics Market | 2026-2036
AI-Powered Video Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Powered Video Analytics Market Analysis
The EU AI Act is decoupling biometric video analytics from legacy procurement frameworks across European public safety agencies. Hikvision Digital Technology anchors its position through deep manufacturing scale in camera hardware paired with embedded inference chips. Genetec Inc. differentiates via unified security platform architecture that integrates third-party analytics modules. Axis Communications AB specializes in edge-computing cameras with onboard deep learning accelerators, reducing bandwidth dependency for real-time processing.
AI-powered video analytics encompasses software systems that apply computer vision algorithms, convolutional neural networks, and temporal pattern recognition to streaming video feeds for automated detection, classification, and prediction of events or behaviors. These systems process frame sequences at 15-30 fps through GPU or NPU hardware to generate structured metadata for security operations, traffic optimization, or customer journey mapping. Surveillance systems still occupy the largest revenue pool, though retail analytics is registering the fastest expansion as brick-and-mortar operators deploy shelf-scanning and queue-management algorithms. Deep learning architectures are displacing rules-based computer vision in traffic management deployments, where multi-object tracking across complex intersections demands adaptive model performance.
The U.S. Department of Homeland Security and the U.K. Information Commissioner's Office are tightening algorithmic transparency mandates for facial recognition deployments in transportation hubs, forcing vendors to document training data provenance and demographic accuracy metrics. China's SAMR and NMPA are drafting national standards for intelligent video surveillance interoperability that will reshape export certification requirements for equipment manufacturers. Stakeholders must monitor whether edge computing or cloud-based inference wins the latency-privacy tradeoff in critical infrastructure deployments.
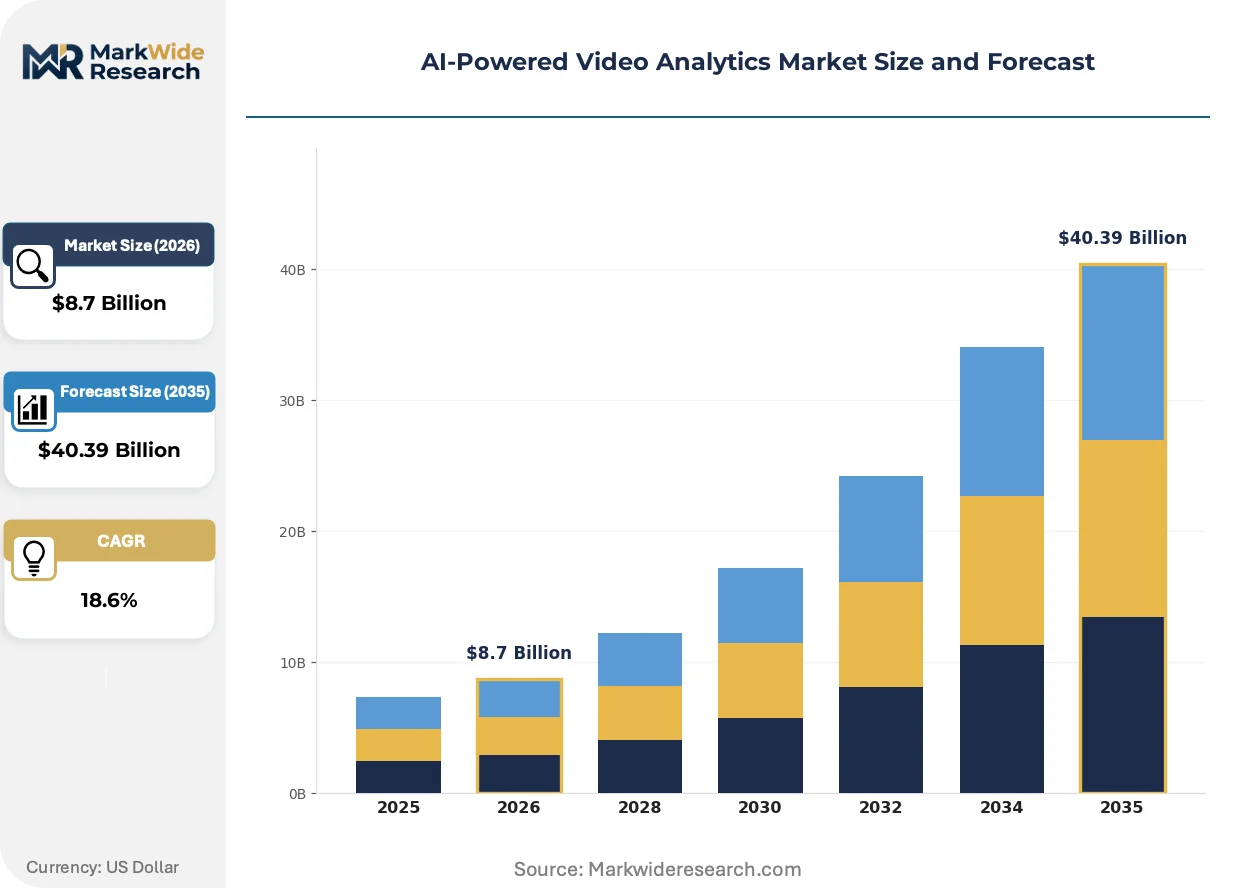
Market Dynamics
The EU AI Act's risk-based classification system is decoupling biometric video analytics from legacy procurement frameworks across European public safety agencies, forcing vendors to restructure compliance architectures and renegotiate municipal contracts.
Growth Catalysts
- Federal transportation security mandates:The U.S. Department of Homeland Security is accelerating algorithmic deployment at major aviation hubs for automated threat detection in passenger screening zones.
- Smart city infrastructure pipelines:Singapore's national digital masterplan is embedding real-time crowd analytics into urban command centers for event management and transit optimization.
- Edge computing hardware maturation:Onboard deep learning accelerators in network cameras are reducing bandwidth costs and enabling real-time inference without cloud dependency.
Market Restraints
- GPU and NPU supply concentration:Inference chip fabrication depends on a concentrated foundry base in East Asia, creating vulnerability in hardware procurement timelines.
- Algorithmic transparency mandates:The U.K. Information Commissioner's Office requires documented training data provenance and demographic accuracy metrics, extending sales cycles for facial recognition deployments.
- Rules-based computer vision substitution:Legacy traffic management systems in smaller municipalities resist full replacement due to sunk capital in installed camera networks.
Strategic Opportunities
- Retail analytics white space:Brick-and-mortar operators are deploying shelf-scanning and queue-management algorithms to recover competitive positioning against e-commerce logistics.
- Interoperability standardization in China:SAMR and NMPA national standards for intelligent video surveillance will reshape export certification requirements, favoring early-compliant manufacturers.
- Privacy-preserving edge architectures:Convergence of federated learning with edge inference is opening municipal contracts where data residency requirements previously blocked cloud solutions.
Industry Challenges
- Computer vision engineering talent scarcity:Multi-object tracking across complex intersections demands specialized expertise in temporal pattern recognition that outstrips current labor pool depth.
- Legacy security platform integration friction:Municipal buyers face technical debt when embedding AI modules into decades-old physical security management systems.
- Cross-border model validation complexity:Training data from one demographic context often fails accuracy thresholds when deployed in jurisdictions with divergent population characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Powered Video Analytics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Traffic Management, Retail Analytics, Sports Performance Technology: Computer Vision, Machine Learning, Natural Language Processing, Deep Learning End User: Public Safety, Retail Stores, Transportation Hubs, Sports Organizations Deployment: Cloud-based, On-premises, Hybrid, Edge Computing |
| Companies Covered | Hikvision Digital Technology, Genetec Inc., Axis Communications AB, Coram AI, Motorola Solutions, Bosch Security Systems, Dahua Technology, Eagle Eye Networks, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Powered Video Analytics Market Emerging Trajectories
Deep learning architectures are actively displacing rules-based computer vision across traffic management and surveillance deployments, compressing the technical shelf life of established software vendors while elevating hardware-integrated solution providers.
Transformer-based vision models are expanding into real-time video analytics through optimized attention mechanisms that reduce computational load for multi-object tracking. Traffic management authorities in the Netherlands and South Korea are piloting these architectures at complex urban intersections where occlusion and variable lighting degrade convolutional neural network performance. The shift is compressing competitive differentiation around proprietary model architectures rather than camera hardware specifications.
The EU AI Act's prohibition on real-time biometric identification in public spaces is forcing segmentation between high-risk and limited-risk application categories. Vendors must now maintain dual product lines: one for restricted law enforcement contexts with enhanced conformity assessment, another for retail and traffic applications with lighter oversight. German and French municipal buyers are delaying procurement decisions pending clarified implementation guidance from national data protection authorities.
Buyers are unbundling after-sales service contracts from initial hardware-software bundles, preferring subscription-based model retraining and accuracy auditing. Large retail chains in the United States are negotiating separate agreements with third-party algorithm validation firms rather than accepting vendor-provided performance metrics. This shift is visible most acutely in facial recognition deployments where demographic parity testing has become a procurement gate.
AI-Powered Video Analytics Market Segmentation
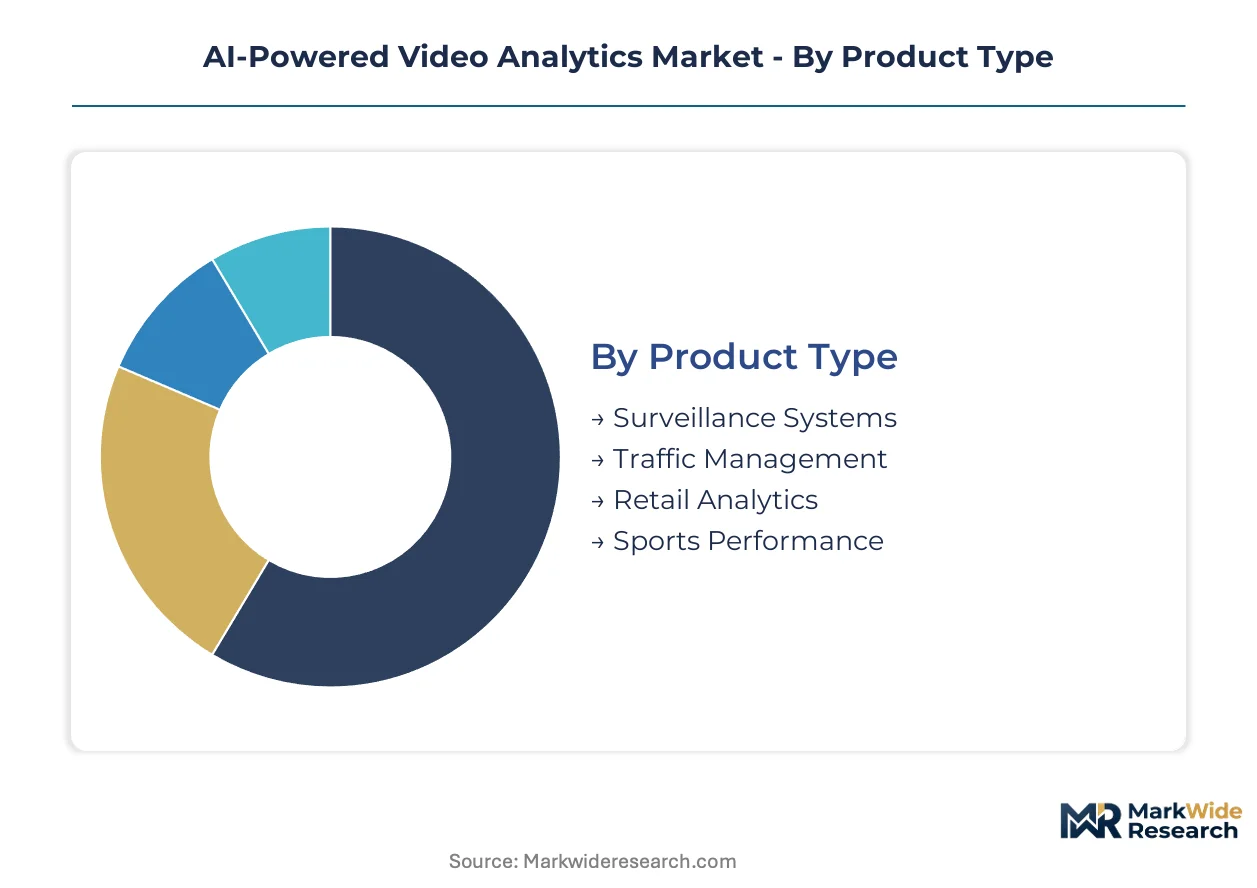
Segmentation in AI-powered video analytics reflects divergent hardware-software coupling requirements across surveillance, retail, and traffic applications. Buyers prioritize latency tolerance, data residency constraints, and integration depth with legacy security infrastructure when selecting deployment architectures.
Product Type:
Procurement budgets concentrate where real-time inference delivers measurable operational outcomes versus post-event review.
- Surveillance Systems:These deployments process 15-30 fps video streams through GPU or NPU hardware for automated threat detection and perimeter monitoring. Municipal contracts in Singapore and federal transportation security mandates in the United States anchor demand for multi-camera command center integration.
- Traffic Management:Multi-object tracking across complex intersections demands adaptive deep learning architectures that displace rules-based computer vision. Pilot programs in the Netherlands and South Korea validate transformer-based vision models for occlusion-heavy urban environments.
- Retail Analytics:Shelf-scanning and queue-management algorithms recover competitive positioning for brick-and-mortar operators against e-commerce logistics.
- Sports Performance:Athlete tracking systems generate biomechanical metadata for coaching optimization and broadcast augmentation.
Surveillance Systems leads on scale; Retail Analytics leads on momentum.
Technology:
Model architecture selection hinges on the accuracy-latency tradeoff specific to each use case's frame processing requirements.
- Deep Learning:Convolutional neural networks and transformer-based vision models enable adaptive performance across variable lighting and occlusion conditions. Traffic authorities in South Korea pilot these architectures where legacy systems fail accuracy thresholds.
- Computer Vision:Rules-based algorithms persist in smaller municipalities with sunk capital in installed camera networks resisting full replacement cycles.
- Machine Learning:Statistical pattern recognition supports behavioral anomaly detection in lower-complexity surveillance deployments.
- Natural Language Processing:Audio-visual fusion applications integrate spoken command recognition with video metadata for accessibility compliance.
Deep Learning dominates new procurement; Computer Vision retains installed base stickiness.
End User:
Regulatory scrutiny intensity varies sharply across sectors, shaping vendor compliance architecture investments.
- Public Safety:The EU AI Act's risk-based classification forces dual product line maintenance for restricted law enforcement contexts versus lighter-touch applications. German and French municipal buyers delay procurement pending national data protection authority guidance.
- Transportation Hubs:The U.S. Department of Homeland Security mandates algorithmic transparency documentation including training data provenance and demographic accuracy metrics for facial recognition deployments.
- Retail Stores:Large chains negotiate separate agreements with third-party algorithm validation firms rather than accepting vendor-provided performance metrics.
- Sports Organizations:Privacy considerations around athlete biometric data collection drive federated learning adoption for training data minimization.
Public Safety commands premium pricing; Transportation Hubs shows steepest expansion trajectory.
Deployment:
Latency requirements and data residency rules determine cloud-edge distribution of inference workloads.
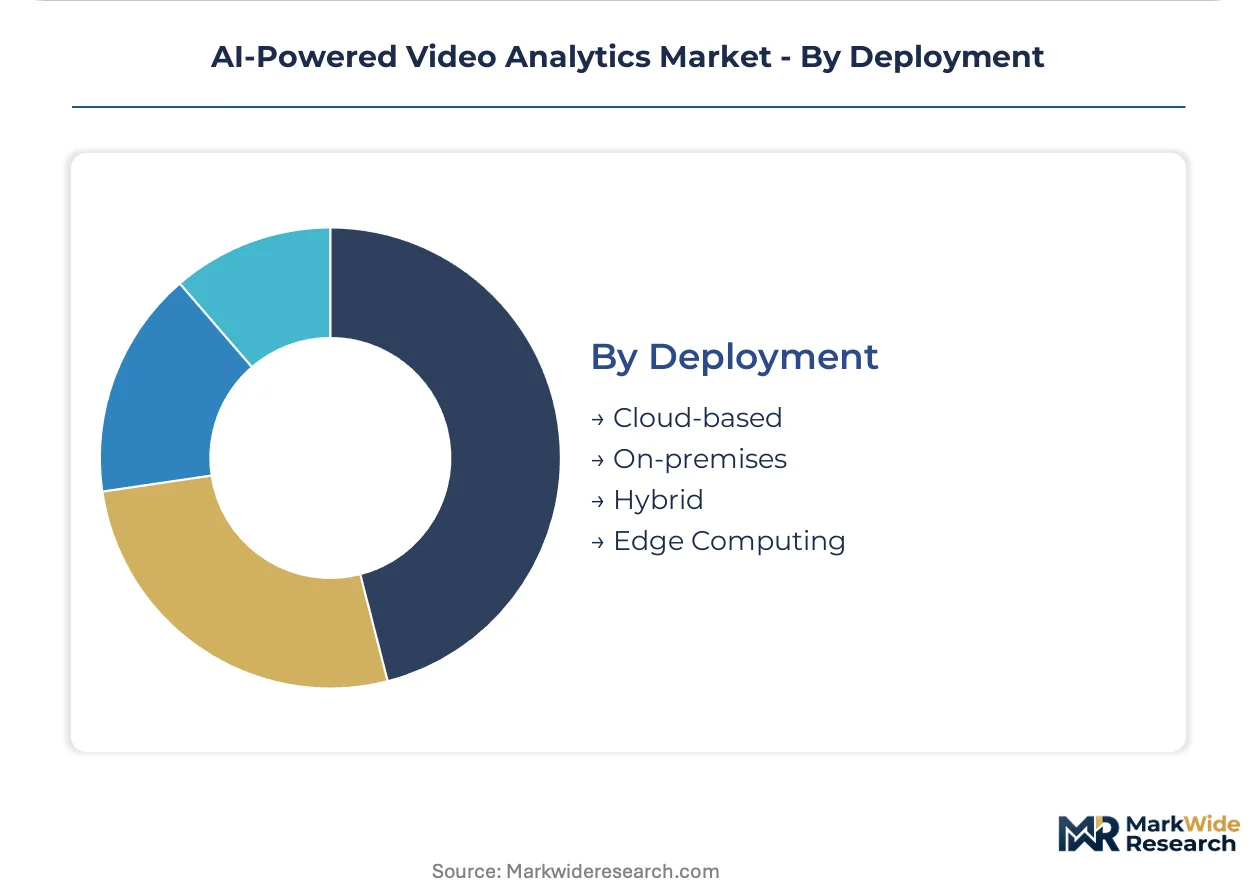
- Edge Computing:Onboard deep learning accelerators in network cameras reduce bandwidth costs and enable real-time inference without cloud dependency. Singapore's smart city infrastructure embeds these architectures in urban command centers.
- Cloud-based:Centralized model retraining and accuracy auditing support large retail chain deployments with demographic parity testing requirements.
- On-premises:Air-gapped installations serve critical infrastructure operators with strict data sovereignty mandates.
- Hybrid:Federated learning convergence with edge inference opens municipal contracts where data residency requirements previously blocked pure cloud solutions.
Edge Computing gains share fastest; Cloud-based retains scalability advantages for multi-site retail operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computer vision research originated in United States academic laboratories during the 1960s, with Stanford and MIT establishing foundational algorithms later commercialized through Silicon Valley venture capital. Industrial scaling migrated to East Asian manufacturing clusters during the 2010s as embedded inference hardware production concentrated in Taiwan and South Korea.
United States
The Department of Homeland Security mandates algorithmic transparency for facial recognition at aviation hubs, accelerating procurement for automated threat detection systems. The FAA coordinates with the TSA on passenger screening zone upgrades across Atlanta, Chicago, and Los Angeles airports. Silicon Valley clusters in San Jose and San Francisco anchor venture funding for edge-computing startups developing privacy-preserving architectures.
China
SAMR and NMPA are drafting national interoperability standards that will reshape export certification requirements for surveillance equipment manufacturers. The MIIT oversees intelligent video surveillance integration into smart city infrastructure across the Yangtze River Delta. Shenzhen and Hangzhou host dense concentrations of camera hardware fabricators pairing embedded inference chips with manufacturing scale.
Germany
The KBA and federal data protection authorities are implementing EU AI Act conformity assessment procedures for biometric identification systems in transportation applications. Industrial demand concentrates in Bavaria and Baden-Württemberg for factory-floor safety monitoring and quality control automation. Munich hosts specialized engineering firms developing temporal pattern recognition for multi-object tracking in automotive logistics.
Singapore
The national digital masterplan embeds real-time crowd analytics into urban command centers for event management and transit optimization. The Infocomm Media Development Authority regulates data residency requirements that favor edge computing architectures over cloud-dependent solutions. The one-north research corridor clusters computer vision engineering talent for Southeast Asian smart city export projects.
South Korea
MFDS and national standards bodies are certifying intelligent video surveillance systems for critical infrastructure protection. The Ministry of Land, Infrastructure and Transport pilots transformer-based vision models at complex Seoul intersections where occlusion degrades legacy convolutional neural network performance. Busan-Ulsan manufacturing zones produce deep learning accelerators for network camera integration.
AI-Powered Video Analytics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across compliance architecture sophistication and hardware-software integration depth. The vendor base organizes into three tiers: integrated platform providers maintaining unified security architectures, specialized edge-computing hardware manufacturers, and modular analytics software vendors licensing to third-party integrators. Dominant competitive moves include vertical integration into captive inference chip supply and strategic partnerships with municipal smart city procurement offices.
Within the integrated platform tier, Genetec Inc. and Axis Communications AB exemplify architecture approaches that embed third-party analytics modules within unified command interfaces. Hikvision Digital Technology anchors the hardware-integrated segment through manufacturing scale advantages in camera production paired with embedded processing capabilities. These three firms represent divergent strategic postures on the cloud-edge latency tradeoff that shapes municipal contract awards.
| Leading Market Players |
|---|
| Hikvision Digital Technology |
| Genetec Inc. |
| Axis Communications AB |
| Coram AI |
| Motorola Solutions |
| Bosch Security Systems |
| Dahua Technology |
| Eagle Eye Networks |
| Panasonic Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Federal transportation security mandates for algorithmic transparency documentation are forcing vendors to absorb compliance certification costs into pricing structures, compressing margins on facial recognition deployments while elevating premium tiers for edge-computing hardware with onboard inference capabilities.
Pricing Analysis
Subscription-based model retraining with separate accuracy auditing contracts now dominates municipal and large retail procurement, displacing bundled hardware-software packages. Price differentiation separates vendors with EU AI Act conformity assessment documentation from those lacking certified training data provenance. Cost compression in mid-tier surveillance systems is intensifying as Hikvision and Dahua manufacturing scale floods baseline camera markets. Transportation hub buyers show least price sensitivity due to federal mandate urgency, while smaller municipalities resist replacement cycles for rules-based legacy systems.
Supply Chain Analysis
China's SAMR and NMPA domestic-content requirements for intelligent video surveillance interoperability are reshaping sourcing patterns for export-bound manufacturers. Inference chip fabrication concentrates in Taiwan, South Korea, and mainland China, with GPU and NPU supply anchored in TSMC and Samsung foundry capacity. Raw material dependencies span silicon wafers, cobalt-based thermal management substrates, and precision optical lens assemblies. Single-source vulnerability in advanced node semiconductor production creates procurement timeline risk. Distribution runs through specialized security integrators and direct municipal procurement channels rather than commodity electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI-powered video analytics market functions as a stable compounder, with smart city infrastructure pipelines providing durable demand visibility across multi-year municipal budgeting cycles.
For Market Incumbents: Anchor platform stickiness through backward integration into captive inference chip supply, securing allocation priority during semiconductor supply constraints. Deepen certification investments for EU AI Act high-risk system conformity assessment to defend municipal contract win rates against modular software entrants. The threat of transformer-based vision model commoditization demands proprietary architecture differentiation. For New Entrants and Emerging Players: Cloud-native API distribution channels offer lowest-friction entry into retail analytics white space, where brick-and-mortar operators seek shelf-scanning and queue-management algorithms without legacy platform baggage. Target mid-size airport authorities in secondary US hubs where TSA mandate urgency outstrips incumbent sales cycle capacity. Lead with federated learning edge architectures that bypass data residency objections blocking pure-cloud competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-computing hardware specialists possessing camera manufacturing partnerships and embedded accelerator integration capabilities. The acquisition target archetype combines computer vision engineering depth with existing municipal smart city procurement relationships. Watch for inflection when national data protection authorities in Germany and France issue clarified EU AI Act implementation guidance triggering delayed procurement releases.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | Onboard deep learning accelerators in Axis cameras reduce bandwidth dependency for Singapore smart city deployments. |
| EU AI Act Conformity Certification | Dual product line maintenance for high-risk and limited-risk applications opens German municipal contracts pending BfDI guidance. |
| Retail Analytics API Platform Launch | Shelf-scanning algorithm marketplaces enable third-party validation contracts with US big-box retailers. |
| Strategic Partnership with Municipal Procurement | Direct relationships with Singapore IMDA accelerate urban command center embedded analytics adoption. |
| Acquisition of Computer Vision Specialist | Temporal pattern recognition expertise addresses multi-object tracking talent scarcity in traffic management pilots. |
Methodological Framework
Multiple input streams — primary interviews with municipal procurement officers, physical security integrators, and computer vision engineering leads; secondary validation through SEC filings of listed camera manufacturers, EU AI Act implementation guidance documents, and TSA procurement disclosure databases; plus customs data on embedded inference chip trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across deployment model, end-use vertical, and regional regulatory cluster dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from installed base replacement velocity and greenfield smart city infrastructure commitment tracking. Edge computing adoption curves and cloud-based model retraining subscription attach rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for transformer-based vision model deployment would alter the outlook if occlusion-handling performance gains accelerate beyond pilot program validation. Forecasts reflect assumptions around EU AI Act implementation timing and federal transportation security mandate funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Motion Simulation Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Europe Computational Fluid Dynamics Market