
 United States Computational Fluid Dynamics Market | 2026-2036
United States Computational Fluid Dynamics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Computational Fluid Dynamics Market Intelligence
Aftermarket service revenue is reconfiguring how CFD vendors capture lifetime value from enterprise accounts. ANSYS, Inc. leverages its multiphysics platform breadth to anchor long-term support contracts across automotive and energy clients. Altair Engineering Inc. competes through subscription pricing that lowers upfront barriers for mid-sized manufacturers. Autodesk, Inc. extends its design-to-simulation workflow integration to control the entry-level segment where CAD users first adopt CFD capabilities.
Computational Fluid Dynamics encompasses numerical methods and algorithms that solve the Navier-Stokes equations to analyze fluid flow, heat transfer, and related phenomena, typically requiring mesh resolutions from thousands to billions of cells depending on turbulence model fidelity. The discipline serves industrial purposes ranging from optimizing internal combustion engine efficiency to predicting wind loads on structures and thermal management in electronics. Software licensing commands the dominant margin pool as vendors shift from perpetual licenses toward recurring revenue, while cloud-based deployment grows fastest among academic institutions and government agencies that lack capital for on-premises HPC clusters. Aerospace application demand concentrates in jet engine combustion and aerodynamic drag reduction where physical prototyping costs remain prohibitive.
FAA airworthiness standards mandate extensive simulation documentation for certification of new aircraft designs, directly expanding CFD validation requirements for defense contractors and commercial aviation suppliers. NIST calibration protocols and DOE exascale computing initiatives shape benchmark expectations that vendors must meet to qualify for federal procurement. Stakeholders must weigh the trade-off between specialized physics solvers and platform consolidation as procurement teams consolidate vendor relationships.
Market Dynamics
Cloud-native solver architectures are compressing the capital barrier for high-fidelity turbulence modeling, forcing incumbent vendors to restructure licensing economics around consumption-based metering rather than perpetual seat sales.
Growth Catalysts
- FAA Airworthiness Directives:Certification mandates for jet engine combustor simulations expand validation workloads across defense contractors and Tier-1 aviation suppliers in Texas and California.
- Hypersonic vehicle programs:Government laboratories in New Mexico and Virginia demand elastic HPC capacity for scramjet thermal-structural coupling analysis that exceeds on-premises cluster limits.
- Digital twin integration:Automotive powertrain divisions embed real-time CFD feedback loops into engine control unit calibration pipelines, creating recurring simulation subscription demand.
Market Restraints
- GPU memory wall:Billion-cell LES meshes exceed current NVIDIA H100 memory capacity, forcing time-step decomposition that inflates wall-clock runtime by 40-60% for combustion applications.
- Specialized talent scarcity:Turbulence model developers with PhD-level expertise command compensation premiums that mid-sized engineering consultancies cannot sustain.
- On-premise HPC depreciation:DOE national laboratories face congressional pressure to decommission aging CPU clusters before amortization cycles complete, stranding capital for CFD-focused facilities.
Strategic Opportunities
- Rocky Mountain energy corridor:Wyoming and Colorado shale operators require multiphase flow simulation for carbon capture injection site characterization, a vertical with limited vendor penetration.
- AI-surrogate model convergence:Physics-informed neural networks trained on sparse high-fidelity data enable real-time optimization loops that complement traditional RANS solvers.
- Subscription pricing normalization:Altair's unit-based model demonstrates price elasticity among Great Lakes automotive suppliers previously excluded from enterprise licensing tiers.
Industry Challenges
- Legacy code base integration:Fortran-based in-house solvers at established aerospace primes resist containerization, delaying cloud migration timelines by 18-24 months.
- Verification and validation backlog:NIST uncertainty quantification standards require extensive benchmark documentation that consumes 30% of engineering hours on government contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Computational Fluid Dynamics Market |
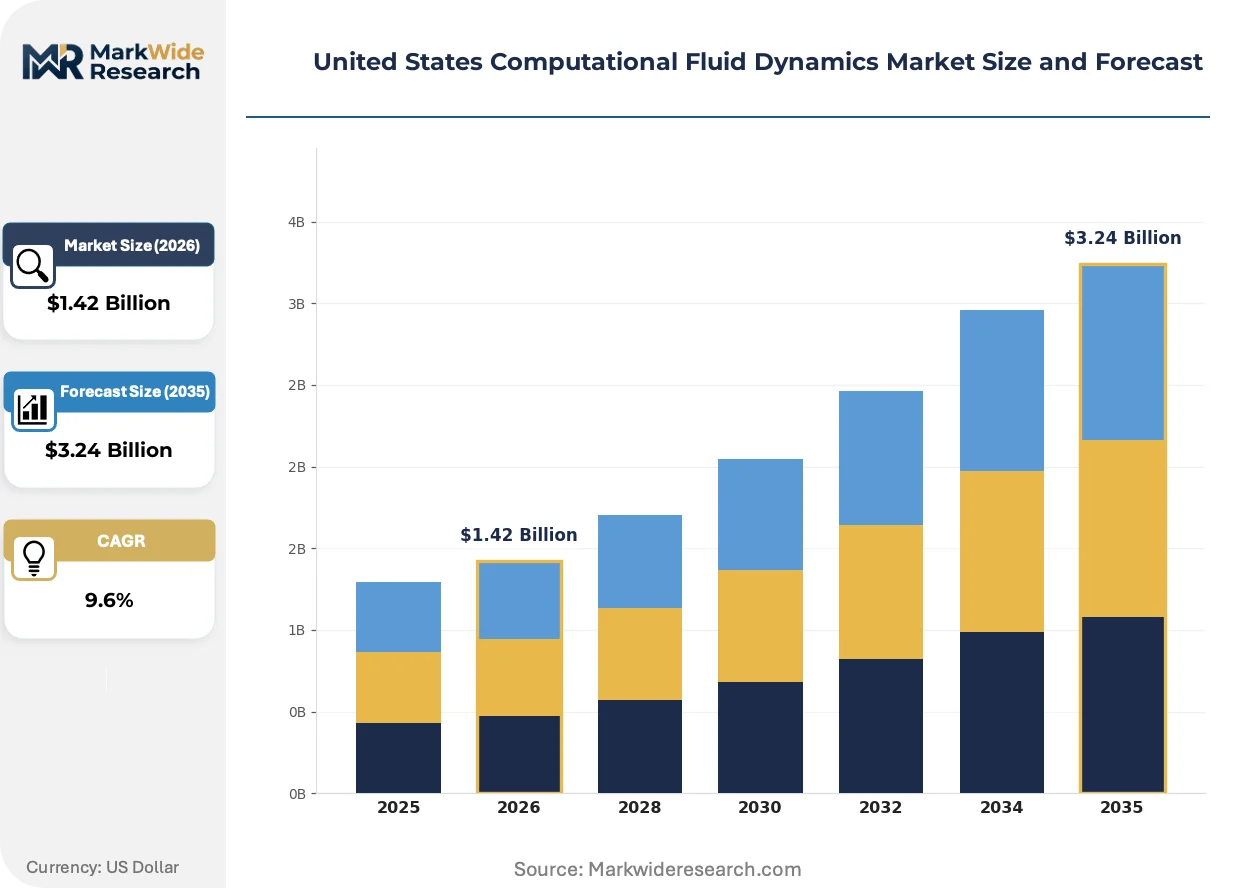
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Consulting Application: Aerospace, Automotive, Energy, Marine End User: Manufacturers, Academic Institutions, Government Agencies, Research Organizations Deployment: On-Premises, Cloud-Based, Hybrid, Local |
| Companies Covered | Flow Science, Altair Engineering Inc., M-Star Simulations, LLC, Azore Software, LLC, Autodesk, Inc., Kelco Industries, ANSYS, Inc., Airflow Sciences Corporation, CONVERGENT SCIENCE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Computational Fluid Dynamics Market Strategic Shifts & Innovations
GPU-accelerated lattice Boltzmann methods are compressing the trade-off between geometric fidelity and turnaround time, enabling design-space exploration that was computationally inaccessible under traditional finite-volume approaches.
Lattice Boltzmann solvers targeting automotive aerodynamics now resolve underhood thermal management with 10x faster wall-clock times than Reynolds-averaged Navier-Stokes implementations. Detroit-based OEMs deploy these tools for overnight design iterations during vehicle development sprints. The method is rendering obsolete the practice of reserving high-fidelity external aerodynamics for final validation phases only.
NIST calibration protocols for hypersonic vehicle simulation establish uncertainty quantification benchmarks that vendors must document to qualify for Air Force Research Laboratory procurement. Contractors in Ohio and Florida restructure validation workflows around these standards to secure SBIR funding. Small and mid-sized simulation shops without dedicated V&V staff face exclusion from defense contract pools.
Consumption-based licensing models displace perpetual seat sales as procurement teams prioritize operational expenditure treatment for simulation budgets. Government research laboratories in Tennessee and California lead this transition, negotiating enterprise-wide solver access rather than node-locked installations. The shift concentrates purchasing authority within central IT procurement functions and away from individual engineering managers.
United States Computational Fluid Dynamics Market Segmentation
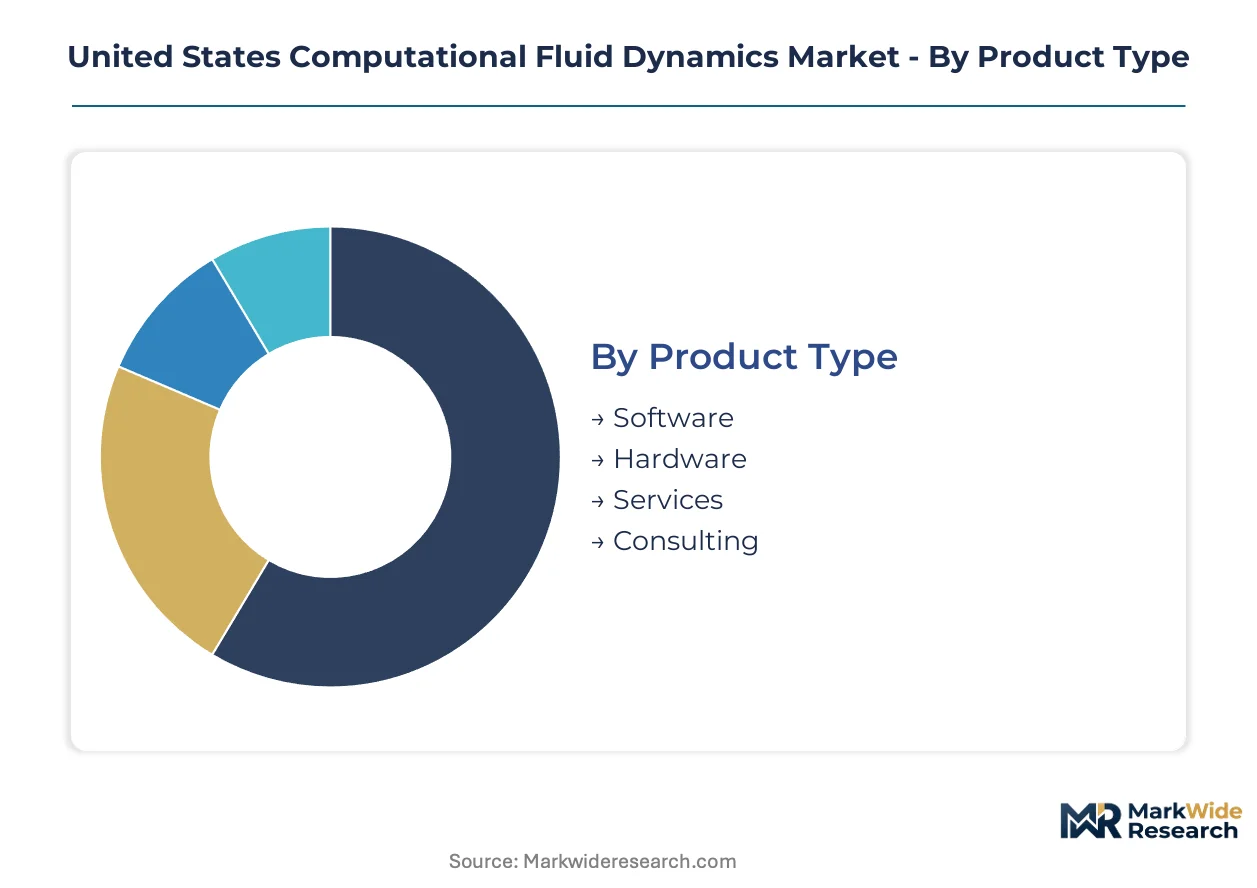
CFD procurement patterns diverge sharply across customer archetypes, with aerospace primes prioritizing perpetual licenses for classified workloads while academic institutions drive cloud adoption for elastic compute access. Deployment choices directly constrain solver fidelity and validation protocols, making segmentation mapping essential for vendor resource allocation.
Product Type:
Cost tier stratification determines margin capture and customer lifetime value trajectories across the software-to-services spectrum.
- Software:Licensing encompasses solver suites, meshing tools, and post-processing visualization platforms with turbulence model libraries. Aerospace manufacturers in Texas and California anchor demand here, compelled by FAA airworthiness directives requiring documented Navier-Stokes validation for jet engine certification.
- Services:Managed simulation workflows and outsourced HPC burst capacity address talent scarcity at mid-sized engineering consultancies. Government laboratories in New Mexico purchase these offerings to circumvent GPU memory limitations for billion-cell hypersonic meshes.
- Hardware:GPU clusters and high-bandwidth interconnects for on-premise turbulence modeling.
- Consulting:Physics-informed model development and uncertainty quantification documentation.
Software holds installed capacity. Services is rotating up the share rankings.
Application:
End-use physics complexity governs pricing power and renewal rates across industrial verticals.
- Aerospace:Combustor simulation and aerodynamic drag reduction dominate validation workloads. Defense contractors face NIST uncertainty quantification mandates that consume engineering hours but secure SBIR eligibility.
- Automotive:Powertrain thermal management and external aerodynamics drive lattice Boltzmann adoption. Detroit OEMs deploy overnight design iterations for underhood cooling optimization.
- Energy:Multiphase flow simulation for carbon capture injection site characterization in Wyoming and Colorado shale formations.
- Marine:Hull hydrodynamics and cavitation prediction for naval architecture applications.
Aerospace holds installed capacity. Automotive is rotating up the share rankings.
End User:
Customer procurement authority and budget treatment create divergent sales motion requirements.
- Government Agencies:DOE national laboratories and Air Force Research Laboratory facilities negotiate enterprise-wide solver access with operational expenditure treatment. Congressional pressure on HPC depreciation cycles accelerates cloud migration timelines.
- Academic Institutions:Universities lacking capital for on-premises clusters drive consumption-based licensing growth fastest among all customer types.
- Manufacturers:Automotive and energy producers embedding real-time CFD into digital twin pipelines.
- Research Organizations:Federally funded centers pursuing exascale computing benchmarks.
Government Agencies hold installed capacity. Academic Institutions is rotating up the share rankings.
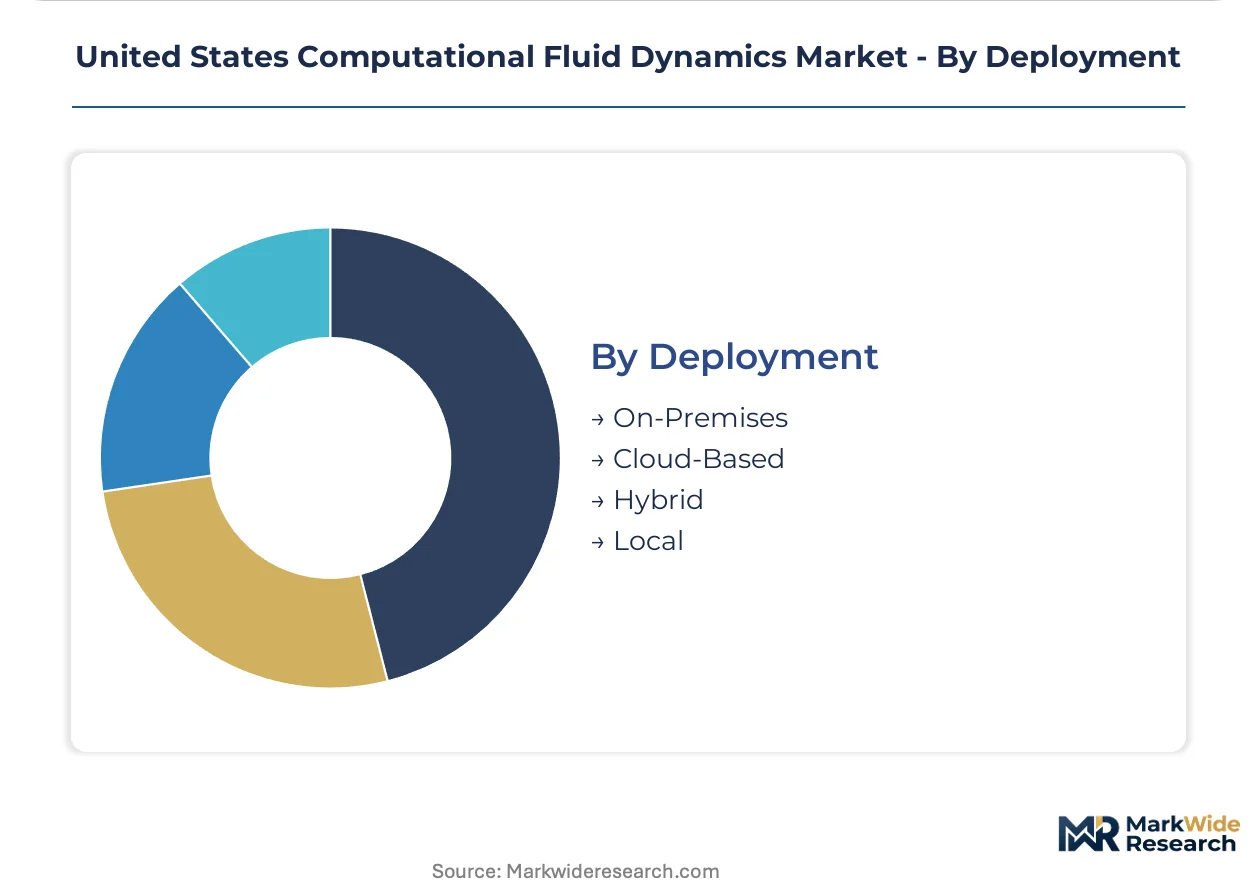
Deployment:
Infrastructure location relative to sensitive data governs security clearance eligibility and solver architecture choices.
- Cloud-Based:Elastic HPC capacity enables scramjet thermal-structural coupling analysis exceeding on-premises limits. Tennessee and California laboratories lead this transition, consolidating purchasing authority within central IT procurement.
- On-Premises:Air-gapped installations remain mandatory for classified defense workloads and ITAR-controlled simulations. Legacy Fortran-based solvers at established primes resist containerization, delaying migration by 18-24 months.
- Hybrid:Burst capacity to cloud for peak validation workloads with sensitive preprocessing on-premise.
- Local:Workstation-class deployments for entry-level CAD-integrated simulation.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CFD software development and high-performance computing infrastructure concentrate along three distinct corridors: defense-aerospace clusters in the Southwest, automotive engineering centers in the Midwest, and government research facilities spanning the Mountain West and Southeast. Each corridor exhibits divergent procurement patterns shaped by security clearance requirements, legacy system dependencies, and cloud migration timelines.
Texas
Defense contractors in the Dallas-Fort Worth and Houston corridors drive demand for ITAR-compliant on-premise installations. FAA airworthiness directives mandate extensive jet engine combustor simulation documentation, expanding validation workloads at Lockheed Martin and Raytheon facilities. The state hosts the nation's densest concentration of classified CFD workloads requiring air-gapped HPC clusters.
California
Commercial aerospace manufacturers and Silicon Valley cloud providers shape hybrid deployment architectures. SpaceX and Northrop Grumman facilities in Hawthorne and Redondo Beach balance sensitive defense work with elastic cloud burst capacity for non-classified thermal modeling. DOE Lawrence Livermore National Laboratory exascale initiatives establish benchmark standards that vendors must meet for federal qualification.
Michigan
Detroit-based OEMs anchor automotive CFD adoption, deploying lattice Boltzmann solvers for overnight underhood thermal design iterations. Ford and General Motors powertrain divisions embed real-time simulation feedback into engine control unit calibration pipelines. The state's engineering talent pool supports the highest density of digital twin integration projects among Great Lakes manufacturing regions.
New Mexico
Air Force Research Laboratory and Sandia National Laboratories demand elastic HPC capacity for scramjet thermal-structural coupling analysis exceeding on-premises cluster limits. Government research facilities here lead cloud-native solver adoption, negotiating enterprise-wide consumption-based licensing rather than node-locked installations. Congressional pressure on HPC depreciation cycles accelerates migration timelines relative to other DOE laboratory systems.
Virginia
Northern Virginia defense contractors and Hampton Roads aerospace suppliers face NIST uncertainty quantification mandates consuming substantial engineering documentation hours. Small and mid-sized simulation shops without dedicated verification and validation staff confront exclusion from SBIR funding pools. The state's proximity to Pentagon procurement offices concentrates federal contract capture activity.
United States Computational Fluid Dynamics Market Key Industry Players
Multiphysics platform vendors and specialized solver developers split the market between consolidation momentum and niche persistence. The vendor base exhibits moderate concentration, with three to four firms capturing dominant share in enterprise aerospace and automotive accounts while dozens of smaller specialists serve vertical-specific physics requirements. Two strategic archetypes predominate: breadth-focused platform consolidators leveraging post-acquisition integration, and depth-focused physics specialists commanding premium pricing for combustion or particle-laden flow applications. Competitive moves center on consumption-based licensing restructuring and GPU-native solver architecture development.
Among platform consolidators, ANSYS, Inc. and Autodesk, Inc. exemplify the breadth archetype through multiphysics integration and design-to-simulation workflow control. Altair Engineering Inc. occupies a distinct position with unit-based subscription pricing that lowers upfront barriers for mid-sized manufacturers previously excluded from enterprise tiers. These three firms anchor the competitive dynamic, with specialized developers like Flow Science and CONVERGENT SCIENCE representing the depth-focused alternative for combustion and internal engine flow applications.
| Leading Market Players |
|---|
| Flow Science |
| Altair Engineering Inc. |
| M-Star Simulations, LLC |
| Azore Software, LLC |
| Autodesk, Inc. |
| Kelco Industries |
| ANSYS, Inc. |
| Airflow Sciences Corporation |
| CONVERGENT SCIENCE |
| Others |
Cost & Logistics Intelligence
Single-source dependency on NVIDIA GPU architectures compresses pricing tier spreads while forcing supply chain consolidation around H100 and successor chip allocations. FAA certification mandates for jet engine simulation documentation anchor premium pricing for validated solver suites, while academic cloud consumption normalizes entry-level subscription economics.
Pricing Analysis
FAA airworthiness directives dictate the pricing tier structure across defense contractor procurement. Three-tier pricing structure across perpetual licenses, subscription SaaS, and consumption-based cloud metering separates aerospace primes from mid-tier automotive suppliers and academic institutions. Price differentiation hinges on turbulence model fidelity certification and NIST validation documentation depth. Cost compression in cloud-native solver tiers intensifies because GPU memory limitations force time-step decomposition workarounds. Academic institutions exhibit highest price sensitivity; defense primes with SBIR eligibility demonstrate lowest sensitivity due to pass-through federal funding.
Supply Chain Analysis
Upstream semiconductor feedstock concentration in Taiwan, South Korea, and the United States governs HPC cluster availability for on-premise deployments. NVIDIA GPU wafers, high-bandwidth memory modules, and InfiniBand interconnects constitute critical input dependencies. Single-source vulnerability around TSMC advanced node production creates procurement chokepoints for billion-cell LES mesh hardware. Distribution runs through direct OEM relationships for defense contractors and hyperscaler marketplaces for cloud-native academic access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States CFD market sits in a cyclical recovery phase driven by hypersonic vehicle program budget expansion and DOE exascale computing initiative acceleration.
For Market Incumbents: Build switching-cost moats through deep integration of lattice Boltzmann solvers into Detroit OEM digital twin pipelines. Incumbents should anchor long-term support contracts with multiphysics platform bundling to counter GPU-native entrant disruption. Certification investment in NIST uncertainty quantification documentation secures SBIR eligibility moats against mid-sized simulation shops lacking dedicated V&V staff. For New Entrants and Emerging Players: Build out physics-informed neural network surrogate models for real-time optimization loops in automotive powertrain calibration. The Rocky Mountain energy corridor presents the most penetrable vertical, with Wyoming and Colorado shale operators requiring multiphase flow simulation for carbon capture site characterization where vendor penetration remains limited. A consumption-based unit pricing go-to-market angle mirrors Altair's demonstrated elasticity success among Great Lakes mid-tier manufacturers. For Investors and Strategic Acquirers: The market sits at an infrastructure refresh phase that favors GPU-native solver architecture specialists over legacy Fortran code bases. Long-term viability over a five-to-ten-year window hinges on cloud-native containerization capability and AI-surrogate model convergence. Acquisition targets should demonstrate elastic HPC burst capacity provisioning. The signal to watch is congressional HPC depreciation pressure accelerating DOE laboratory cloud migration timelines beyond the 18-24 month legacy resistance window.| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Native Solver Architecture Development | NVIDIA H100 memory wall constraints favor native architectures over ported legacy code bases. |
| Consumption-Based Licensing Transition | Tennessee and California DOE laboratories lead operational expenditure treatment negotiations. |
| AI-Surrogate Model Integration | Physics-informed neural networks enable real-time optimization loops complementing RANS solvers. |
| Vertical Integration into HPC Burst Capacity | Managed simulation workflows address GPU memory limitations for billion-cell hypersonic meshes. |
| NIST Validation Documentation Investment | Uncertainty quantification benchmarks secure SBIR eligibility for defense contract capture. |
Research Approach
Cross-validation between primary interviews with CFD software product managers, aerospace engineering directors, DOE laboratory procurement officers, and automotive powertrain simulation leads anchors the qualitative findings. Secondary validation draws from FAA airworthiness directive filings, DOE exascale computing initiative disclosures, NIST calibration protocol documentation, and hyperscaler HPC capacity expansion announcements. Bottom-up solver deployment counts triangulate against top-down software licensing revenue estimates across the analysis window.
Calibration against historical CAGRs from adjacent simulation software markets informs the projection horizon. Segmentation dimensions modeled encompass deployment architecture, end-user procurement authority, application physics complexity, and turbulence model fidelity tier. CAGRs derive from elasticity-adjusted adoption curves incorporating GPU memory constraint impacts and cloud migration timeline acceleration. Industry-specific inputs include hypersonic program budget allocations and Detroit OEM digital twin integration roadmaps.
Stress conditions across congressional HPC depreciation pressure, NVIDIA supply allocation volatility, and FAA certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud-native solver adoption velocity and AI-surrogate model technical maturation. Cross-checking against DOE laboratory procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Process Analyzer Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
Europe Computational Fluid Dynamics Market