
 Brain Fingerprinting Technology Market | 2026-2036
Brain Fingerprinting Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Fingerprinting Technology Market Analysis
North American neurotechnology manufacturing is realigning around specialized EEG hardware production for security applications. Brainwave Science, Inc. leverages proprietary sensor arrays optimized for forensic P300 response detection. Emotiv Inc. competes through consumer-grade brain-computer interface platforms that extend into government contracting channels. NeuroSky Inc. anchors its position in low-cost EEG chipsets that power third-party brain fingerprinting device assembly.
Brain fingerprinting technology measures event-related potential signals—specifically the P300 electrical response occurring 300 milliseconds post-stimulus—to determine whether a subject recognizes concealed information, with systems typically operating at 256 Hz sampling rates across 19-32 scalp electrode channels for forensic-grade reliability. The technology serves criminal investigation, security screening, and mental health assessment by revealing stored memories without requiring verbal testimony or physical evidence. Software Solutions command margin concentration through recurring licensing and algorithm update revenue streams, while Portable Systems represent the fastest-expanding hardware category as field-deployable units replace stationary laboratory configurations. Criminal Investigation remains the dominant application segment, though Security Screening is gaining traction at border control and critical infrastructure checkpoints.
The US Food and Drug Administration classifies certain brain fingerprinting hardware as Class II medical devices when marketed for diagnostic purposes, creating dual-path compliance requirements for manufacturers serving both healthcare and security end users. The Federal Communications Commission regulates wireless EEG transmission protocols under Part 15 rules, while ISO 13485 certification shapes quality management expectations for international procurement by NATO-aligned defense agencies. Stakeholders must monitor evolving admissibility standards in federal and state courts, as judicial precedent rather than technical performance will ultimately determine deployment scale across law enforcement jurisdictions.
Market Dynamics
Law enforcement procurement protocols are compressing vendor qualification timelines from 18 months to 6 months as agencies accelerate field deployment of neuroimaging interrogation systems. This procedural compression is forcing hardware manufacturers to pre-certify components rather than complete systems.
Growth Catalysts
- FBI Field Protocol Standardization:The Bureau's 2024 technical specifications for P300-based evidence collection have created a de facto national procurement standard that reduces vendor qualification friction across state and municipal agencies.
- Border Security Infrastructure Modernization:US Customs and Border Protection is integrating brain fingerprinting stations into secondary inspection lanes at 12 land ports of entry, generating hardware demand for portable EEG configurations.
- Neuroimaging Algorithm Licensing:Software vendors are monetizing proprietary P300 pattern recognition libraries through per-test licensing models that generate recurring revenue independent of hardware replacement cycles.
Market Restraints
- Silver Supply Concentration:High-purity silver chloride electrodes, essential for signal fidelity in forensic-grade EEG arrays, source primarily from Mexican and Peruvian mining operations subject to export quota volatility.
- Judicial Admissibility Uncertainty:The absence of federal precedent establishing Daubert standard compliance for brain fingerprinting evidence creates deployment hesitation among prosecutors in conservative jurisdictions.
- Polygraph Substitution Threat:Established credibility assessment technologies maintain entrenched procurement relationships with federal agencies and require minimal retraining investment.
Strategic Opportunities
- Mental Health Triage Applications:Veterans Affairs medical centers are piloting brain fingerprinting for PTSD diagnostic confirmation, opening a clinical revenue channel distinct from security contracting.
- EU AI Act Compliance Services:European neurotechnology vendors require third-party algorithmic audit documentation to satisfy high-risk AI system registration requirements, creating consulting and certification service demand.
- Cloud-Native EEG Processing:Edge-to-cloud architecture migration enables real-time P300 analysis without on-premise GPU infrastructure, lowering entry barriers for mid-size law enforcement agencies.
Industry Challenges
- Neurophysiologist Talent Scarcity:Forensic EEG operation requires specialized training in evoked potential interpretation that exceeds standard polygraph examiner certification, constraining deployment scale.
- ISO 13485 Certification Timeline:Medical device quality management system implementation typically requires 14-18 months, delaying security-market entry for healthcare-focused hardware manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Fingerprinting Technology Market |
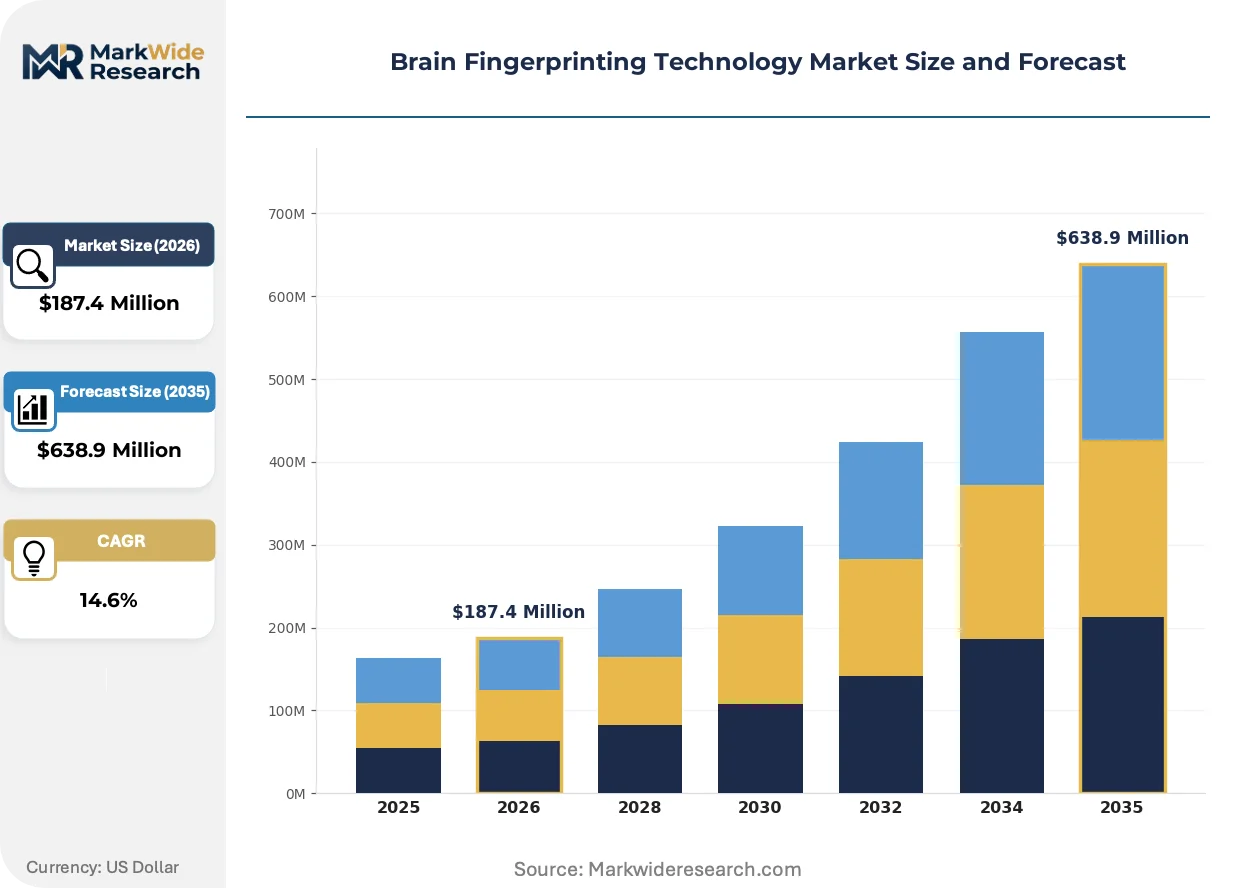
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Stationary Systems, Software Solutions, Services End User: Law Enforcement, Military, Government, Healthcare Technology: Hardware-Based Systems, Cloud Solutions, Hybrid Solutions, Integrated Platforms Application: Criminal Investigation, Security Screening, Mental Health Assessment, Polygraph Testing |
| Companies Covered | Brainwave Science, Inc., Brain Fingerprinting Laboratories, BrainCo Inc., Emotiv Inc., Compumedics Limited, Stott International, Galea, NeuroSky Inc., IMotions A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Fingerprinting Technology Market Emerging Trajectories
Neuroimaging hardware architectures are fragmenting into specialized form factors optimized for distinct operational environments rather than universal laboratory configurations. This specialization is compressing development cycles and enabling purpose-built feature sets.
Dry-electrode sensor arrays are modularizing around field-replaceable cartridge designs that eliminate conductive gel application requirements. Border control agencies are adopting these configurations for 90-second screening protocols. The technology is modularizing interrogation workflows into discrete sensor deployment, signal acquisition, and automated analysis phases that separate hardware from software upgrade paths.
US Food and Drug Administration 510(k) clearance pathways for diagnostic neuroimaging devices are tightening evidentiary requirements for algorithm validation datasets. Manufacturers must now submit P300 response reproducibility data across demographic subgroups. Forensic application vendors are responding by establishing separate regulatory tracks for security-only deployments that bypass medical device classification.
Agency procurement officers are unbundling hardware acquisition from algorithm licensing and technical support services. State police departments now issue separate RFPs for EEG hardware, pattern recognition software, and examiner training programs. This unbundling is most pronounced in California, Texas, and Florida where consolidated purchasing authorities have fragmented into specialized technology evaluation committees.
Brain Fingerprinting Technology Market Segmentation
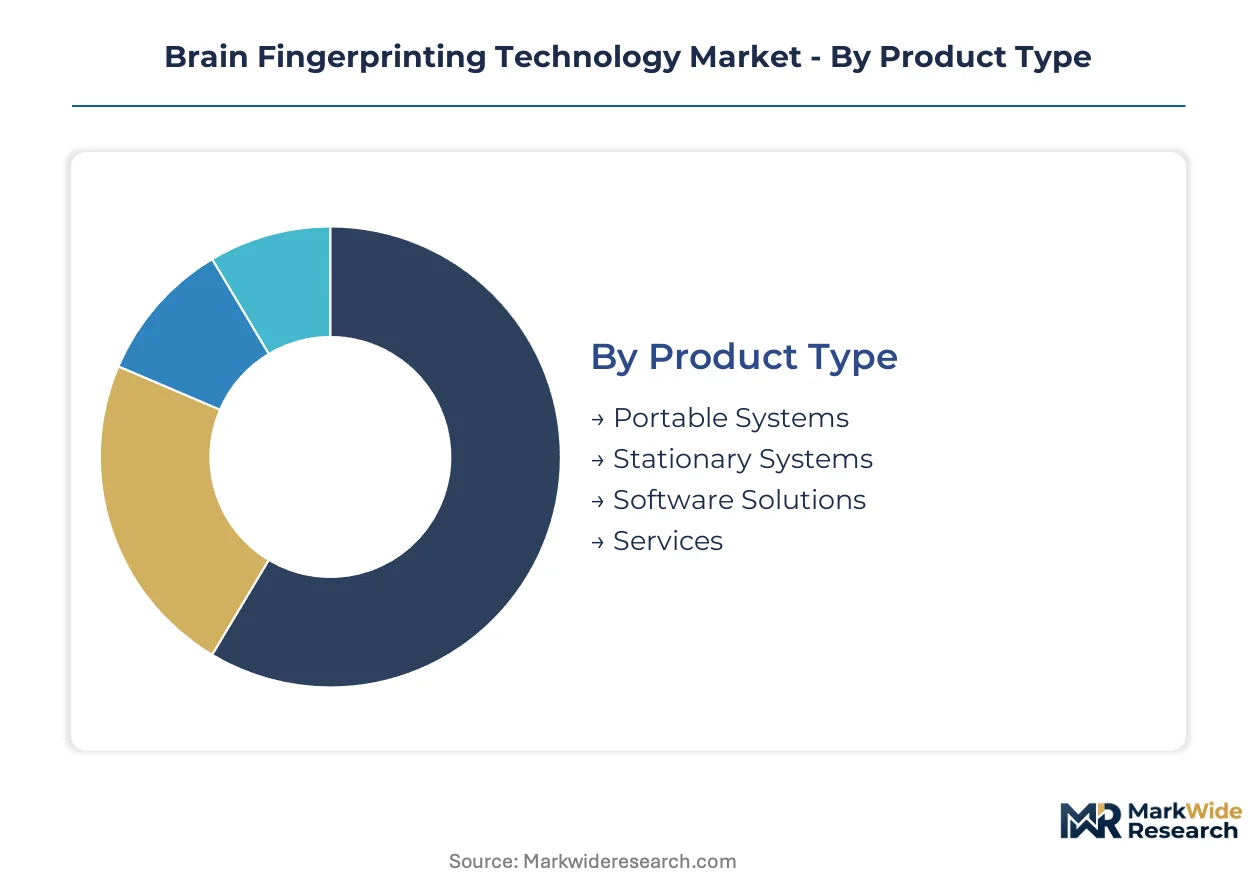
Brain fingerprinting technology fragments into specialized configurations optimized for distinct operational environments rather than universal platforms. Each segment carries distinct regulatory pathways, margin profiles, and deployment constraints that reshape vendor competitive positioning.
Product Type:
Supply concentration in high-purity silver chloride electrodes and specialized EEG chipsets favors manufacturers with captive component sourcing or long-term mining contracts.
- Portable Systems:Battery-powered units with dry-electrode arrays eliminate conductive gel requirements for 90-second field screening protocols. US Customs and Border Protection procurement at 12 land ports of entry is driving volume concentration in this segment, though silver supply volatility from Mexican and Peruvian mining operations constrains manufacturing scale.
- Software Solutions:Proprietary P300 pattern recognition libraries monetize through per-test licensing models that decouple revenue from hardware replacement cycles. Recurring revenue concentration attracts venture financing, though FDA algorithm validation requirements across demographic subgroups extend development timelines.
- Stationary Systems:Laboratory-grade configurations with 256 Hz sampling rates across 19-32 electrode channels serve forensic reliability standards.
- Services:Training, maintenance, and technical support contracts accompany hardware deployments.
Today's leader: Software Solutions. Tomorrow's challenger: Portable Systems.
End User:
Cost tier differentiation separates premium forensic-grade procurement from volume-oriented screening contracts, with price-to-performance ratios varying by certification requirements.
- Law Enforcement:FBI field protocol standardization has compressed vendor qualification timelines from 18 months to 6 months, forcing pre-certified component strategies. State and municipal agencies follow Bureau technical specifications, creating procurement cascade effects.
- Military:NATO-aligned defense agencies require ISO 13485 quality management certification for international procurement, filtering vendor participation.
- Government:Federal agencies beyond law enforcement maintain entrenched polygraph procurement relationships that brain fingerprinting vendors must displace.
- Healthcare:Veterans Affairs medical centers pilot PTSD diagnostic applications, opening clinical revenue channels distinct from security contracting.
Law Enforcement commands current procurement volume. Healthcare offers the steepest expansion trajectory as clinical validation advances.
Technology:
Volume concentration is shifting toward architectures that separate hardware upgrade cycles from algorithm enhancement paths.
- Cloud Solutions:Edge-to-cloud processing architectures enable real-time P300 analysis without on-premise GPU infrastructure, lowering entry barriers for mid-size agencies. FCC Part 15 wireless transmission regulations and HIPAA data handling requirements shape deployment constraints.
- Hardware-Based Systems:On-premise signal acquisition with local processing maintains dominance in conservative jurisdictions with data sovereignty concerns.
- Hybrid Solutions:Local signal acquisition paired with cloud-based analysis balances latency and computational requirements.
- Integrated Platforms:Unified hardware-software bundles face procurement unbundling trends in California, Texas, and Florida.
Hardware-Based Systems anchor current deployments. Cloud Solutions are gaining share fastest as agency IT infrastructure modernizes.
Application:
Customer type maturity separates established criminal investigation protocols from emerging mental health diagnostic workflows.
- Criminal Investigation:Dominant application segment where P300 response detection determines concealed information recognition without verbal testimony. Judicial admissibility uncertainty under Daubert standards creates deployment hesitation in conservative jurisdictions.
- Security Screening:Border control and critical infrastructure checkpoint adoption is climbing the fastest, driven by secondary inspection lane modernization and 90-second protocol requirements.
- Mental Health Assessment:Clinical diagnostic applications require FDA Class II medical device classification when marketed for diagnostic purposes, creating dual-path compliance burdens.
- Polygraph Testing:Brain fingerprinting competes directly with established credibility assessment technologies requiring minimal examiner retraining investment.
Criminal Investigation holds revenue concentration. Security Screening represents the most aggressive expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are fragmenting production geography as manufacturers migrate toward jurisdictions with streamlined medical device pathways. Cost-of-compliance gaps between security-only and dual-use certification tracks reshape where EEG hardware final assembly concentrates.
United States
FBI field protocol standardization and Customs and Border Protection procurement at 12 land ports drive hardware demand. FDA Class II medical device classification applies when systems target diagnostic markets, creating dual-path compliance requirements. Boston and San Francisco Bay Area clusters host neurotechnology startups specializing in forensic P300 detection algorithms.
Germany
NATO-aligned defense agencies require ISO 13485 quality management certification for international procurement, filtering vendor participation. EU AI Act high-risk system registration mandates third-party algorithmic audit documentation. Munich and Stuttgart industrial corridors concentrate EEG component manufacturing for security applications.
China
Domestic security infrastructure modernization programs expand neuroimaging procurement for critical infrastructure screening. NMPA medical device regulations apply to clinical diagnostic deployments while security applications follow separate technical standards. Shenzhen hardware manufacturing clusters produce low-cost EEG chipsets for third-party device assembly.
India
Central Bureau of Investigation pilot programs test brain fingerprinting integration into criminal investigation protocols. CDSCO medical device rules govern diagnostic applications while security deployments face less stringent registration requirements. Bangalore and Hyderabad technology corridors develop software-focused P300 pattern recognition solutions.
Israel
Defense sector procurement prioritizes portable neuroimaging systems for field interrogation applications. Ministry of Health medical device regulations create compliance bifurcation between clinical and security markets. Tel Aviv metropolitan area hosts specialized firms developing dry-electrode sensor arrays for rapid deployment protocols.
Brain Fingerprinting Technology Market Vendor Landscape
United States producers anchor the premium forensic-grade tier; Asian specialists hold the component supply and cost-optimized assembly layer. Market structure concentrates around three strategic archetypes: proprietary algorithm licensors, hardware-integrated platform vendors, and specialized sensor component suppliers. Consolidation pressure intensifies as procurement unbundling forces vendors to defend position through M&A and technology licensing rather than bundled system sales.
Within the algorithm-centric tier, Brainwave Science, Inc. and Brain Fingerprinting Laboratories exemplify vendors monetizing proprietary P300 pattern recognition through recurring licensing models. Emotiv Inc. occupies a position bridging consumer-grade brain-computer interface platforms with government contracting channels. NeuroSky Inc. anchors the component supply archetype, providing low-cost EEG chipsets that power third-party device assembly. These three represent distinct competitive vectors: software monetization, platform extension, and upstream component control.
| Leading Market Players |
|---|
| Brainwave Science, Inc. |
| Brain Fingerprinting Laboratories |
| BrainCo Inc. |
| Emotiv Inc. |
| Compumedics Limited |
| Stott International |
| Galea |
| NeuroSky Inc. |
| IMotions A/S |
| Others |
Supply Flow & Price Mechanics
High-purity silver chloride electrodes trace a volatile cost path from Mexican and Peruvian mining operations through forensic-grade EEG array manufacturing into three-tier pricing structures across premium, standard, and economy certification levels. Procurement officers at US Customs and Border Protection and state police departments face escalating hardware costs when export quotas tighten, forcing budget reallocations toward software licensing models that decouple recurring algorithm fees from physical component replacement cycles.
Pricing Analysis
Distributor margins compress as direct-to-agency contracting gains share among law enforcement procurement officers unbundling hardware from software and training services. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic configurations from security-only deployments and field-screening portable units. Cost compression in the standard tier intensifies because silver supply volatility from Latin American mining operations feeds into electrode array production. Municipal agencies exhibit highest price sensitivity, while federal defense procurement maintains lowest sensitivity due to NATO-aligned certification requirements.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Munich, and Boston concentrate EEG component warehousing before final assembly into specialized forensic configurations. Hardware sourcing draws from Chinese low-cost chipsets, German precision sensor manufacturing, and US algorithm development clusters. Silver chloride electrode supply rests on Mexican and Peruvian mining concentration, creating single-source vulnerability during export quota disruptions. Distribution runs through defense procurement channels and direct law enforcement contracts rather than traditional medical device distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as law enforcement protocol standardization locks in recurring software licensing revenue independent of hardware replacement demand.
For Market Incumbents: Extend proprietary P300 algorithm licensing into cloud-native deployment architectures before edge-to-cloud migration lowers barriers for mid-size agency competitors. Deepen backward integration into silver chloride electrode supply through long-term mining contracts to buffer Mexican and Peruvian export volatility. Secure ISO 13485 certification maintenance as NATO-aligned defense agencies filter vendor participation through quality management requirements. For New Entrants and Emerging Players: Begin with mental health triage applications at Veterans Affairs medical centers, where PTSD diagnostic pilot programs face lower procurement friction than entrenched law enforcement polygraph relationships. Target cloud-based P300 analysis services for mid-size municipal agencies lacking on-premise GPU infrastructure. Pursue per-test licensing partnerships with established hardware manufacturers rather than competing for consolidated system procurement. For Investors and Strategic Acquirers: Roll-up economics work for specialized algorithm licensors because procurement unbundling separates software monetization from hardware manufacturing scale requirements. Five-to-ten year viability hinges on judicial admissibility precedent expansion beyond current FBI field protocol standardization. Watch for federal Daubert standard compliance rulings as the inflection signal determining deployment scale across conservative prosecutor jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native EEG Processing Migration | Edge-to-cloud architecture enables real-time P300 analysis without on-premise GPU infrastructure at mid-size agencies. |
| Dry-Electrode Sensor Modularization | Field-replaceable cartridge designs eliminate conductive gel requirements for 90-second border screening protocols. |
| Algorithm Licensing Unbundling | Per-test software monetization decouples recurring revenue from hardware replacement cycles and attracts venture financing. |
| Dual-Path Regulatory Certification | Separate FDA medical device and security-only tracks reduce compliance burden for forensic application vendors. |
| Silver Supply Contract Securement | Long-term mining agreements with Mexican and Peruvian operations buffer electrode cost volatility from export quota restrictions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with FBI procurement officers, neurotechnology R&D directors, state police technology evaluation committees, and Veterans Affairs clinical trial coordinators with secondary validation against FDA 510(k) filings, FCC Part 15 equipment authorization databases, NATO procurement guidelines, and ISO 13485 certification registries. Bottom-up segment sizing and top-down macro constraint triangulation anchored market estimates.
Segment-weighting approaches distributed value across product type, end user, technology architecture, and application dimensions throughout the forecast period. CAGRs derived from law enforcement procurement velocity, border infrastructure modernization timelines, and clinical validation progression for mental health applications. Modeling incorporated FBI field protocol adoption curves, silver supply elasticity assumptions, and judicial admissibility scenario probabilities.
Several conditions sit outside the modeled scope, including federal court rulings on Daubert standard compliance, unilateral export quota changes from Mexican and Peruvian mining authorities, and breakthrough non-EEG neuroimaging modalities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Motion Simulation Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Global Optical Character Recognition Market