
 Digital Smell Technology Market | 2026-2036
Digital Smell Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Smell Technology Market Insights
Project finance for sensor fabrication facilities is tilting competitive dynamics toward capital-efficient players with modular cleanroom strategies. Aryballe Technologies leverages photonic biosensor architectures to sustain R&D intensity in volatile organic compound detection. Siemens anchors industrial automation demand through its process control integration capabilities, while Sensirion AG specializes in miniaturized gas sensor modules for consumer device embedding.
Digital smell technology encompasses hardware and software systems that detect, analyze, digitize, and reproduce odor signatures using arrays of chemical sensors coupled with pattern recognition algorithms, typically achieving detection thresholds in parts-per-billion concentration ranges for target analytes. These systems serve industrial quality assurance, environmental monitoring, immersive entertainment, and diagnostic healthcare applications by translating volatile molecular information into machine-readable data streams. Electronic nose platforms currently dominate commercial deployment due to their maturity in food safety and pharmaceutical quality control workflows, while olfactory displays represent the fastest-expanding segment as virtual reality headsets integrate scent emission hardware. Sensor networks command premium margin pools in smart city and industrial IoT deployments where distributed monitoring architectures replace single-point measurement systems.
The FDA regulates medical diagnostic applications of digital olfaction systems through its in vitro diagnostic device framework, while REACH and RoHS constrain material selection for European-manufactured sensor components. ISO standards for electronic nose performance validation provide cross-border interoperability benchmarks that reduce market access friction for certified device manufacturers. Stakeholders must monitor convergence between AI Act transparency requirements and sensor algorithm opacity as regulatory scrutiny intensifies around machine-learning-driven odor classification systems.
Market Dynamics
Photonic biosensor architectures are compressing detection thresholds while REACH and EU AI Act compliance requirements force material transparency across sensor supply chains, restructuring competitive positioning toward capital-efficient modular fabrication.
Growth Catalysts
- REACH-compliant material innovation:Non-toxic polymer substrates for volatile organic compound detection unlock European industrial automation deployments previously blocked by substance restrictions.
- Food safety mandates:Electronic nose systems penetrate quality control workflows as manufacturers face intensifying contamination liability exposure and batch traceability requirements.
- German automotive cluster concentration:Stuttgart and Munich manufacturing corridors integrate olfactory sensors into smart production lines for real-time process monitoring and defect prevention.
Market Restraints
- Precious metal input volatility:Palladium and platinum nanoparticle costs in metal-oxide sensor arrays fluctuate with automotive catalyst demand, compressing hardware margins.
- Calibration infrastructure concentration:Certified reference gas suppliers cluster in Switzerland and Germany, creating single-point failure risks for distributed sensor networks.
- Cross-reference interference limitations:Current sensor arrays struggle with humidity compensation in tropical climates, restricting deployment reliability.
Strategic Opportunities
- Diagnostic healthcare convergence:Breath-based disease screening applications expand as FDA in vitro diagnostic pathways clarify for volatile biomarker detection systems.
- Immersive entertainment hardware embedding:Virtual reality headset manufacturers in Japan and South Korea prototype olfactory display modules for experiential content differentiation.
- EU Green Deal procurement incentives:Public sector environmental monitoring tenders prioritize low-power sensor networks, favoring energy-efficient photonic architectures.
Industry Challenges
- Multidisciplinary talent scarcity:Chemoinformatics specialists capable of bridging molecular recognition with machine learning classification remain concentrated in academic institutions.
- ISO validation timeline compression:Cross-border interoperability certification for electronic nose performance benchmarks extends product commercialization cycles.
- Legacy process control integration friction:Siemens and Rockwell automation protocols require custom middleware development for olfactory sensor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Smell Technology Market |
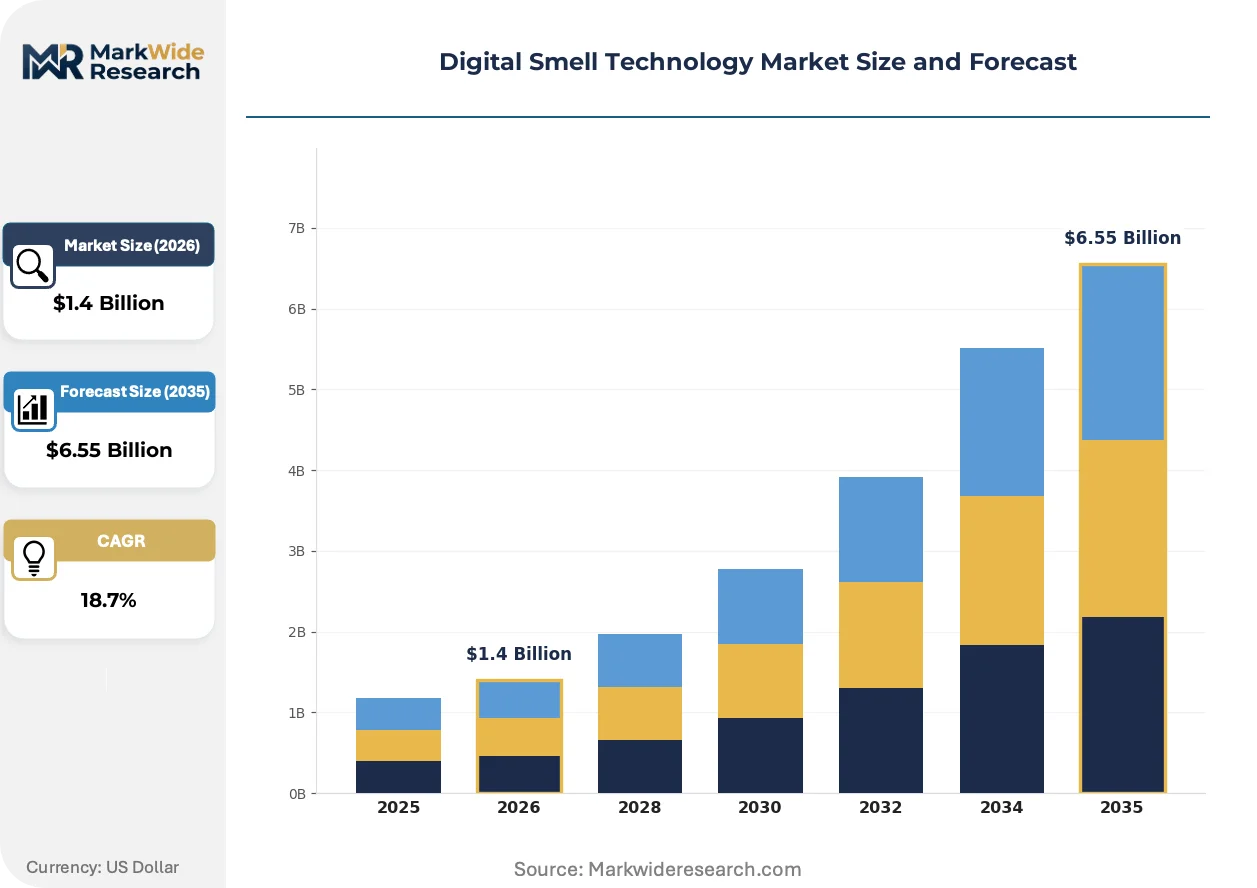
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Consumer Electronics, Food & Beverage, Healthcare, Virtual Reality Technology: Electronic Nose, Sensor Networks, Olfactory Displays, Aroma Generators End User: Retail, Academics, Entertainment, Research Institutions Product Type: Devices, Software Solutions, R&D Services, Prototyping Tools |
| Companies Covered | Alpha MOS, Siemens, Amphenol Corporation, Aryballe Technologies, Aromajoin Corporation, Airsense Analytics GmbH, Sensirion AG, Honeywell International Inc., Electronic Sensor Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Smell Technology Market Trends and Innovations
Machine learning inference at the sensor edge is compressing classification latency while regulatory transparency mandates reshape algorithm development practices across medical and industrial deployments.
Photonic biosensor platforms leveraging interferometric detection principles are virtualizing odor signature capture without consumable chemical reagents. Food and beverage manufacturers adopt these architectures for continuous production line monitoring, eliminating calibration drift inherent in metal-oxide alternatives. This virtualization is collapsing the distinction between laboratory-grade accuracy and field-deployable ruggedness.
EU AI Act algorithmic transparency requirements impose documentation burdens on pattern recognition systems used for odor classification. Developers must now maintain explainable decision trails for volatile organic compound identification workflows, particularly affecting diagnostic healthcare applications. German and French sensor manufacturers are restructuring R&D processes to embed interpretability by design rather than retrofitting compliance.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Industrial buyers now procure sensor hardware, calibration gases, and predictive maintenance analytics through separate specialized channels. This disintermediation concentrates in North American pharmaceutical quality control operations where procurement functions have consolidated vendor management authority.
Digital Smell Technology Market Segmentation
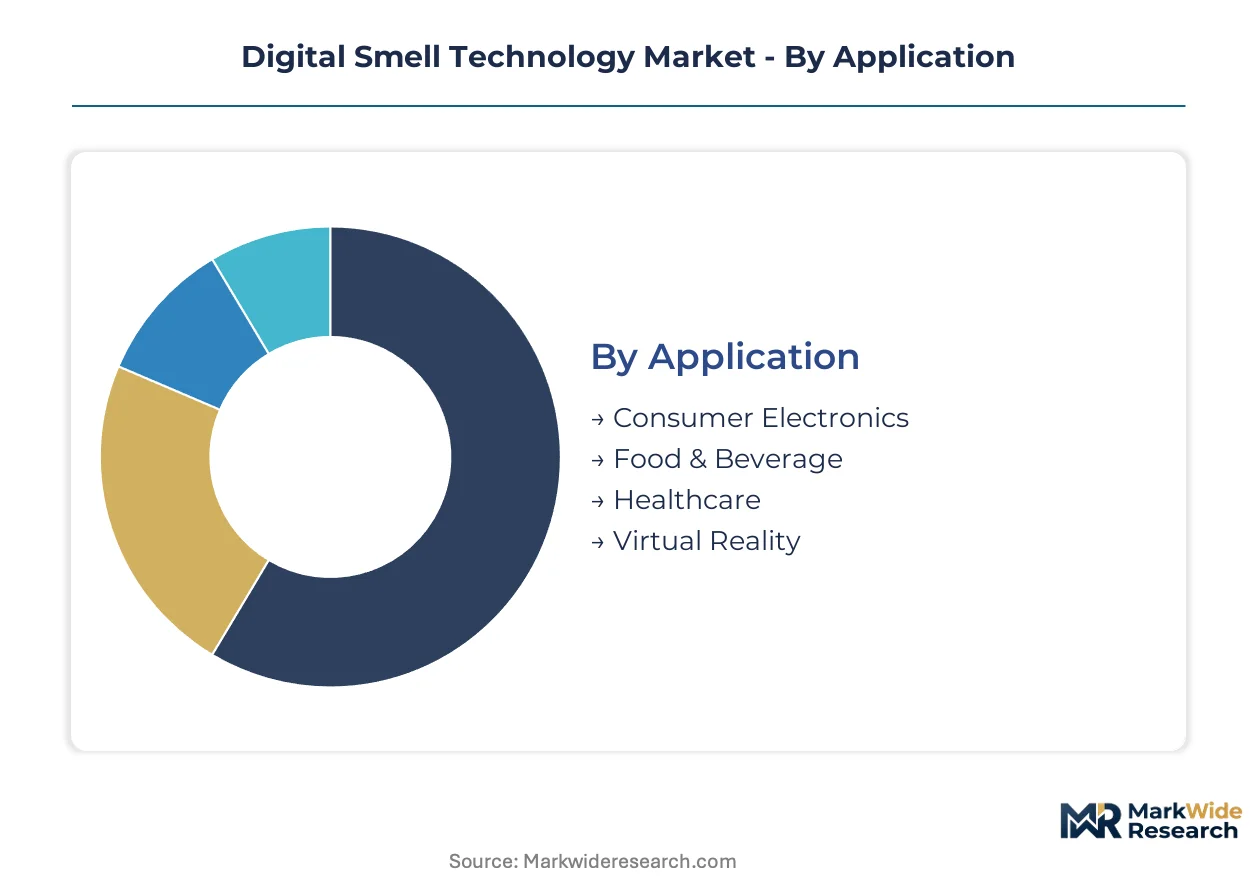
Digital smell technology markets fragment across hardware maturity curves and software abstraction layers. Procurement patterns diverge sharply between industrial buyers seeking calibrated sensor networks and consumer-facing developers prototyping immersive experiences. After-sales service intensity varies dramatically by segment, with laboratory-grade equipment demanding recurring calibration contracts while embedded modules ship with minimal field support.
Application:
After-sales service intensity clusters around industrial deployments where ISO validation and recalibration cycles generate recurring revenue streams.
- Consumer Electronics:Miniaturized gas sensor modules integrate into smartphones and wearables for personal air quality monitoring. Demand concentrates in Japan and South Korea where handset manufacturers differentiate through environmental sensing features. REACH-compliant polymer substrates unlock European market access previously blocked by substance restrictions.
- Food & Beverage:Electronic nose systems detect spoilage markers and contamination signatures in production line workflows. German and French manufacturers drive adoption as batch traceability mandates intensify liability exposure for quality failures. EFSA guidelines on rapid detection methods accelerate procurement timelines.
- Healthcare:Breath-based diagnostic platforms identify volatile biomarkers for disease screening applications.
- Virtual Reality:Olfactory display modules embed into headsets for experiential content differentiation.
By volume, Consumer Electronics leads. By growth pace, Virtual Reality is ahead.
Technology:
Cost tier stratification separates laboratory-grade photonic architectures from commodity metal-oxide sensors.
- Electronic Nose:Arrays of chemical sensors coupled with pattern recognition algorithms achieve parts-per-billion detection thresholds. Mature quality control workflows in pharmaceutical manufacturing anchor demand in Switzerland and Germany. FDA in vitro diagnostic pathways clarify for medical applications.
- Sensor Networks:Distributed monitoring architectures replace single-point measurement systems in smart city deployments. EU Green Deal procurement incentives favor low-power photonic designs for environmental monitoring tenders. Premium margin pools concentrate in industrial IoT integrations.
- Olfactory Displays:Scent emission hardware for immersive entertainment represents the steepest expansion trajectory.
- Aroma Generators:Programmable fragrance release systems target retail and hospitality experience design.
Electronic Nose commands current revenue share. Sensor Networks gain share fastest.
End User:
Customer type determines procurement complexity, with research institutions negotiating bespoke specifications against retail buyers seeking plug-and-play solutions.
- Retail:Scent marketing systems deploy in flagship stores and hospitality venues to influence consumer behavior. Japanese department stores and French luxury brands drive specification requirements for programmable fragrance intensity. After-sales service contracts cover cartridge replenishment and hardware maintenance.
- Academics:University laboratories purchase configurable sensor platforms for chemoinformatics research. Funding concentration in German and Swiss technical universities sustains demand for research-grade calibration standards. Multidisciplinary talent scarcity limits deployment scale.
- Entertainment:Theme parks and immersive experience designers prototype olfactory content integration.
- Research Institutions:National laboratories validate sensor performance against certified reference materials.
Retail generates highest transaction frequency. Academics sustain longest replacement cycles.
Product Type:
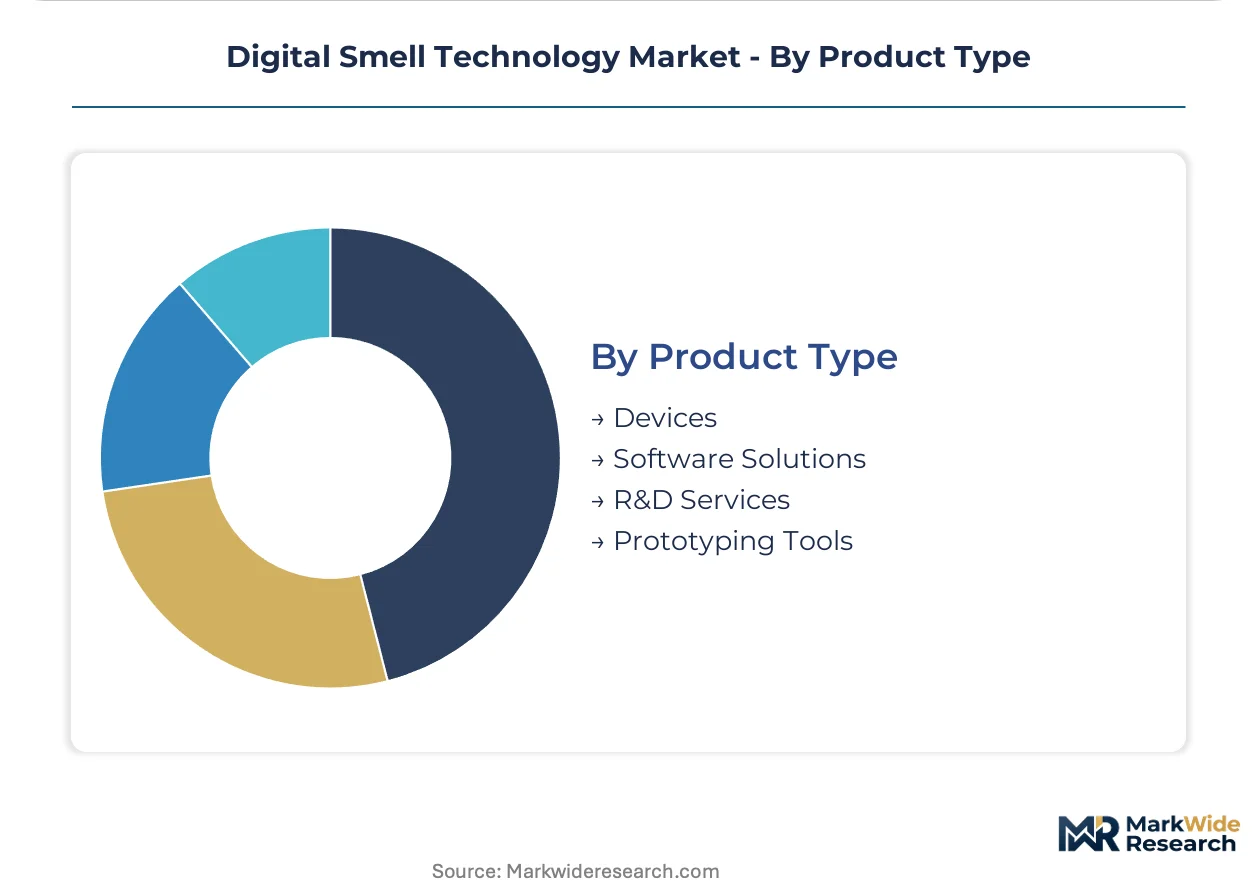
Margin structure inverts between hardware shipments and recurring software licensing, with R&D services capturing value from capability scarcity.
- Devices:Standalone electronic nose hardware and embedded sensor modules ship with firmware for edge classification. German automotive clusters in Stuttgart integrate olfactory sensors into smart manufacturing lines for real-time process monitoring. Precious metal input volatility in palladium and platinum nanoparticles compresses hardware margins.
- Software Solutions:Pattern recognition algorithms and cloud analytics platforms process odor signature data streams. EU AI Act transparency requirements impose documentation burdens on machine-learning-driven classification systems. Interpretability-by-design restructuring adds R&D overhead.
- R&D Services:Custom sensor development and chemoinformatics consulting bridge molecular recognition with machine learning.
- Prototyping Tools:Evaluation kits and developer boards accelerate product concept validation.
Devices dominate current shipment value. Software Solutions expand margin contribution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement incentives and REACH substance restrictions are redistributing manufacturing investment toward compliant fabrication clusters. National environmental monitoring tenders increasingly specify low-power sensor architectures, accelerating regional specialization patterns.
Germany
Stuttgart and Munich automotive corridors integrate olfactory sensors into smart manufacturing lines for real-time defect prevention. The EU AI Act imposes algorithmic transparency requirements on pattern recognition systems deployed in industrial automation. Bavaria-based sensor manufacturers are restructuring R&D processes to embed interpretability by design.
United States
FDA in vitro diagnostic pathways clarify for breath-based disease screening applications, expanding healthcare deployment scope. The EPA regulates environmental monitoring sensor networks through air quality certification standards. Greater Boston pharmaceutical quality control operations drive after-sales service unbundling trends.
Japan
Handset manufacturers differentiate through personal air quality monitoring features in miniaturized gas sensor modules. METI standards guide consumer electronics integration specifications for wearable environmental sensors. Tokyo and Osaka prototyping centers develop olfactory display modules for virtual reality headset embedding.
France
Luxury brands and department stores drive programmable fragrance intensity specifications for scent marketing systems. EFSA guidelines on rapid detection methods accelerate electronic nose procurement timelines in food manufacturing. Île-de-France sensor developers face EU AI Act documentation burdens for odor classification algorithms.
South Korea
Virtual reality hardware manufacturers prototype experiential content differentiation through embedded scent emission modules. The national standards body aligns with ISO electronic nose performance validation benchmarks for cross-border interoperability. Seoul metropolitan area consumer electronics clusters concentrate miniaturized sensor module demand.
Digital Smell Technology Market Competitive Landscape
On the supply side, the industry is consolidating around capital-efficient modular fabrication strategies and photonic biosensor architectures. Tiered competitive positioning separates laboratory-grade precision manufacturers from commodity sensor assemblers. Strategic archetypes include industrial automation integrators, photonic architecture specialists, and miniaturized module suppliers. Dominant competitive moves encompass strategic partnerships for process control integration and technology licensing for REACH-compliant material substrates.
Among European-based developers, Aryballe Technologies and Sensirion AG exemplify divergent specialization vectors within the hardware tier. Siemens occupies a position representing industrial automation integration capabilities. These three entities collectively illustrate the competitive spectrum spanning photonic detection architectures, miniaturized consumer embedding modules, and process control system anchoring.
| Leading Market Players |
|---|
| Alpha MOS |
| Siemens |
| Amphenol Corporation |
| Aryballe Technologies |
| Aromajoin Corporation |
| Airsense Analytics GmbH |
| Sensirion AG |
| Honeywell International Inc. |
| Electronic Sensor Technology |
| Others |
Pricing and Supply Chain Analysis
Stuttgart and Munich fabrication clusters anchor photonic biosensor capacity, concentrating supply-side leverage among REACH-compliant manufacturers who command premium positioning against metal-oxide commodity assemblers. Their modular cleanroom strategies compress capital intensity thresholds, reshaping downstream pricing power toward capital-efficient players with certified reference gas partnerships.
Pricing Analysis
Certification level creates the primary spread, with ISO-validated electronic nose systems commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across laboratory-grade, industrial-field, and consumer-embedded levels reflects performance tier and after-sales bundling intensity. Cost compression in metal-oxide sensor arrays stems from palladium and platinum nanoparticle volatility tied to automotive catalyst demand. Pharmaceutical quality control buyers exhibit lowest price sensitivity due to liability exposure, while consumer electronics procurement teams drive aggressive module cost-down targets.
Supply Chain Analysis
Photonic sensor substrates draw from specialized polymer foundries in Germany, Switzerland, and Japan, with nanoparticle deposition equipment concentrated among Dutch and American tool vendors. Raw material dependencies span REACH-compliant polymer substrates, interferometric waveguide components, and certified reference gas formulations. Single-source vulnerability clusters around Swiss and German calibration gas suppliers, creating network failure exposure for distributed industrial deployments. Distribution runs through direct OEM integration for automotive and pharmaceutical buyers, with modular sensor modules flowing through electronics distributors for consumer device embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital smell technology markets recover cyclically as industrial automation capital expenditure rebounds from recent manufacturing slowdowns, with German automotive cluster demand serving as the lead indicator.
For Market Incumbents: Pre-empt photonic architecture commoditization by locking exclusive REACH-compliant polymer substrate supply agreements with Bavarian chemical suppliers. Deepen process control integration capabilities through middleware development partnerships with Siemens and Rockwell automation protocol teams, defending against emerging modular cleanroom entrants with lower capital barriers. For New Entrants and Emerging Players: Pursue olfactory display module white space in Japanese and South Korean virtual reality headset supply chains, where experiential content differentiation commands hardware embedding premiums. Target academic and national laboratory procurement channels for configurable sensor platforms, leveraging chemoinformatics talent scarcity to justify extended R&D service contracts before scaling to industrial volumes. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU AI Act transparency requirements and REACH substance restrictions continuously filter out undercapitalized competitors. Acquisition targets should concentrate on photonic biosensor architecture specialists with embedded interpretability-by-design capabilities. Watch FDA in vitro diagnostic pathway clarifications for breath-based disease screening as the inflection signal for healthcare segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Architecture Licensing | REACH-compliant polymer substrate partnerships unlock European industrial automation procurement channels. |
| Process Control Integration | Middleware development for Siemens protocols anchors smart manufacturing line sensor deployments. |
| Diagnostic Regulatory Pathway | FDA in vitro diagnostic submissions expand breath-based disease screening application scope. |
| Immersive Hardware Embedding | Olfactory display module partnerships with Japanese VR manufacturers accelerate experiential content adoption. |
| Calibration Infrastructure Control | Certified reference gas supplier acquisitions reduce single-point failure risks in distributed sensor networks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with sensor platform engineers, industrial automation procurement leads, pharmaceutical quality control directors, and chemoinformatics researchers; and secondary validation against EMA device filings, EPA air quality certification standards, ISO performance benchmark documentation, and REACH substance restriction updates. Bottom-up sensor shipment estimates triangulated against top-down industrial automation capital expenditure patterns.
Forecast inputs span technology maturity curves, regulatory compliance timeline shifts, and end-use adoption thresholds across the projection horizon. Segmentation dimensions modeled include application vertical, hardware architecture tier, end-user procurement complexity, and regional regulatory cluster. CAGRs derived from slope analysis of historical penetration rates adjusted for REACH and EU AI Act implementation pacing, with photonic biosensor cost-down curves and metal-oxide material volatility serving as industry-specific sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and automotive production volumes would shift the trajectory. Forecasts reflect assumptions around calibration infrastructure stability and regulatory timeline adherence. Cross-checking against German automotive cluster order backlogs and FDA diagnostic pathway publication schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Motion Simulation Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Incubator Analyzer Market