
 Global Weather Forecasting Systems Market | 2026-2036
Global Weather Forecasting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Weather Forecasting Systems Market Foresight
Subscription-based weather intelligence is pivoting how forecast providers monetize atmospheric data. Vaisala leverages its sensor manufacturing depth to bundle hardware with recurring analytics services. StormGeo anchors maritime routing contracts through proprietary wave-height algorithms. AccuWeather, Inc. competes by extending consumer app reach into enterprise risk management portals.
Weather forecasting systems encompass hardware, software, and service architectures that collect atmospheric variables, process them through physics-based or machine-driven models, and distribute predictive outputs to decision-makers. Numerical weather prediction platforms still occupy the largest installed base, though artificial intelligence models are displacing legacy compute cycles for nowcasting tasks. Aviation safety applications command premium pricing due to ICAO-mandated flight planning requirements, while renewable energy firms represent the fastest-growing end user category as grid operators require sub-hourly generation forecasts. Data assimilation technology sits at the core margin pool, since proprietary ingestion methods differentiate forecast accuracy.
FAA mandates govern aviation weather product standards in the United States, while EASA enforces parallel certification requirements across Europe. China's Meteorological Administration operates under GB standards that prioritize dual carbon goals through renewable forecasting obligations. Stakeholders must monitor how national meteorological agencies reconcile open data mandates with commercial service licensing.
Market Dynamics
Artificial intelligence architectures are compressing forecast generation cycles from hours to minutes, forcing incumbents to restructure compute infrastructure around GPU clusters rather than traditional supercomputing arrays.
Growth Catalysts
- ICAO Flight Planning Mandates:International aviation regulators require turbulence-aware routing systems for transoceanic corridors, compelling carriers to upgrade meteorological subscriptions.
- Renewable Grid Integration:Utility operators in Germany and China require sub-hourly generation forecasts to balance intermittent solar and wind assets against baseload demand.
- Edge Computing Deployment:Microsatellite constellations now stream raw atmospheric data directly to ground-based inference engines, bypassing centralized processing bottlenecks.
Market Restraints
- Silicon Supply Concentration:Specialized AI accelerators for meteorological inference depend on Taiwan-based foundry capacity, exposing forecast providers to geopolitical disruption.
- Data Sovereignty Friction:China's GB standards restrict cross-border atmospheric data flows, fragmenting training datasets for global model developers.
- Legacy System Entrenchment:National meteorological agencies in the United States and Europe maintain decades-old numerical prediction codebases that resist modular replacement.
Strategic Opportunities
- India Agricultural Microinsurance:Monsoon prediction services remain underpenetrated among smallholder cooperatives, creating white space for parametric weather products.
- EU AI Act Compliance Services:Forecasting platforms can bundle explainability tooling to help energy traders meet algorithmic transparency requirements for automated bidding systems.
- Drone-Based Boundary Layer Sensing:Unmanned aerial systems carrying radiosondes capture hyperlocal atmospheric profiles that satellites miss, opening urban microclimate forecasting.
Industry Challenges
- Atmospheric Data Scientist Scarcity:The intersection of fluid dynamics expertise and machine learning engineering remains thinly staffed across forecast providers.
- Certification Timeline Compression:FAA and EASA validation protocols for aviation weather products require 18-24 month approval cycles, lagging behind software update velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Weather Forecasting Systems Market |
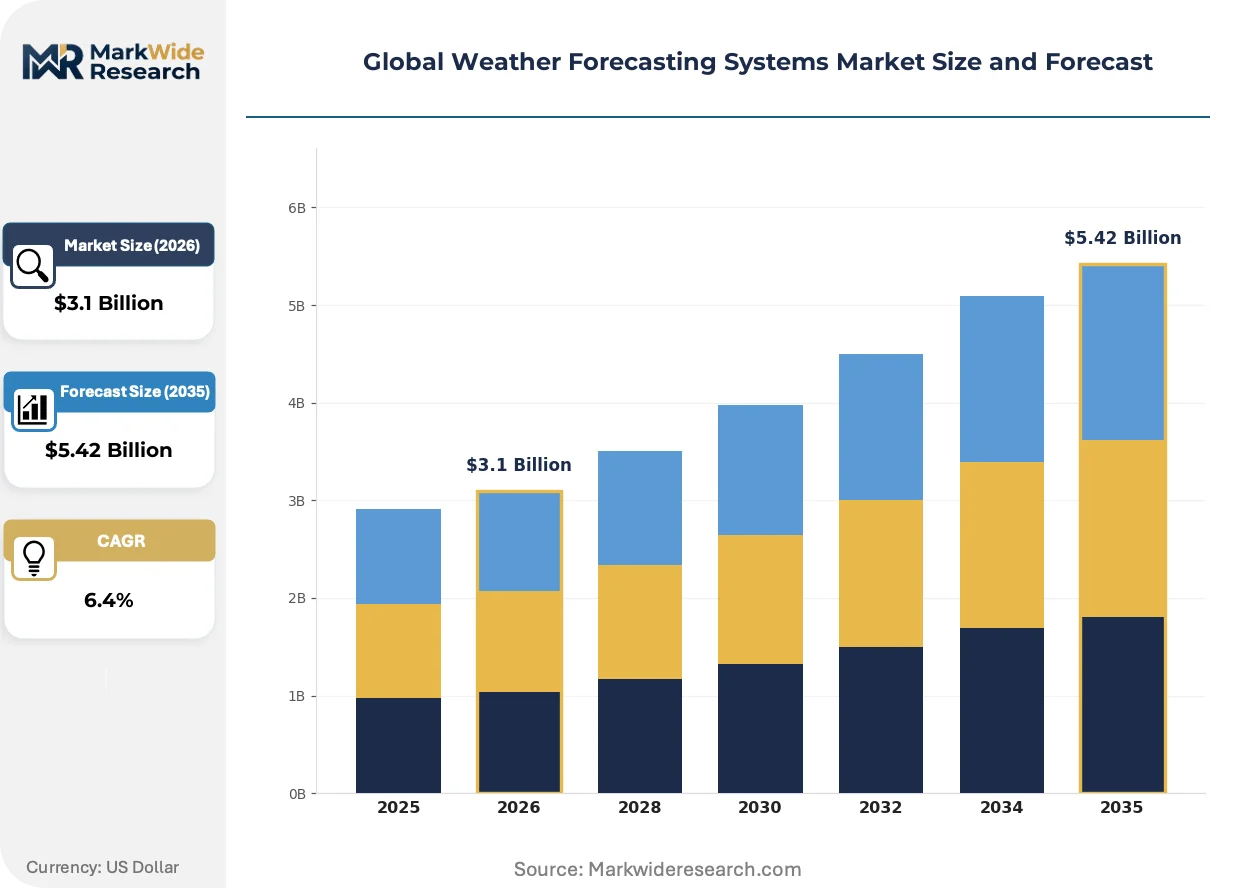
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Numerical Weather Prediction, Satellite Meteorology, Radar Systems, Weather Stations, Data Buoy Networks Technology: Doppler Radar, Lidar, Remote Sensing, Artificial Intelligence Models, Climate Simulation, Data Assimilation Application: Agriculture, Aviation Safety, Disaster Management, Energy Sector, Marine Operations, Urban Planning End User: Meteorological Agencies, Research Institutes, Renewable Energy Firms, Maritime Authorities, Defense Departments |
| Companies Covered | Vaisala, AccuWeather, Inc., The Weather Company LLC, Lockheed Martin Corporation, Campbell Scientific, Inc., All Weather, Inc. (AWI), DTN, StormGeo, Columbia Weather Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Weather Forecasting Systems Market Shifts & Advancements
Forecast delivery architectures are fragmenting from monolithic national centers toward distributed sensor-to-edge pipelines, compressing latency and opening new competitive entry points.
Federated learning frameworks are decentralizing model training across national meteorological agencies without centralizing sensitive atmospheric data. The European Centre for Medium-Range Weather Forecasts pilots this approach with member states, preserving sovereignty while pooling predictive capacity. This architecture is decentralizing competitive advantage from raw compute scale toward proprietary data assimilation techniques.
REACH chemical registration requirements now govern the rare gas mixtures used in lidar wind sensors deployed across offshore wind farms. Manufacturers must document full supply chain toxicity profiles for neon and xenon isotopes, extending procurement timelines. German turbine operators face the steepest compliance burden, driving substitution toward solid-state Doppler alternatives.
Energy traders now unbundle forecast subscriptions from bundled hardware maintenance contracts, pressuring providers to price atmospheric intelligence as pure software. Independent power producers in Texas and California lead this disintermediation, procuring API-accessible ensemble predictions directly from specialized analytics firms rather than integrated system vendors.
Global Weather Forecasting Systems Market Segmentation
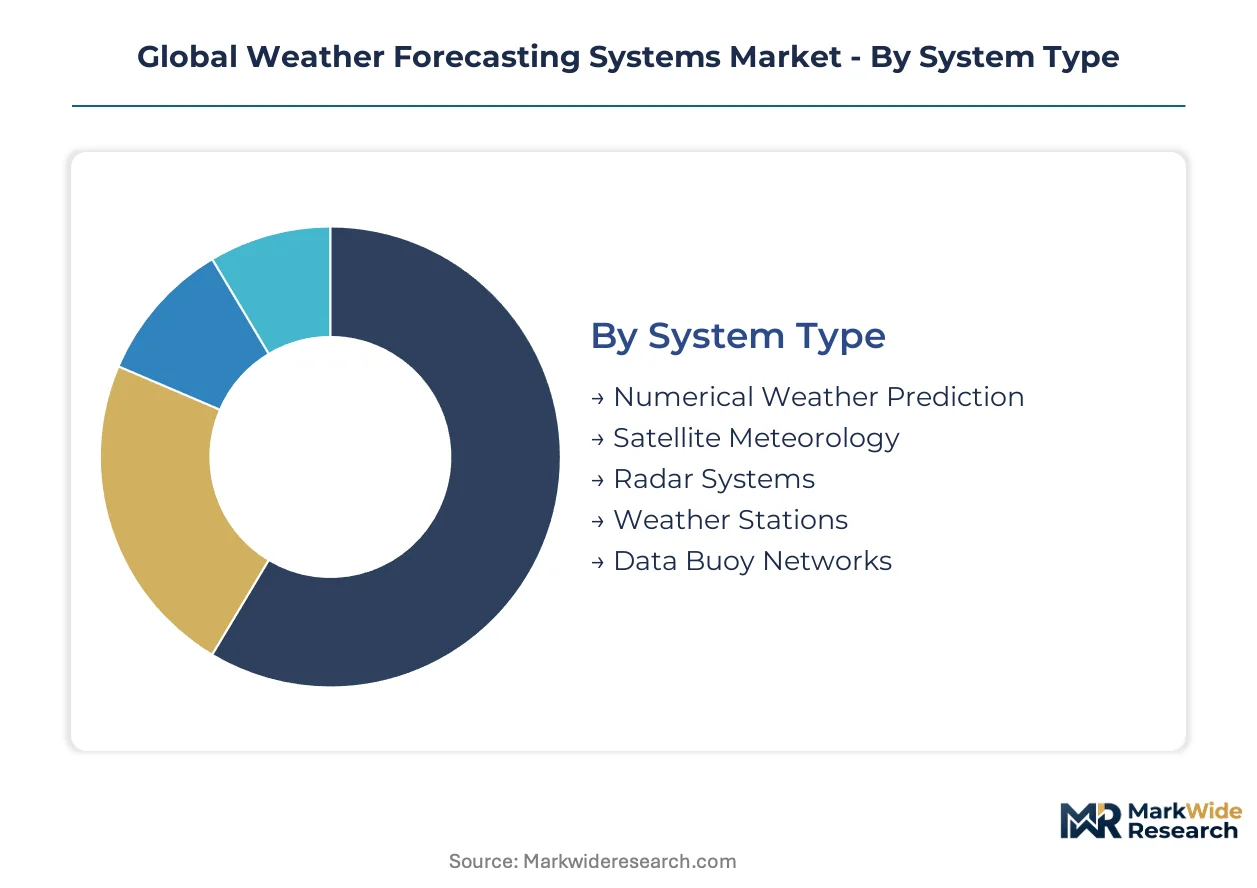
Weather forecasting systems fragment across multiple technical and commercial dimensions. System architecture, sensing modality, and end-use application each impose distinct procurement patterns and margin structures on providers.
System Type:
Capital intensity varies sharply across system categories, with orbital and marine infrastructure demanding multiyear deployment cycles while terrestrial networks scale incrementally.
- Numerical Weather Prediction:Physics-based computational platforms ingest atmospheric variables through ensemble modeling to generate medium-range forecasts. National meteorological agencies in Germany and China maintain the largest installed supercomputing clusters for operational runs, though maintenance costs pressure migration toward cloud-resident architectures.
- Satellite Meteorology:Geostationary and polar-orbiting platforms carrying multispectral radiometers capture synoptic-scale weather patterns. Procurement concentrates among defense departments and national space agencies, where sovereign sensing capabilities override commercial subscription models.
- Radar Systems:Ground-based Doppler networks provide precipitation and wind field detection for nowcasting applications. The FAA mandates specific coverage densities across United States terminal radar approach control zones, creating regulated demand floors.
- Weather Stations:Surface observation networks combine automated sensors with human-augmented installations. Agricultural cooperatives in India and utility operators in Texas drive distributed deployment for microclimate monitoring.
- Data Buoy Networks:Oceanographic platforms transmit wave height, sea surface temperature, and atmospheric pressure from marine corridors. Maritime authorities operating transoceanic shipping lanes anchor procurement, with StormGeo and similar routing providers accessing buoy feeds through bilateral data agreements.
Numerical Weather Prediction absorbs the bulk of installed capacity; Artificial Intelligence Models are expanding most quickly through nowcasting substitution.
Technology:
Technology selection pivots on the latency-accuracy tradeoff, with operational users tolerating longer computation cycles for ensemble reliability while tactical applications prioritize inference speed.
- Doppler Radar:Pulse-Doppler architectures measure radial velocity and reflectivity for severe weather detection. Aviation safety mandates in the United States and Europe sustain replacement cycles for aging NEXRAD-class installations.
- Lidar:Laser-based wind sensing captures boundary-layer profiles for wind farm optimization. REACH chemical registration requirements for rare gas mixtures in offshore units are accelerating substitution toward solid-state alternatives.
- Remote Sensing:Passive and active satellite instruments retrieve atmospheric temperature, moisture, and aerosol properties. China's GB standards prioritize domestic constellation deployment for renewable forecasting compliance.
- Artificial Intelligence Models:Deep learning architectures trained on reanalysis data compress forecast generation from hours to minutes. GPU cluster procurement is displacing traditional supercomputing arrays among commercial providers.
- Climate Simulation:Century-scale earth system models support policy and reinsurance applications. Research institutes in Europe and the United States dominate access to computational resources for decadal projection runs.
- Data Assimilation:Proprietary ingestion methods combining observations with model states differentiate forecast accuracy. This segment commands premium pricing through vendor-specific variational and ensemble Kalman filter implementations.
Data Assimilation captures the highest margin pool; Artificial Intelligence Models are climbing the fastest as nowcasting displaces legacy numerical methods.
Application:
Application segmentation reflects divergent regulatory intensity, with safety-critical uses commanding certification overhead that general-purpose forecasting escapes.
- Agriculture:Seasonal and sub-seasonal predictions inform planting, irrigation, and harvest timing. Parametric microinsurance products in India remain underpenetrated among smallholder cooperatives.
- Aviation Safety:Turbulence-aware routing and terminal weather products carry ICAO-mandated certification requirements. Premium pricing reflects 18-24 month FAA and EASA validation protocols.
- Disaster Management:Early warning systems for cyclones, floods, and wildfires require multi-agency coordination. National meteorological agencies in typhoon-prone corridors anchor procurement.
- Energy Sector:Sub-hourly generation forecasts balance intermittent renewable assets against baseload demand. Grid operators in Germany and Texas lead disintermediation toward API-accessible ensemble predictions.
- Marine Operations:Wave-height algorithms and route optimization reduce fuel consumption and cargo damage. StormGeo anchors maritime contracts through proprietary oceanographic processing.
- Urban Planning:Heat island monitoring and air quality forecasting support municipal resilience investments. Cities in China and the southwestern United States deploy dense sensor networks for microclimate mapping.
Aviation Safety generates the highest revenue per installation; Energy Sector applications are gaining share fastest as grid decarbonization accelerates forecast granularity requirements.
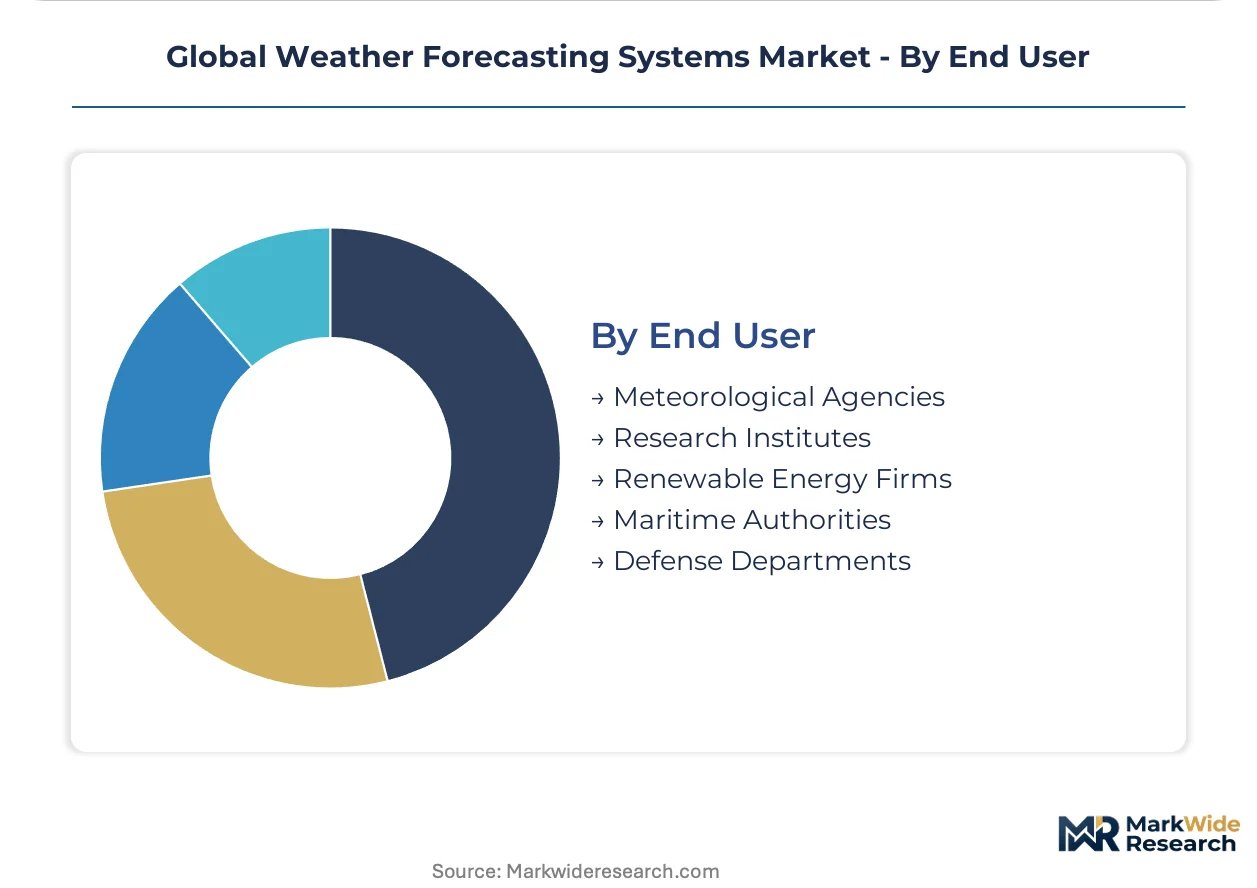
End User:
End user segmentation separates sovereign purchasers with multi-decade procurement horizons from commercial operators seeking subscription flexibility.
- Meteorological Agencies:National centers maintain operational responsibility for public forecasting and severe weather warnings. Legacy numerical prediction codebases in the United States and Europe resist modular replacement despite AI alternatives.
- Research Institutes:Academic and government laboratories advance model physics and data assimilation techniques. Federated learning pilots at the European Centre for Medium-Range Weather Forecasts pool predictive capacity without centralizing sensitive data.
- Renewable Energy Firms:Wind and solar operators require granular generation forecasts for trading and dispatch optimization. Independent power producers in Texas and California unbundle subscriptions from hardware maintenance contracts.
- Maritime Authorities:Port operators and coast guards monitor marine weather for vessel traffic management. Procurement concentrates on wave and visibility products for high-traffic corridors.
- Defense Departments:Military weather services require secure, denied-environment forecasting capabilities. Classified requirements sustain dedicated satellite and computational infrastructure outside commercial markets.
Meteorological Agencies command the largest cumulative installed base; Renewable Energy Firms are expanding most quickly as grid operators impose sub-hourly forecasting obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing concentrates in Germany, China, and the United States, while service consumption spreads across aviation corridors and renewable energy clusters. Taiwan-based foundries supply specialized AI accelerators that power next-generation inference engines. Cross-border atmospheric data flows face mounting friction as national agencies assert sovereignty over meteorological observations.
United States
The FAA mandates turbulence-aware routing systems for transoceanic aviation corridors, compelling carriers to upgrade meteorological subscriptions. Independent power producers in Texas and California unbundle forecast subscriptions from hardware maintenance contracts, procuring API-accessible ensemble predictions directly. The National Weather Service maintains legacy numerical prediction codebases that resist modular replacement despite AI alternatives.
Germany
Grid operators require sub-hourly generation forecasts to balance intermittent solar and wind assets against baseload demand. REACH chemical registration requirements govern rare gas mixtures in offshore lidar wind sensors, accelerating substitution toward solid-state Doppler alternatives. The European Centre for Medium-Range Weather Forecasts pilots federated learning frameworks with member states, pooling predictive capacity without centralizing sensitive atmospheric data.
China
GB standards prioritize dual carbon goals through renewable forecasting obligations, restricting cross-border atmospheric data flows and fragmenting training datasets for global model developers. The Meteorological Administration operates under procurement rules that favor domestic constellation deployment for sovereign sensing capabilities. Yangtze River Delta utilities drive demand for edge computing deployment that streams raw atmospheric data directly to ground-based inference engines.
India
Monsoon prediction services remain underpenetrated among smallholder cooperatives, creating white space for parametric weather products. The Central Electricity Authority imposes grid forecasting obligations on renewable energy firms that expand faster than meteorological infrastructure. Agricultural clusters in Maharashtra and Gujarat deploy distributed weather station networks for microclimate monitoring that supports irrigation timing decisions.
Japan
METI coordinates public-private partnerships for typhoon early warning systems that protect dense coastal infrastructure. Defense departments sustain dedicated satellite and computational infrastructure outside commercial markets for denied-environment forecasting capabilities. Kanto region utilities integrate sub-hourly solar generation forecasts into automated bidding systems for electricity markets.
Global Weather Forecasting Systems Market Competitive Landscape
Capital-heavy sensor manufacturers compete with asset-light analytics providers for margin capture in weather intelligence. The vendor base spans vertically integrated hardware specialists, software-centric forecast platforms, and hybrid service bundlers. Three archetypes dominate: component fabricators with captive foundry relationships, subscription-based intelligence platforms with recurring revenue models, and systems integrators anchoring long-term maritime and aviation contracts. Competitive moves concentrate on federated data partnerships that preserve national sovereignty while pooling training datasets, plus GPU cluster procurement that displaces traditional supercomputing infrastructure.
Within the integrated sensor tier, Vaisala leverages its manufacturing depth to bundle hardware with recurring analytics services. AccuWeather, Inc. occupies a position exemplifying consumer-to-enterprise platform expansion, extending app reach into risk management portals. StormGeo anchors maritime routing contracts through proprietary wave-height algorithms that reduce fuel consumption for shipping operators.
| Leading Market Players |
|---|
| Vaisala |
| AccuWeather, Inc. |
| The Weather Company LLC |
| Lockheed Martin Corporation |
| Campbell Scientific, Inc. |
| All Weather, Inc. (AWI) |
| DTN |
| StormGeo |
| Columbia Weather Systems Inc. |
| Others |
Supply & Pricing Matrix
GPU cluster procurement costs cascade through three distinct pricing tiers as hyperscaler compute contracts anchor premium forecasting services while modular sensor hardware competes on landed cost. Taiwan-based foundry capacity for AI accelerators tightens margin structures at the inference-engine tier, forcing commercial providers to renegotiate long-term offtake terms or absorb spot-market volatility.
Pricing Analysis
Price erosion across aviation safety subscriptions traces to unbundling pressures as independent power producers in Texas and California procure API-accessible ensemble predictions directly from analytics firms rather than integrated system vendors. Three-tier pricing structure across premium, standard, and economy levels separates ICAO-certified turbulence products from non-certified route optimization tools and basic consumer-grade forecasts. Certification grade and volume scale drive price differentiation, with FAA-validated terminal weather products commanding substantial premiums over uncertified nowcasting outputs. Renewable energy firms exhibit highest price sensitivity, while defense departments tolerate cost premiums for denied-environment capabilities.
Supply Chain Analysis
Freight costs for geostationary satellite components and specialized lidar wind sensors amplify landed pricing volatility as procurement cycles extend. Manufacturing concentrates in Germany, China, and the United States, with Taiwan-based foundries supplying AI accelerators that power next-generation inference engines. Rare gas mixtures for offshore Doppler units, silicon wafers for GPU clusters, and precision optics for multispectral radiometers constitute critical input dependencies. Single-source vulnerability around Taiwan semiconductor fabrication exposes forecast providers to geopolitical disruption. Distribution runs through national meteorological agencies with sovereign procurement authority and commercial analytics platforms with direct enterprise API sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as GPU cluster procurement requirements and FAA certification timelines favor scaled incumbents with captive compute infrastructure and regulatory relationships.
For Market Incumbents: To counter disintermediation by asset-light analytics providers, national meteorological agencies and integrated sensor manufacturers should deepen backward integration into Taiwan-based foundry relationships for AI accelerator supply security while accelerating cloud-resident architecture migration to reduce maintenance overhead. Certification investment in FAA and EASA validation protocols preserves premium pricing power in aviation safety corridors. For New Entrants and Emerging Players: Smallholder agricultural cooperatives in India remain underserved by parametric microinsurance products tied to monsoon prediction accuracy, offering penetrable entry points without competing against entrenched national forecasting infrastructure. Drone-based boundary layer sensing for urban microclimate applications opens white space where satellite coverage gaps persist. Go-to-market through agricultural extension networks and municipal resilience offices bypasses direct competition with sovereign meteorological agencies. For Investors and Strategic Acquirers: Federated learning framework adoption at the European Centre for Medium-Range Weather Forecasts is the leading indicator that data-sovereignty-compliant model training architectures will reshape competitive advantage from raw compute scale toward proprietary data assimilation techniques. Long-term viability centers on analytics platforms with demonstrated accuracy differentiation and recurring subscription revenue rather than capital-heavy sensor hardware with lumpy procurement cycles. Watch for GPU cluster procurement announcements as inflection signals for inference-engine competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Cluster Procurement | Secures Taiwan-based foundry capacity for AI inference-engine competitive positioning. |
| FAA Certification Investment | Validates turbulence products for 18-24 month approval cycles in aviation corridors. |
| Federated Learning Partnership | Pools European predictive capacity without centralizing sensitive atmospheric data. |
| API-First Platform Launch | Enables Texas and California renewable operators to unbundle forecasts from hardware. |
| Drone Sensor Network Deployment | Captures hyperlocal boundary layer profiles for urban microclimate forecasting. |
Research Methodology
Independent corroboration across meteorological agency procurement officers, aviation safety regulators, renewable energy trading desks, and maritime routing providers underwrites the qualitative findings in this study. Primary interviews with GPU cluster procurement leads, data assimilation specialists, and federated learning program directors combined with secondary validation through FAA certification databases, EASA validation protocols, and national meteorological agency budget disclosures. Bottom-up sensor deployment counts and top-down atmospheric intelligence revenue estimates triangulate market sizing.
Rate-of-change decomposition across system type, sensing modality, technology architecture, and end-use application segments drives the analytical framework over the projection horizon. CAGRs derive from installed base migration curves for numerical weather prediction platforms, GPU cluster procurement trajectories for AI model providers, and regulatory mandate implementation timelines for aviation safety products. Forecast inputs include ICAO flight planning mandate adoption rates, sub-hourly renewable forecasting obligation rollouts in Germany and China, and Taiwan foundry capacity allocation for meteorological AI accelerators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan semiconductor supply disruptions, FAA certification timeline compression, and cross-border atmospheric data sovereignty restrictions. Forecasts reflect documented assumptions about GPU cluster cost trajectories and federated learning framework adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market