
 Incubator Analyzer Market | 2026-2036
Incubator Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Incubator Analyzer Market Outlook
Equipment leasing and performance-based service contracts are reshaping competitive dynamics in the incubator analyzer space. Fluke Biomedical leverages its calibration instrumentation heritage to anchor long-term service agreements with hospital networks. General Electric sustains installed base loyalty through predictive maintenance platforms tied to analyzer fleets. Atom Medical Corporation competes on manufacturing scale in Asia-Pacific markets with localized certification support.
An incubator analyzer is a precision thermal validation instrument that measures temperature uniformity, humidity levels, and gas composition inside laboratory incubators using calibrated sensor arrays and data logging systems; it ensures environmental parameters remain within specified tolerances for sensitive biological processes. CO2 incubators dominate analyzer attachment rates due to stringent cell culture protocols in biopharma manufacturing. Hybrid systems represent the fastest-growing technology segment as laboratories seek multi-parameter validation from single platforms. Pharmaceutical companies constitute the deepest margin pool among end users given regulatory audit frequency and instrument redundancy requirements.
FDA quality system regulations and ISO 17025 calibration standards shape product design by mandating traceable measurement uncertainty documentation and periodic revalidation intervals. EPA energy efficiency guidelines influence analyzer specifications for refrigerated incubator testing protocols. EMA good manufacturing practice inspections extend demand for dual-sensor redundancy configurations in European biologics facilities. Stakeholders must monitor evolving harmonization between regional metrology institutes as cross-border laboratory accreditation becomes a procurement gate.
Market Dynamics
Equipment leasing and performance-based service contracts are reshaping competitive dynamics in the incubator analyzer space. Fluke Biomedical leverages its calibration instrumentation heritage to anchor long-term service agreements with hospital networks. General Electric sustains installed base loyalty through predictive maintenance platforms tied to analyzer fleets. Atom Medical Corporation competes on manufacturing scale in Asia-Pacific markets with localized certification support.
Growth Catalysts
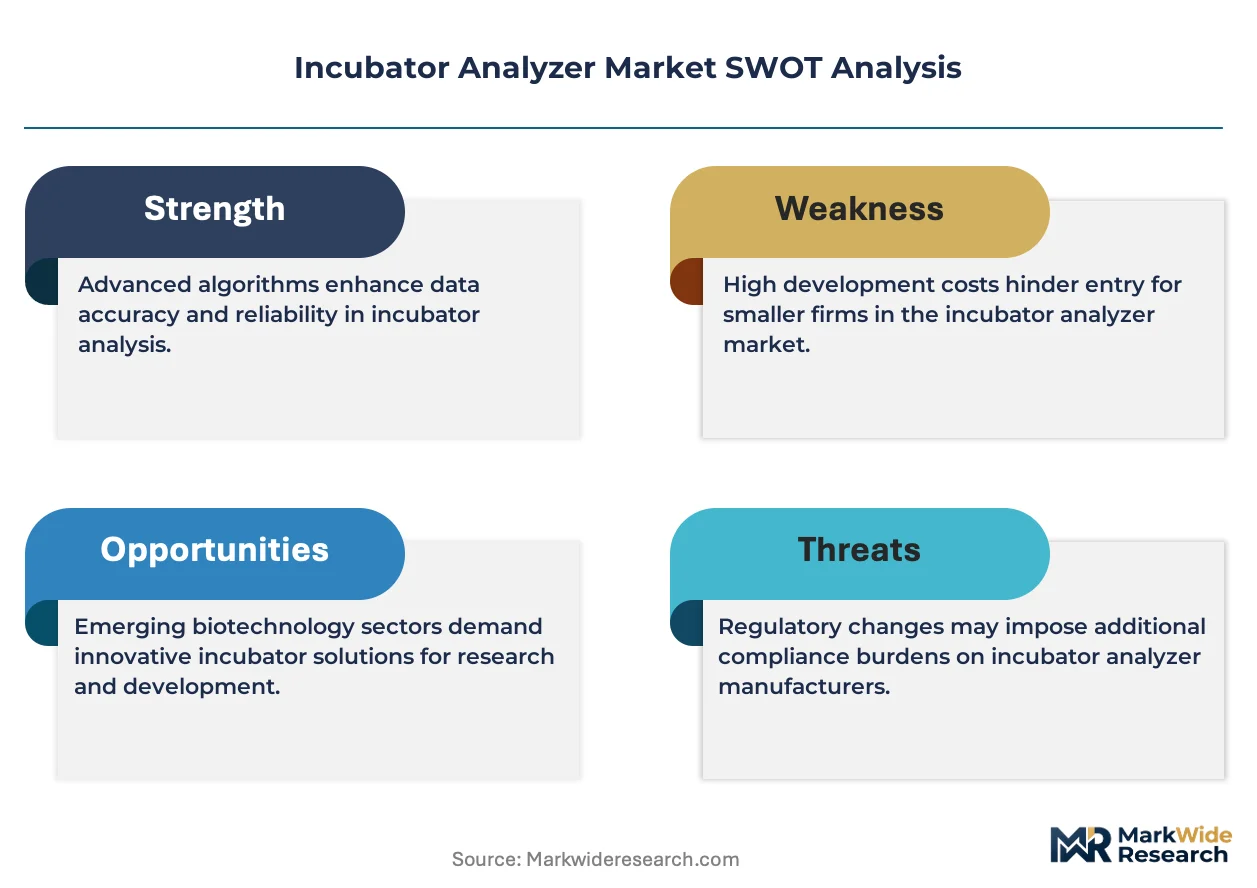
- ISO 17025 calibration standards:Tightening validation requirements for thermal uniformity testing are compelling laboratories to upgrade legacy analyzer fleets with traceable measurement systems.
- Biopharma manufacturing expansion:Biotechnology firms are expanding incubator analyzer procurement to support cell culture workflows and meet regulatory audit frequency demands.
- Neonatal intensive care unit upgrades:Hospital infrastructure modernization in the United States, Germany, and China is driving replacement cycles for precision environmental monitoring equipment.
Market Restraints
- Sensor array cost volatility:Platinum resistance thermometers and NDIR gas sensors face input cost pressure from precious metal and optical component supply chains.
- Calibration infrastructure concentration:Accredited metrology laboratories cluster in Germany, the United States, and Japan, creating geographic bottlenecks for ISO 17025 traceability.
- Dual-sensor redundancy mandates:EMA good manufacturing practice inspections require redundant configurations that inflate capital expenditure for European biologics facilities.
Strategic Opportunities
- Hybrid system technology convergence:Laboratories seek multi-parameter validation from single platforms combining thermal, humidity, and gas composition sensing.
- Service contract unbundling:Predictive maintenance platforms and remote calibration services represent new recurring revenue channels distinct from hardware sales.
- EPA energy efficiency guidelines:Refrigerated incubator testing protocols create specification differentiation for analyzer vendors targeting sustainability-conscious procurement.
Industry Challenges
- Thermal metrology expertise scarcity:Skilled technicians capable of executing measurement uncertainty documentation and periodic revalidation intervals remain concentrated in accredited calibration laboratories.
- Legacy incubator integration friction:Retrofitting validated analyzer systems into existing cell culture workflows requires custom sensor array configurations and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incubator Analyzer Market |
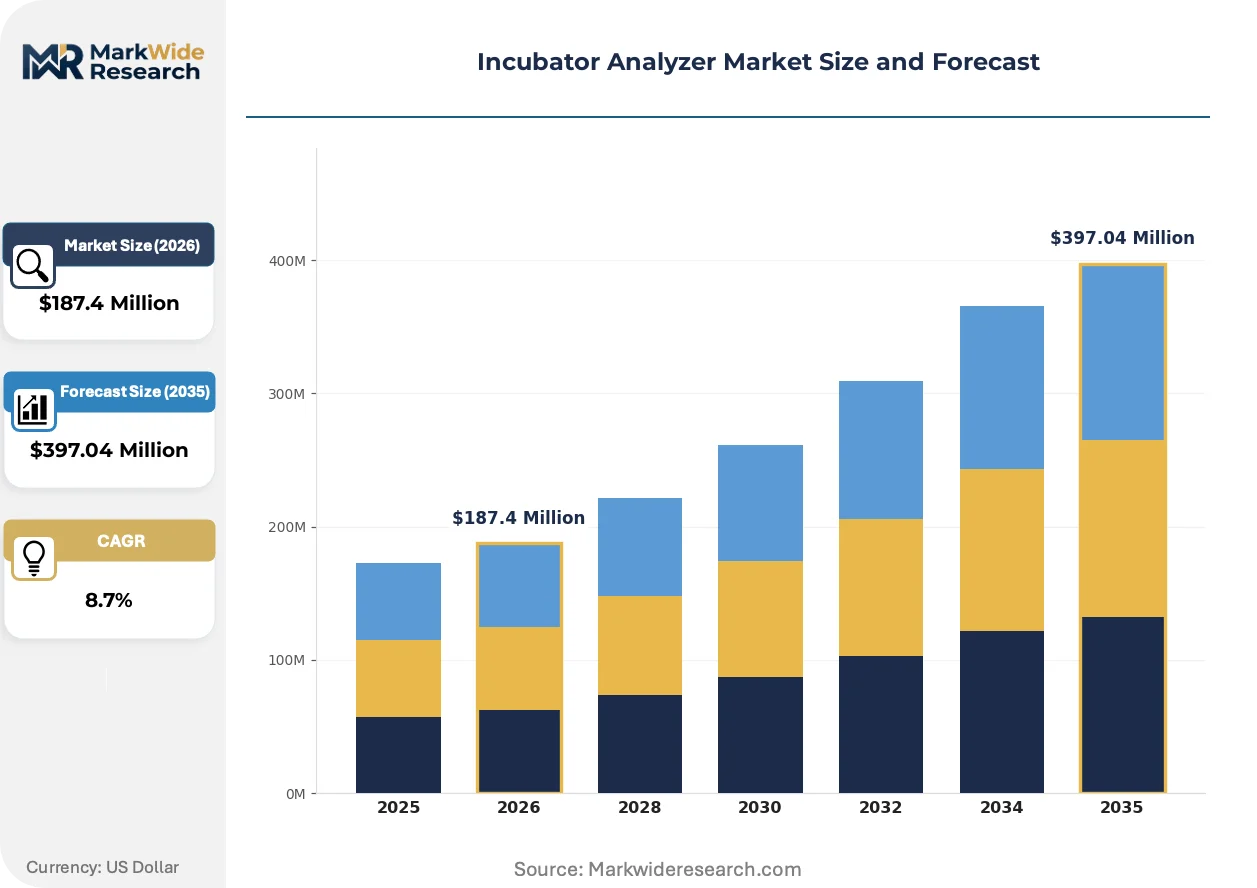
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Incubators, Shaking Incubators, CO2 Incubators, Refrigerated Incubators Technology: Electric Heating, Water Bath, Thermoelectric, Hybrid Systems End User: Biotechnology Firms, Research Laboratories, Pharmaceutical Companies, Educational Institutions Application: Cell Culture, Microbial Growth, Tissue Engineering, Genetic Research |
| Companies Covered | Biodex, Fluke Biomedical, Atom Medical Corporation, CIRS, General Electric, Rave Innovations, Glen Med Solutions, ERS, GAMMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incubator Analyzer Market Strategic Shifts
Multi-parameter validation platforms are displacing single-function instruments as laboratories consolidate environmental monitoring infrastructure. Vendors are embedding predictive algorithms and cloud-connected data logging to transform hardware sales into recurring service relationships.
Sensor fusion architecture is hybridizing thermal, humidity, and gas composition measurement into unified validation platforms. Pharmaceutical companies are adopting these systems fastest due to regulatory audit frequency and instrument redundancy requirements. The technology is hybridizing what were three separate capital purchases into single-platform procurement, compressing vendor addressable market scope while deepening account penetration.
FDA quality system regulations now mandate traceable measurement uncertainty documentation with defined revalidation intervals. This policy shift forces analyzer vendors to embed automated calibration logging and certificate generation directly into firmware. Biopharma manufacturing facilities in the United States are responding by specifying analyzers with built-in compliance documentation workflows.
Hospital networks are consolidating incubator analyzer procurement through centralized biomedical engineering departments rather than individual laboratory autonomy. This buyer concentration is compressing vendor sales cycles while elevating service contract negotiability. The pattern is most visible in United States health systems where predictive maintenance platforms determine vendor selection criteria.
Incubator Analyzer Market Segmentation
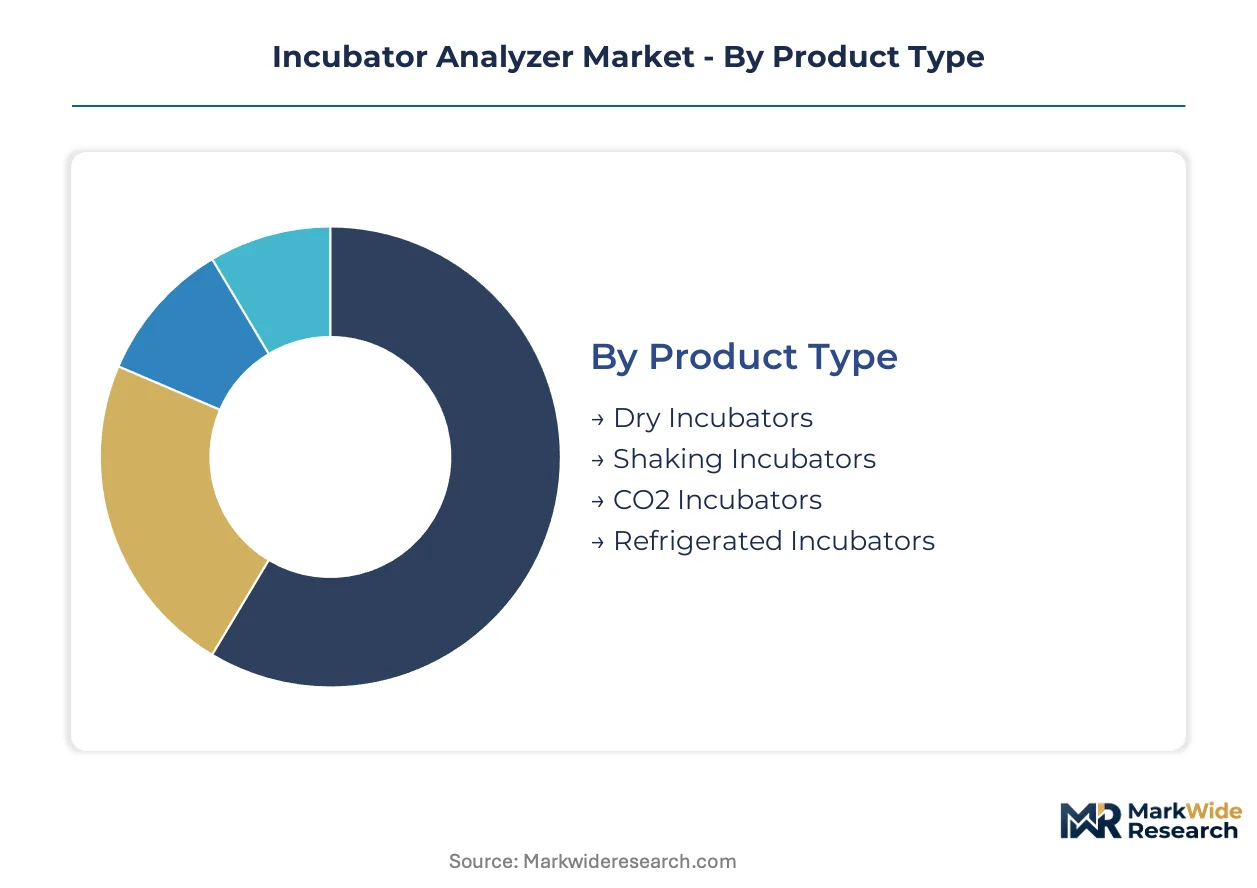
Incubator analyzer procurement patterns diverge sharply across product configurations and end-use environments. Service contract attach rates, calibration frequency requirements, and regulatory audit intensity create distinct margin profiles that vendors must map precisely to capture recurring revenue streams.
Product Type:
After-sales intensity varies dramatically by thermal system complexity, with gas-controlled and refrigerated units demanding substantially higher calibration and preventive maintenance investment than passive heating platforms.
- CO2 Incubators:These precision environmental chambers integrate infrared gas sensors and active humidity control to maintain physiological conditions for mammalian cell culture. Pharmaceutical companies in Germany and the United States drive replacement cycles here, compelled by FDA quality system regulations and EMA good manufacturing practice inspection schedules that mandate documented thermal uniformity validation.
- Refrigerated Incubators:Compressor-based cooling systems with heating elements enable sub-ambient temperature protocols for enzyme studies and bacterial preservation. Demand concentrates in biotechnology clusters around Boston and Shanghai where EPA energy efficiency guidelines and China's dual carbon goals shape procurement specifications for sustainability-conscious facilities.
- Dry Incubators:Electrically heated chambers without humidity or gas control serve basic microbiology workflows.
- Shaking Incubators:Orbital or reciprocating motion platforms combine thermal control with agitation for suspension cell culture.
By volume, dry incubators lead. By growth pace, CO2 incubators are ahead.
Technology:
Capital expenditure tiers separate mature heating methods from emerging multi-parameter platforms that consolidate previously discrete instrumentation purchases.
- Hybrid Systems:Sensor fusion architectures unify thermal, humidity, and gas composition measurement into single validation workflows. Research laboratories in the United States adopt these fastest, drawn by ISO 17025 calibration standard compliance automation and reduced technician time for measurement uncertainty documentation.
- Electric Heating:Resistive element thermal control dominates installed base volume across educational institutions and routine microbiology applications.
- Water Bath:Circulating heated fluid systems deliver exceptional temperature uniformity for specialized enzymatic reactions.
- Thermoelectric:Peltier-based heating and cooling eliminates compressor maintenance but faces power consumption constraints in large-chamber designs.
Electric heating retains the largest installed base. Hybrid systems command the steepest expansion trajectory.
End User:
Customer type determines pricing power, with regulatory audit frequency and instrument redundancy requirements creating tiered margin pools that vendors prioritize through differentiated service bundling.
- Pharmaceutical Companies:These organizations operate under the strictest validation protocols, requiring dual-sensor redundancy and automated certificate generation for FDA and EMA inspections. Facilities in Switzerland and the United Kingdom specify analyzers with embedded compliance documentation workflows to reduce metrology labor costs.
- Biotechnology Firms:Cell culture workflow scale-up drives analyzer procurement as venture-backed companies transition from research to GMP manufacturing.
- Research Laboratories:Academic and government facilities balance precision requirements against grant-funded capital constraints.
- Educational Institutions:Undergraduate teaching labs prioritize durability and simplified operation over multi-parameter validation capabilities.
Pharmaceutical companies generate the highest service contract values. Biotechnology firms show the most rapid analyzer fleet expansion.
Application:
Protocol sensitivity to environmental parameter drift dictates analyzer specification intensity, with living cell applications demanding substantially more rigorous validation than non-viable sample processing.
- Cell Culture:Mammalian and stem cell workflows require continuous CO2, temperature, and humidity monitoring within tight tolerances to prevent differentiation or death. Biopharma manufacturing facilities in China and Germany anchor demand here, responding to NMPA and EMA regulatory harmonization pressures for cross-border laboratory accreditation.
- Tissue Engineering:Three-dimensional scaffold-based cultures amplify environmental control requirements for nutrient diffusion and waste removal.
- Microbial Growth:Bacterial and yeast cultivation protocols tolerate wider parameter ranges than mammalian systems.
- Genetic Research:PCR preparation and nucleic acid hybridization workflows utilize incubators for temperature-controlled reagent processing.
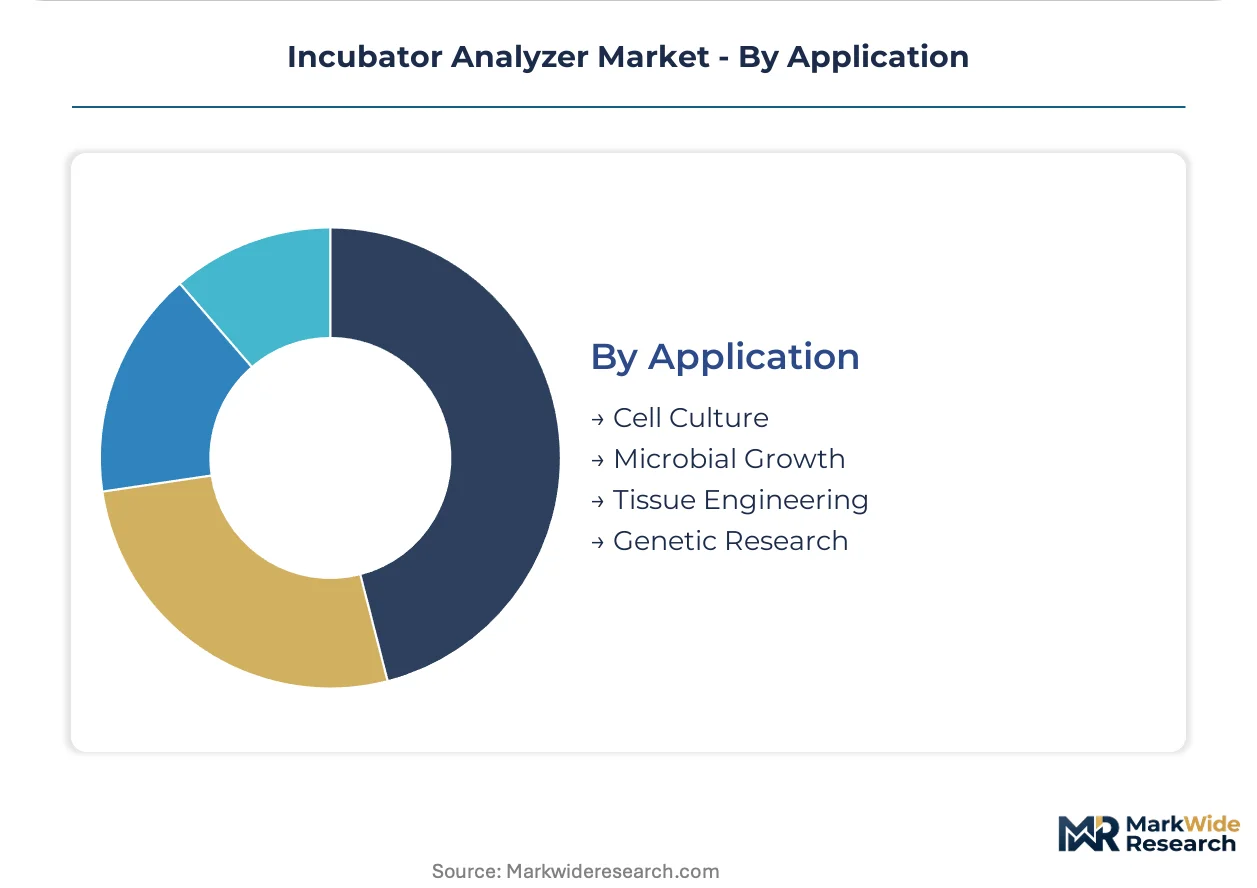
Cell culture applications dominate analyzer attachment rates. Tissue engineering is climbing fastest as regenerative medicine manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality system regulations and ISO 17025 calibration standards are tightening validation requirements across major biopharma manufacturing clusters. Germany, the United States, China, Switzerland, and Japan concentrate demand for precision thermal validation instrumentation.
United States
Biopharma manufacturing expansion around Boston and San Francisco drives analyzer procurement for cell culture workflows. FDA quality system regulations mandate traceable measurement uncertainty documentation with defined revalidation intervals. Hospital networks in the Midwest are consolidating procurement through centralized biomedical engineering departments.
Germany
EMA good manufacturing practice inspections require dual-sensor redundancy configurations that inflate capital expenditure for biologics facilities. ISO 17025 calibration standards shape product design through accredited metrology laboratory concentration in Bavaria and North Rhine-Westphalia. The Rhine-Main biotechnology cluster anchors replacement cycles for precision environmental monitoring equipment.
China
NMPA regulatory harmonization pressures and dual carbon goals shape procurement specifications for sustainability-conscious facilities. Neonatal intensive care unit upgrades in Shanghai and Beijing drive replacement cycles for precision environmental monitoring. The Yangtze River Delta biotechnology corridor shows rapid analyzer fleet expansion among venture-backed companies.
Switzerland
Swissmedic inspection schedules and pharmaceutical company instrument redundancy requirements create tiered margin pools for vendors. Facilities in Basel and Zurich specify analyzers with embedded compliance documentation workflows to reduce metrology labor costs. The country's precision instrumentation heritage supports calibration infrastructure density.
Japan
METI industrial policy and PMDA quality guidelines extend demand for automated calibration logging systems. Accredited metrology laboratories cluster in the Kanto and Kansai regions, creating geographic concentration for ISO 17025 traceability. Tokyo-based hospital networks are specifying predictive maintenance platforms as vendor selection criteria.
Incubator Analyzer Market Competitive Environment
Channel-controlling players compete with product-specialist players across a fragmented vendor base. Calibration instrumentation heritage and predictive maintenance platforms represent distinct competitive moats. Three archetypes dominate: diversified industrial conglomerates with service contract scale, specialized biomedical calibration firms with metrology expertise, and Asia-Pacific manufacturers with localized certification support. Geographic expansion and service contract unbundling constitute the dominant competitive moves.
Within the calibration-specialist tier, Fluke Biomedical and General Electric exemplify divergent approaches to installed base loyalty. Fluke Biomedical represents the precision instrumentation heritage archetype, while General Electric occupies a position as diversified industrial conglomerate. Atom Medical Corporation anchors the Asia-Pacific manufacturing scale archetype. These three companies collectively illustrate how service contract structures and geographic positioning differentiate competitive positioning in thermal validation markets.
| Leading Market Players |
|---|
| Biodex |
| Fluke Biomedical |
| Atom Medical Corporation |
| CIRS |
| General Electric |
| Rave Innovations |
| Glen Med Solutions |
| ERS |
| GAMMEX |
| Others |
Value Chain & Pricing Dynamics
Bavaria's precision instrumentation cluster concentrates platinum resistance thermometer and NDIR gas sensor manufacturing, giving German and Japanese component suppliers substantial leverage over analyzer OEM pricing. This geographic concentration of thermal metrology expertise tightens margins for downstream vendors while amplifying certification-grade price premiums.
Pricing Analysis
Certification level (ISO 17025/FDA-grade) creates the primary spread between analyzer tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with pharmaceutical companies absorbing the steepest premiums for dual-sensor redundancy and automated compliance documentation. Cost compression in the standard tier is intensifying because biotechnology firms negotiate volume discounts during cell culture workflow scale-up. Educational institutions exhibit the highest price sensitivity, while pharmaceutical companies show the least.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese trading houses stabilize cash flow for platinum and optical component procurement. Manufacturing concentrates in Germany, Japan, and the United States for precision sensor arrays, while China dominates printed circuit board and enclosure fabrication. The supply chain draws from precious metal spot markets and specialized optical foundries, creating single-source vulnerability for NDIR gas sensing modules. Distribution runs through biomedical equipment distributors and direct hospital network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The incubator analyzer market sits at a platform-economics inflection where sensor fusion architectures and cloud-connected validation workflows are consolidating three separate instrument categories into unified procurement decisions.
For Market Incumbents: Pre-empt hybrid system displacement by embedding predictive maintenance platforms into existing analyzer fleets before biotechnology firms complete their GMP manufacturing transitions. Secure backward integration into platinum resistance thermometer supply through partnerships with Bavarian metrology specialists. Channel control through long-term service agreements with hospital networks remains the critical defensive lever against Asia-Pacific manufacturing scale entrants. For New Entrants and Emerging Players: Establish a beachhead in China's Yangtze River Delta biotechnology corridor where venture-backed cell culture companies prioritize localized certification support over incumbent brand loyalty. Target the shaking incubator segment where agitation-mechanism expertise creates differentiation against thermal-only specialists. A calibration-as-a-service go-to-market angle bypasses capital-intensive hardware manufacturing while capturing recurring revenue from ISO 17025 compliance automation demand. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors calibration-specialist firms with embedded firmware compliance documentation capabilities over diversified industrial conglomerates with diluted R&D focus. The 5-10 year viability window rewards acquisition targets possessing automated measurement uncertainty certificate generation and cloud data logging infrastructure. Watch for FDA harmonization with NMPA inspection protocols as the inflection signal indicating accelerated cross-border laboratory accreditation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Platform Integration | Consolidates thermal, humidity, and gas validation into single procurement decisions for biopharma facilities. |
| Calibration Infrastructure Partnership | Secures ISO 17025 traceability access in Germany, Japan, and the United States for regulatory compliance. |
| Predictive Maintenance Platform Launch | Transforms hardware sales into recurring service relationships with hospital network biomedical engineering departments. |
| Geographic Expansion into China | Captures NMPA regulatory harmonization-driven demand from Shanghai and Beijing neonatal intensive care upgrades. |
| Acquisition of Sensor Fusion Specialist | Accelerates multi-parameter validation capabilities for pharmaceutical company dual-sensor redundancy requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, ISO 17025 accreditation body directories, and EMA good manufacturing practice inspection databases. Primary interviews engaged biomedical engineering directors at hospital networks, metrology laboratory managers at accredited calibration facilities, procurement leads at biotechnology firms, and regulatory affairs specialists at pharmaceutical manufacturers. Secondary validation drew from SEC 10-K filings of diversified industrial conglomerates, customs trade data for thermal validation equipment, and GPO contract databases for hospital capital equipment procurement. Bottom-up analyzer fleet sizing triangulates against top-down biopharma manufacturing capacity expansion estimates.
Forecast inputs span product type segmentation across CO2, refrigerated, dry, and shaking incubator configurations; technology tiers from electric heating through hybrid sensor fusion systems; and end-user categories including pharmaceutical companies, biotechnology firms, research laboratories, and educational institutions. CAGRs were derived from replacement cycle analysis tied to regulatory inspection frequency and thermal uniformity validation mandate expansion. Industry-specific forecast inputs incorporate EPA energy efficiency guideline adoption curves and EMA dual-sensor redundancy inspection precedent propagation.
Stress conditions across platinum price volatility, NDIR sensor lead time extension, and ISO 17025 accreditation laboratory capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization pace and biopharma manufacturing facility commissioning timelines. Macroeconomic contraction affecting venture capital availability for biotechnology scale-up, regulatory divergence between FDA and NMPA inspection protocols, or breakthrough thermoelectric cooling efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Global Weather Forecasting Systems Market